
 North America Automation in Retail Market | 2026-2036
North America Automation in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automation in Retail Market Insights
Market Context
Canadian warehouse robotics producers is rebalancing capacity toward retail fulfillment systems after years of e-commerce specialization. Amazon.com Inc leverages its proprietary Just Walk Out architecture to dominate cashierless store deployments across the United States. Honeywell International Inc anchors its position through barcode scanning and RFID hardware that integrates with legacy point-of-sale infrastructure. Zebra Technologies Corporation competes aggressively in mobile computing terminals that bridge in-store inventory visibility with online order management.
Technical Definition and Segment Structure
Automation in retail encompasses electromechanical systems, software platforms, and sensor networks that execute merchandise handling, transaction processing, inventory tracking, and customer service functions with minimal human intervention, typically operating through centralized control architectures with edge-computing nodes for real-time responsiveness. Automated checkout systems command the largest installed base among product types, though computer vision modules within the technology dimension are capturing disproportionate investment as retailers pursue shrinkage reduction. Cloud-based solutions within the delivery model category sustain the fastest deployment velocity, while on-premises installations retain preference among supermarket operators with stringent data sovereignty requirements.
Regulatory Environment and Outlook
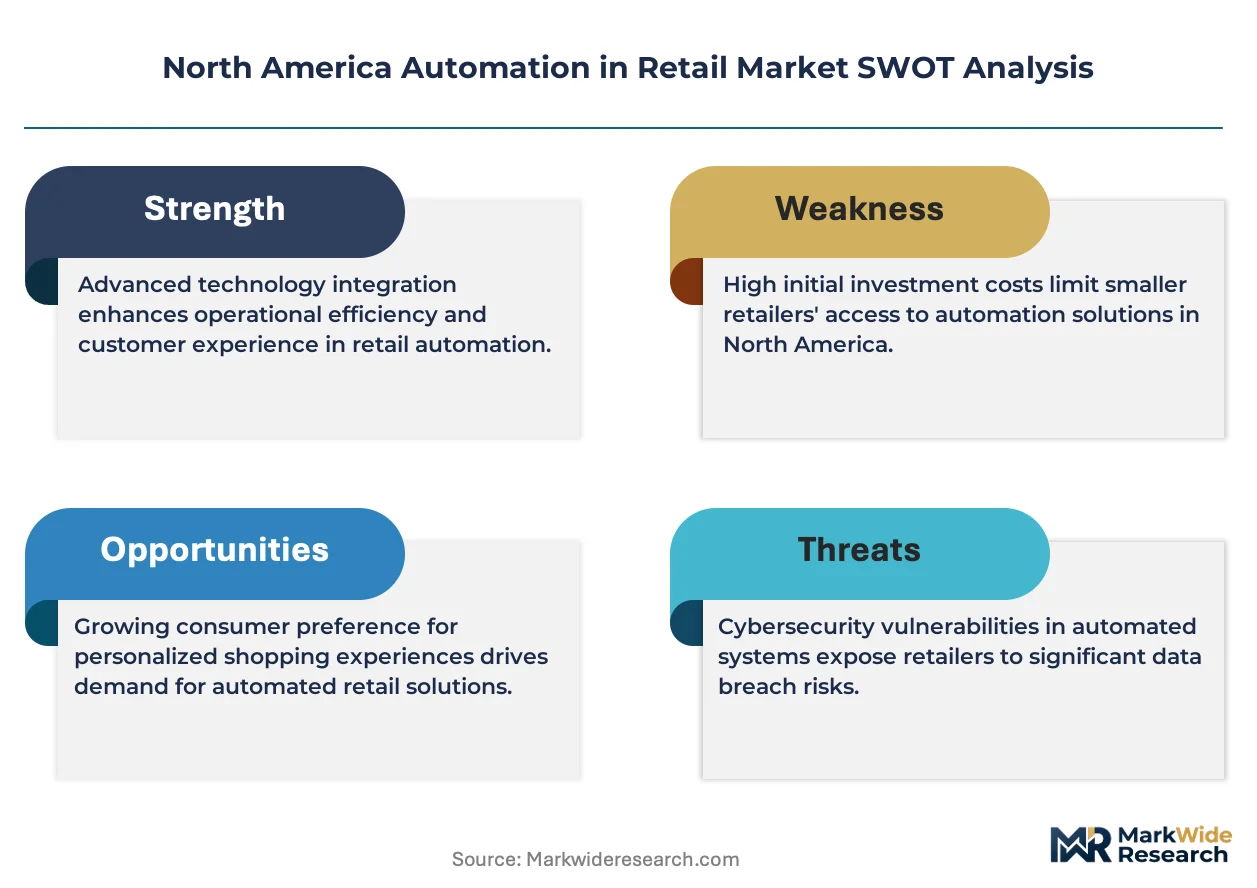
The Federal Trade Commission scrutinizes automated pricing algorithms for collusion risk, while state-level biometric privacy laws in Illinois and California constrain facial recognition deployments in retail settings. The National Institute of Standards and Technology issues cybersecurity frameworks that shape vendor qualification standards for connected retail infrastructure. Stakeholders must monitor evolving accessibility mandates under the Americans with Disabilities Act as touchscreen and voice-interface requirements for self-service kiosks tighten.
Market Dynamics
State-level minimum wage mandates across California, Texas, and New York are compressing labor cost arbitrage windows, compelling grocery chains and big-box retailers to accelerate autonomous checkout and warehouse robotics deployments ahead of depreciation cycles.
Growth Catalysts
- Biometric Privacy Frameworks:Illinois Biometric Information Privacy Act and California Consumer Privacy Act create compliance infrastructure that legitimizes facial recognition deployments for loss prevention, expanding addressable market for computer vision vendors.
- Supermarket Operators:Large-format grocers in Texas and Florida are consolidating self-checkout footprints to capture throughput gains from high-volume suburban locations with limited labor availability.
- Edge Computing Architectures:Distributed processing nodes reduce latency for real-time inventory tracking, enabling shelf-scanning robots to operate without constant cloud connectivity in bandwidth-constrained rural stores.
Market Restraints
- Semiconductor Supply Concentration:GPU and sensor chip fabrication concentrated in East Asian foundries creates vulnerability for computer vision module production timelines.
- Americans with Disabilities Act Accessibility Mandates:Evolving touchscreen height and voice-interface requirements for self-service kiosks force retrofit costs on deployed hardware bases.
- Manual Checkout Labor Pool:Persistent availability of low-wage workers in secondary metro areas delays ROI justification for automation capital expenditure in smaller format stores.
Strategic Opportunities
- Canadian Retail Fulfillment:Underpenetrated autonomous warehouse density in Toronto and Vancouver corridors offers first-mover positioning for robotics system integrators.
- RFID-Computer Vision Convergence:Hybrid tracking systems combining radio-frequency identification with camera networks enable item-level traceability without requiring universal tag adoption.
- Inflation Reduction Act Clean Energy Credits:Facility automation retrofits in qualifying logistics centers access federal incentives that improve project hurdle rates.
Industry Challenges
- Mechatronics Technician Scarcity:Maintenance of automated guided vehicles and robotic arms requires specialized skill sets concentrated in automotive manufacturing regions, creating geographic hiring mismatches.
- Legacy POS Integration Complexity:Decades-old transaction processing infrastructure in established retail chains demands custom middleware development for seamless data handoff to cloud analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automation in Retail Market |
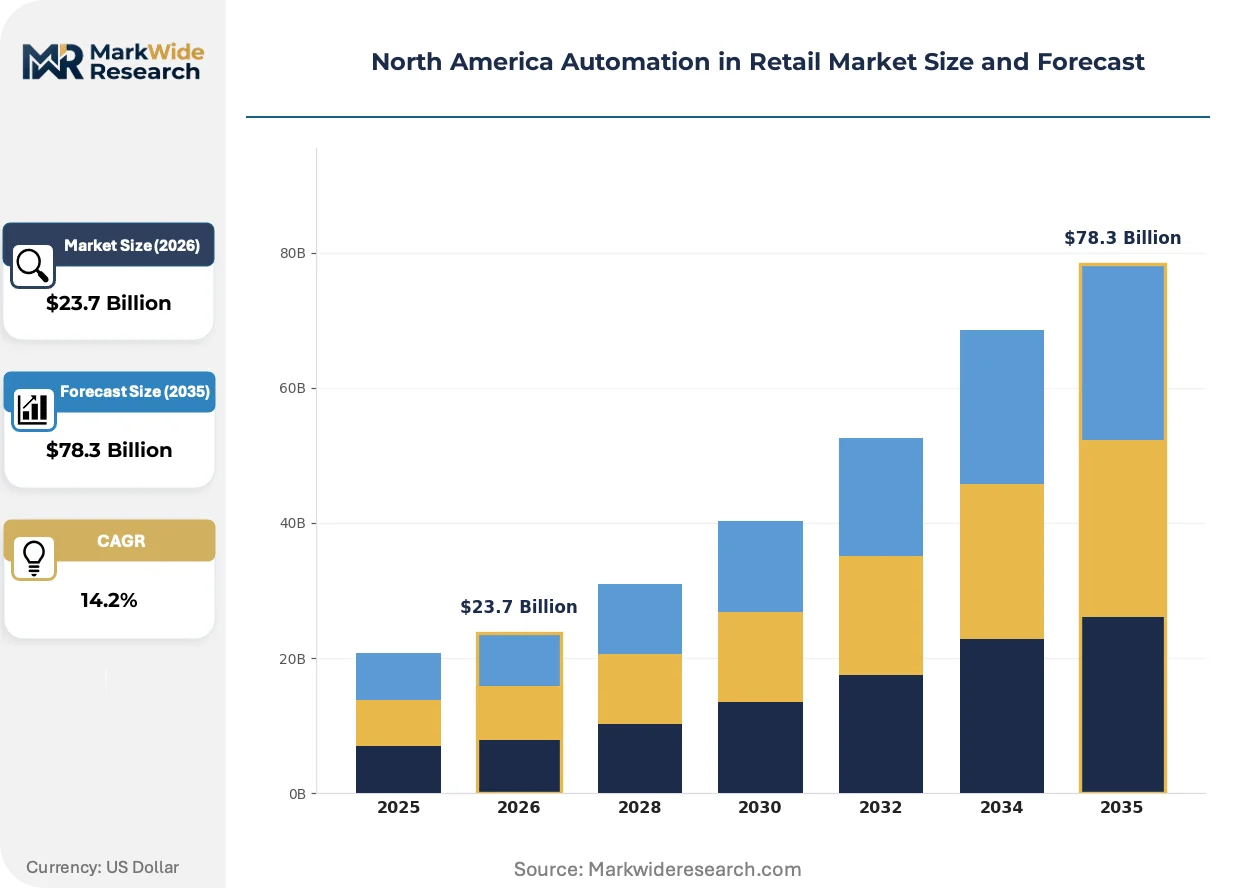
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Automated Checkout Systems, Inventory Management Solutions, Mobile Payment Applications End User: Supermarkets, Department Stores, E-commerce Platforms, Specialty Retailers Technology: AI Analytics, RFID, Cloud-Based Solutions, Computer Vision Delivery Model: On-Premises, Cloud-Hosted, Subscription-Based, Hybrid |
| Companies Covered | Amazon.com Inc, Honeywell International Inc, NCR Voyix Corporation, Diebold Nixdorf Incorporated, Zebra Technologies Corporation, Datalogic SpA, ECR Software Corporation, Fujitsu Limited, Pricer AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automation in Retail Market Trends and Innovations
Computer vision hardware and software stacks are fragmenting into interchangeable components, allowing retailers to mix sensor suppliers with analytics providers rather than accepting bundled proprietary systems.
Edge-based inference engines for shelf monitoring and customer tracking are modularizing around standardized camera modules and open APIs. Mid-size grocery cooperatives in the Midwest are piloting these configurations to avoid vendor lock-in from Amazon-scale integrated stacks. This decomposition is compressing implementation timelines from eighteen-month enterprise deployments to ninety-day departmental rollouts.
FTC scrutiny of algorithmic pricing under Section 5 enforcement guidelines is reshaping vendor qualification protocols. Retailers deploying dynamic price optimization must now document anti-collusion safeguards in procurement contracts. Automated pricing software providers serving California and Illinois markets are restructuring offerings to include audit trails and human-in-the-loop approval thresholds.
Buying committees at regional retail chains are unbundling hardware procurement from software licensing and maintenance agreements. Traditional bundled capital sales models are yielding to separate subscription contracts for computer vision analytics, robot fleet management, and cloud data storage. This shift is most visible among fifty-to-two-hundred-store operators in Texas and Georgia seeking operational flexibility over long-term asset ownership.
North America Automation in Retail Market Segmentation
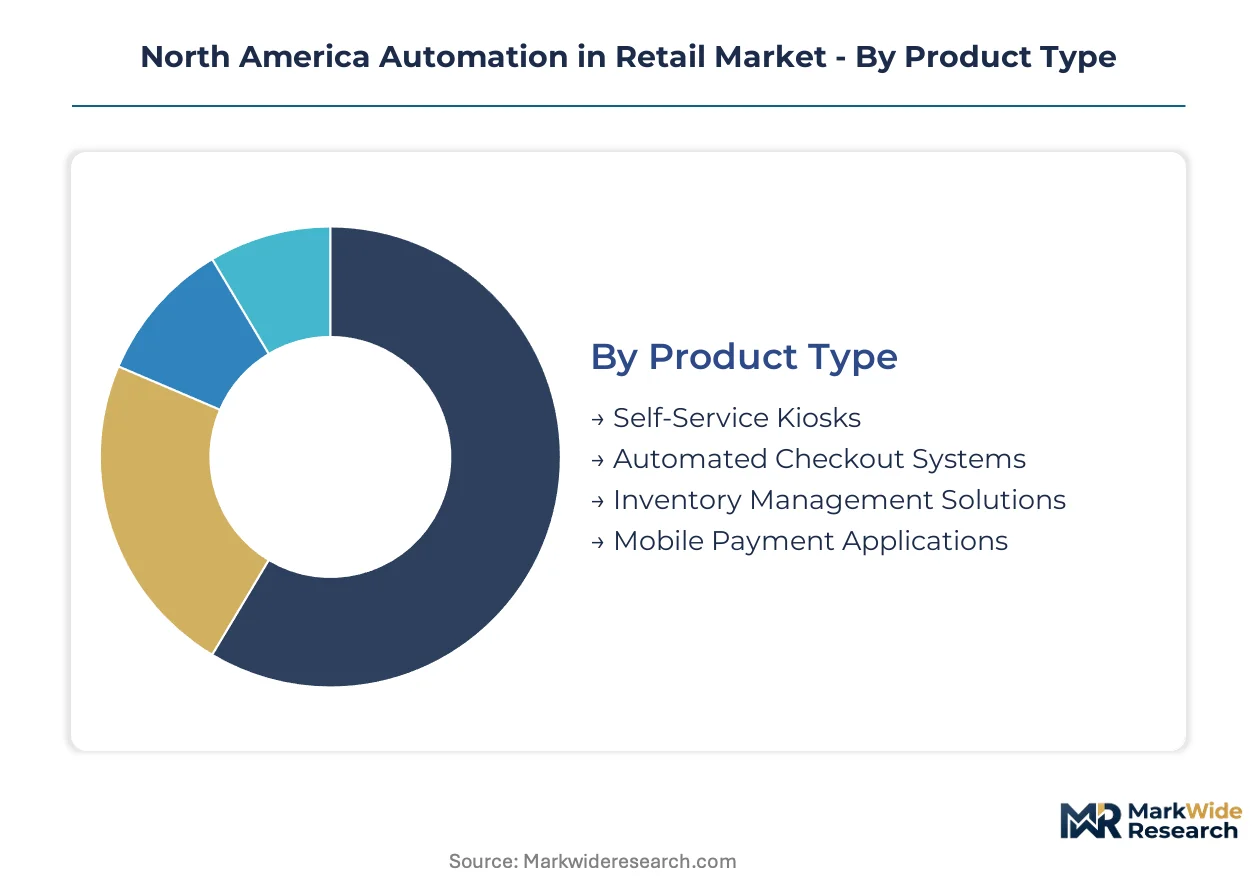
Retail automation vendors configure product portfolios around four intersecting dimensions. Technology choices cascade through delivery models and end-user requirements, creating distinct competitive arenas where hardware specialists, software platforms, and system integrators compete for different customer relationships.
Product Type:
Supply concentration in automated checkout hardware favors established point-of-sale manufacturers with captive semiconductor sourcing relationships.
- Automated Checkout Systems:These electromechanical terminals integrate barcode scanners, payment processors, and weight verification sensors into unified transaction stations. California and Texas supermarket operators deploy these systems most aggressively, driven by state-level minimum wage mandates that compress labor cost arbitrage windows.
- Self-Service Kiosks:Freestanding units handle ordering, wayfinding, and payment functions through touchscreen and voice interfaces. The Americans with Disabilities Act accessibility requirements for height and audio output specifications constrain design flexibility and force retrofit costs on deployed hardware bases.
- Inventory Management Solutions:Shelf-scanning robots and RFID tracking systems provide real-time stock visibility.
- Mobile Payment Applications:Smartphone-integrated transaction processing reduces dedicated hardware requirements.
Automated checkout systems absorb the bulk of installed capacity; inventory management solutions are expanding most quickly.
End User:
Application intensity varies sharply by retail format, with large-footprint operators achieving faster automation ROI than constrained-format competitors.
- Supermarkets:High-volume grocery chains in Texas and Florida consolidate self-checkout footprints to capture throughput gains from suburban locations with limited labor availability. These operators prioritize systems with legacy POS integration capabilities to avoid rip-and-replace infrastructure investments.
- E-commerce Platforms:Pure-play online retailers drive demand for warehouse robotics and fulfillment automation. Canadian warehouse robotics producers are rebalancing capacity toward retail fulfillment systems after years of e-commerce specialization, targeting Toronto and Vancouver corridors for first-mover positioning.
- Department Stores:Mid-size apparel and home goods retailers deploy clienteling tablets and RFID inventory systems.
- Specialty Retailers:Niche operators in beauty, electronics, and sporting goods favor modular, department-level rollouts over enterprise deployments.
Supermarkets command the largest automation expenditure base; e-commerce platforms are climbing the fastest.
Technology:
Margin structures diverge between hardware-centric and software-centric technology layers, with analytics platforms capturing recurring revenue streams.
- Computer Vision:Camera networks and edge-based inference engines enable shelf monitoring, customer tracking, and loss prevention without constant cloud connectivity. Illinois Biometric Information Privacy Act and California Consumer Privacy Act compliance infrastructure legitimizes facial recognition deployments, expanding the addressable market for vision system vendors.
- Cloud-Based Solutions:Centralized data platforms sustain the fastest deployment velocity across retail segments, though supermarket operators with stringent data sovereignty requirements retain preference for on-premises installations.
- AI Analytics:Machine learning models optimize pricing, demand forecasting, and inventory allocation.
- RFID:Radio-frequency identification tags enable item-level traceability in supply chain and store operations.
Computer vision captures disproportionate investment flow; cloud-based solutions are gaining share fastest.
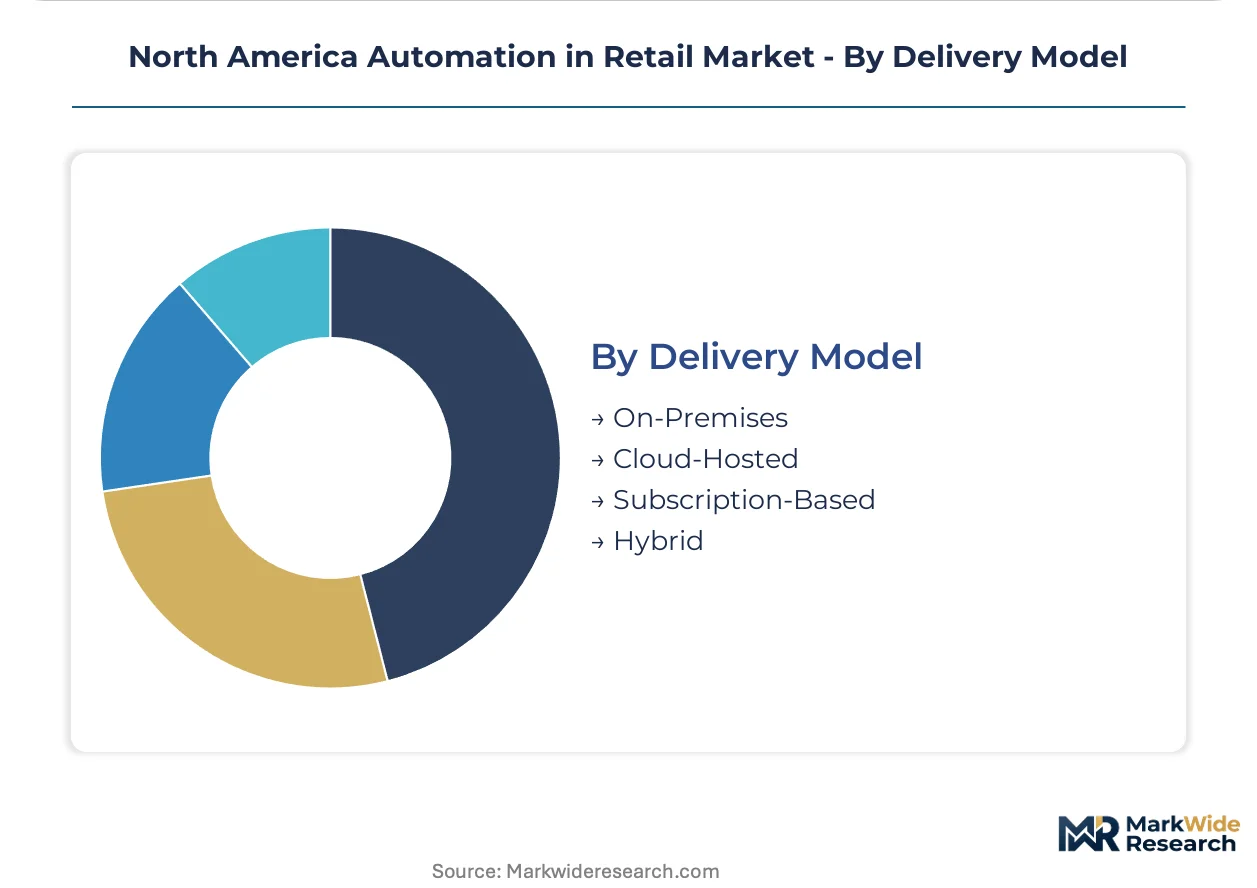
Delivery Model:
Customer type stratification between asset-heavy and asset-light procurement preferences is restructuring vendor commercial relationships.
- Subscription-Based:Separate contracts for computer vision analytics, robot fleet management, and cloud data storage replace traditional bundled capital sales. Fifty-to-two-hundred-store operators in Texas and Georgia favor this structure for operational flexibility over long-term asset ownership.
- Hybrid:Combinations of on-premises hardware with cloud-hosted software balance data sovereignty requirements against scalability needs. This configuration dominates among established retail chains with decades-old transaction processing infrastructure demanding custom middleware development.
- On-Premises:Fully localized deployment retains preference among operators with stringent data control requirements.
- Cloud-Hosted:Fully remote infrastructure delivery minimizes capital expenditure and IT staffing requirements.
Subscription-based contracts are displacing bundled sales most rapidly; hybrid deployments retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley chip fabrication anchors North American computer vision hardware supply chains for retail automation systems. Canadian warehouse robotics clusters in Toronto and Vancouver corridors rebalance capacity toward retail fulfillment after years of e-commerce specialization. Mexican manufacturing zones near the US border assemble sensor modules and electromechanical components for cross-border distribution.
United States
California and Texas supermarket chains deploy self-checkout systems most aggressively under state-level minimum wage mandates. The Federal Trade Commission scrutinizes automated pricing algorithms for collusion risk under Section 5 enforcement guidelines. Los Angeles and Dallas-Fort Worth metro areas concentrate cashierless store pilot programs where labor cost pressures compress ROI timelines.
Canada
Toronto and Vancouver corridors offer underpenetrated autonomous warehouse density for robotics system integrators targeting retail fulfillment. Health Canada and PMRA cybersecurity frameworks shape vendor qualification standards for connected retail infrastructure. Quebec-based automation producers supply bilingual self-service kiosk interfaces for national grocery cooperatives.
Mexico
Northern border states assemble electromechanical components and sensor modules for US retail automation OEMs seeking nearshoring alternatives. The country's national consumer protection regulator monitors automated pricing transparency in cross-border retail operations. Baja California and Chihuahua manufacturing clusters export barcode scanning hardware to California distribution hubs.
North America Automation in Retail Market Competitive Landscape
Global majors compete with regional champions across hardware procurement and software licensing dimensions in North American retail automation. The vendor base stratifies into three tiers: integrated platform providers with captive cloud infrastructure, specialized hardware fabricators with legacy POS integration expertise, and modular software vendors selling computer vision analytics separately. Strategic moves center on unbundling bundled capital sales into subscription contracts and developing hybrid deployment architectures that balance data sovereignty against scalability.
Within the integrated platform tier, Amazon.com Inc exemplifies end-to-end system ownership spanning proprietary computer vision to cloud-hosted transaction processing. Honeywell International Inc and Zebra Technologies Corporation anchor the specialized hardware segment, with the former representing barcode scanning and RFID integration capabilities and the latter occupying a position in mobile computing terminals that bridge inventory visibility with online order management.
| Leading Market Players |
|---|
| Amazon.com Inc |
| Honeywell International Inc |
| NCR Voyix Corporation |
| Diebold Nixdorf Incorporated |
| Zebra Technologies Corporation |
| Datalogic SpA |
| ECR Software Corporation |
| Fujitsu Limited |
| Pricer AB |
| Others |
Pricing and Supply Chain Analysis
Warranty bundling divergence separates integrated platform providers from modular component vendors, with the former capturing recurring service revenue while the latter compete on unbundled hardware margins. This bifurcation concentrates procurement power among fifty-to-two-hundred-store operators in Texas and Georgia seeking operational flexibility, while supermarket chains with stringent data sovereignty requirements absorb premium pricing for on-premises installations with captive maintenance agreements.
Pricing Analysis
Service bundling separates subscription-based analytics contracts from unbundled hardware procurement, with computer vision software commanding recurring revenue streams while electromechanical terminals face commodity pressure. Price differentiation hinges on legacy POS integration complexity and edge computing capability tiers. Cost compression in self-checkout hardware intensifies as Canadian warehouse robotics producers rebalance capacity toward retail fulfillment systems. Mid-size grocery cooperatives exhibit highest price sensitivity, while Amazon-scale integrated stacks demonstrate lowest sensitivity due to captive cloud infrastructure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for proprietary computer vision stacks, while distributor networks serve regional retail chains with modular component sourcing. GPU and sensor chip fabrication concentrates in Taiwan, South Korea, and China, creating vulnerability for North American computer vision module production timelines. Semiconductor supply draws from East Asian foundries, electromechanical components from Mexican border states, and edge computing hardware from Silicon Valley clusters. Single-source vulnerability in GPU fabrication poses structural risk. Distribution runs through systems integrators with legacy POS integration expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive cloud infrastructure and semiconductor sourcing relationships, as FTC algorithmic pricing scrutiny and legacy POS integration complexity force weaker players toward acquisition or exit.
For Market Incumbents: Lock in supermarket operator relationships through hybrid deployment architectures that balance data sovereignty requirements against scalability needs. Deepen backward integration into edge computing hardware to reduce exposure to East Asian semiconductor supply concentration. Capture computer vision software revenue through separate subscription contracts that displace bundled capital sales. For New Entrants and Emerging Players: Illinois Biometric Information Privacy Act and California Consumer Privacy Act compliance infrastructure opens a window for facial recognition vendors to capture loss prevention budgets from regional retail chains. Target underpenetrated autonomous warehouse density in Toronto and Vancouver corridors where Canadian robotics producers are rebalancing capacity. Pursue RFID-computer vision convergence as a go-to-market angle enabling item-level traceability without universal tag adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-size software vendors with modular analytics platforms and open API architectures. Five-to-ten year viability favors vendors with recurring revenue streams from subscription-based computer vision analytics rather than one-time hardware sales. Monitor FTC Section 5 enforcement guideline expansion as an inflection indicator for algorithmic pricing software valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing Hardware | Reduces GPU supply vulnerability from Taiwan and South Korean foundry concentration. |
| Hybrid Deployment Architecture Development | Captures supermarket operators with stringent data sovereignty requirements in California and Texas. |
| Biometric Privacy Compliance Certification | Legitimizes facial recognition deployments under Illinois BIPA and California CCPA frameworks. |
| Subscription-Based Analytics Unbundling | Aligns with fifty-to-two-hundred-store operators in Texas and Georgia seeking operational flexibility. |
| Legacy POS Middleware Investment | Enables seamless data handoff from decades-old transaction infrastructure to cloud analytics platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with retail automation procurement directors, supermarket operations executives, robotics system integrators, and computer vision software vendors. FTC enforcement guideline databases, NIST cybersecurity framework documentation, and state-level biometric privacy statute records provided regulatory boundary conditions. Bottom-up triangulation across hardware shipment data and top-down reconciliation against retail capital expenditure disclosures validated market sizing.
Data-stream reconciliation across product type, technology layer, delivery model, and end-user format dimensions structured the analytical framework. Deployment velocity differentials between cloud-based solutions and on-premises installations, edge computing architecture adoption curves, and legacy POS integration complexity premiums informed CAGR derivation across the projection horizon. Labor cost pressure indices from state minimum wage mandate schedules and semiconductor supply lead time variations shaped scenario weightings.
The model assumes a particular technology adoption path; alternative pathways for computer vision module standardization would alter the outlook if open API architectures accelerate faster than proprietary stack consolidation. Forecasts reflect documented assumptions about edge computing bandwidth requirements and FTC algorithmic pricing enforcement intensity. Practitioners should monitor Illinois and California biometric privacy litigation trends and East Asian semiconductor export restriction announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Global Kiosk Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Ticket Machine Market
Retail Technology
Retail Inventory Software Market
Retail Technology
E-Retail Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Digital Kiosk Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Cash Register Machines Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Smart Retail Systems Market
Retail Technology
AR in Retail Market
Retail Technology
Omni-Channel Retail Solutions Market