
 Retail Inventory Software Market | 2026-2036
Retail Inventory Software Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Inventory Software Market Insights
Subscription-based replenishment analytics is repositioning how inventory platforms monetize value beyond perpetual licenses. Oracle Corporation leverages embedded AI forecasting to anchor enterprise-grade demand planning across grocery and apparel chains. SAP SE sustains dominance in multi-entity stock orchestration through deep ERP integration. Manhattan Associates specializes in warehouse-centric inventory execution, competing on fulfillment velocity rather than breadth.
Retail inventory software comprises applications that track stock levels, automate reorder triggers, and synchronize availability data across sales channels through API-connected databases and RFID or barcode ingestion protocols. Cloud-based deployment leads product type adoption due to lower capital barriers and elastic compute for seasonal demand spikes, while hybrid architectures capture margin pools from retailers with legacy on-premises investments requiring gradual migration. Among end users, large enterprises dominate current spending, though franchise networks represent the fastest expansion vector as multi-location visibility becomes operationally critical.
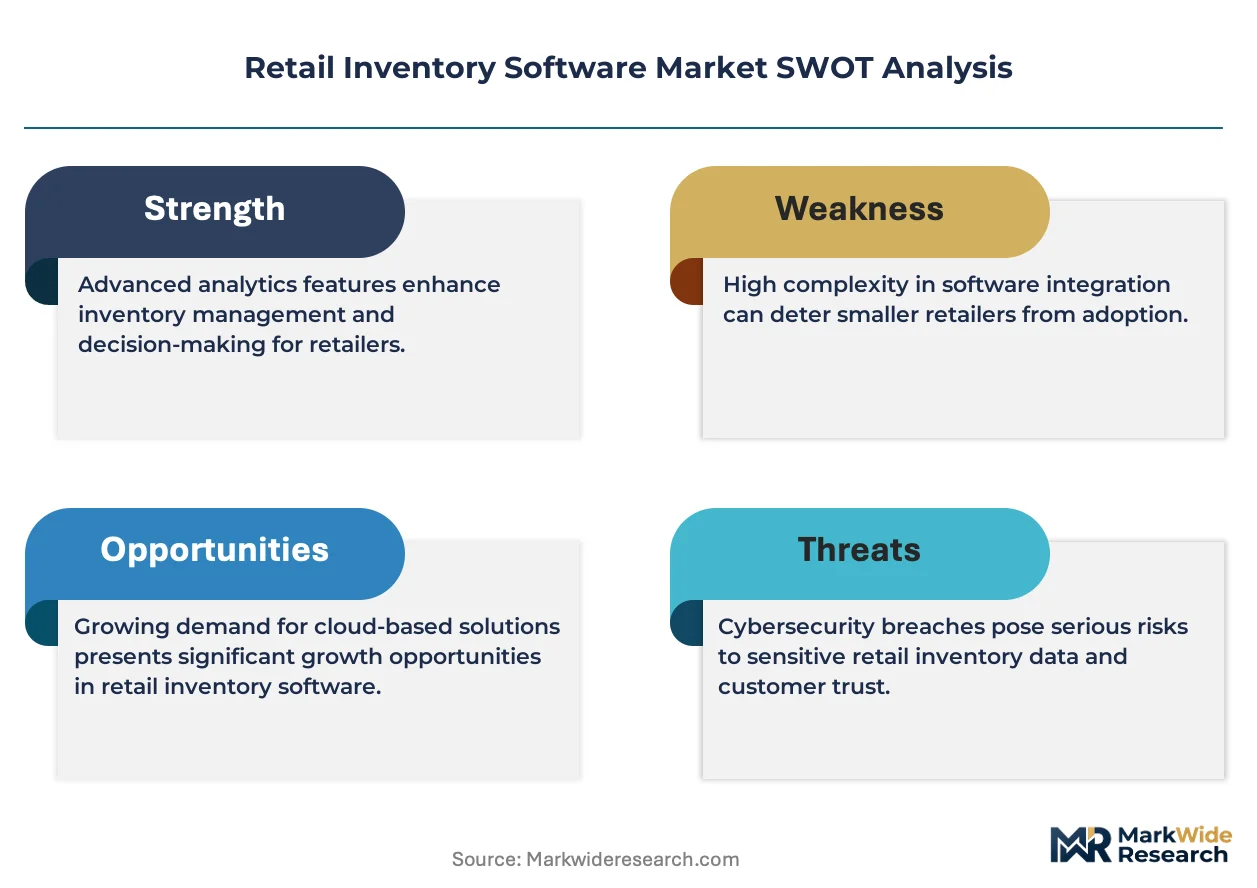
FDA traceability rules for food retailers, EPA electronic waste directives affecting hardware-dependent on-premises systems, and GDPR data residency requirements in Europe collectively elevate compliance costs and favor vendors with certified cloud infrastructure. The EU AI Act introduces additional algorithmic transparency obligations for automated reorder engines deployed in European markets. Stakeholders must evaluate whether vendor roadmaps prioritize explainable AI governance and cross-border data sovereignty before committing to long-term platform contracts.
Market Dynamics
Real-time stock visibility mandates from omnichannel fulfillment networks are forcing wholesale architecture replacements across retail IT estates, compressing vendor consolidation timelines and elevating API-native platforms above legacy batch systems.
Growth Catalysts
- GDPR cloud migration mandates:European data residency rules compel retailers to abandon on-premises inventory databases for certified cloud infrastructure, expanding addressable market for compliant SaaS vendors.
- Warehouse automation investment waves:Robotics deployment in United States distribution centers requires synchronized inventory feeds, driving demand for millisecond-latency stock tracking platforms.
- RFID ingestion protocol standardization:Item-level tagging adoption in apparel and grocery chains enables automated cycle counting and shrinkage reduction at enterprise scale.
Market Restraints
- Legacy ERP integration friction:Decades-old on-premises systems in mid-market retail chains resist API connectivity, inflating implementation costs and extending deployment timelines.
- Technical talent scarcity:Shortage of cloud-native inventory engineers and supply chain data scientists constrains rollout velocity for advanced forecasting modules.
- Input cost volatility in hardware-dependent deployments:Server and networking equipment price swings destabilize total cost of ownership calculations for hybrid architecture adopters.
Strategic Opportunities
- Franchise network expansion:Multi-location visibility requirements in fast-growing franchise systems create greenfield demand for centralized inventory orchestration platforms.
- EU AI Act algorithmic transparency:Automated reorder engines deployed in European markets must demonstrate explainable decision pathways, favoring vendors with built-in governance tooling.
- Subscription monetization models:Consumption-based pricing for replenishment analytics displaces perpetual licenses, opening recurring revenue streams in mid-market segments.
Industry Challenges
- Cross-border data sovereignty complexity:Divergent national cloud storage requirements across operating jurisdictions fragment platform architectures and inflate compliance overhead.
- Interoperability certification delays:Protracted vendor testing cycles for ERP connector validation stall deployment schedules and strain customer relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Inventory Software Market |
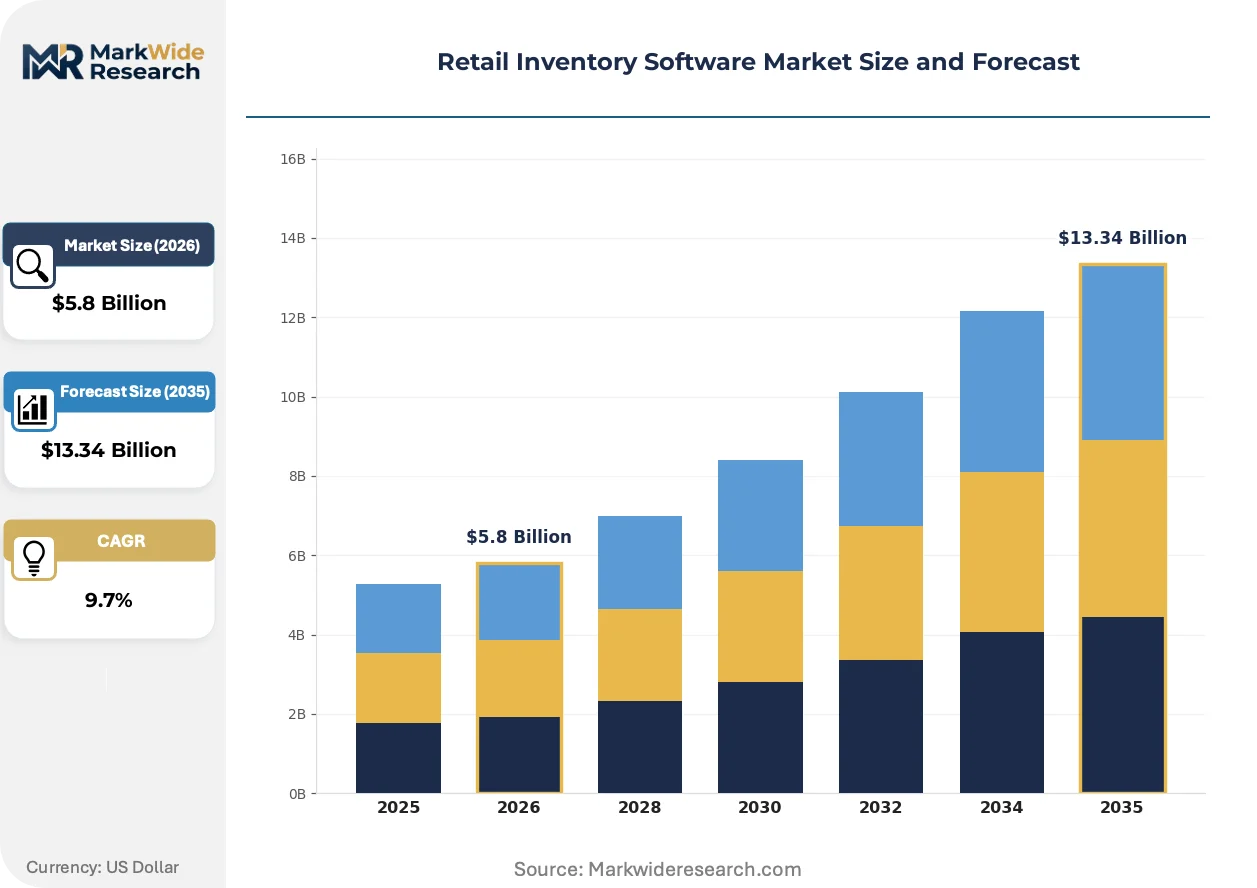
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Small Enterprises, Medium Enterprises, Large Enterprises, Franchise Deployment: Single-Store, Multi-Store, Chain Operations, E-commerce Customer Type: Retailers, Wholesalers, Distributors, Others |
| Companies Covered | Oracle Corporation, SAP SE, Microsoft Corporation, IBM Corporation, NCR Corporation, Manhattan Associates, Fishbowl Inventory, NetSuite, Lightspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Inventory Software Market Trends and Innovations
Embedded intelligence and edge computing architectures are redrawing competitive boundaries, compressing the gap between sensing stock conditions and executing fulfillment decisions.
Machine learning forecasting modules are absorbing demand signal complexity previously handled by statistical time-series models. Grocery and apparel chains with volatile seasonal patterns deploy these engines to reduce safety stock buffers. The technology is absorbing planning analyst headcount, reallocating human capital toward exception management and supplier negotiation.
EU AI Act transparency obligations are mandating algorithmic audit trails for automated replenishment systems. Retailers operating in European markets must document decision logic for regulatory inspection. Food and pharmaceutical inventory platforms face the steepest compliance ramps, accelerating vendor selection criteria toward explainable AI governance.
Franchise operators are consolidating procurement of inventory software through master service agreements rather than location-by-location purchasing. This buyer concentration shifts pricing power toward large platform vendors with multi-tenant architectures. United States-based franchise networks represent the most visible concentration, though German and Chinese franchise systems are following similar consolidation patterns.
Retail Inventory Software Market Segmentation
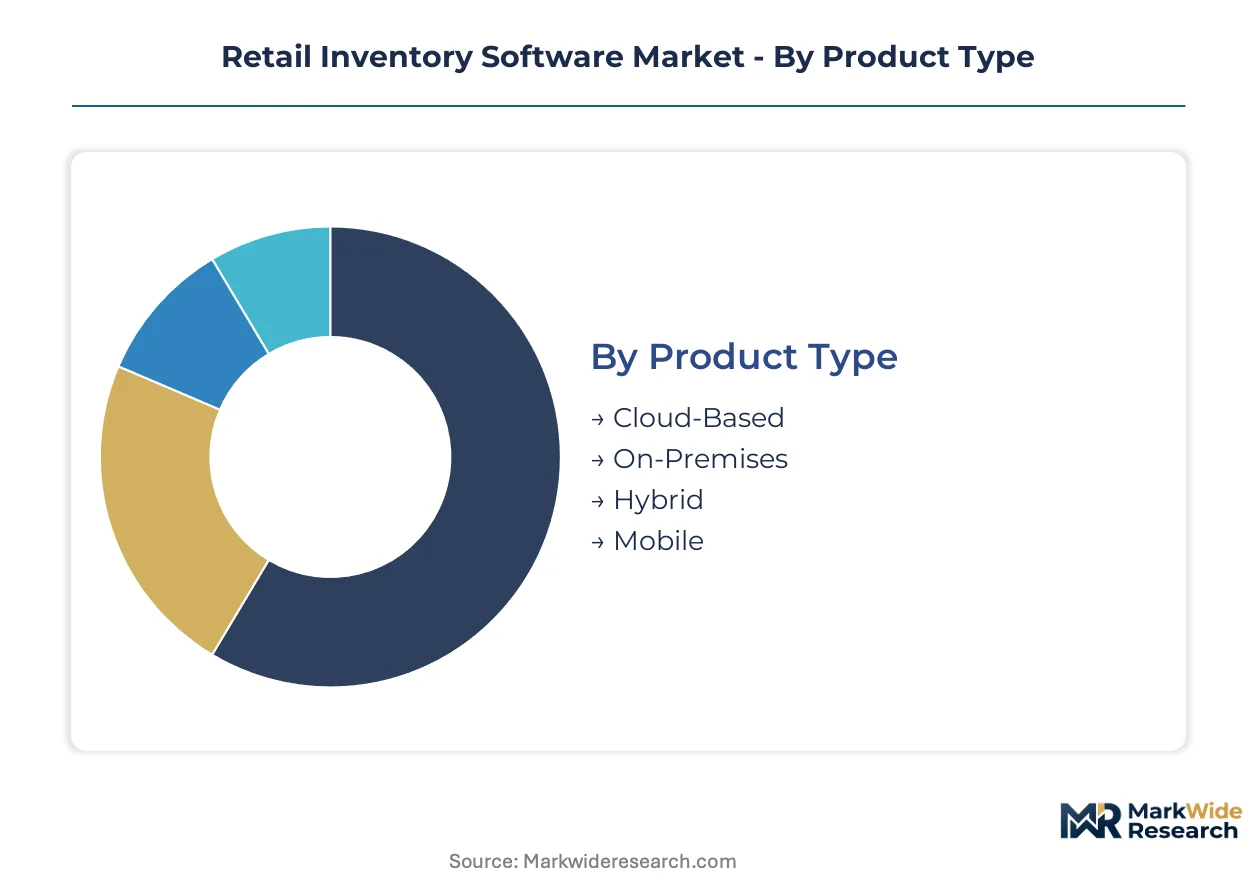
Retail inventory software purchasing decisions hinge on deployment architecture, operational scale, and channel complexity. Buyers weigh cloud elasticity against data sovereignty requirements while franchise networks prioritize centralized visibility over single-location solutions.
Product Type:
Capital expenditure tolerance and compliance mandates determine architecture selection across retail IT estates.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for seasonal demand spikes without server procurement cycles. United States grocery chains and German apparel retailers dominate adoption, compelled by GDPR data residency rules and state-level privacy statutes that prohibit on-premises database retention.
- On-Premises:Dedicated hardware deployments persist where FDA traceability rules for food retailers mandate localized audit trails or where legacy ERP connectors resist API migration. These installations concentrate among mid-market chains with decades-old technical debt and constrained IT modernization budgets.
- Hybrid:Split architectures preserve sensitive transaction data on local servers while pushing analytics workloads to cloud infrastructure. Retailers with phased migration roadmaps favor this bridge configuration.
- Mobile:Native iOS and Android applications enable floor staff to execute cycle counts, receive alerts, and adjust stock positions without workstation dependency. Field-heavy operations in warehouse and distribution contexts drive uptake.
Cloud-Based leads on scale; Mobile leads on momentum.
End User:
Organizational complexity dictates feature requirements and integration depth.
- Large Enterprises:Multi-entity stock orchestration demands real-time synchronization across hundreds of locations with sub-second latency. These buyers command custom development roadmaps and dedicated customer success resources from vendors.
- Franchise:Master service agreements consolidate procurement across dispersed owner-operators, creating concentrated demand for centralized dashboards with location-level permission granularity. United States franchise networks represent the most visible expansion vector.
- Medium Enterprises:Regional chains with 10-50 locations seek pre-configured connectors to major ERP platforms without extensive professional services engagement.
- Small Enterprises:Single-location retailers prioritize out-of-box functionality with minimal implementation overhead and subscription pricing aligned to transaction volume tiers.
Large Enterprises anchor current revenue; Franchise networks are expanding most quickly.
Deployment:
Channel architecture determines synchronization requirements and API throughput specifications.
- Multi-Store:Distributed inventory visibility across regional footprints requires conflict resolution algorithms for simultaneous stock adjustments. These deployments concentrate among United States specialty retailers expanding from flagship locations into secondary markets.
- E-commerce:Direct-to-consumer fulfillment mandates real-time availability publication across marketplaces, social commerce platforms, and proprietary storefronts with millisecond update frequencies.
- Chain Operations:Corporate-controlled location networks benefit from centralized procurement and standardized replenishment policies enforced through master data management.
- Single-Store:Standalone installations serve independent retailers with straightforward stock tracking needs and limited integration complexity.
Multi-Store dominates transaction volume; E-commerce shows the steepest expansion trajectory.
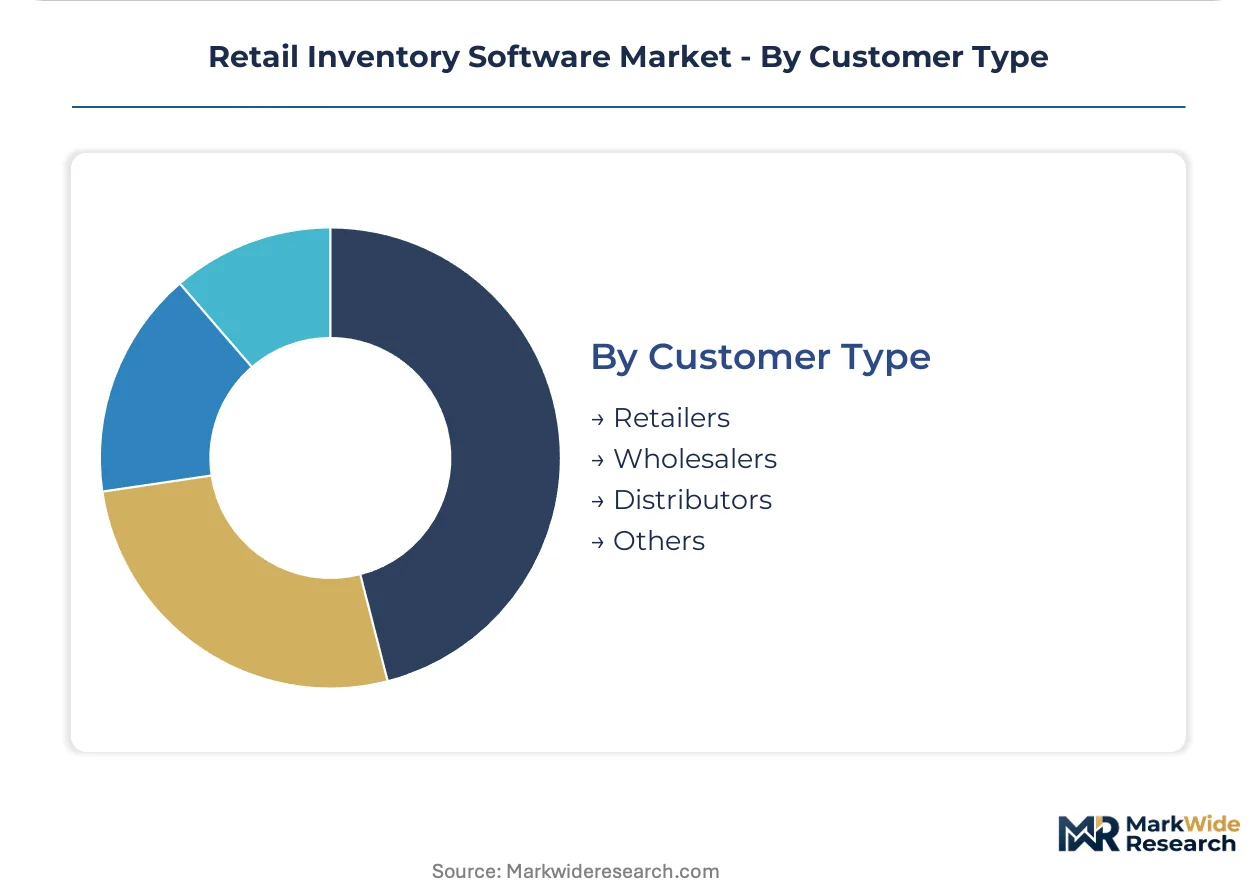
Customer Type:
Position in the value chain shapes inventory velocity and replenishment automation priorities.
- Retailers:Point-of-sale integration and omnichannel fulfillment coordination drive specification requirements, with grocery and apparel verticals representing the largest addressable pools.
- Distributors:Cross-dock operations and vendor-managed inventory programs necessitate advanced forecasting modules and supplier collaboration portals.
- Wholesalers:Bulk transaction processing and pallet-level tracking differentiate requirements from unit-level retail implementations.
- Others:Third-party logistics providers and inventory-as-a-service operators adopt white-label configurations for client-specific visibility layers.
Retailers command the largest installed base; Distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost differentials between jurisdictions are redirecting cloud infrastructure investment toward markets with harmonized data residency frameworks. Retailers operating across multiple territories face escalating arbitrage pressure as GDPR-mandated certifications in Europe inflate operational overhead relative to United States or Asian deployments.
United States
Warehouse automation investment in distribution centers drives millisecond-latency inventory tracking demand. State-level privacy statutes in California and Virginia compound federal compliance burdens, accelerating SaaS migration away from legacy on-premises architectures. Dallas-Fort Worth and Chicago logistics corridors concentrate robotics deployment requiring synchronized stock feeds.
Germany
Multi-entity stock orchestration demands from Mittelstand manufacturers expanding into retail channels elevate ERP-integrated platform requirements. EU AI Act algorithmic transparency obligations mandate explainable decision pathways for automated replenishment engines deployed nationwide. Munich and Stuttgart industrial clusters host pharmaceutical and automotive retailers adopting certified cloud infrastructure for FDA-aligned traceability.
China
Dual carbon goals under MIIT directives compel energy-efficient data center migration for inventory platform hosting. GB standards for electronic data interchange reshape API connectivity requirements between domestic retailers and international suppliers. Yangtze River Delta e-commerce hubs in Shanghai and Hangzhou deploy real-time availability publication across social commerce platforms.
United Kingdom
Post-Brexit divergence from EU data adequacy rulings fragments cross-border cloud storage architectures for omnichannel retailers. FCA operational resilience requirements for listed retail groups mandate sub-second inventory synchronization across London and regional fulfillment nodes. Birmingham and Manchester distribution networks prioritize RFID-enabled cycle counting to reduce shrinkage in apparel verticals.
India
PLI scheme incentives for electronics manufacturing drive component traceability software adoption among retail supply chains. BIS data localization guidelines for payment-adjacent inventory systems redirect cloud contract awards toward domestic hyperscale providers. Karnataka and Maharashtra technology corridors host franchise networks consolidating procurement through centralized orchestration dashboards.
Retail Inventory Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade platforms commanding concentrated procurement decisions while mid-market solutions fragment across vertical-specific vendors. The vendor landscape organizes around three tiers: ERP-embedded incumbents with deep integration moats, warehouse-centric execution specialists competing on fulfillment velocity, and cloud-native challengers monetizing through consumption-based analytics. Consolidation pressure intensifies as interoperability certification delays strain customer relationships and API-native architectures displace legacy batch systems.
Within the ERP-embedded tier, Oracle Corporation and SAP SE exemplify platform consolidation strategies that leverage existing enterprise relationships to anchor inventory modules within broader digital transformation contracts. Manhattan Associates occupies a position among warehouse-centric specialists, representing the fulfillment-velocity archetype that competes on operational execution rather than functional breadth. These three anchors demonstrate how competitive positioning diverges between integration depth and operational specialization across the addressable market.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Microsoft Corporation |
| IBM Corporation |
| NCR Corporation |
| Manhattan Associates |
| Fishbowl Inventory |
| NetSuite |
| Lightspeed |
| Others |
Pricing and Supply Chain Analysis
Franchise network procurement consolidation through master service agreements is compressing vendor pricing power and forcing platform providers toward consumption-based monetization models that align costs with transaction volumes.
Pricing Analysis
Distributor margins in cloud-based inventory software deployments typically absorb 15-25% of end-customer spend before reaching retail IT budgets. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and data sovereignty certification tier. Cost compression in mid-market SaaS tiers is intensifying because hyperscaler infrastructure competition is driving compute pricing downward. Small enterprises exhibit highest price sensitivity due to constrained IT budgets, while large enterprises prioritize latency performance over per-seat cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced server processors and memory modules that anchor cloud data center operations for inventory platform hosting. Software supply chains draw from open-source component libraries, proprietary API frameworks, and certified cloud infrastructure providers across the United States, Germany, and China. Tariff exposure on networking equipment imports into the United States elevates total cost of ownership for hybrid architecture adopters. Distribution runs through direct vendor sales teams for enterprise accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR-mandated cloud certifications in Europe inflate operational overhead relative to United States deployments, creating arbitrage opportunities for vendors with dual-region infrastructure strategies.
For Market Incumbents: Hedge against API-native challengers by deepening ERP integration moats and acquiring specialized warehouse execution firms that compress fulfillment latency. Invest in explainable AI governance tooling to preempt EU AI Act compliance displacement. Capacity addition in certified European data centers preserves contract eligibility with German pharmaceutical and automotive retailers. For New Entrants and Emerging Players: Begin with franchise network orchestration platforms targeting United States-based multi-location operators with centralized procurement mandates. White-label configurations for third-party logistics providers represent the most penetrable segment given minimal incumbent saturation. A channel partnership strategy with regional ERP implementers accelerates customer acquisition without direct enterprise sales overhead. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native challengers monetizing consumption-based replenishment analytics in mid-market segments. Long-term viability hinges on algorithmic transparency capabilities and cross-border data sovereignty architecture. Watch for FDA traceability rule expansion into additional food categories as inflection indicator for compliance-heavy platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity with SAP and Oracle systems secures enterprise renewal rates above 90%. |
| Acquisition of Specialist Firm | Warehouse execution specialists add millisecond-latency capabilities that grocery chains demand. |
| Geographic Expansion | Certified cloud infrastructure in Germany unlocks Mittelstand manufacturing-retail hybrid demand. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure reduce compute costs for seasonal elasticity. |
| Product Launch | Explainable AI modules address EU AI Act transparency mandates before competitor response. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and ERP vendor annual reports. Bottom-up sizing of cloud deployment volumes triangulated against top-down retail IT spending estimates from national statistical agencies.
Segment-weighting applied deployment architecture, organizational scale, and channel complexity as primary dimensions across the modeling period, with vertical-specific layering for grocery, apparel, and pharmaceutical retail. CAGRs derived from logistic adoption curves fitted to historical cloud migration patterns and warehouse automation investment cycles. Forecast inputs incorporated GDPR compliance cost trajectories and RFID protocol standardization timelines.
Several conditions sit outside the modeled scope, including sovereign cloud mandates from jurisdictions not yet issuing final regulations and breakthroughs in quantum encryption that could reshape data residency requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
America's AI in the Retail Market
Retail Technology
Ticket Machine Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Smart Shelves Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
E-Retail Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
North America Automation in Retail Market
Retail Technology
AR in Retail Market
Retail Technology
Digital Kiosk Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Global Kiosk Market