
 Customer-Facing Technology Market | 2026-2036
Customer-Facing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Customer-Facing Technology Market Outlook
ISO/IEC 27001 certification for information security management is reorganizing vendor eligibility in enterprise procurement cycles. Samsung Electronics leverages vertical integration across display hardware and embedded software stacks. Salesforce sustains dominance in cloud-based CRM deployments through channel density and ISV ecosystem control. Diebold Nixdorf anchors its position in banking self-service terminals via manufacturing scale and service infrastructure.
Customer-facing technology encompasses hardware and software systems designed to facilitate direct interaction between organizations and consumers, typically incorporating touch interfaces, biometric authentication, natural language processing, and real-time data synchronization across edge and cloud nodes. Its primary commercial purpose is to reduce service friction, capture behavioral data, and enable personalized engagement at scale. Interactive kiosks and mobile apps currently occupy the largest margin pools, while chatbot deployments represent the fastest-expanding segment as large language models reduce implementation costs. Cloud-based deployment models lead in new installations, though hybrid architectures persist in regulated sectors where data residency requirements constrain full SaaS migration.
FCC guidelines on robocalling and automated communications shape consent frameworks for voice-based customer outreach in the United States, while GDPR and the EU AI Act impose algorithmic transparency and data minimization obligations on European deployments. FDA oversight of software-as-medical-device also constrains health-adjacent kiosks that capture vital signs or deliver diagnostic information. Stakeholders must monitor diverging compliance timelines across jurisdictions when architecting unified technology platforms.
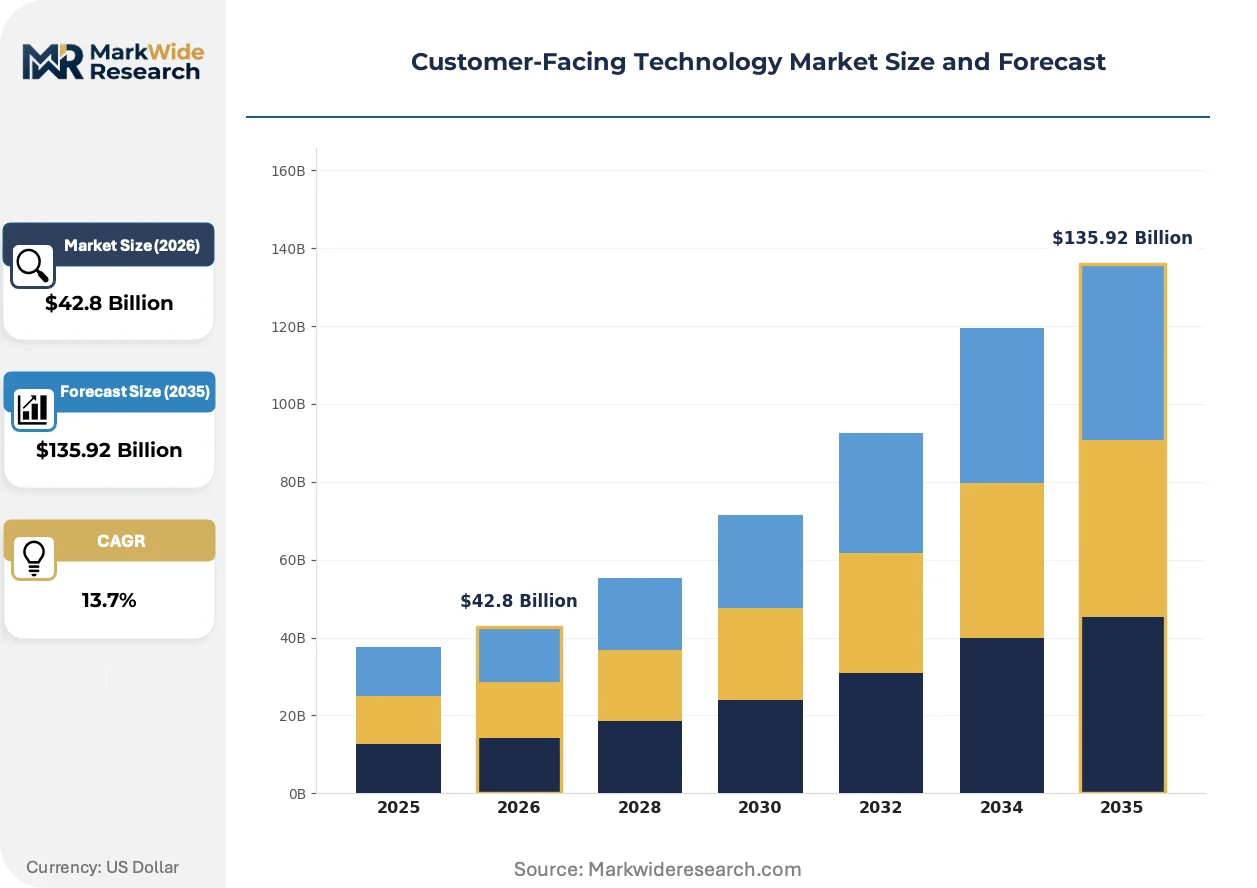
Market Dynamics
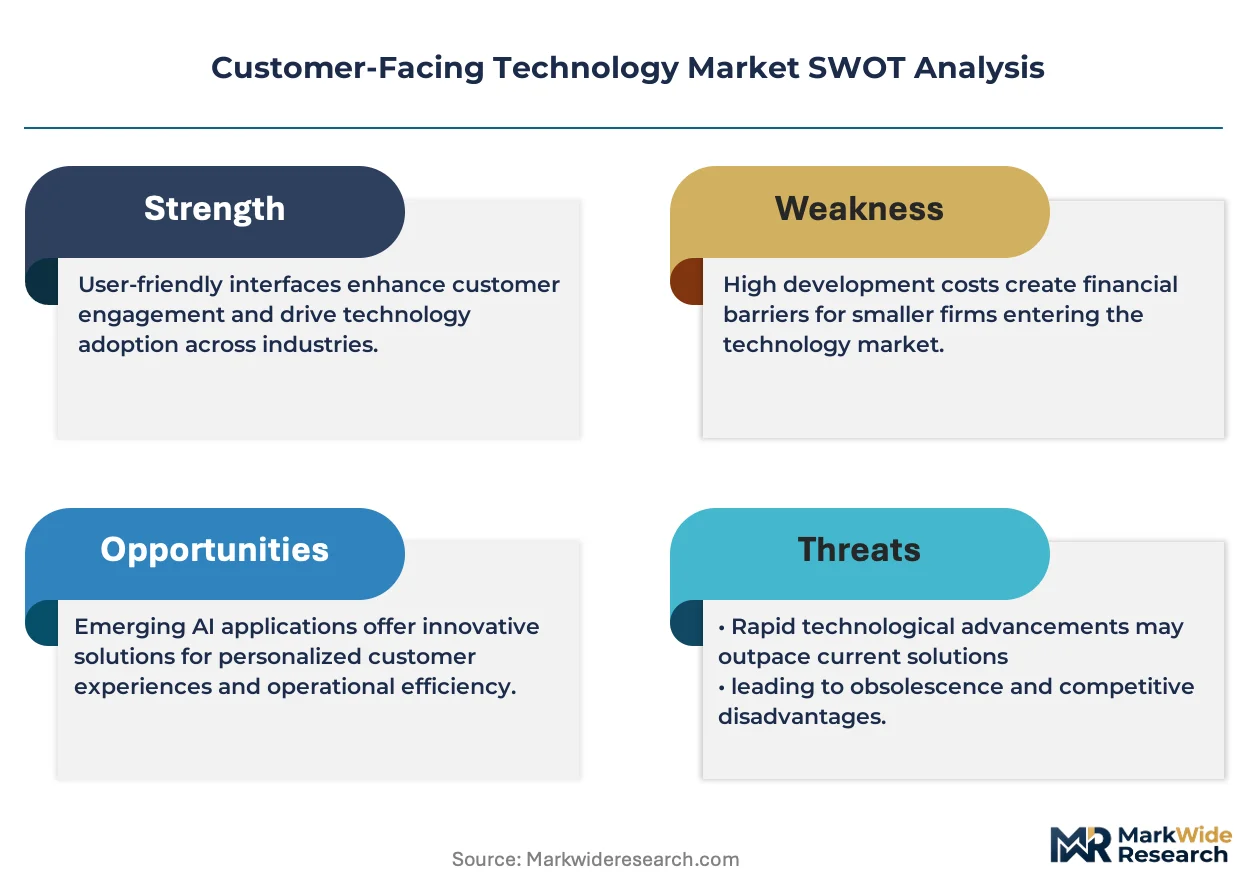
Large language models are compressing implementation costs for conversational interfaces, accelerating chatbot deployment across quick-service restaurants and retail chains while forcing incumbent vendors to reprice legacy software licenses.
Growth Catalysts
- EU AI Act transparency mandates:Automated customer interaction systems in Europe must deploy explainable algorithms, creating procurement pull for vendors with interpretable model architectures.
- Self-service kiosk penetration in grocery:Supermarket chains deploy touch-screen checkout terminals to reduce labor costs and capture real-time basket data for personalization engines.
- Biometric authentication integration:Fingerprint and facial recognition modules are embedding into banking terminals and hospitality check-in systems, reducing fraud rates and transaction friction.
Market Restraints
- Semiconductor supply concentration:Edge AI chips for kiosk vision processing depend on Taiwan-based foundry capacity, exposing hardware vendors to geopolitical disruption risk.
- FCC robocalling consent frameworks:Voice-based customer outreach systems face tightened opt-in requirements, increasing compliance overhead for automated calling campaigns in the United States.
- Legacy POS integration friction:New customer-facing terminals must interface with decades-old retail transaction protocols, extending deployment timelines and customization costs.
Strategic Opportunities
- India BIS certification pathways:The country's standards body is streamlining approval for imported interactive displays, lowering barriers for kiosk manufacturers targeting quick-service restaurant expansion.
- Healthcare-adjacent diagnostic kiosks:FDA software-as-medical-device pathways are clarifying for terminals that capture vital signs, opening regulated revenue pools beyond retail.
- Voice-to-text convergence with LLMs:Natural language processing engines are merging with speech recognition to enable multilingual self-service without human agent escalation.
Industry Challenges
- ISO/IEC 27001 certification timelines:Enterprise procurement cycles now require information security management validation, delaying vendor onboarding by 6-12 months for uncertified suppliers.
- Edge-to-cloud synchronization complexity:Real-time behavioral data pipelines must maintain sub-second latency across distributed kiosk networks while respecting data residency constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer-Facing Technology Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $135.92 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: CRM, Chatbots, Mobile Apps, Interactive Kiosks Customer Segment: Retail, Banking, E-Commerce, Hospitality Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services Feature Set: Personalization, Automation, Analytics, Security |
| Companies Covered | Samsung Electronics Co. Ltd., Sony Corporation, LG Corporation, NEC Display Solutions, Panasonic Corporation, Diebold Nixdorf Incorporated, Salesforce, Microsoft, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer-Facing Technology Market Strategic Shifts
Generative AI is restructuring how organizations design customer interaction workflows, shifting investment from rules-based chatbots toward adaptive conversational systems that learn from transaction patterns.
Touchless gesture interfaces are supplanting capacitive touchscreens in high-traffic environments. Quick-service restaurants in the United States are piloting mid-air haptic controls to reduce surface contamination concerns. This interface shift is compressing hardware refresh cycles as chains replace three-year-old terminals ahead of schedule.
The EU AI Act algorithmic transparency requirements are reshaping vendor development priorities. Automated decision-making systems must now provide audit trails for customer-facing recommendations. Banking self-service terminal manufacturers are responding by embedding explainability modules that surface logic trees for loan pre-qualification outcomes.
Buyer procurement patterns are consolidating around integrated platform vendors rather than point solutions. Retail chains are bundling kiosk hardware, CRM software, and analytics subscriptions into single-vendor contracts. This preference shift is most visible in the United States, where big-box retailers are reducing supplier counts from twelve to three core technology partners.
Customer-Facing Technology Market Segmentation
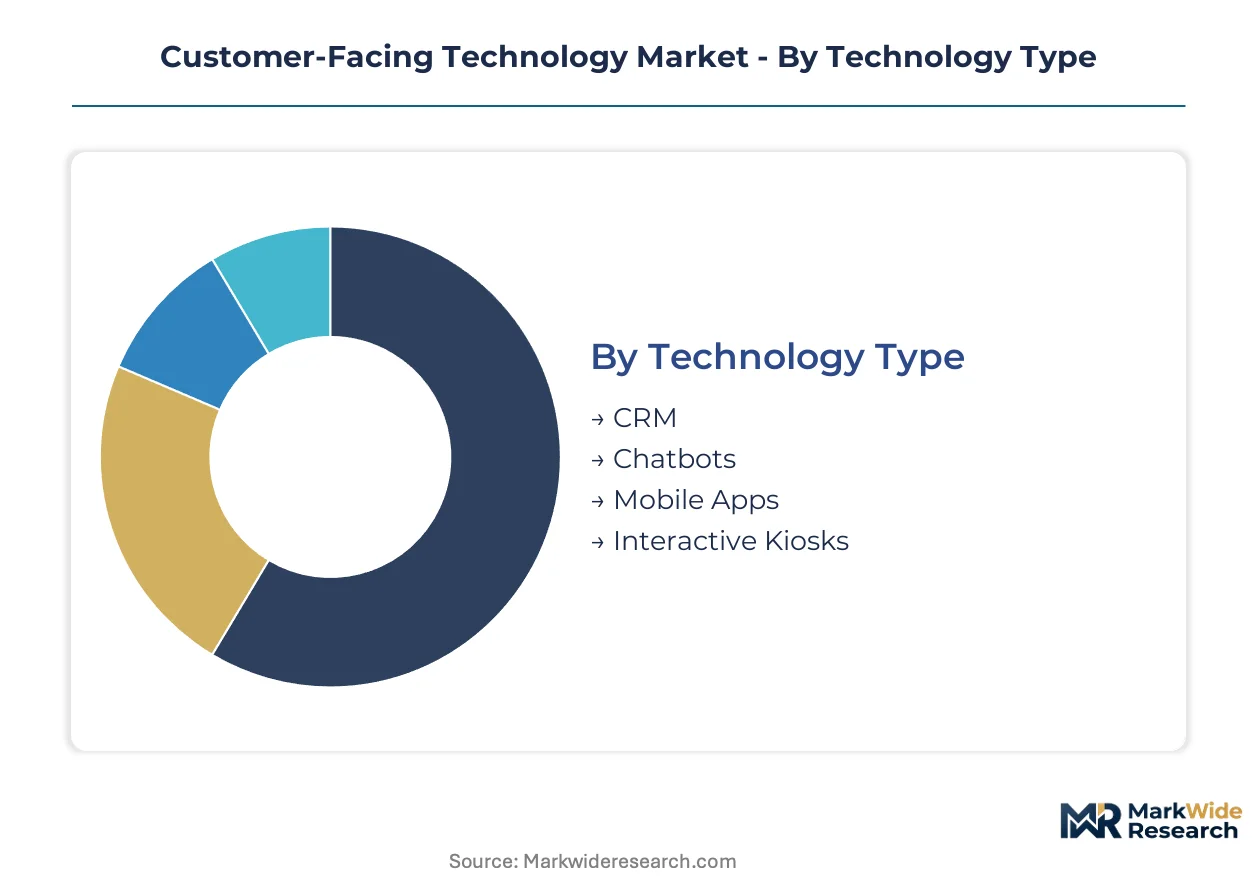
Channel mix varies sharply across customer-facing technology deployments. Retail chains favor bundled hardware-software packages, while banking and hospitality operators prioritize managed service contracts with uptime guarantees. Understanding segment boundaries clarifies where procurement authority sits and which vendors control access.
Technology Type:
Channel economics diverge by interface modality. Touch-based hardware flows through specialized integrators, while conversational software deploys via direct SaaS relationships.
- CRM:Cloud-native platforms consolidate customer data across touchpoints, enabling real-time personalization. Banking and retail chains in the United States drive procurement, constrained by ISO/IEC 27001 certification requirements that filter vendor pools.
- Chatbots:Large language models compress implementation costs for natural language interfaces. Quick-service restaurants deploy these most aggressively to deflect order-taking labor, though EU AI Act transparency mandates complicate European rollouts.
- Mobile Apps:Native and progressive web applications extend self-service to personal devices.
- Interactive Kiosks:Touch-screen terminals with embedded vision processing handle checkout and information services.
CRM dominates installed base. Chatbots are where expansion concentrates.
Customer Segment:
Application context dictates specification requirements and compliance exposure.
- Retail:Self-service checkout terminals and loyalty integration platforms capture basket data for personalization engines. Big-box chains in the United States lead capital deployment, pressured by labor cost targets and real-time inventory synchronization needs.
- Banking:Biometric-enabled self-service terminals handle cash dispensing, account inquiry, and loan pre-qualification. Fraud reduction mandates and explainability requirements under EU AI Act reshape vendor selection toward interpretable algorithm architectures.
- E-Commerce:Digital-native checkout and recommendation systems operate without physical touchpoints.
- Hospitality:Check-in terminals and in-room control interfaces reduce front-desk staffing.
Retail commands the largest hardware procurement volumes. Banking offers the steepest expansion trajectory for biometric-integrated terminals.
Deployment Model:
Cost tier and data residency constraints determine architecture selection.
- Cloud-Based:SaaS delivery minimizes upfront capital and accelerates feature updates. New installations favor this model, though GDPR and sector-specific data localization rules constrain full migration in European and health-adjacent deployments.
- Hybrid:Edge processing for latency-sensitive operations pairs with cloud analytics. Regulated sectors adopt this most frequently to satisfy data residency while capturing centralized intelligence.
- On-Premise:Fully captive infrastructure persists in high-security environments.
- Managed Services:Outsourced operations and maintenance contracts transfer uptime risk to vendors.
Cloud-based leads new installations. Hybrid is gaining share fastest where compliance complexity intersects with real-time performance requirements.
Feature Set:
Margin pools concentrate in capabilities that reduce labor or capture proprietary behavioral data.
- Personalization:Recommendation engines and dynamic content adaptation increase transaction value. Retail chains deploy these to replicate online targeting in physical environments, though algorithmic transparency obligations under EU AI Act raise implementation costs.
- Automation:Workflow orchestration and self-service routing eliminate human touchpoints. Quick-service restaurants prioritize order automation to compress service times and reallocate labor to food preparation.
- Analytics:Behavioral data pipelines and predictive modeling inform operational decisions.
- Security:Biometric authentication, encryption, and audit logging protect transaction integrity.
Automation dominates current procurement priorities. Personalization is where vendor differentiation and pricing power concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC robocalling consent frameworks and EU AI Act transparency mandates are reshaping procurement patterns across major economies. Quick-service restaurant chains and big-box retailers in the United States drive hardware deployment, while European banking terminals face algorithmic explainability requirements.
United States
Quick-service restaurants and big-box retailers deploy self-service kiosks to compress checkout times and capture real-time basket data. FCC guidelines on automated communications impose tightened opt-in requirements for voice-based outreach systems. Dallas-Fort Worth and Atlanta metro areas concentrate pilot deployments of touchless gesture interfaces in high-traffic food service environments.
Germany
Banking self-service terminals integrate biometric authentication modules to reduce fraud rates in cash dispensing and loan pre-qualification workflows. EU AI Act mandates require explainable algorithms for automated customer recommendations, favoring vendors with interpretable model architectures. Frankfurt and Munich anchor development clusters for compliance-ready terminal software.
India
Quick-service restaurant expansion drives demand for imported interactive displays and self-service ordering terminals. BIS certification pathways are streamlining approval processes for kiosk manufacturers targeting food service deployment. Bangalore and Mumbai metropolitan areas concentrate domestic system integration capabilities for retail and hospitality sectors.
Japan
Hospitality operators deploy check-in terminals and in-room control interfaces to reduce front-desk staffing requirements in urban hotel markets. METI guidelines shape data handling standards for customer-facing systems in tourism-dependent regions. Tokyo and Osaka lead capital deployment for multilingual self-service platforms targeting international visitor recovery.
United Kingdom
Retail chains consolidate procurement around integrated platform vendors bundling kiosk hardware with CRM software and analytics subscriptions. GDPR data minimization obligations constrain full cloud migration for customer behavioral data pipelines. London and Manchester anchor vendor selection decisions for enterprise-grade self-service deployments.
Customer-Facing Technology Market Competitive Environment
Player mix skews toward diversified electronics conglomerates with captive display manufacturing and enterprise software platforms with dense ISV ecosystems. Market structure shows tiered concentration, with integrated hardware-software vendors occupying premium procurement relationships and point-solution specialists competing on implementation speed. Two strategic archetypes dominate: vertically integrated display manufacturers and cloud-native CRM platforms. Competitive moves center on strategic partnerships reducing supplier counts and portfolio diversification into adjacent biometric authentication modules.
Within the diversified electronics tier, Samsung Electronics Co. Ltd. and LG Corporation exemplify vertical integration across display hardware and embedded software stacks. Salesforce occupies a position representing cloud-native platform consolidation, anchoring procurement relationships through channel density. Diebold Nixdorf Incorporated sits within the banking terminal specialization archetype, its manufacturing scale and service infrastructure serving as a reference point for self-service hardware deployment.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| Sony Corporation |
| LG Corporation |
| NEC Display Solutions |
| Panasonic Corporation |
| Diebold Nixdorf Incorporated |
| Salesforce |
| Microsoft |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
ISO/IEC 27001 certification gates enterprise procurement eligibility while simultaneously stratifying vendor pricing tiers, forcing uncertified suppliers into discount positioning and certified incumbents toward premium anchoring across banking and retail deployment contracts.
Pricing Analysis
Certification level (ISO/IEC 27001, CE marking, FDA-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with biometric-integrated terminals commanding higher positioning than basic touch-screen units. Cost compression in the standard tier is intensifying because large language models commoditize conversational software components. Quick-service restaurant chains exhibit highest price sensitivity, while banking operators prioritize security-grade certification over unit economics.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing capacity constrains edge AI chip availability for kiosk vision processing modules. Hardware assembly concentrates in China, South Korea, and Taiwan, with embedded software development anchored in the United States and Germany. Raw material dependencies span display panels, biometric sensors, and specialized edge processors. Single-source vulnerability in Taiwan-based foundry exposure threatens hardware delivery timelines. Distribution runs through specialized systems integrators serving vertical-specific deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around algorithmic transparency and data residency creates durable defensive moats for vendors with pre-certified, explainable architectures and established compliance documentation.
For Market Incumbents: Secure ISO/IEC 27001 renewal timelines ahead of procurement cycle peaks to maintain enterprise eligibility. Deepen backward integration into biometric sensor modules to reduce Taiwan foundry exposure and capture margin pools in banking terminal deployments. Counter emerging LLM-native chatbot vendors by bundling legacy CRM relationships with managed service contracts that elevate switching costs.
For New Entrants and Emerging Players: Anchor in India's quick-service restaurant expansion corridor where BIS certification streamlining reduces import friction for interactive display manufacturers. Target mid-size retail chains in the United Kingdom seeking to consolidate from twelve suppliers to three integrated platform partners. Pursue white-label kiosk hardware partnerships with domestic system integrators lacking captive manufacturing capabilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biometric-integrated terminal manufacturing as edge AI chip requirements expand. Long-term viability favors vendors with diversified foundry relationships and recurring managed service revenue streams. Monitor FDA software-as-medical-device clearance timelines for healthcare-adjacent kiosk developers as inflection signals for regulated revenue pool access.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration | Embedding fingerprint and facial recognition reduces fraud rates in banking terminals while differentiating hardware offerings. |
| EU AI Act Compliance Certification | Explainable algorithm documentation opens procurement access to European banking and retail deployment contracts. |
| Managed Service Contract Expansion | Uptime guarantee offerings transfer operational risk from retail chains while locking in recurring revenue streams. |
| India BIS Certification Streamlining | Accelerated approval pathways lower barriers for kiosk manufacturers targeting quick-service restaurant growth corridors. |
| Healthcare Diagnostic Kiosk Development | FDA software-as-medical-device pathways unlock regulated revenue pools beyond traditional retail and banking segments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with technology procurement officers, kiosk deployment project managers, and banking self-service terminal engineers; and secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory submission databases. Bottom-up unit deployment estimates triangulated against top-down market sizing from channel partner shipment data.
Across the analysis window, the forecasting framework modeled technology type, customer segment, deployment model, and feature set dimensions. CAGRs derived from historical deployment trajectories adjusted for regulatory inflection points and foundry capacity constraints. Edge AI chip demand curves and biometric authentication adoption rates served as primary industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained Taiwan foundry capacity and stable EU AI Act implementation timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as semiconductor supply diversification and algorithmic transparency enforcement standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
America's AI in the Retail Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Global Smart Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Cash Register Machines Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Smart Shelves Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
AR in Retail Market