
 Retail-As-A-Service (Raas) Market | 2026-2036
Retail-As-A-Service (Raas) Market Size, Share, and Industry Trends Forecast 2026-2036
Retail-As-A-Service (Raas) Market Analytics
Subscription-based software-defined point-of-sale infrastructure is decoupling hardware ownership from retail operations. Amazon leverages captive cloud infrastructure to anchor fulfillment-as-a-service bundles for third-party merchants. Microsoft sustains enterprise-grade API ecosystems that integrate inventory, payment, and customer analytics into unified dashboards. IBM Corporation competes through hybrid deployment architectures that address data residency requirements across regulated European markets.
Retail-As-A-Service denotes a commercial model where retailers procure technology infrastructure, software platforms, and operational support through recurring service contracts rather than capital expenditure, typically delivered via cloud-native architectures with 99.9% uptime SLAs and API-first integration protocols. The subscription model segment leads current deployment patterns among mid-market chains seeking predictable operating expenditure structures, while hybrid solutions represent the fastest-growing integration category as legacy retailers phase out on-premise systems without full cloud migration. Cloud computing underpins the majority of new installations, though IoT solutions command premium pricing where real-time shelf monitoring and automated replenishment justify sensor hardware costs.
The EU AI Act, GDPR, and REACH frameworks collectively shape product development priorities for RaaS vendors serving European retailers, particularly regarding automated decision-making transparency in customer analytics and restricted substance compliance in IoT hardware. The US Federal Trade Commission and state-level privacy statutes, notably the California Consumer Privacy Act, impose parallel compliance burdens for vendors with transatlantic operations. Stakeholders must monitor evolving algorithmic accountability standards and cross-border data transfer mechanisms as determinants of competitive access in major retail markets.
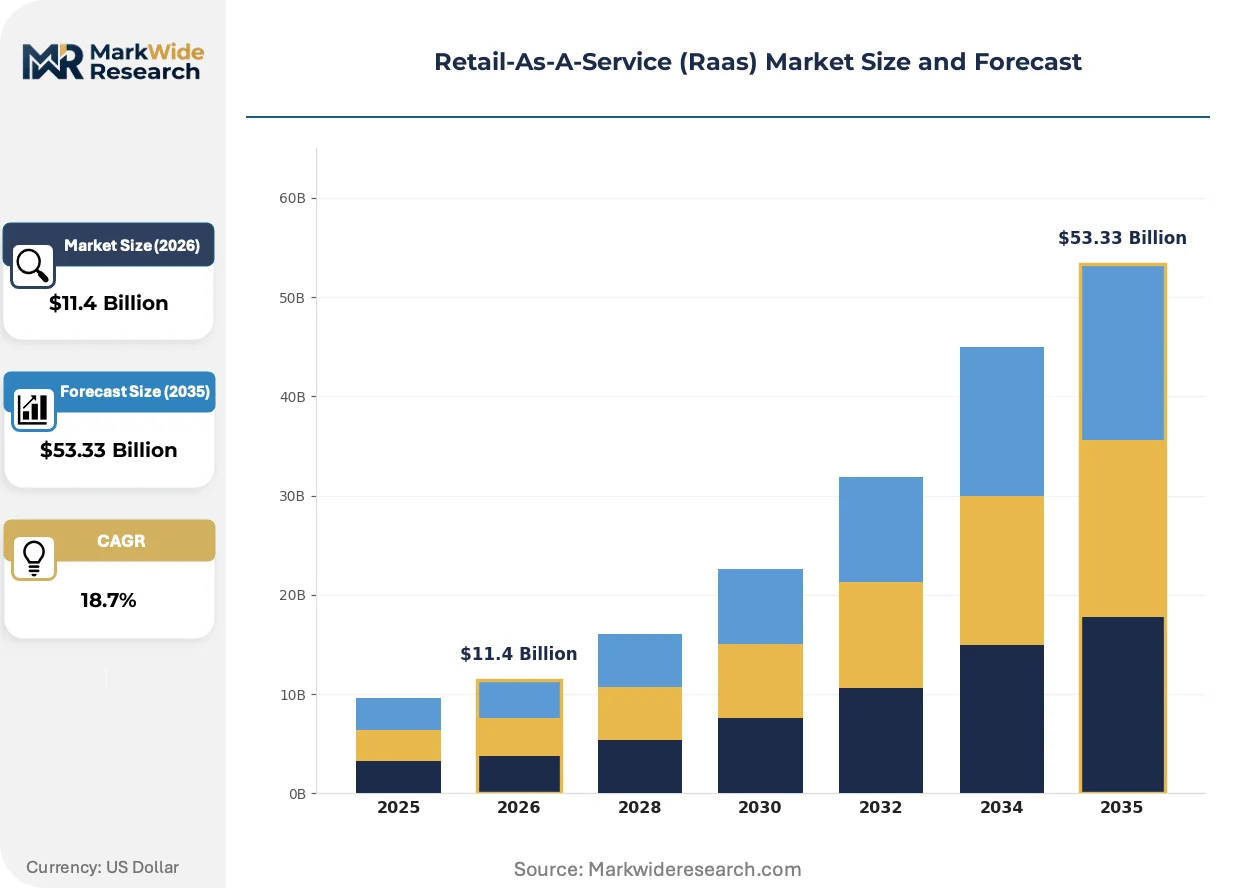
Market Dynamics
Subscription-based software-defined point-of-sale infrastructure is decoupling hardware ownership from retail operations, forcing legacy system vendors to pivot toward recurring revenue architectures or face displacement by cloud-native entrants offering 99.9% uptime SLAs.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making transparency requirements in customer analytics are accelerating retailer migration toward data-sovereign hosting architectures that embed audit-ready governance layers.
- Grocery chain modernization:Western European supermarket operators are replacing end-of-life on-premise systems with API-first platforms that unify inventory, payment, and loyalty management into single-dashboard operations.
- Edge computing deployment:Real-time shelf monitoring and automated replenishment systems are justifying sensor hardware investments through measurable labor cost reductions and stockout prevention.
Market Restraints
- Data residency fragmentation:Cross-border data transfer uncertainty between EU member states and third countries is complicating multi-national retailer deployments and inflating legal review costs.
- Legacy system technical debt:Decades-old mainframe integrations in mid-market chains require expensive middleware development before API-first platforms can achieve functional parity.
- Specialized talent scarcity:Shortages of cloud-native retail engineers and GDPR compliance specialists are extending implementation timelines and elevating professional services costs.
Strategic Opportunities
- France's retail consolidation wave:Independent specialty retailers in secondary urban markets remain underserved by current RaaS vendors, creating whitespace for mid-market-focused platform entrants.
- IoT-predictive maintenance convergence:Sensor networks that anticipate refrigeration and HVAC failures before they disrupt operations represent an adjacent service layer with premium pricing potential.
- CSRD reporting integration:Upcoming corporate sustainability disclosure requirements position RaaS vendors to embed carbon footprint tracking and supply chain transparency tools as differentiated modules.
Industry Challenges
- Hybrid architecture complexity:Retailers phasing out on-premise systems without full cloud migration face integration failures between legacy databases and modern API endpoints.
- Certification timeline compression:REACH substance restrictions on IoT hardware components are forcing rapid supplier qualification cycles that strain procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail-As-A-Service (Raas) Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $53.33 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription Model, Pay-Per-Use, Hosted Services, Hybrid Solutions Integration Level: API Integration, Plug-and-Play, In-House Solutions, Custom Integrations Customer Type: Small Businesses, Enterprises, Startups, Franchise Owners Technology: Cloud Computing, Mobile App Development, IoT Solutions, Data Analytics |
| Companies Covered | IBM Corporation, Fujitsu Limited, Cisco Systems, Toshiba Corporation, NEC Corporation, Cegid, Microsoft, Amazon, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail-As-A-Service (Raas) Market Evolving Landscape
Unified commerce platforms are collapsing the traditional separation between online and in-store transaction processing, creating architectural pressure on vendors that maintain separate codebases for each channel.
API-first middleware is unifying point-of-sale, inventory management, and customer analytics into single data layers. Mid-market grocery chains in Germany and the United Kingdom are adopting these stacks fastest, compressing vendor selection cycles from eighteen months to under six as procurement teams prioritize pre-integrated suites over best-of-breed assemblies.
GDPR enforcement actions by CNIL in France and the Information Commissioner's Office in the United Kingdom are tightening consent management requirements for loyalty programs. Retailers now demand RaaS platforms with built-in data subject request automation and purpose limitation controls, shifting competitive advantage toward vendors with native privacy engineering rather than bolt-on compliance modules.
Buyer preference for outcome-based commercial structures is displacing traditional per-terminal licensing in European markets. Retailers in the Netherlands and Belgium increasingly negotiate contracts tied to uptime guarantees and transaction volume thresholds rather than fixed fees, transferring operational risk to platform providers and squeezing margins for vendors without mature service delivery organizations.
Retail-As-A-Service (Raas) Market Segmentation
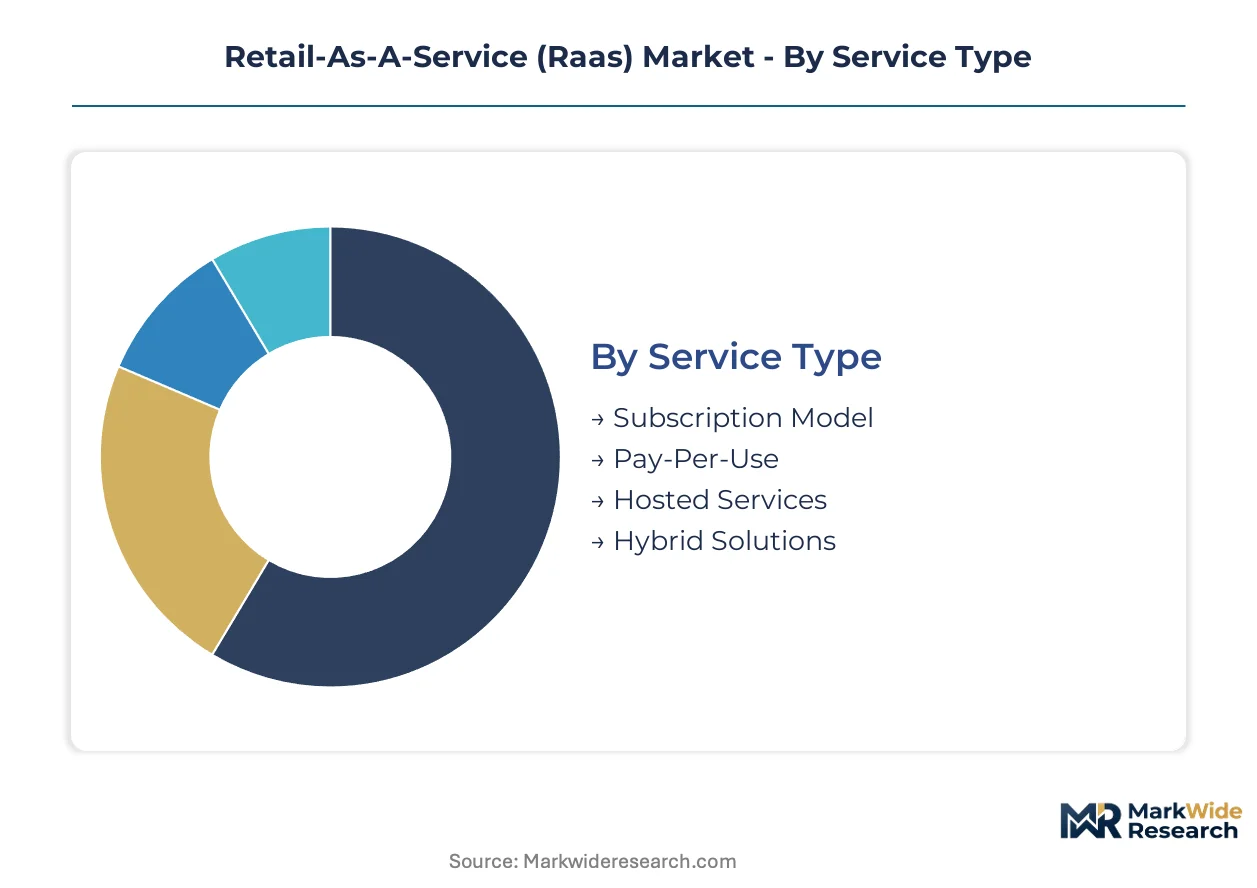
Retail-As-A-Service segmentation reveals how procurement patterns diverge across technical sophistication, operational scale, and regulatory exposure. Vendors configure delivery architectures differently for each slice, with integration complexity and compliance burden acting as the primary sorting mechanisms.
Service Type:
Replacement cycles vary dramatically by commercial structure, with capital-constrained retailers favoring arrangements that shift hardware risk to providers.
- Subscription Model:Recurring fee structures bundle software licensing, infrastructure hosting, and maintenance into predictable monthly expenditures. German and French mid-market grocery chains dominate current uptake, prioritizing operating expenditure predictability over ownership.
- Hybrid Solutions:Architectures split processing between cloud-native front-ends and on-premise data repositories address data residency mandates. Western European retailers phasing out legacy mainframes without full cloud migration drive steepest expansion trajectory here.
- Pay-Per-Use:Transaction-volume pricing aligns vendor compensation with actual retail activity. Seasonal operators and pop-up concepts in Belgian and Dutch urban centers favor this structure.
- Hosted Services:Dedicated single-tenant deployments satisfy audit requirements for high-transaction-volume operators. UK specialty pharmacy chains and luxury goods retailers specify these for GDPR Article 32 security demonstrations.
Subscription Model sits at the top of the volume ranking, with Hybrid Solutions climbing the fastest.
Integration Level:
Technical debt accumulation determines integration approach, with API maturity separating modern retailers from legacy operators.
- API Integration:RESTful and GraphQL interfaces enable real-time data exchange between POS, inventory, and customer analytics layers. German supermarket cooperatives and French retail federations mandate these for multi-vendor ecosystem compatibility.
- Custom Integrations:Bespoke middleware development bridges proprietary legacy systems with modern platforms. UK department store chains with decades-old ERP investments require extensive professional services engagement here.
- Plug-and-Play:Pre-certified hardware-software bundles minimize deployment friction. Independent specialty retailers in secondary French cities select these for speed-to-operation.
- In-House Solutions:Retailer-controlled development teams build proprietary connectors. Large UK grocery multiples with captive IT capabilities pursue this path for competitive differentiation.
API Integration commands the largest deployment base, while Custom Integrations expand most rapidly as legacy modernization accelerates.
Customer Type:
Organizational scale dictates service packaging, with procurement sophistication and compliance exposure shaping vendor engagement models.
- Enterprises:Multi-national operators negotiate master service agreements with data residency guarantees and 99.99% uptime SLAs. Pan-European grocery and apparel retailers anchor demand in this tier.
- Small Businesses:Independent operators prioritize rapid deployment and minimal technical overhead. Neighborhood retailers across Germany and the Netherlands populate this segment heavily.
- Franchise Owners:Networked operators require centralized governance with local execution flexibility. French retail cooperatives and UK convenience store franchises drive specialized platform development.
- Startups:Venture-backed entrants favor scalable architectures that accommodate rapid store count expansion. Direct-to-consumer brands establishing physical presence in London and Paris cluster here.
Enterprises generate the highest contract values, with Franchise Owners posting the strongest growth momentum.
Technology:
Infrastructure choices reflect data gravity requirements, with latency sensitivity and regulatory scope determining architecture selection.
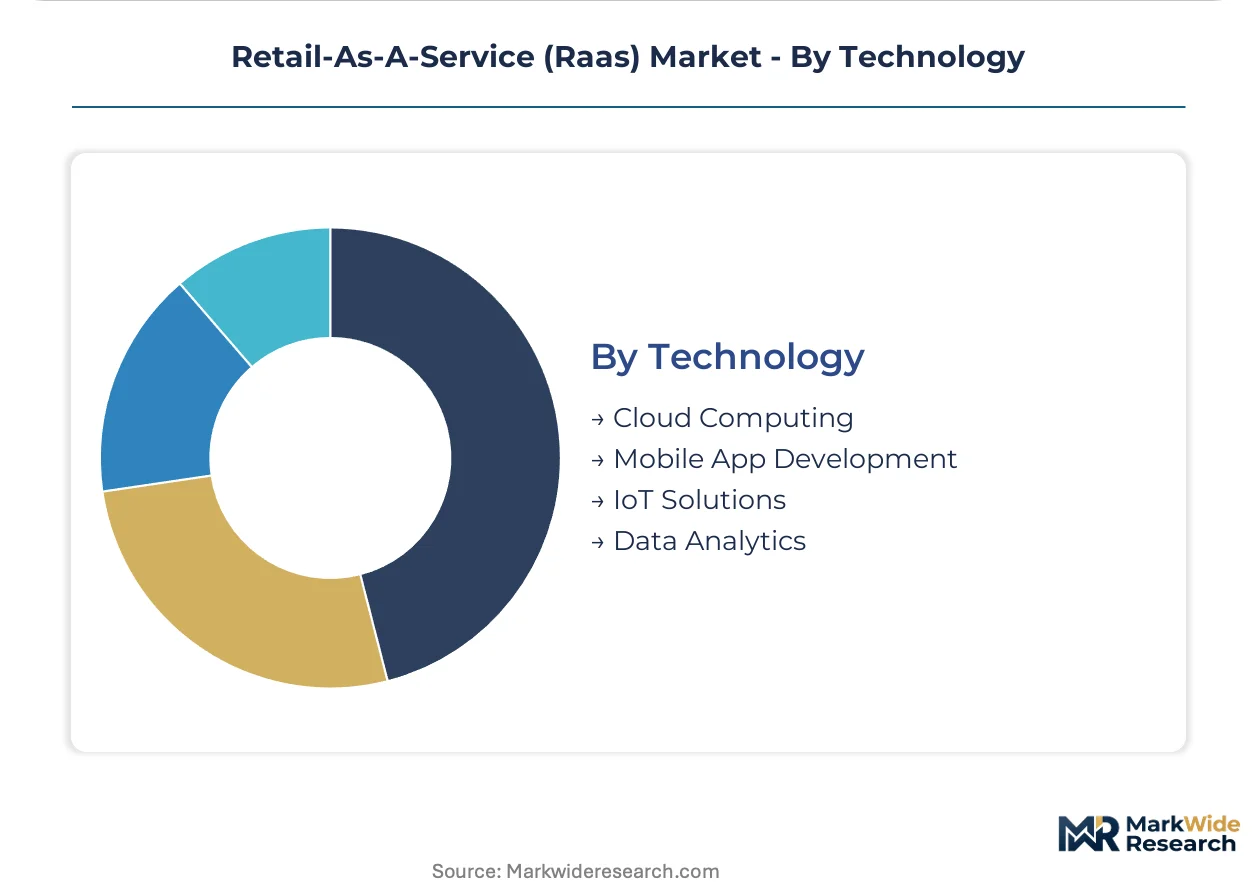
- Cloud Computing:Multi-tenant SaaS platforms deliver elastic capacity for transaction volume spikes. German and UK retailers lead adoption, with French operators accelerating post-GDPR enforcement clarification.
- IoT Solutions:Sensor networks enable automated shelf monitoring, predictive refrigeration maintenance, and footfall analytics. Premium grocery formats in urban France and Belgium justify hardware investments through labor optimization.
- Data Analytics:Customer behavior modeling and demand forecasting modules extract value from transaction streams. UK and Dutch retailers embed these for loyalty program optimization and dynamic pricing.
- Mobile App Development:Consumer-facing applications and associate-enablement tools extend platform reach. Younger demographics in Scandinavian markets drive feature prioritization here.
Cloud Computing dominates installed base, with IoT Solutions gaining share fastest as sensor economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's grocery cooperatives outpace French retail federations in API-first platform adoption, while UK specialty pharmacy chains lead in hosted service deployments for GDPR Article 32 compliance.
Germany
Mid-market grocery cooperatives in Bavaria and North Rhine-Westphalia are replacing end-of-life on-premise systems with subscription-based POS infrastructure. The Federal Office for Information Security (BSI) mandates baseline IT security certification for cloud service providers serving critical retail infrastructure. Frankfurt's financial technology cluster hosts data-sovereign hosting architectures that embed audit-ready governance layers for automated decision-making transparency.
France
Independent specialty retailers in secondary urban markets across Île-de-France and Auvergne-Rhône-Alpes remain underserved by current RaaS vendors, creating whitespace for mid-market-focused platform entrants. CNIL enforcement actions tighten consent management requirements for loyalty programs, shifting competitive advantage toward vendors with native privacy engineering. Paris anchors demand for unified commerce platforms that collapse online and in-store transaction processing into single-dashboard operations.
United Kingdom
UK specialty pharmacy chains and luxury goods retailers specify dedicated single-tenant deployments for GDPR Article 32 security demonstrations. The Information Commissioner's Office tightens purpose limitation controls, accelerating retailer migration toward data-sovereign hosting architectures. London's retail technology cluster concentrates vendor development of customer behavior modeling modules for loyalty program optimization.
Netherlands
Seasonal operators and pop-up concepts in Amsterdam and Rotterdam urban centers favor pay-per-use transaction-volume pricing structures. Dutch retailers increasingly negotiate contracts tied to uptime guarantees and transaction volume thresholds rather than fixed fees, transferring operational risk to platform providers. The Dutch Data Protection Authority enforces stringent cross-border data transfer protocols, complicating multi-national retailer deployments.
Belgium
Premium grocery formats in Brussels and Flemish urban centers justify IoT sensor hardware investments through measurable labor cost reductions and stockout prevention. REACH substance restrictions on IoT hardware components force rapid supplier qualification cycles that strain procurement teams. Antwerp's logistics technology cluster supports edge computing deployment for real-time shelf monitoring and automated replenishment systems.
Retail-As-A-Service (Raas) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native entrants displacing legacy system vendors through 99.9% uptime SLAs and API-first integration protocols. The vendor base concentrates around three strategic archetypes: hyperscale cloud providers with captive infrastructure, enterprise software incumbents with hybrid deployment capabilities, and specialized retail technology vendors with sector-specific compliance expertise. Dominant competitive moves include strategic partnerships with grocery cooperatives for modernization programs and geographic expansion into underserved secondary urban markets.
Within the enterprise software tier, IBM Corporation exemplifies hybrid deployment architectures that address data residency requirements across regulated European markets. Microsoft anchors API ecosystem development that unifies inventory, payment, and customer analytics into unified dashboards for mid-market chains. Amazon occupies a position in fulfillment-as-a-service bundles for third-party merchants leveraging captive cloud infrastructure.
| Leading Market Players |
|---|
| IBM Corporation |
| Fujitsu Limited |
| Cisco Systems |
| Toshiba Corporation |
| NEC Corporation |
| Cegid |
| Microsoft |
| Amazon |
| Others |
Value Network & Pricing Analysis
Sensor hardware costs for IoT-enabled shelf monitoring flow from Taiwanese semiconductor foundries through German system integrators, ultimately anchoring premium pricing tiers for French grocery operators seeking automated replenishment capabilities.
Pricing Analysis
Capacity additions in Netherlands-based edge computing facilities are reshaping price floors for real-time inventory processing services. Three-tier pricing structure across enterprise-grade, mid-market, and small-business levels reflects differentiation by API integration complexity and GDPR compliance certification. Pricing pressure stems from hyperscale cloud providers bundling POS infrastructure below standalone vendor economics. Small-business independent retailers exhibit highest price sensitivity, while pan-European grocery multiples prioritize uptime guarantees over per-terminal cost.
Supply Chain Analysis
France's domestic-content mandates for critical retail infrastructure are reshaping sourcing patterns for payment terminal hardware and edge computing modules. Component supply concentrates in Germany, Taiwan, and South Korea for semiconductor chipsets, with final assembly gravitating toward Poland and Czech Republic. Raw material dependencies span rare earth elements for sensor magnets, lithium-ion cells for mobile POS units, and specialized polymers for durable casings. Single-source vulnerability around Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through authorized value-added resellers with GDPR certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Retail-As-A-Service rests on cloud-native architecture standardization reducing per-deployment engineering hours, alongside premium-tier demand for AI-enabled customer analytics modules.
For Market Incumbents: Hedge against displacement by cloud-native entrants through captive professional services capacity for legacy system migration. Deepen backward integration into data-sovereign hosting infrastructure to defend against hyperscale provider bundling. Prioritize GDPR Article 32 certification investments as competitive moats in UK and French procurement cycles.
For New Entrants and Emerging Players: Begin with independent specialty retailers in secondary French urban markets where incumbent coverage remains sparse. Target Belgian and Dutch seasonal operators with pay-per-use pricing structures that transfer operational risk from capital-constrained buyers. Lead with plug-and-play deployment speed rather than customization depth.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-market vendors lack scale to absorb compliance engineering costs for EU AI Act and REACH frameworks. Long-term viability favors platforms with hybrid deployment architectures serving data residency requirements across regulated European markets. Watch for CNIL and ICO enforcement acceleration as inflection signal for privacy-engineering valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Unifies POS, inventory, and loyalty management into single-dashboard operations for German grocery cooperatives. |
| Data-Sovereign Hosting Expansion | Addresses GDPR Article 32 compliance requirements for UK specialty pharmacy and luxury retail segments. |
| IoT Sensor Network Deployment | Enables automated shelf monitoring and predictive maintenance for premium grocery formats in Belgium and France. |
| Hybrid Architecture Development | Bridges legacy mainframe systems with cloud-native front-ends for Western European retailers phasing out on-premise infrastructure. |
| Strategic Partnership with Retail Federations | Accelerates adoption through pre-integrated suites mandated by French retail cooperatives and German supermarket associations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for Retail-As-A-Service adoption. Primary engagement captured perspectives from retail technology procurement officers, cloud platform engineers, GDPR compliance specialists, and grocery chain operations directors. Secondary validation drew from hyperscaler capex disclosures, EU regulatory filing databases, retail federation technology surveys, and SEC filings of publicly traded vendors. Bottom-up deployment tracking across service type segments triangulated against top-down market sizing from infrastructure spending flows.
Segment-weighting approaches distributed value estimates across subscription model, hybrid solutions, pay-per-use, and hosted service categories, with further stratification by integration level and customer type. Cloud computing, IoT solutions, data analytics, and mobile app development technology segments received distinct growth trajectory modeling. CAGRs derived from deployment velocity curves, replacement cycle compression, and regulatory mandate timelines across the analysis window. Forecast inputs incorporated EU AI Act implementation pacing and REACH substance restriction phase-in schedules.
Several conditions sit outside the modeled scope, including potential trade policy disruptions affecting semiconductor supply, unforeseen GDPR enforcement pattern shifts, and macroeconomic contractions altering retailer capital expenditure priorities. Forecasts reflect documented assumptions regarding cloud migration rates and compliance cost absorption capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Global Kiosk Market
Retail Technology
E-Retail Market
Retail Technology
Cash Register Machines Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Self-Service Market
Retail Technology
Ticket Machine Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Digital Kiosk Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Retail Inventory Software Market