
 Smart Retail Systems Market | 2026-2036
Smart Retail Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Retail Systems Market Outlook
East Asian semiconductor foundries are expanding edge-AI chip output for retail endpoints, and this supply-side capacity event is broadening the hardware base for in-store analytics. Amazon.com leverages its cloud-to-edge infrastructure to sustain dominance in frictionless checkout systems. Intel Corporation anchors the silicon layer with low-power inference processors designed for shelf-edge cameras. NVIDIA Corporation competes through GPU-accelerated platforms that enable real-time customer behavior analytics in physical stores.
Smart retail systems integrate sensors, edge computing nodes, and software platforms to automate inventory tracking, personalize shopper engagement, and optimize checkout throughput with sub-100-millisecond response times. These systems serve commercial establishments seeking to merge digital convenience with physical proximity. Point of Sale systems occupy the largest revenue pool as legacy terminals undergo AI-enabled replacement cycles. Electronic Shelf Labels represent the fastest-expanding hardware category as dynamic pricing spreads from grocery to electronics retail. Cloud Computing underpins most new deployments, though edge-local processing is gaining share for latency-sensitive applications.
FDA guidelines on consumer data privacy in biometric retail analytics shape product development for vendors targeting US deployments. The EU AI Act imposes risk-classification requirements on automated customer profiling systems, while GDPR constrains how behavioral data flows across national borders. China's SAMR enforces algorithmic transparency rules for recommendation engines used in unmanned stores. Stakeholders must weigh regulatory fragmentation against the operational savings of centralized platform architectures.
Market Dynamics
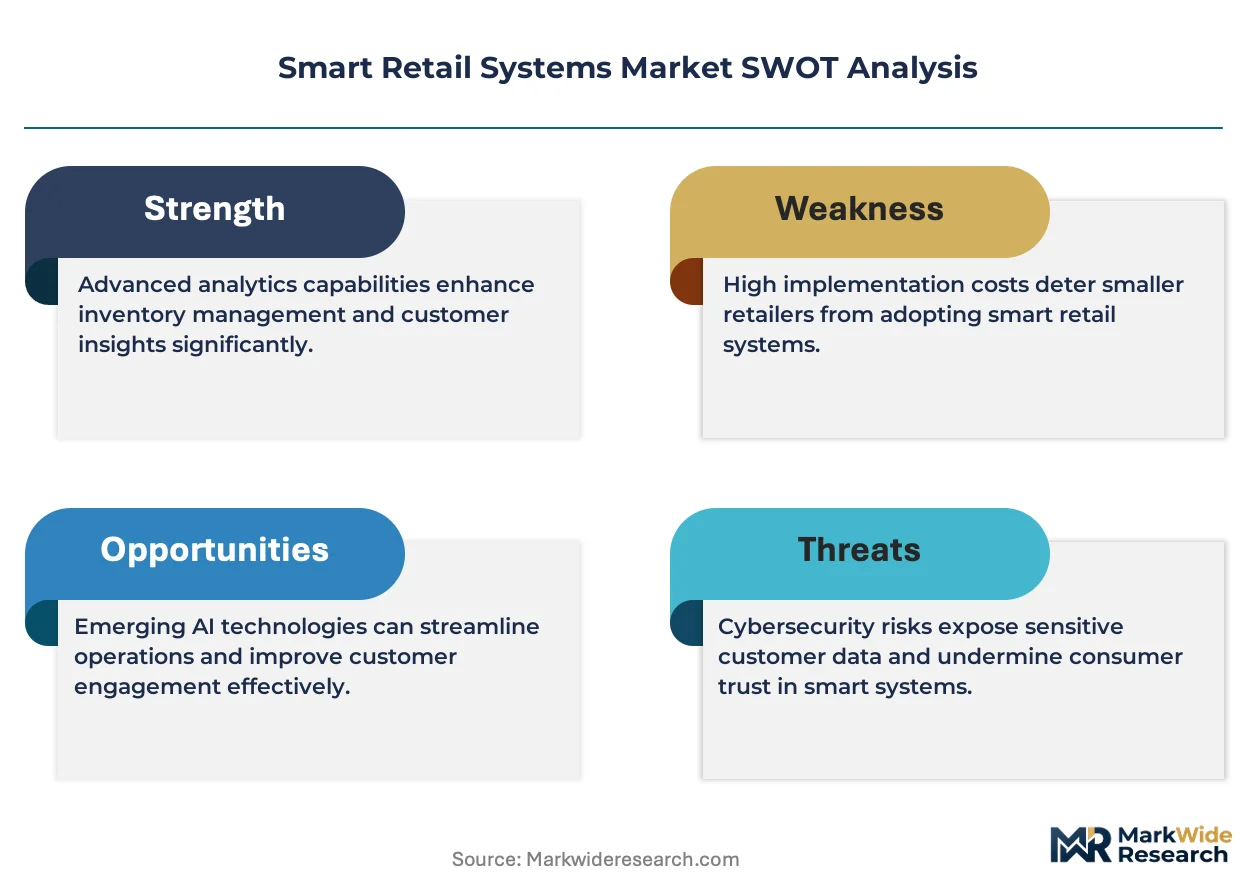
Edge AI inference at store level is compressing latency for real-time inventory tracking while EGD-aligned sustainability audits in Germany accelerate self-checkout hardware replacement cycles.
Growth Catalysts
- Electronic Shelf Labels:Dynamic pricing spreads from grocery to electronics retail, creating hardware refresh demand across European supermarket chains.
- EU AI Act risk-classification requirements:Automated customer profiling systems face new compliance mandates that favor vendors with pre-certified edge computing architectures.
- China's tier-one city concentration:Alibaba and JD.com operate unmanned convenience stores that normalize frictionless checkout expectations among urban consumers.
Market Restraints
- Semiconductor supply concentration:East Asian foundries dominate edge-AI chip fabrication, creating single-source vulnerability for retail endpoint hardware.
- GDPR cross-border data constraints:Behavioral data flows face national border restrictions that complicate centralized platform architectures for multinational retailers.
- Biometric analytics regulatory friction:FDA guidelines on consumer data privacy in biometric retail analytics delay product launches for US-targeting vendors.
Strategic Opportunities
- India's organized retail expansion:FDI policy liberalization in multi-brand retail creates first-mover advantage for self-checkout system providers.
- Cloud-to-edge infrastructure convergence:Hybrid processing models enable latency-sensitive applications previously restricted to fully local deployments.
- SAMR algorithmic transparency rules:China's mandate for recommendation engine disclosure creates compliance service revenue streams for analytics vendors.
Industry Challenges
- Legacy POS integration complexity:AI-enabled terminal replacements require middleware development for ERP system compatibility.
- Edge computing talent scarcity:Embedded systems engineers with retail domain expertise command premium compensation in competitive labor markets.
- CSRD sustainability reporting timelines:EU corporate sustainability disclosure requirements compress vendor certification cycles for hardware procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Retail Systems Market |
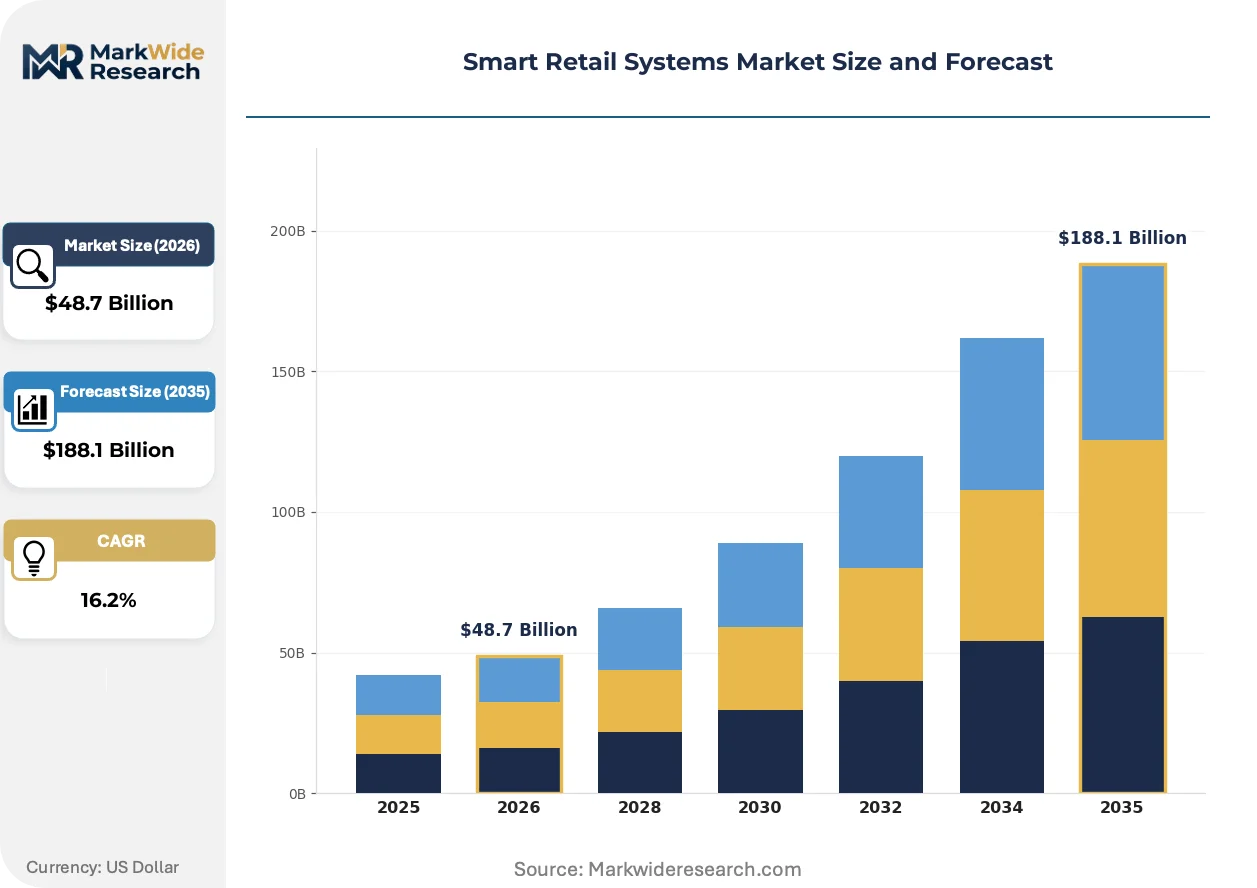
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $188.1 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point of Sale, Digital Signage, Electronic Shelf Labels, Inventory Management Customer Type: Small Businesses, Large Enterprises, E-commerce Platforms, Brick-and-Mortar Technology: Artificial Intelligence, Cloud Computing, Big Data Analytics, RFID Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Amazon.com, IBM, Intel Corporation, Cisco Systems, Google LLC, Microsoft, NVIDIA Corporation, Samsung Electronics, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Retail Systems Market Strategic Shifts
Frictionless checkout architectures are forcing consolidation among sensor fusion vendors while regulatory fragmentation across major economies complicates platform standardization efforts.
Computer vision-based shelf monitoring is unifying inventory tracking with loss prevention in single hardware deployments. Mid-size grocery chains in South Korea adopt these systems faster than big-box retailers due to simpler store layouts. The technology is unifying previously separate capital budgets for security and supply chain management.
REACH substance restrictions on electronic components are forcing reformulation of shelf label batteries and display materials. Vendors serving European supermarket chains now pre-certify hardware against RoHS and CE marking requirements before product launch. Electronic Shelf Label manufacturers face the steepest compliance cost increases due to miniaturization constraints.
Buyer consolidation among supermarket chains is concentrating procurement power and extending replacement cycle timelines. Independent hardware vendors lose share to platform-integrated suppliers offering bundled software subscriptions. Germany's Edeka and Rewe buying cooperatives demonstrate this pattern most visibly in Western Europe.
Smart Retail Systems Market Segmentation
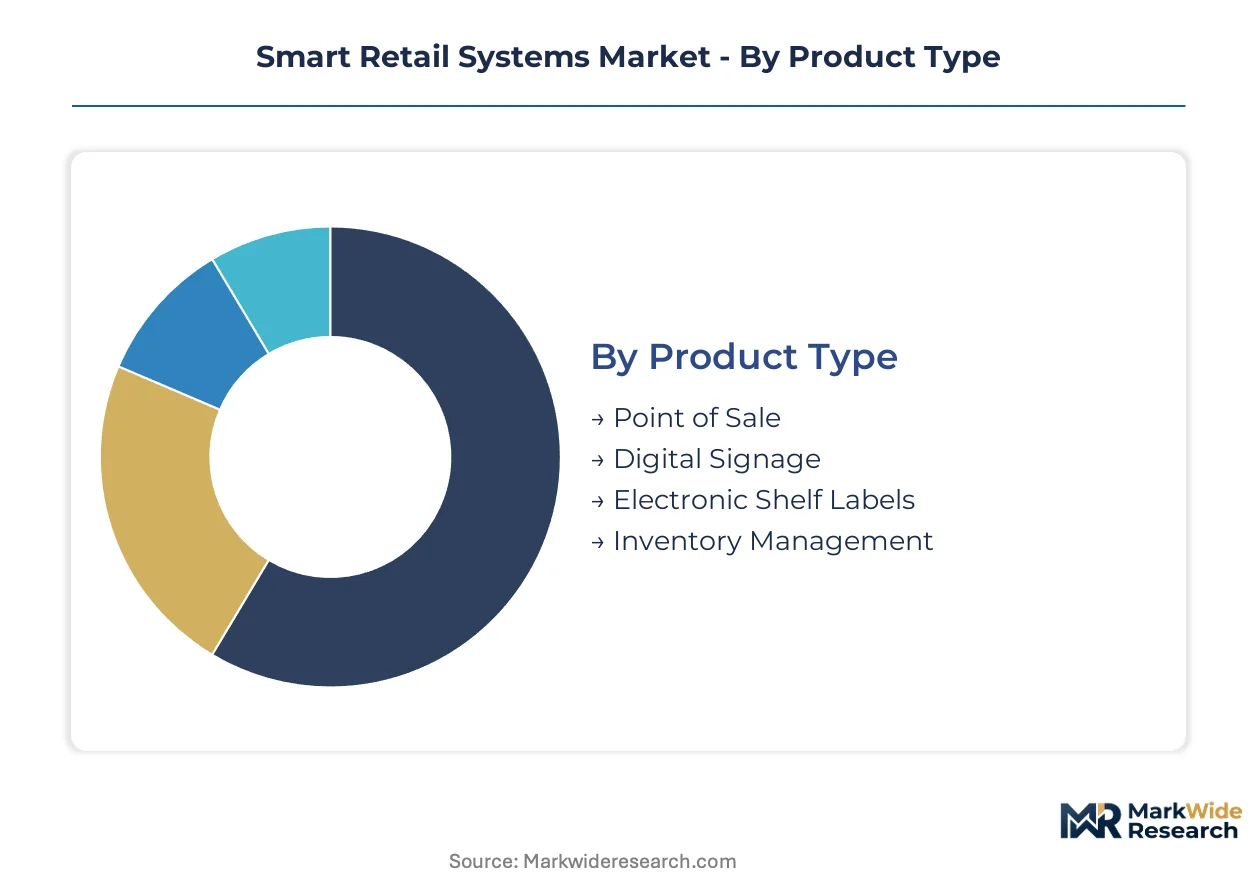
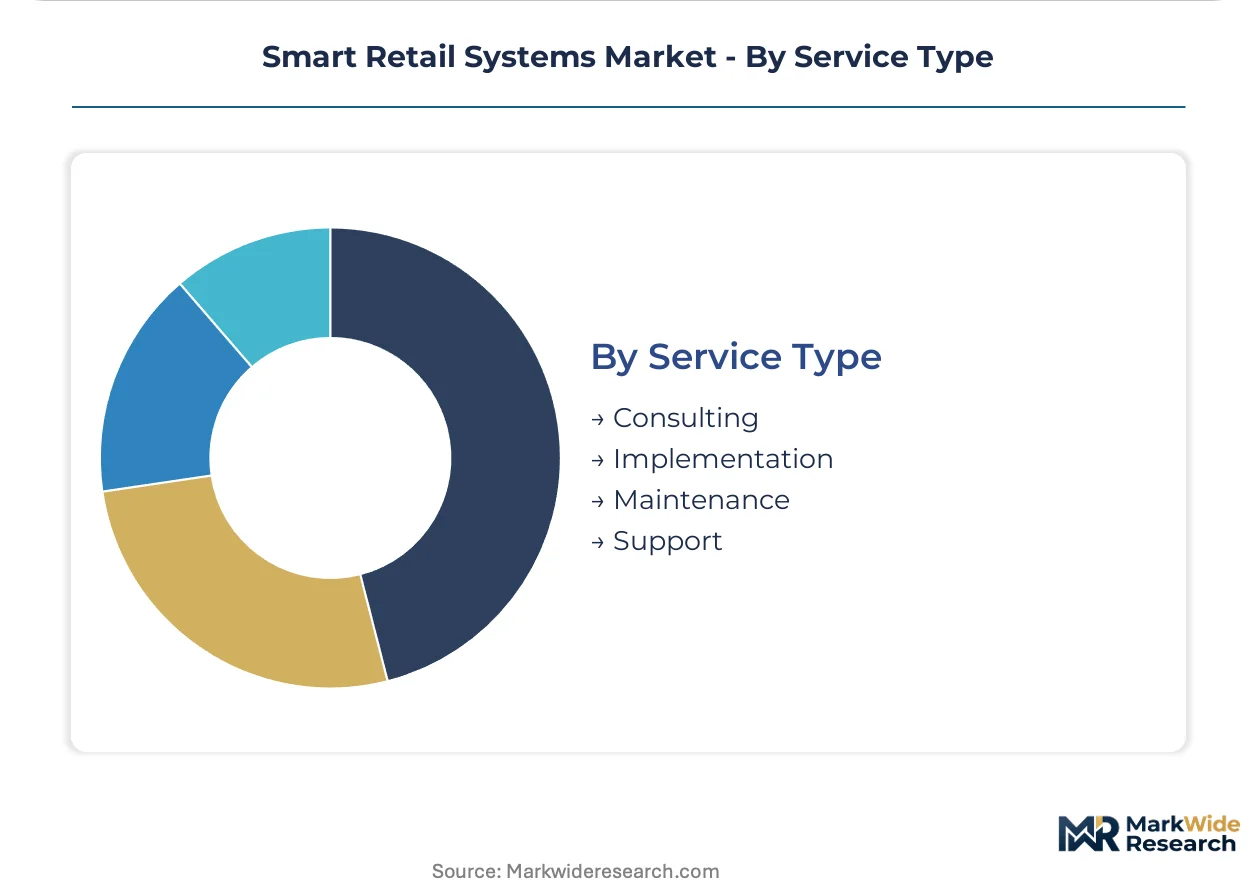
Smart retail systems fragment across four distinct taxonomies that shape procurement patterns and vendor positioning. Product type determines hardware refresh cycles. Customer type dictates solution complexity and integration requirements. Technology selection governs latency performance and regulatory exposure. Service type influences recurring revenue stability for platform providers.
Product Type:
Standardization dominates at the infrastructure layer while customization concentrates at the customer-facing edge of this category.
- Point of Sale:AI-enabled terminals with integrated payment processing and biometric authentication capabilities. Large supermarket chains in Germany deploy these under EGD-aligned sustainability audits that compress replacement timelines. Hardware refresh demand concentrates where legacy ERP integration complexity has delayed prior upgrades.
- Electronic Shelf Labels:E-ink and LCD displays enabling real-time price adjustments through centralized content management systems. Dynamic pricing spreads from grocery to electronics retail across European chains facing REACH substance restrictions on battery and display materials. Miniaturization constraints amplify compliance cost burdens for this hardware category.
- Digital Signage:Networked displays for promotional content and wayfinding in retail environments.
- Inventory Management:Sensor networks and computer vision systems for stock-level monitoring and automated replenishment triggers.
Leading the category by volume: Point of Sale. Expanding most quickly: Electronic Shelf Labels.
Customer Type:
Enterprise scale drives platform standardization while small-business adoption favors modular, service-wrapped deployments.
- Large Enterprises:Multi-store operators requiring centralized analytics dashboards and cross-border data governance frameworks. These buyers concentrate procurement power through buying cooperatives like Germany's Edeka and Rewe, extending replacement cycles and favoring bundled software subscriptions over independent hardware vendors.
- E-commerce Platforms:Online-first retailers operating hybrid fulfillment networks with unmanned store pilots. Alibaba and JD.com in China's tier-one cities normalize frictionless checkout expectations that reshape physical retail technology roadmaps.
- Small Businesses:Independent retailers with limited IT staff and constrained capital budgets.
- Brick-and-Mortar:Traditional retail operators without significant e-commerce integration.
Dominating procurement value: Large Enterprises. Gaining share fastest: E-commerce Platforms.
Technology:
Cloud architectures deliver economies of scale while edge-local processing commands premium positioning for latency-sensitive applications.
- Artificial Intelligence:Machine learning models for demand forecasting, customer behavior analytics, and automated checkout. Edge AI inference at store level compresses response times below 100 milliseconds for real-time inventory tracking. EU AI Act risk-classification requirements favor vendors with pre-certified edge computing architectures for automated customer profiling.
- Cloud Computing:Centralized data processing and software-as-a-service delivery models. Amazon.com leverages cloud-to-edge infrastructure to sustain dominance in frictionless checkout systems. Most new deployments rely on cloud underpinnings despite growing edge-local processing share.
- Big Data Analytics:Aggregation and visualization of transaction patterns across store networks and digital channels.
- RFID:Radio-frequency identification for item-level tracking and automated inventory reconciliation.
Widest deployment base: Cloud Computing. Steepest capability expansion: Artificial Intelligence.
Service Type:
Implementation and consulting command project-based pricing while maintenance and support generate recurring revenue streams with higher margin stability.
- Implementation:System integration, hardware installation, and software configuration services. Legacy POS integration complexity requires middleware development for ERP compatibility, extending project timelines and inflating service margins. Talent scarcity for embedded systems engineers with retail domain expertise amplifies cost pressure.
- Maintenance:Ongoing hardware servicing, software updates, and uptime guarantees. CSRD sustainability reporting timelines compress vendor certification cycles for hardware procurement, increasing documentation burdens for maintenance providers serving European retail chains.
- Consulting:Strategic advisory on technology selection, regulatory compliance, and operational transformation.
- Support:Help desk, troubleshooting, and user training services.
Highest revenue concentration: Implementation. Most margin-stable trajectory: Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in East Asia anchors hardware supply for retail endpoint deployments, while software development clusters in North America and Europe shape platform architectures. Demand concentrates where urban retail density intersects with regulatory frameworks favoring automation.
United States
Big-box retailers and grocery chains drive self-checkout hardware refreshes as labor costs rise in metropolitan markets. FDA guidelines on biometric data privacy constrain facial recognition deployments in customer analytics, forcing vendors toward edge-local processing architectures. The San Francisco Bay Area hosts development centers for frictionless checkout platforms serving national retail networks.
Germany
Supermarket buying cooperatives concentrate procurement power for electronic shelf labels and AI-enabled POS terminals. EGD-aligned sustainability audits compress hardware replacement timelines under CSRD reporting obligations. The Rhine-Ruhr industrial corridor anchors manufacturing partnerships for shelf-edge camera systems serving Edeka and Rewe cooperative members.
China
Alibaba and JD.com operate unmanned convenience stores in Shanghai and Beijing that normalize frictionless checkout expectations. SAMR enforces algorithmic transparency rules for recommendation engines, creating compliance service demand. The Yangtze River Delta cluster concentrates edge-AI chip fabrication capacity for retail endpoint hardware.
South Korea
Mid-size grocery chains adopt computer vision shelf monitoring faster than big-box retailers due to simpler store layouts. MFDS data governance standards influence biometric analytics deployment in retail environments. Seoul Capital Area retailers integrate inventory tracking with loss prevention in single hardware deployments.
India
Organized retail expansion accelerates self-checkout adoption as FDI policy liberalization attracts foreign multi-brand operators. BIS certification requirements for electronic point-of-sale equipment extend vendor qualification timelines. Maharashtra and Karnataka host pilot deployments for cloud-to-edge retail infrastructure serving urban convenience store networks.
Smart Retail Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized edge-AI silicon and vertical software stacks. The vendor base stratifies across cloud infrastructure providers, semiconductor fabricators, and point-of-sale hardware specialists. Three archetypes dominate: hyperscale platform operators with cloud-to-edge integration, chip vendors supplying low-power inference processors, and retail-focused system integrators with ERP middleware capabilities. Competitive moves concentrate on strategic partnerships between silicon and software layers, plus geographic expansion through local system integrator networks.
Within the hyperscale platform tier, Amazon.com exemplifies cloud-to-edge infrastructure convergence for frictionless checkout systems. Among semiconductor specialists, Intel Corporation and NVIDIA Corporation anchor opposing architectural approaches—low-power inference at the edge versus GPU-accelerated analytics platforms. These three entities represent distinct competitive vectors: integrated retail service delivery, power-efficient silicon design, and compute-intensive behavioral analytics.
| Leading Market Players |
|---|
| Amazon.com |
| IBM |
| Intel Corporation |
| Cisco Systems |
| Google LLC |
| Microsoft |
| NVIDIA Corporation |
| Samsung Electronics |
| Huawei Technologies |
| Others |
Value Chain & Pricing Dynamics
Edge-AI chip fabrication migration to advanced process nodes simultaneously compresses per-unit inference costs and concentrates supply leverage among East Asian foundry operators serving retail endpoint manufacturers.
Pricing Analysis
Warranty and software maintenance bundling separates premium-tier POS vendors from hardware-only suppliers competing on upfront unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU AI Act and FDA biometric guidelines. Cost compression in mid-tier electronic shelf labels intensifies as REACH compliance adds battery reformulation expenses. Small-business retailers exhibit highest price sensitivity, while large enterprise cooperatives prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Edge-AI processor supply rests on Taiwanese and South Korean semiconductor foundries with advanced node capacity. Silicon wafer fabrication draws from Japanese specialty chemical producers for photoresist and high-purity gases. Single-source vulnerability concentrates in EUV lithography equipment. Distribution runs through regional system integrator networks anchored in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computer vision-based shelf monitoring is displacing legacy barcode-scanning inventory systems, compressing replacement cycles for mid-size grocery operators seeking unified loss-prevention architectures.
For Market Incumbents: To counter cloud-to-edge platform consolidation by hyperscale operators, anchor defensive positioning through backward integration into edge-AI silicon design partnerships and pre-certification investments under EU AI Act risk-classification frameworks. Prioritize middleware development capabilities that resolve legacy ERP integration complexity for large supermarket cooperatives. For New Entrants and Emerging Players: Direct-to-retailer digital channels bypass incumbent distributor markups in India's organized retail expansion corridor. White-space concentration sits with self-checkout hardware for tier-two city convenience store networks. Partner with local system integrators possessing BIS certification expertise to compress vendor qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical software stack acquisitions by semiconductor vendors seeking retail domain expertise. Long-term viability favors targets with pre-certified edge computing architectures and recurring maintenance revenue streams. Watch SAMR algorithmic transparency enforcement intensity as inflection signal for compliance-service revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-to-edge convergence enables sub-100-millisecond response times for frictionless checkout systems. |
| Acquisition of Specialist Firm | Sensor fusion vendors consolidate as computer vision unifies inventory tracking with loss prevention. |
| Strategic Partnership | Silicon-software layer alliances accelerate pre-certification under EU AI Act risk-classification requirements. |
| Geographic Expansion | Local system integrator networks in India bypass FDI policy friction for multi-brand retail entrants. |
| Product Launch | Dynamic pricing ESL hardware spreads from grocery to electronics retail under REACH substance compliance. |
Study Parameters
Independent corroboration across CTOs at large supermarket chains, procurement leads at buying cooperatives, edge-AI platform engineers, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from SEC filings of cloud infrastructure providers, hyperscaler capex disclosures, EU AI Act implementation guidance, and SAMR algorithmic transparency directives. Bottom-up and top-down triangulation reconciles vendor shipment data with retailer deployment timelines.
Comparable-period anchoring to historical POS replacement cycles and electronic shelf label adoption curves shapes the projection horizon across the analysis window. Segmentation dimensions modeled include product type, customer scale tier, deployment architecture, and regional regulatory cluster. CAGRs derive from installed base growth rates adjusted for hardware refresh compression under sustainability reporting timelines. Forecast inputs incorporate edge-AI chip foundry capacity expansion and CSRD certification cycle impacts.
The model holds under stable semiconductor supply conditions and sustained FDI liberalization in organized retail; deviation in East Asian foundry utilization rates or sudden biometric data privacy enforcement shifts would revise trajectory. A small set of named triggers warrants ongoing watch: EU AI Act enforcement intensity, SAMR algorithmic transparency rule expansion, and REACH substance restriction scope creep.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Smart Shopping Cart Market
Retail Technology
Cash Register Machines Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Ticket Machine Market
Retail Technology
Global Kiosk Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Smart Shelves Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
North America Automation in Retail Market