
 US Retail Recon Software Market | 2026-2036
US Retail Recon Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Retail Recon Software Market Insights
Enterprise-grade audit accuracy is collapsing the tolerance gap between manual and automated reconciliation processes. BlackLine, Inc. leverages cloud-native architecture to anchor mid-market retail chains seeking real-time financial close capabilities. Oracle Corporation dominates enterprise deployments with embedded ERP connectivity, while ReconArt, Inc. specializes in configurable workflow engines for multi-location operators.
Retail recon software automates transaction matching, exception identification, and ledger synchronization across point-of-sale, inventory, and payment systems, typically processing millions of daily records with sub-second matching latency against configurable tolerance rules. The primary commercial purpose is elimination of manual spreadsheet reconciliation that consumes finance team capacity and introduces material misstatement risk. Cloud-Based deployment leads segment expansion as retailers prioritize elastic compute for seasonal volume spikes, while AI-Powered technology is displacing rule-based matching engines with probabilistic models that adapt to novel discrepancy patterns without explicit programming. Inventory Management product modules capture disproportionate margin pools by integrating RFID Integration feeds for perpetual physical-digital alignment.
NIST cybersecurity frameworks and PCI-DSS payment card standards shape product roadmaps by mandating encrypted audit trails and access segregation that recon platforms must embed natively. State-level consumer protection statutes in New York and Illinois add jurisdiction-specific disclosure requirements that vendors navigate through configurable compliance templates. Stakeholders must monitor how FedNow instant payment adoption alters settlement timing assumptions built into existing reconciliation engines.
Market Dynamics
FTC intensification of retail payment accuracy enforcement is compressing upgrade cycles for reconciliation platforms, forcing finance teams to abandon manual spreadsheet processes before audit exposure materializes.
Growth Catalysts
- FedNow instant payment adoption:Real-time settlement rails demand sub-second reconciliation engines that legacy batch systems cannot deliver, compelling infrastructure replacement across mid-market retail chains.
- California retail corridor concentration:Los Angeles and San Francisco metro areas host dense specialty store networks where multi-location operators require automated exception handling for high-volume transaction throughput.
- PCI-DSS 4.0 encryption mandates:Payment card industry standards now require encrypted audit trails with access segregation, driving native compliance embedding in recon software roadmaps.
Market Restraints
- Cloud infrastructure cost volatility:Elastic compute pricing for seasonal retail volume spikes creates unpredictable operating expenditure exposure that CFOs struggle to forecast.
- AI talent scarcity:Probabilistic matching engine development requires machine learning engineers with financial services domain expertise, a skill set concentrated in fintech hubs with wage premiums.
- Legacy ERP integration friction:Oracle and SAP incumbent systems impose proprietary data formats that extend implementation timelines and require expensive middleware development.
Strategic Opportunities
- RFID-integrated inventory modules:Perpetual physical-digital alignment through radio-frequency identification feeds captures margin pools in apparel and electronics verticals where shrinkage erodes profitability.
- Illinois consumer protection templates:Configurable compliance engines addressing state-level disclosure requirements create differentiation against one-size-fits-all competitors.
- AI-rule hybrid architectures:Convergence of probabilistic models with explicit tolerance rules enables adaptive discrepancy detection without sacrificing audit explainability demanded by SEC registrants.
Industry Challenges
- Financial controller skill gaps:Automated reconciliation deployment requires staff proficient in exception workflow configuration and tolerance rule optimization, competencies absent from traditional accounting curricula.
- NIST framework implementation timelines:Cybersecurity audit trail requirements demand 12-18 month compliance sprints that delay product releases and strain engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Retail Recon Software Market |
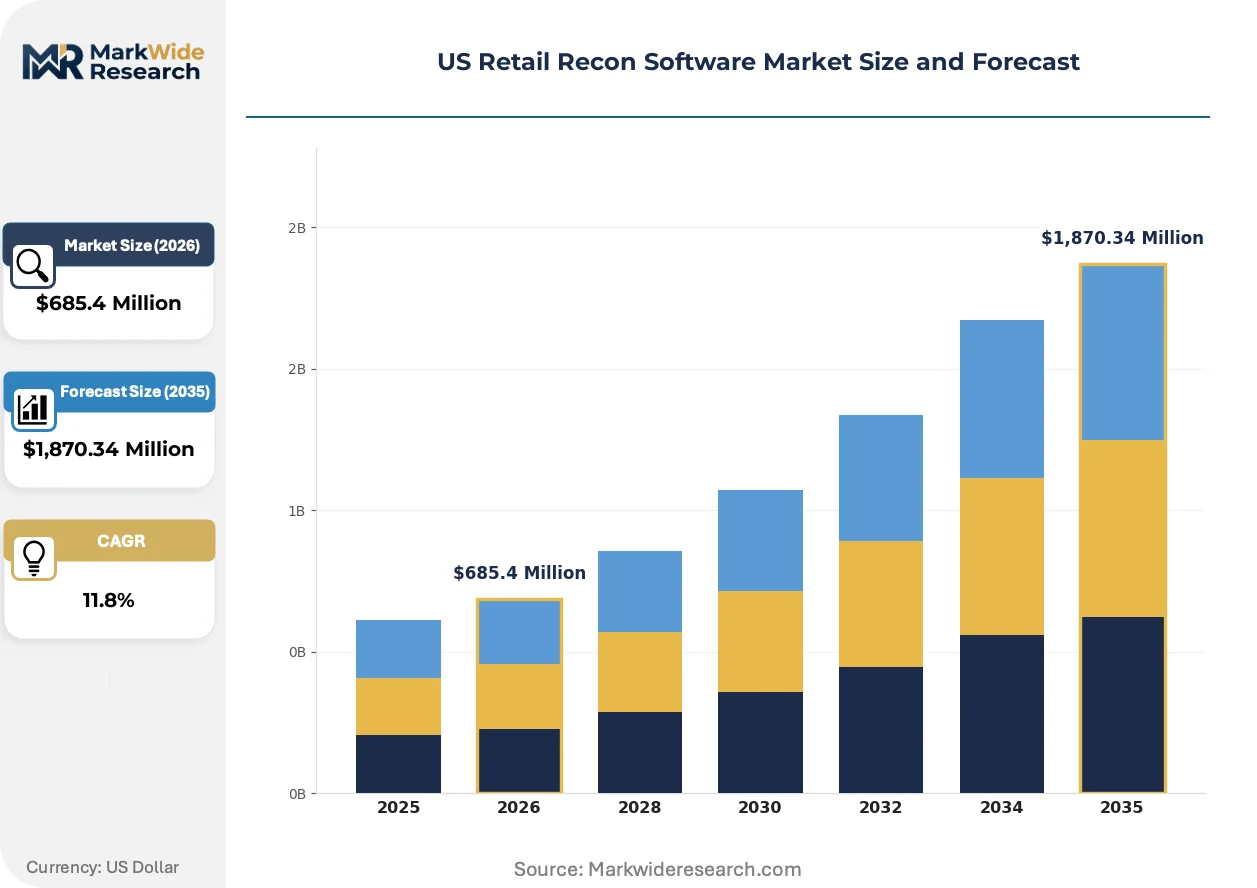
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,870.34 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audit Solutions, Inventory Management, Price Checking, Compliance Tracking Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Applications End User: Retail Chains, Supermarkets, E-Commerce Platforms, Specialty Stores Technology: AI-Powered, Machine Learning, Data Analytics, RFID Integration |
| Companies Covered | ReconArt, Inc., Broadridge Financial Solutions, Inc., BlackLine, Inc., Oracle Corporation, SAP SE, Fiserv, Inc., Baldwin Hackett & Meeks, Inc., SigmaIQ, AutoRek, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Retail Recon Software Market Trends and Innovations
Machine learning inference at the transaction matching layer is compressing the latency window for discrepancy detection while expanding the complexity of patterns that automated systems can resolve without human intervention.
Probabilistic AI matching is decomposing rule-based reconciliation engines by adapting to novel discrepancy patterns without explicit programming. Specialty retailers in California's dense corridor are deploying these systems for real-time financial close during seasonal volume spikes. The structural consequence is collapsing tolerance gaps between manual and automated processes, eliminating finance team capacity constraints.
FTC intensifying scrutiny of retail payment accuracy is mandating software upgrades that embed encrypted audit trails natively. This regulatory pressure forces reconciliation vendors to prioritize PCI-DSS compliance over feature expansion. Enterprise retail chains are responding by accelerating procurement cycles for cloud-native platforms with pre-certified security architectures.
Buying committees are consolidating vendor selection authority within CFO organizations, displacing decentralized IT procurement that previously prioritized technical specifications over audit risk reduction. Mid-market retail chains now demand outcome-based pricing tied to exception reduction metrics rather than seat-based licensing. This shift is most visible in New York and Illinois where state consumer protection statutes elevate compliance officer influence in software decisions.
US Retail Recon Software Market Segmentation
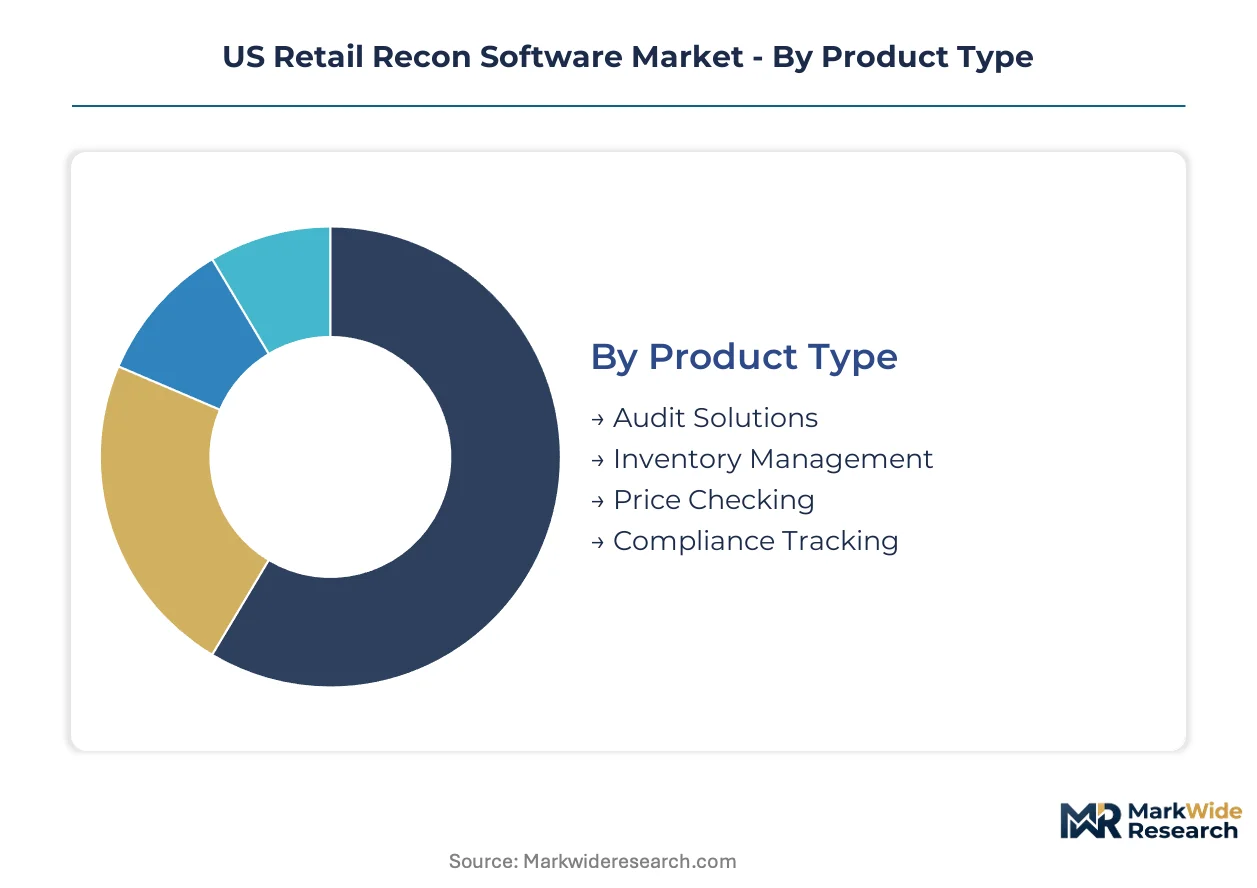
Retail reconciliation software segments reflect divergent technical requirements across transaction velocity, regulatory exposure, and physical-digital integration depth. Understanding these divisions clarifies where procurement budgets concentrate and which capability gaps create competitive vulnerability.
Product Type:
Domestic demand clusters in audit-intensive categories serving California and New York retail corridors, while inventory modules draw export-linked specialty retailers managing cross-border SKU complexity.
- Audit Solutions:Automated transaction matching engines with configurable tolerance rules process millions of daily records for financial close acceleration. Demand concentrates among Los Angeles and San Francisco metro retail chains where FTC payment accuracy scrutiny compresses upgrade cycles.
- Inventory Management:Perpetual physical-digital alignment systems integrating RFID feeds for shrinkage reduction in apparel and electronics verticals. Specialty stores across California's dense corridor deploy these for real-time stock visibility during seasonal volume spikes.
- Price Checking:Point-of-sale discrepancy detection modules ensuring promotional pricing execution accuracy.
- Compliance Tracking:Configurable workflow engines addressing Illinois and New York state-level consumer protection disclosure requirements.
Audit Solutions commands the established base. The steepest expansion runs through Inventory Management.
Deployment:
Cost tier stratification separates enterprise capital expenditure commitments from mid-market operating expenditure preferences, with hybrid architectures capturing margin-sensitive operators.
- Cloud-Based:Elastic compute architectures enabling seasonal volume scaling without infrastructure ownership. Mid-market retail chains prioritize this model for unpredictable transaction throughput patterns.
- Hybrid:Split processing sensitive audit data on-premise while pushing analytics to cloud environments. Multi-location operators in PCI-DSS regulated environments favor this for encrypted audit trail compliance.
- On-Premise:Dedicated infrastructure for maximum data sovereignty control.
- Mobile Applications:Field-accessible reconciliation interfaces for distributed store managers.
On-Premise retains legacy installed base. Cloud-Based climbs the fastest as CFOs prioritize forecastable operating expenditure over capital deployment.
End User:
Customer type segmentation tracks organizational complexity, with transaction volume and location dispersion determining feature requirements and implementation timelines.
- Specialty Stores:Focused-format retailers with concentrated SKU ranges requiring rapid exception handling for high-velocity transactions. California's apparel and electronics verticals drive concentrated procurement.
- Retail Chains:National operators with standardized POS infrastructure demanding enterprise-grade ERP connectivity and centralized financial close coordination.
- Supermarkets:High-frequency, low-margin operators with perishable inventory reconciliation needs.
- E-Commerce Platforms:Digital-native retailers with multi-channel payment reconciliation complexity.
Retail Chains commands the established base. Specialty Stores gain share fastest as FTC enforcement elevates audit accuracy requirements.
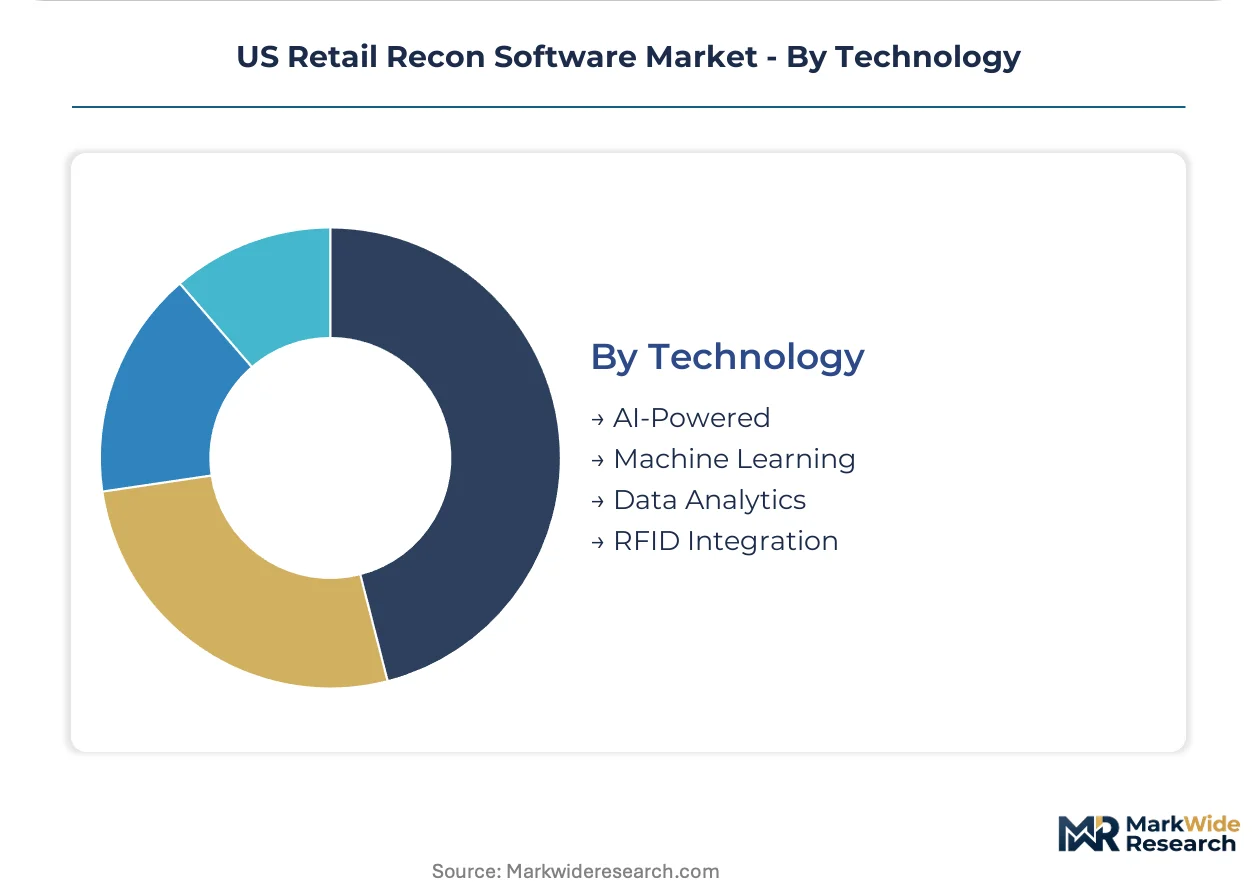
Technology:
Maturity differentiation separates probabilistic AI systems from deterministic rule engines, with adoption velocity varying by internal technical capability and regulatory explainability demands.
- AI-Powered:Probabilistic matching engines adapting to novel discrepancy patterns without explicit programming. SEC registrants demand these for adaptive detection combined with audit explainability.
- RFID Integration:Radio-frequency identification feeds enabling perpetual inventory alignment between physical stock and digital ledgers. Apparel verticals deploy this for shrinkage reduction.
- Machine Learning:Supervised pattern recognition for historical anomaly detection.
- Data Analytics:Descriptive and diagnostic reconciliation reporting for controller visibility.
Data Analytics commands the established base. AI-Powered expands most quickly as talent scarcity constraints ease through vendor-managed model deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in retail recon software remain domestically weighted, with US vendors serving concentrated demand clusters while importing specialized talent from fintech hubs. Trade flows center on intellectual property licensing rather than physical goods, creating distinctive regional specialization patterns across state-level markets.
California
Los Angeles and San Francisco metro areas anchor the densest specialty store networks demanding real-time exception handling. The California Consumer Privacy Act shapes vendor data residency requirements for audit trail storage. Apparel and electronics verticals in these corridors deploy RFID-integrated inventory modules for shrinkage reduction during seasonal volume spikes.
New York
State-level consumer protection statutes elevate compliance officer influence in software procurement decisions. The New York Department of Financial Services imposes disclosure requirements that vendors address through configurable workflow templates. Manhattan-based retail chains prioritize outcome-based pricing tied to exception reduction metrics over traditional seat-based licensing.
Illinois
Chicago-area multi-location operators drive demand for hybrid deployment architectures splitting sensitive audit data on-premise from cloud analytics. State consumer protection laws mandate jurisdiction-specific disclosure protocols. The metro's logistics-intensive retail sector requires perpetual inventory alignment systems for high-velocity SKU management.
Texas
Dallas-Fort Worth retail chains seek elastic compute architectures for unpredictable transaction throughput patterns. State tax audit intensity compresses financial close timelines, accelerating automated reconciliation adoption. The region's energy sector crossover creates demand for controllers proficient in exception workflow configuration.
Massachusetts
Greater Boston's fintech talent concentration supports probabilistic matching engine development for SEC registrants demanding audit explainability. State-level data governance frameworks influence encrypted audit trail specifications. Cambridge-area technology retailers deploy AI-rule hybrid architectures for adaptive discrepancy detection.
US Retail Recon Software Market Competitive Landscape
Concentration sits with enterprise software incumbents embedding reconciliation within broader ERP suites, while specialized vendors capture mid-market share through configurable workflow differentiation. The vendor landscape stratifies across three tiers: cloud-native specialists, legacy ERP extenders, and vertical-specific boutiques. Dominant competitive moves include strategic partnerships with payment processors and portfolio diversification into adjacent compliance automation.
Within the cloud-native specialist tier, BlackLine, Inc. and ReconArt, Inc. exemplify contrasting architectural approaches—BlackLine anchors mid-market retail chains seeking real-time financial close capabilities through native cloud deployment, while ReconArt occupies a position serving multi-location operators with configurable workflow engines. Oracle Corporation represents the enterprise ERP extender archetype, leveraging embedded connectivity to dominate large-chain deployments where system consolidation outweighs best-of-breed functionality.
| Leading Market Players |
|---|
| ReconArt, Inc. |
| Broadridge Financial Solutions, Inc. |
| BlackLine, Inc. |
| Oracle Corporation |
| SAP SE |
| Fiserv, Inc. |
| Baldwin Hackett & Meeks, Inc. |
| SigmaIQ |
| AutoRek |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation timelines for cloud-native reconciliation platforms concentrate vendor pricing power with enterprise incumbents while compressing margins for mid-market specialists competing on speed-to-value. This lead-time differential shapes how procurement committees weight total cost of ownership against audit risk exposure.
Pricing Analysis
Mid-market retail chains anchor pricing structures around outcome-based contracts tied to exception reduction metrics rather than traditional seat-based licensing. Three-tier pricing stratifies across enterprise-grade ERP-embedded suites, configurable cloud-native platforms, and vertical-specific boutiques with RFID integration modules. Pricing pressure stems from CFO demands for forecastable operating expenditure over capital deployment, with specialty store networks in California exhibiting highest price sensitivity due to seasonal volume unpredictability.
Supply Chain Analysis
Just-in-time deployment preferences dominate as retailers prioritize elastic compute for seasonal transaction spikes over dedicated infrastructure ownership. Cloud infrastructure provisioning draws from hyperscaler networks concentrated in Virginia, Oregon, and Ohio data center corridors, with AI/ML engineering talent sourcing from Massachusetts and Washington fintech hubs. Single-source vulnerability rests on concentrated hyperscaler dependency, while distribution runs through direct vendor-to-enterprise sales channels supplemented by systems integrator partnerships for legacy ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buying committee consolidation within CFO organizations has shifted procurement leverage toward finance teams prioritizing audit risk reduction over technical specifications, fragmenting vendor influence previously concentrated with decentralized IT procurement.
For Market Incumbents: Fortify embedded ERP connectivity advantages through accelerated PCI-DSS 4.0 certification timelines that cloud-native challengers cannot match. Deepen vertical integration into RFID hardware partnerships for inventory module differentiation against best-of-breed specialists. This defensive posture counters mid-market entrants exploiting financial controller skill gaps with managed exception workflow services. For New Entrants and Emerging Players: SOC 2 Type II fast-track certification opens procurement doors at Illinois and New York multi-location operators where compliance officer influence exceeds IT technical evaluation. Target specialty store networks in California's Los Angeles-San Francisco corridor with pre-configured seasonal scaling architectures. Lead generation through outcome-based pilot programs demonstrating exception reduction within thirty-day proof-of-concept windows. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy ERP vendors divesting non-core reconciliation modules to focus on core database and application layers. Long-term viability hinges on AI-rule hybrid architecture development capabilities serving SEC registrants demanding both adaptive detection and audit explainability. Monitor FedNow instant payment adoption velocity as inflection indicator for infrastructure replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Rule Hybrid Architecture Development | Enables adaptive discrepancy detection for SEC registrants requiring audit explainability. |
| RFID Hardware Partnership Integration | Captures apparel and electronics shrinkage reduction budgets through perpetual inventory alignment. |
| PCI-DSS 4.0 Pre-Certification Acceleration | Compresses procurement cycles for FTC-scrutinized retail chains abandoning manual reconciliation. |
| Outcome-Based Pricing Model Deployment | Aligns vendor compensation with CFO-prioritized exception reduction metrics over seat counts. |
| FedNow Real-Time Settlement Engine Adaptation | Positions platforms for sub-second reconciliation demands legacy batch systems cannot satisfy. |
Research Methodology
Cross-validation between primary interviews with CFOs, financial controllers, and compliance officers and secondary validation through SEC 10-K filings, FTC enforcement action records, and PCI-DSS certification databases anchors the qualitative findings. Bottom-up triangulation aggregates deployment data across California, New York, Illinois, Texas, and Massachusetts retail corridors, while top-down analysis reconciles vendor revenue disclosures against modeled addressable market expansion.
Sensitivity analysis across deployment model, organization size, vertical specialization, and integration complexity dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segmented growth rate reconciliation against historical adoption velocity in audit-intensive regulatory environments. FedNow adoption curves and RFID integration penetration serve as industry-specific forecast inputs modeling infrastructure replacement timing.
Decision-makers should treat outputs as directional under assumptions of continued FTC payment accuracy enforcement intensity and hyperscaler pricing stability; material deviation would warrant model refresh. Revision becomes warranted when FedNow settlement volume crosses thresholds triggering widespread legacy system obsolescence or when AI talent scarcity constraints ease sufficiently to democratize probabilistic matching engine development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Self-Checkout System Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Smart Shelves Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Global Smart Retail Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Self-Service Market
Retail Technology
AR in Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
Global Kiosk Market
Retail Technology
Customer-Facing Technology Market