
 US Self-Checkout Systems Market | 2026-2036
US Self-Checkout Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Self-Checkout Systems Market Intelligence
The shift towards hardware-as-a-service and flexible leasing models is rewriting the competitive landscape for self-checkout systems, enabling smaller retailers to adopt advanced technology without large upfront capital expenditure. NCR Corporation leverages its extensive service network and financing options to secure large retail chain contracts. In contrast, Mashgin specializes in AI-powered, touchless checkout for convenience stores and cafeterias. Toshiba Global Commerce Solutions differentiates through its integrated hardware and software solutions tailored for grocery environments.
US self-checkout systems are automated points of sale that allow customers to scan, pack, and pay for goods without cashier assistance. These systems integrate components like barcode scanners, weight-sensitive bagging areas, and payment terminals compliant with PCI DSS standards. While standalone kiosks remain the dominant product type in supermarkets, integrated solutions using artificial intelligence and RFID technology are experiencing significant uptake. Demand from large retail chains for these advanced systems is driven by the need for better inventory accuracy and loss prevention.
System deployments must comply with the Americans with Disabilities Act (ADA) to ensure accessibility for all users. The Federal Trade Commission (FTC) also scrutinizes data handling practices, particularly for systems using mobile applications or AI-based customer tracking. Navigating these accessibility and data privacy regulations is a critical design constraint for all vendors. The key decision for retailers is balancing the capital investment in new systems against potential labor savings and improved customer throughput.
Market Dynamics
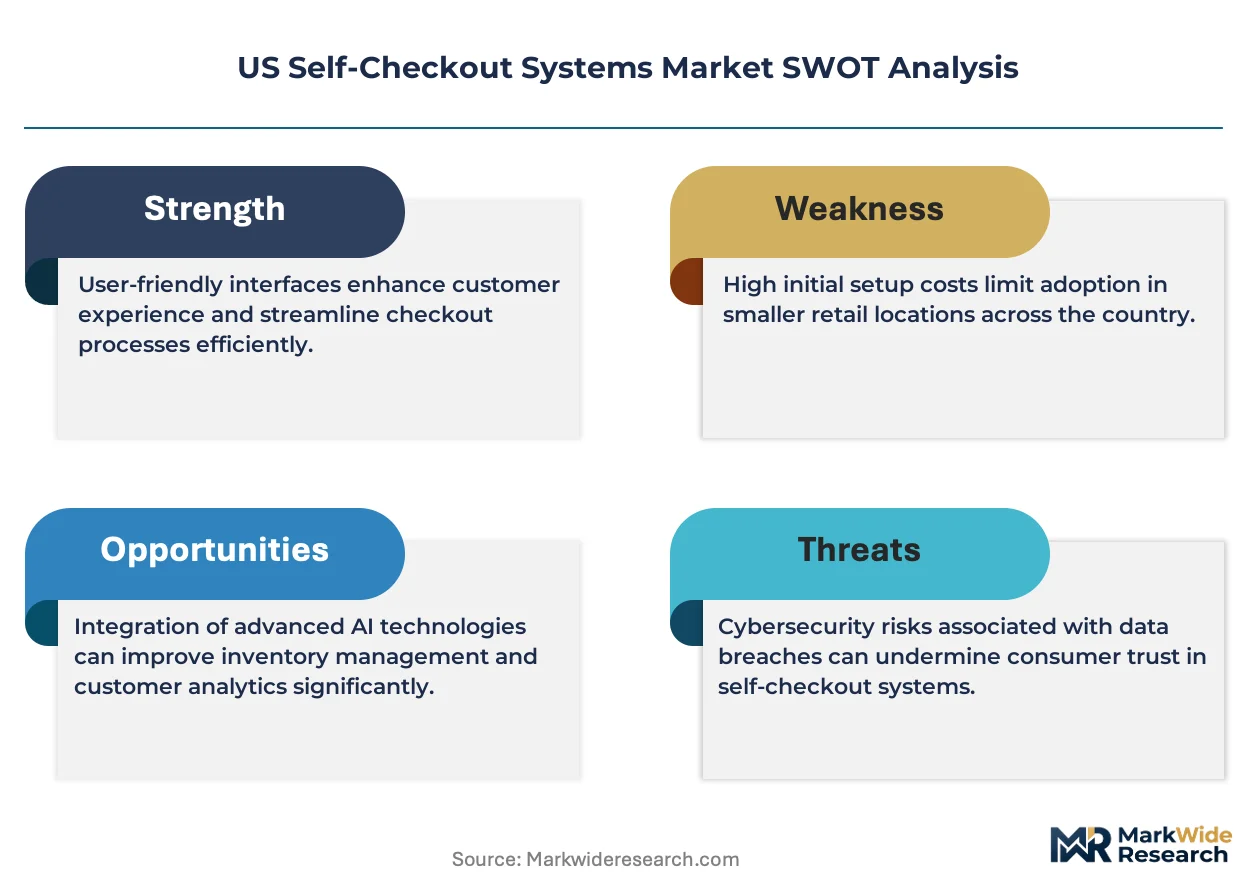
The central dynamic in the US self-checkout market is the tension between reducing high operational labor costs and managing the significant capital expenditure of advanced systems. This is driving a structural shift toward flexible financing and service-based procurement models.
Growth Catalysts
- Artificial Intelligence Integration:The adoption of AI and computer vision for item recognition and loss prevention is a primary catalyst, reducing transaction friction and mitigating theft, which encourages investment by large retail chains.
- Rising Labor Costs:Persistent wage inflation and labor shortages, particularly in states like California and New York, create a strong economic incentive for retailers to automate customer-facing transaction points to control operational expenses.
- Hardware-as-a-Service Models:The availability of leasing and subscription-based models lowers the barrier to entry for small and mid-sized retailers, expanding the addressable market beyond top-tier grocery and big-box stores.
Market Restraints
- High Capital Outlay:The initial investment required for deploying modern self-checkout systems, including hardware, software, and installation, remains a significant barrier for many retailers, particularly independent operators.
- Customer Resistance and Shrinkage:A segment of consumers expresses frustration with system usability, while retailers face challenges with increased theft and operational shrink associated with self-service lanes, which can offset labor savings.
- ADA Compliance Complexity:Designing and deploying systems that fully comply with the Americans with Disabilities Act adds significant cost and engineering complexity, slowing down innovation cycles and rollout schedules.
Strategic Opportunities
- Expansion into New Verticals:There is a substantial opportunity to adapt self-checkout technology for environments beyond traditional retail, including quick-service restaurants, corporate cafeterias, stadiums, and hospitality venues.
- Integrated Mobile Experiences:The convergence of self-checkout kiosks with customers' mobile devices offers a pathway for creating a seamless experience, integrating loyalty programs, personalized offers, and "scan-and-go" functionalities.
- Targeting Mid-Market Retail:Developing scaled-down, cost-effective solutions tailored to the specific needs and budget constraints of mid-sized grocery stores and specialty retailers represents a significant untapped market segment.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complex and often costly process of integrating new self-checkout platforms with retailers' existing point-of-sale, inventory management, and enterprise resource planning systems.
- Data Security and Privacy:Ensuring robust security for payment processing to maintain PCI DSS compliance and addressing FTC scrutiny over the collection and use of customer data from AI-powered systems is a critical challenge.
- Minimizing User Friction:Vendors face the ongoing challenge of improving the user interface and overall experience to reduce the frequency of errors and the need for staff interventions, which directly impacts ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Self-Checkout Systems Market |
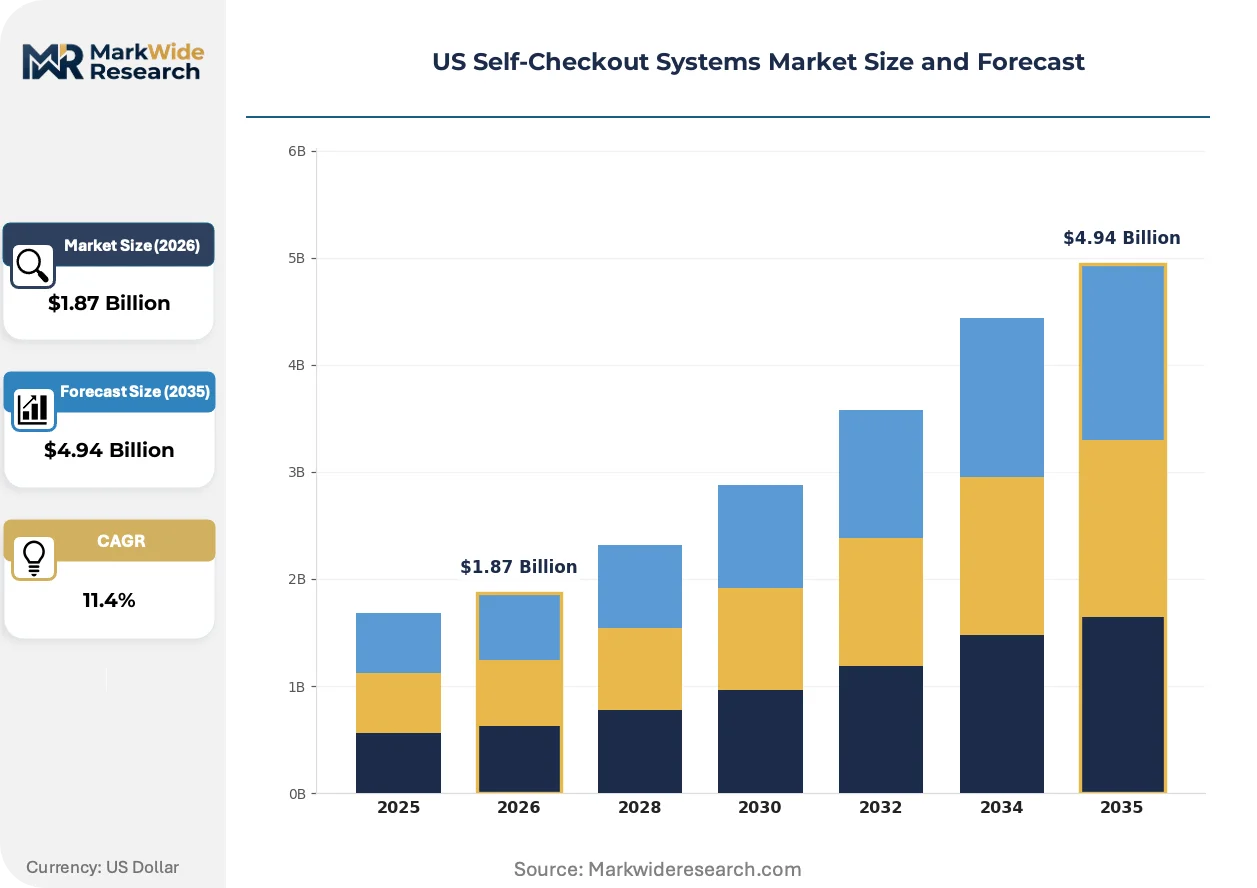
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $4.94 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Kiosks, Interactive Terminals, Mobile Applications, Integrated Solutions Industry Vertical: Retail, Grocery, Hospitality, Entertainment Customer Type: Small Businesses, Large Retail Chains, Supermarkets, Convenience Stores Technology: Barcode Scanning, RFID, Artificial Intelligence, Touchscreen Interfaces |
| Companies Covered | Fujitsu Limited, Mashgin, NCR Corporation, Standard AI, StrongPoint, Diebold Nixdorf, ITAB Shop Concept, ECR Software Corporation, Toshiba Global Commerce Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Self-Checkout Systems Market Strategic Shifts & Innovations
The evolution of self-checkout systems reflects a broader transformation within retail, where the point of sale is becoming an intelligent hub for enhancing operational efficiency and customer data collection. This shift prioritizes speed, security, and a frictionless user experience over simple transaction processing.
Computer vision systems are a key technology enabling the next generation of checkout. These systems use cameras and AI-powered image recognition to identify items without needing a barcode, including fresh produce or prepared foods. Large grocery and convenience store chains are the primary adopters, seeking to accelerate throughput and reduce losses from unscanned items. The self-checkout experience is migrating from a dependency on manual scanning and weight scales to a more fluid, autonomous interaction.
Compliance with the Americans with Disabilities Act (ADA) is a significant regulatory driver influencing system design in the United States. This federal mandate requires that self-service kiosks be accessible to users with disabilities, dictating specifications for height, reach, and alternative input methods like audio guidance. Consequently, retailers must procure ADA-compliant systems to avoid legal challenges, making accessibility a critical feature that vendors must engineer into their hardware from the ground up.
A fundamental shift in procurement patterns is altering the market's financial structure. Retailers are increasingly moving away from outright capital purchases and toward subscription-based hardware-as-a-service (HaaS) contracts that bundle hardware, software, maintenance, and support. This model transfers the burden of technology obsolescence to the vendor and makes advanced systems more accessible. This trend is especially visible among regional grocery chains across the US seeking to modernize without massive upfront investment.
US Self-Checkout Systems Market Segmentation
The US self-checkout systems market requires granular segmentation to understand the diverse needs of retailers and the technological advancements driving adoption. Analyzing these segments reveals where investment is concentrating and which solutions address specific operational challenges within the American retail landscape.
Product Type:
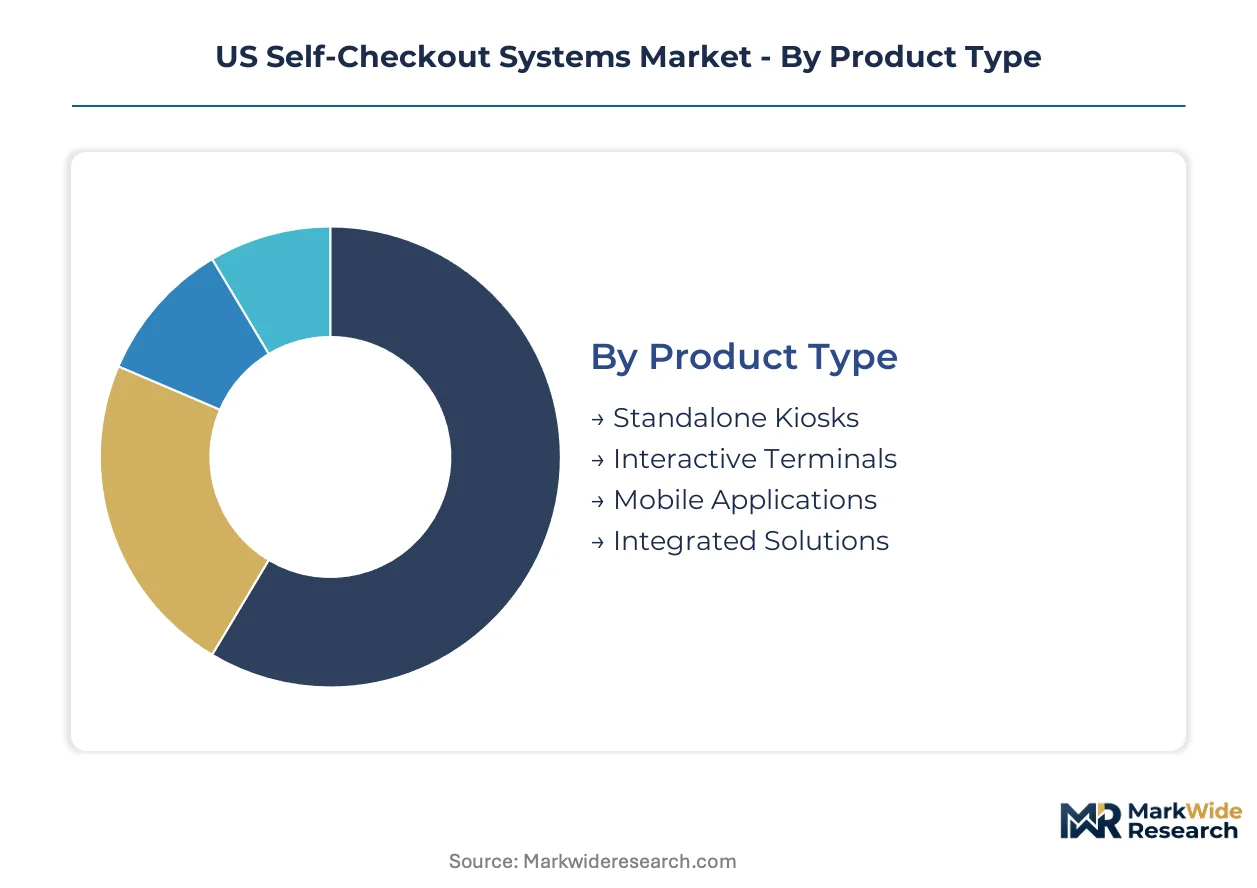
The US self-checkout systems market is segmented across a diverse use-case spectrum, ranging from basic transaction processing to highly integrated customer experiences.
- Standalone Kiosks:These are self-contained units offering basic scan, pack, and pay functionalities, commonly found in supermarkets and big-box stores across the United States. Demand for these systems remains high due to their proven reliability and relatively lower initial deployment costs for broad customer use.
- Interactive Terminals:These systems integrate advanced touchscreen interfaces and sometimes offer guided assistance or personalized promotions during the checkout process. Retailers seek these terminals to enhance customer engagement and streamline complex transactions, particularly in specialty retail environments.
- Mobile Applications:These solutions allow customers to scan items using their smartphones and pay directly through the app, bypassing physical checkout points entirely. Convenience stores and quick-service restaurants in urban centers are exploring mobile apps for rapid, frictionless transactions.
- Integrated Solutions:These comprehensive systems combine hardware, software, and AI-powered analytics for enhanced security, inventory management, and customer data collection. Large retail chains prioritize integrated solutions to improve loss prevention and operational efficiency across their extensive store networks.
The dominant share belongs to Standalone Kiosks, while Integrated Solutions is closing the gap fastest.
Industry Vertical:
Application across various industry verticals defines distinct operational requirements for self-checkout systems.
- Retail:This broad category encompasses general merchandise stores, department stores, and specialty retailers, where self-checkout systems manage diverse product assortments and customer traffic patterns. Retailers implement these systems to reduce labor costs and improve customer throughput during peak shopping periods.
- Grocery:Grocery stores utilize self-checkout for high-volume transactions involving both barcoded and non-barcoded items like produce, requiring robust item recognition and weight-sensing capabilities. Supermarket chains in densely populated US states are heavily investing in these systems to manage staffing challenges.
- Hospitality:Self-checkout technology in hospitality includes kiosks for hotel check-ins, order placement in quick-service restaurants, and ticketing at entertainment venues. These deployments focus on speed and convenience, reducing wait times for guests and customers.
- Entertainment:Entertainment venues like cinemas, theme parks, and sports stadiums deploy self-service kiosks for ticket sales, concession ordering, and merchandise purchases. These systems handle high transaction volumes during specific event windows.
Retail applications continue to command significant volume, with specialized hospitality solutions expanding most quickly.
Customer Type:
Customer type segmentation highlights varying investment capacities and operational scales for self-checkout deployments.
- Small Businesses:These independent operators and local shops typically require cost-effective, easy-to-install self-checkout solutions with minimal maintenance. Their procurement often favors flexible leasing models to avoid large upfront capital outlays.
- Large Retail Chains:National and regional retail chains with extensive store footprints demand scalable, integrated self-checkout systems capable of handling high transaction volumes and complex inventory management. These chains prioritize solutions that offer centralized control and advanced loss prevention features.
- Supermarkets:Grocery store operators, ranging from regional chains to independent grocers, specifically need self-checkout systems that can efficiently process a mix of packaged goods and fresh produce. ADA compliance and robust payment processing are critical for these high-traffic environments.
- Convenience Stores:These smaller retail formats require compact, rapid self-checkout units designed for quick transactions and minimal space. Touchless and AI-powered systems are gaining traction in convenience stores to enhance customer experience.
Large Retail Chains drive substantial procurement, while convenience stores show significant potential for future installations.
Technology:
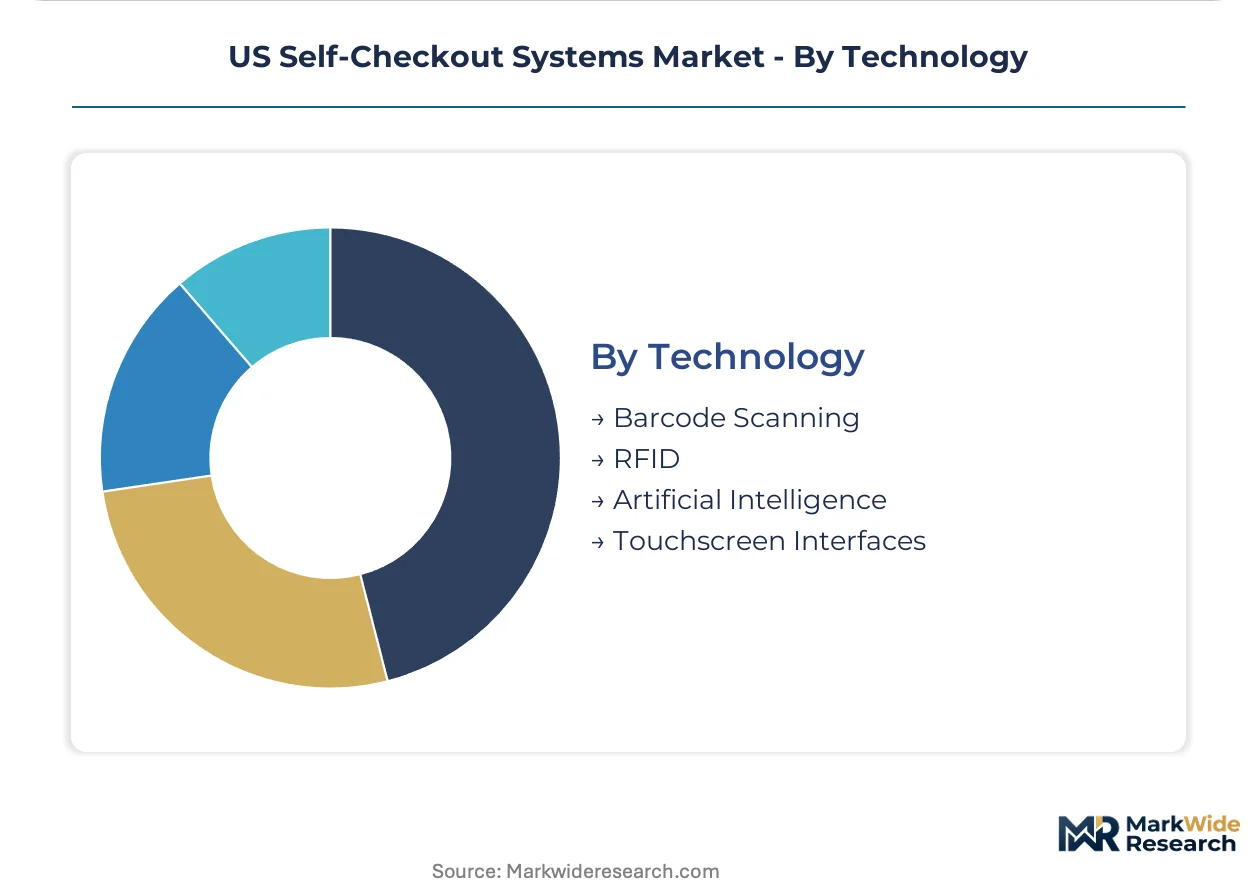
The maturity and sophistication of underlying technology profoundly influence self-checkout system capabilities and adoption rates.
- Barcode Scanning:This foundational technology uses optical readers to identify products via their universal product codes, forming the basis for most traditional self-checkout systems. Barcode scanning remains a cost-effective and widely adopted method for transaction processing in US retail environments.
- RFID:Radio-Frequency Identification technology enables rapid scanning of multiple items simultaneously without direct line-of-sight, significantly accelerating the checkout process. Retailers are exploring RFID for high-value goods and inventory accuracy improvements, particularly in apparel and electronics.
- Artificial Intelligence:AI, including computer vision and machine learning, powers advanced features like item recognition without barcodes, fraud detection, and personalized customer interactions. Large retail chains are investing in AI to mitigate shrinkage and enhance the overall efficiency of self-service lanes.
- Touchscreen Interfaces:These interactive displays provide intuitive navigation for customers, guiding them through the scanning, bagging, and payment steps. Touchscreen interfaces are standard across nearly all modern self-checkout systems, improving user experience.
Established barcode scanning remains foundational, but artificial intelligence technology is gaining share fastest in advanced deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large retail chains and convenience stores represent the primary buyer archetypes driving self-checkout system deployments across the United States. These entities seek solutions to manage operational costs and enhance customer throughput. Demand is particularly pronounced in urban and high-cost labor markets.
California
Demand for advanced self-checkout systems in California stems from persistent wage inflation and a large, tech-savvy consumer base. The Americans with Disabilities Act (ADA) strongly influences system design, ensuring accessibility for all users across the state. Silicon Valley and the greater Los Angeles area witness significant investment in AI-powered and integrated solutions for retail and grocery.
New York Metro
New York Metro retailers prioritize self-checkout systems to mitigate high labor costs and optimize customer flow in densely populated urban environments. Federal Trade Commission (FTC) guidelines on data privacy are a critical consideration for systems deployed in New York. Manhattan's flagship stores and Brooklyn's growing convenience sector are adopting mobile-integrated and touchless checkout experiences.
Texas
Texas exhibits strong demand for self-checkout systems due to its expanding population and the presence of numerous large retail chains. Compliance with PCI DSS standards for payment processing is paramount for all self-checkout installations across Texas. Houston's expansive retail landscape and Dallas's busy commercial hubs are seeing widespread adoption of standalone kiosks and integrated solutions.
Florida
Florida's robust tourism sector and diverse consumer base drive the need for efficient self-checkout systems in hospitality and retail. State-level consumer protection laws complement federal regulations like the FTC's oversight of data handling. The Orlando theme parks and Miami's bustling shopping districts are investing in interactive terminals and mobile payment integrations.
US Self-Checkout Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players across the US self-checkout systems market, creating a landscape of both broad solution providers and niche innovators. The market structure features established hardware vendors alongside agile software and AI developers. Three strategic archetypes include integrated solution providers, touchless technology innovators, and traditional kiosk manufacturers. Strategic partnerships and technology licensing are common competitive moves among these diverse entities.
Within the integrated solutions segment, NCR Corporation exemplifies a legacy provider offering extensive service networks and financing options to large retail chains. Mashgin represents a specialized innovator, focusing on AI-powered, touchless checkout systems particularly suited for convenience stores and cafeterias. Toshiba Global Commerce Solutions occupies a position as a comprehensive provider, delivering integrated hardware and software solutions specifically tailored for grocery environments. These companies anchor different segments of the market, from broad enterprise solutions to targeted, advanced technology deployments. Their diverse approaches reflect the varied demands of the US self-checkout landscape.
| Leading Market Players |
|---|
| Fujitsu Limited |
| Mashgin |
| NCR Corporation |
| Standard AI |
| StrongPoint |
| Diebold Nixdorf |
| ITAB Shop Concept |
| ECR Software Corporation |
| Toshiba Global Commerce Solutions |
| Others |
Cost & Logistics Intelligence
Commodity volatility in specialized sensor components and advanced AI processors directly determines pricing tier spreads for self-checkout systems and shapes the geographic concentration of system assembly.
Pricing Analysis
Cost-plus contract patterns, often indexed to labor rates and component costs, define procurement for large retail chains. Pricing models vary from subscription-based Hardware-as-a-Service for smaller businesses to project-based deployments for extensive store networks. Price differentiation stems from advanced AI capabilities for loss prevention and robust ADA compliance features. Pricing softness runs through the basic standalone kiosk segment due to increased competition and commoditization. Small businesses exhibit high price sensitivity, favoring flexible leasing, while large chains prioritize long-term value, integration, and operational efficiency.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly offered by system integrators to manage cash flow for component procurement. Geographic supply concentration for self-checkout systems centers on China for electronic components and sub-assemblies, with final assembly often occurring in the US or Mexico. Raw material dependencies include microprocessors, specialized touchscreens, and weight-sensitive sensors. Single-source vulnerability for high-performance AI chips represents a structural supply chain risk. Distribution for large retail chains typically runs through direct sales teams and dedicated service networks, while channel partners serve smaller and mid-sized retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US self-checkout systems market represents an early-cycle expansion story, buoyed by the broad penetration of hardware-as-a-service models.
For Market Incumbents: Entrench existing client relationships by offering advanced AI-driven loss prevention upgrades and flexible financing options. Expand service networks to support growing demand for HaaS models across diverse US states. Counter agile software-only providers by deepening vertical integration into AI development and proprietary software platforms. Prioritize R&D in computer vision to maintain technological leadership against emerging threats.
For New Entrants and Emerging Players: Mid-market retail underpenetration, particularly among regional grocery chains, offers a significant white-space opportunity. Target specialty retailers and convenience stores with cost-effective, modular self-checkout solutions. Develop simplified integration protocols for existing POS systems to reduce deployment friction. Leverage mobile-first scan-and-go functionalities as a key go-to-market angle for rapid adoption.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology-forward specialists with strong recurring revenue models. Long-term viability remains robust for 5-10 years due to persistent labor cost pressures and technological advancements. Target AI vision startups or niche HaaS providers with proven customer traction. Sustained reduction in self-checkout shrinkage rates across early adopters serves as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance AI-powered loss prevention | Deters theft in large retail chains, improving ROI for system deployments. |
| Expand Hardware-as-a-Service offerings | Lowers upfront costs for small businesses, broadening market access in new verticals. |
| Develop ADA-compliant modular systems | Addresses regulatory mandates, ensuring accessibility for diverse user bases in US states. |
| Integrate mobile scan-and-go features | Streamlines customer experience in convenience stores, driving higher transaction volumes. |
| Target quick-service restaurant vertical | Unlocks new revenue streams by adapting self-checkout technology for hospitality environments. |
Research Approach
A standing panel of retail operations executives, self-checkout system engineers, and payment solution providers provided ongoing calibration for primary insights. Secondary validation involved SEC filings of public technology companies, retail trade publications, and government labor statistics. This combined approach informed bottom-up market sizing and top-down validation through expert interviews.
Scenario-bracketing established the plausible range for market expansion across the analysis window. Segmentation dimensions modeled included product type, industry vertical, customer type, and underlying technology. Compound annual growth rates were derived from historical trends and projected adoption rates, incorporating US labor cost inflation and technological advancements in AI.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new AI-powered solution providers or major regulatory shifts would shift outcomes. Forecasts reflect assumptions regarding technology adoption and retailer investment priorities. Geopolitical instability or significant shifts in consumer sentiment towards automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Ticket Machine Market
Retail Technology
Smart Shelves Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Self-Checkout System Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Smart Shelf Market
Retail Technology
Cash Register Machines Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Global Kiosk Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Enterprise Mobility in Retail Market