
 Global Smart Retail Market | 2026-2036
Global Smart Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Retail Market Foresight
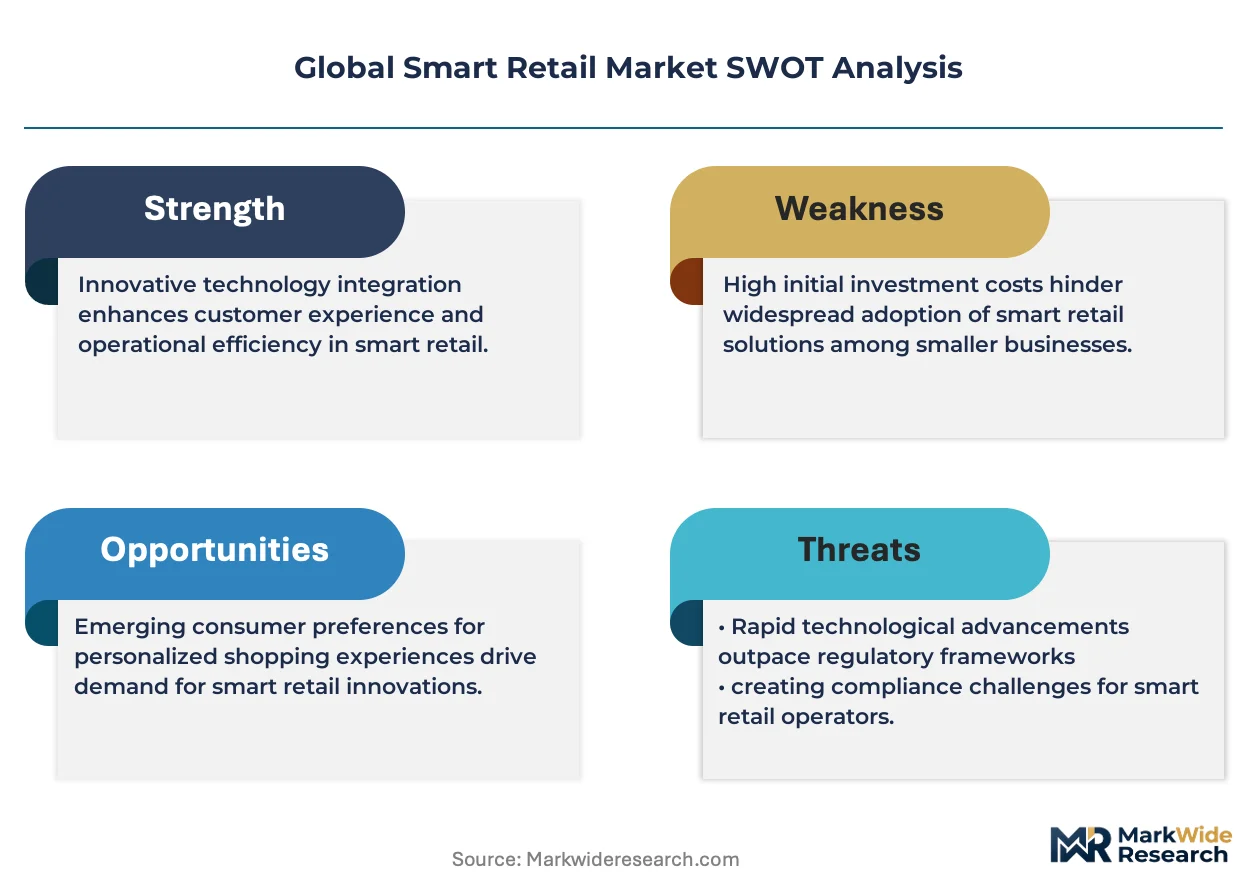
Enterprise-grade AI inference is rotating toward the edge as retailers demand sub-50-millisecond response times for real-time personalization and theft detection. Amazon.com, Inc. leverages its AWS Graviton infrastructure to sustain low-latency inference at physical storefronts. NVIDIA Corporation dominates GPU-accelerated edge computing platforms that power computer vision workloads in smart checkout lanes.
Smart retail encompasses sensor networks, computer vision systems, and machine learning platforms that automate inventory tracking, customer behavior analysis, and transaction processing in physical and omnichannel commerce environments. These systems typically process video feeds at 30-60 frames per second through on-site edge servers to minimize cloud dependency and data egress costs. Retail analytics solutions lead current deployment value as grocers and big-box chains prioritize shrinkage reduction and planogram compliance. Automated checkout applications are expanding fastest among convenience stores seeking labor cost containment during overnight operations.
The EU AI Act and GDPR impose strict algorithmic transparency requirements on customer engagement platforms deployed in European stores, forcing vendors to document training data provenance and decision logic. China's SAMR enforces GB standards for facial recognition terminals while the FDA oversees biometric data handling in US pharmacy-retail hybrid locations. Stakeholders must monitor divergence between Brussels-style risk classification and Beijing's algorithmic registration mandates when architecting cross-border platform deployments.
Market Dynamics
Edge AI inference is compressing response latency below 50 milliseconds, forcing retailers to re-architect store infrastructure around GPU-accelerated local servers rather than cloud-dependent pipelines.
Growth Catalysts
- EU AI Act compliance mandates:European retailers must document algorithmic decision logic for customer analytics platforms, creating certified vendor demand.
- Unmanned store pilots:China's SAMR-approved GB standards for facial recognition terminals accelerate automated checkout deployment in Shanghai and Shenzhen.
- Computer vision at 60 FPS:Real-time shelf monitoring systems automate planogram compliance and shrinkage detection for big-box chains.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in edge inference accelerators creates single-source dependency for computer vision workloads.
- GDPR algorithmic transparency:European data provenance requirements extend procurement cycles for customer engagement platforms by 6-12 months.
- Legacy POS integration:Decade-old transaction systems resist API connectivity with modern sensor networks without middleware layers.
Strategic Opportunities
- Convenience store automation:Overnight labor cost containment drives fastest adoption of automated checkout among 24-hour operators.
- India BIS certification pathway:Emerging retail infrastructure lacks legacy system baggage, enabling greenfield edge AI deployment.
- Computer vision-digital twin convergence:Real-time 3D store modeling merges with inventory systems for dynamic shelf optimization.
Industry Challenges
- Edge ML engineering scarcity:Retailers compete with autonomous vehicle and robotics sectors for firmware-optimized model deployment talent.
- Cross-border data residency:China's Cybersecurity Law and EU GDPR create conflicting localization requirements for multinational platform architectures.
- Sensor calibration drift:Computer vision accuracy degrades under variable lighting conditions, demanding continuous on-site model retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Retail Market |
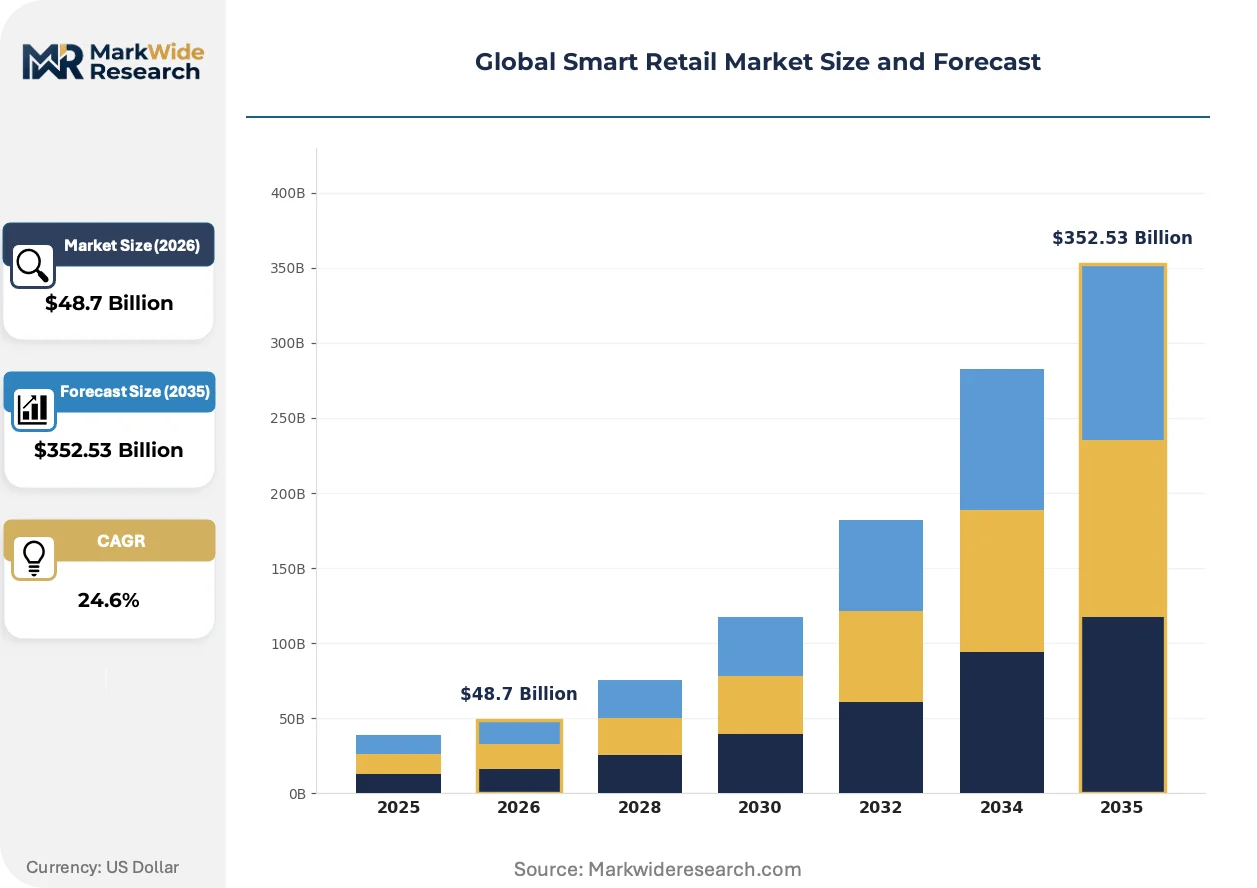
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $352.53 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
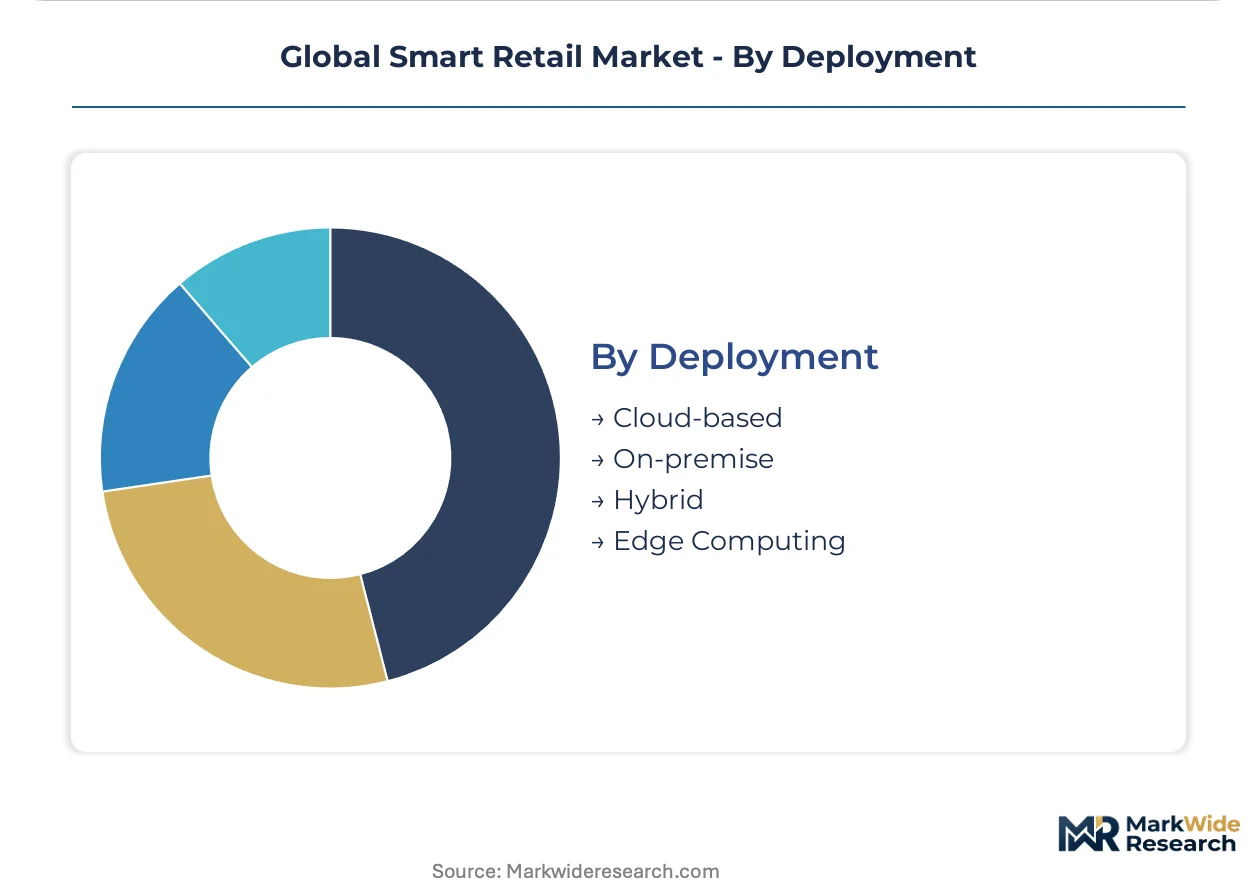
| Segmentation | Solution: Retail Analytics, Smart Shelves, Customer Engagement Platforms, Inventory Management Systems, Digital Signage Application: Personalized Promotions, Automated Checkout, Supply Chain Optimization, In-store Navigation, Demand Forecasting End User: Department Stores, Supermarkets, Specialty Stores, Convenience Stores, E-commerce Platforms Deployment: Cloud-based, On-premise, Hybrid, Edge Computing |
| Companies Covered | Amazon.com, Inc., IBM Corporation, Intel Corporation, Cisco Systems, Inc., Google LLC, NVIDIA Corporation, Huawei Technologies Co., Ltd., Samsung Electronics, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Retail Market Shifts & Advancements
Retail infrastructure is bifurcating between cloud-native analytics and edge-resident inference, with latency-sensitive applications migrating to store-local GPU clusters.
Vision-language models are displacing rule-based shelf monitoring systems. Grocers deploy multimodal AI that interprets product images alongside natural language inventory queries. This architecture compresses planogram compliance verification from hours to minutes while reducing cloud egress fees.
The EU AI Act's risk classification framework is forcing algorithmic documentation standards across European deployments. High-risk customer analytics platforms must submit training data provenance and decision logic for conformity assessment. Vendors are responding by building explainability layers that trace individual recommendations to source features.
Overnight convenience operators are unbundling cashier roles through autonomous checkout systems. Labor cost containment during 10 PM-6 AM shifts drives adoption where transaction volume justifies capital expenditure. South Korean convenience chains demonstrate highest penetration, with regulatory clarity from MFDS enabling rapid biometric payment authorization.
Global Smart Retail Market Segmentation
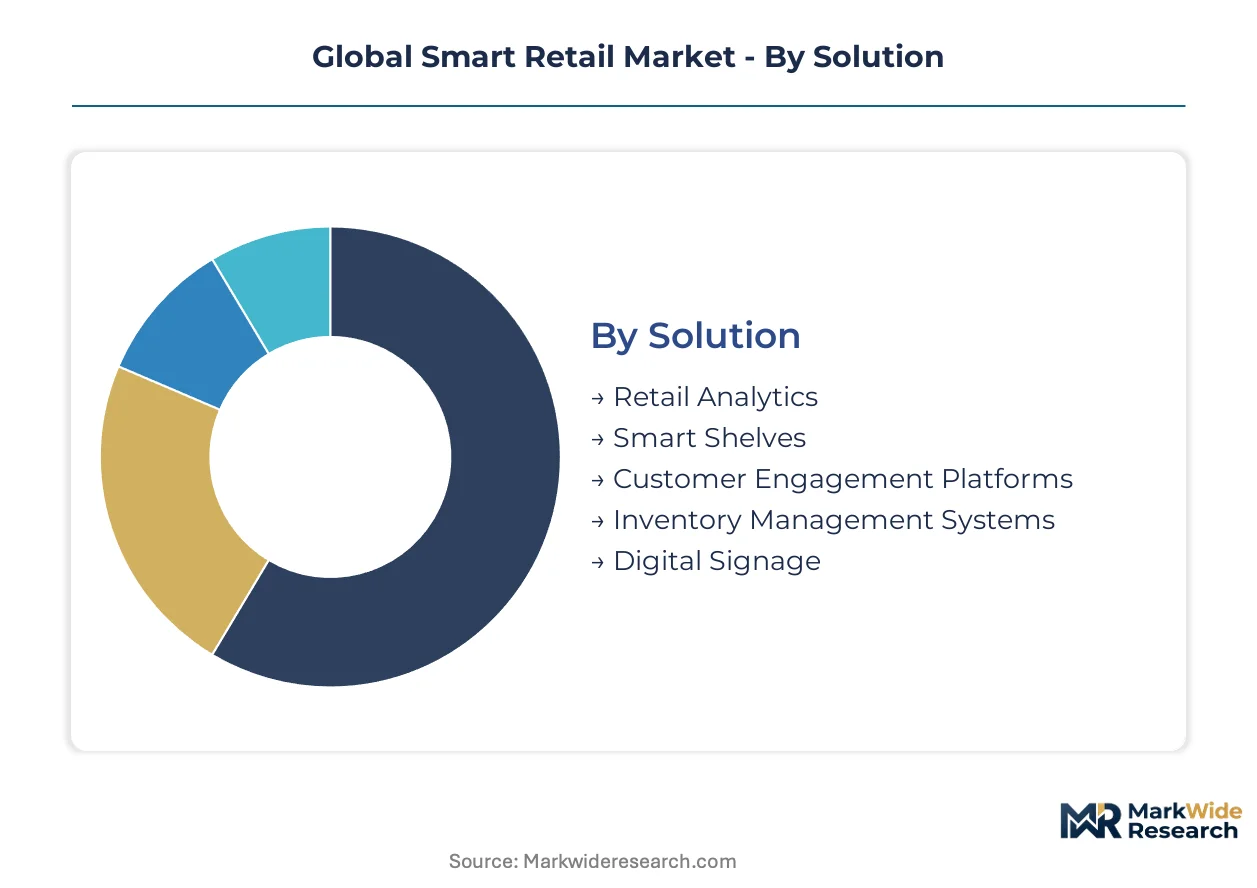
Smart retail deployments fragment across solution architectures, operational use cases, and infrastructure models. Channel strategies diverge sharply between cloud-native analytics providers and edge-hardware vendors. Procurement decisions increasingly hinge on latency requirements and data residency constraints rather than feature parity alone.
Solution:
Retail chains route high-frequency video analytics through edge-resident solutions while batch reporting flows through cloud channels. Solution selection tracks store format complexity and SKU velocity.
- Retail Analytics:Computer vision platforms process 30-60 FPS feeds for shopper pathing and dwell-time measurement. Grocers in Germany and France prioritize these systems under EU AI Act documentation mandates for algorithmic transparency.
- Smart Shelves:Weight-sensor and RFID-enabled shelving automates stock-level monitoring and planogram compliance. Convenience stores in South Korea deploy these most aggressively for overnight labor reduction.
- Customer Engagement Platforms:Facial recognition terminals with demographic inference.
- Inventory Management Systems:RFID and computer vision fusion for real-time stock positioning.
- Digital Signage:Programmable displays with audience-responsive content triggering.
By volume, Retail Analytics leads. By growth pace, Smart Shelves is expanding most quickly.
Application:
Application prioritization follows labor cost structure and transaction density. High-throughput formats emphasize checkout automation; big-box operators prioritize navigation and forecasting.
- Automated Checkout:Computer vision and sensor-fusion systems eliminate cashier stations. Unmanned store pilots in Shanghai and Shenzhen under SAMR GB standards accelerate deployment velocity.
- Supply Chain Optimization:Demand-sensing algorithms reduce safety stock and spoilage. Supermarkets leverage these for perishable inventory precision.
- Personalized Promotions:Real-time offer generation based on shopper proximity and purchase history.
- In-store Navigation:AR-enabled wayfinding for large-format retail environments.
- Demand Forecasting:ML models integrating weather, events, and promotional calendars.
Automated Checkout commands the largest installed base. Personalized Promotions shows the steepest expansion trajectory among application categories.
End User:
End-user procurement scales with square footage and SKU count. Format-specific workflows dictate sensor density and integration complexity.
- Supermarkets:Full-stack deployments spanning analytics, automated checkout, and inventory systems. High SKU velocity and shrinkage exposure justify capital intensity.
- Convenience Stores:Narrow-scope automation targeting overnight labor elimination. South Korean chains demonstrate highest penetration with MFDS-enabled biometric payment authorization.
- Department Stores:Customer engagement and navigation prioritization over inventory automation.
- Specialty Stores:Curated experience focus with limited SKU automation.
- E-commerce Platforms:Physical footprint extensions with click-and-collect optimization.
Supermarkets anchor current revenue concentration. Convenience Stores is climbing the fastest as 24-hour operators unbundle cashier roles.
Deployment:
Deployment architecture selection hinges on millisecond-latency requirements and data egress cost sensitivity. Hybrid models are displacing pure cloud for video-heavy workloads.
- Edge Computing:GPU-accelerated local inference for sub-50-millisecond response on theft detection and personalization. Amazon Web Services Graviton infrastructure sustains these workloads at physical storefronts.
- Hybrid:Edge preprocessing with cloud aggregation for training data and longitudinal analytics. Balances latency against capital expenditure.
- Cloud-based:Centralized processing for non-latency-sensitive reporting and cross-store benchmarking.
- On-premise:Legacy server architectures in regulated environments with strict data localization.
Edge Computing leads by new deployment value. Hybrid is gaining share fastest as retailers phase out cloud-dependent pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in smart retail technology flow from concentrated manufacturing clusters in East Asia toward deployment markets in North America and Europe. China maintains surplus positions in edge hardware and computer vision components. The United States and Germany import substantial volumes of GPU accelerators and sensor modules while exporting software frameworks and cloud infrastructure services.
United States
FDA oversight of biometric data in pharmacy-retail hybrids and AWS Graviton infrastructure deployment at physical storefronts drive domestic edge computing investment. The FTC enforces algorithmic transparency for customer analytics platforms. California and Washington State host the densest concentration of computer vision R&D facilities developing real-time shelf monitoring systems.
China
Unmanned store pilots across Shanghai and Shenzhen accelerate demand for facial recognition terminals and automated checkout systems. SAMR enforces GB standards for biometric data collection in commercial environments. The Yangtze River Delta manufacturing corridor supplies the majority of global edge inference accelerators and smart shelf sensor modules.
Germany
EU AI Act compliance mandates for algorithmic documentation extend procurement cycles for customer engagement platforms. The KBA coordinates with federal data protection authorities on biometric system certification. Bavaria and Baden-Württemberg anchor continental deployment of computer vision systems for planogram compliance in hypermarket chains.
South Korea
Overnight convenience store automation drives fastest adoption of cashierless checkout systems among 24-hour operators. MFDS regulatory clarity enables rapid biometric payment authorization deployment. The Seoul Capital Area demonstrates highest global penetration of autonomous retail formats with integrated computer vision infrastructure.
India
Greenfield retail infrastructure without legacy POS baggage enables direct edge AI deployment in emerging urban formats. BIS certification pathways for IoT devices and biometric terminals streamline vendor qualification. Maharashtra and Karnataka host pilot deployments of smart inventory systems in organized retail expansion zones.
Global Smart Retail Market Competitive Landscape
Concentration sits with cloud hyperscalers and semiconductor specialists who control the infrastructure layer beneath retailer-facing applications. The vendor base separates into three strategic tiers: full-stack platform providers, component specialists, and systems integrators. Competitive dynamics center on M&A activity targeting computer vision startups and strategic partnerships between chip vendors and retail software houses.
Among cloud-native platform providers, Amazon.com, Inc. and Google LLC exemplify the vertically integrated archetype combining edge hardware infrastructure with retail analytics software. NVIDIA Corporation occupies a distinct position as the dominant supplier of GPU-accelerated inference platforms powering computer vision workloads. These three entities anchor the competitive structure by controlling critical bottlenecks in latency-sensitive retail AI deployment.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| IBM Corporation |
| Intel Corporation |
| Cisco Systems, Inc. |
| Google LLC |
| NVIDIA Corporation |
| Huawei Technologies Co., Ltd. |
| Samsung Electronics |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day GPU lead times from Yangtze River Delta fabs concentrate pricing power with NVIDIA Corporation and AWS infrastructure providers, compressing margin flexibility for downstream retail software vendors while amplifying cost pass-through to supermarket chains deploying edge inference clusters.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing for edge AI platforms, with three-tier pricing structure across premium, standard, and economy levels differentiated by inference throughput and EU AI Act documentation depth. Price differentiation stems from certification grade (GDPR-compliant versus basic ISO tiers) and volume scale (enterprise multi-store contracts versus single-location pilots). Pricing pressure intensifies as Chinese edge hardware vendors undercut incumbent GPU pricing by fifteen to twenty percent in Southeast Asian markets. Convenience store operators demonstrate highest price sensitivity due to thin overnight margins, while supermarket chains absorb premium tiers for shrinkage reduction ROI.
Supply Chain Analysis
Port congestion at Shanghai and Shenzhen delays container availability for sensor module imports, extending inbound logistics costs for European and North American retail technology deployers. GPU accelerators and computer vision sensors concentrate manufacturing in China, South Korea, and Taiwan, with raw material dependencies spanning silicon wafers, CMOS image sensors, and rare-earth magnet components for RFID systems. Single-source vulnerability around NVIDIA's CUDA ecosystem creates supply chain risk for retailers standardizing on GPU-accelerated inference. Distribution runs through hyperscaler channel partners and specialized systems integrators serving big-box chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as latency requirements splinter procurement between cloud-native analytics and edge-resident inference, creating specialist niches for computer vision firmware optimizers and regulatory compliance documentation services.
For Market Incumbents: Secure exclusive GPU allocation agreements with NVIDIA Corporation to defend against emerging edge ASIC vendors attacking the sub-fifty-millisecond inference tier. Invest in backward integration into sensor calibration services to capture recurring revenue from planogram compliance deployments threatened by vision-language model commoditization. For New Entrants and Emerging Players: Anchor in India's BIS-certified greenfield retail infrastructure where legacy POS absence enables direct edge AI deployment without middleware integration costs. Target convenience store automation in South Korea's MFDS-regulated biometric payment corridor, offering computer vision-digital twin convergence as a differentiated go-to-market angle against established analytics vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from semiconductor conglomerates' non-core retail software divisions, where edge inference firmware talent sits underutilized outside automotive applications. Long-term viability hinges on regulatory documentation capabilities spanning EU AI Act and China's SAMR GB standards. Watch for inflection when unmanned store pilot density in Shanghai and Shenzhen triggers hyperscaler acquisition appetite for localized compliance expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Partnership | NVIDIA-CSP alliances lock in GPU supply for sub-50ms inference workloads. |
| Regulatory Certification Investment | EU AI Act documentation capabilities differentiate vendors in German supermarket procurement. |
| Computer Vision Acquisition | Vision-language model startups enable planogram compliance automation for grocers. |
| Geographic Expansion | India BIS pathway bypasses legacy POS integration costs for edge AI deployers. |
| Biometric Payment Integration | MFDS-compliant terminals unlock South Korean convenience store automation demand. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with retail technology procurement officers, edge infrastructure engineers, supermarket operations directors, and regulatory compliance specialists; and secondary validation against SAMR GB standard filings, EU AI Act conformity assessment databases, hyperscaler capex disclosures, and customs records for GPU and sensor module trade flows. Bottom-up triangulation across store-format deployment counts and top-down reconciliation against solution provider revenue disclosures anchored value estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning solution architecture (edge versus cloud-hybrid), application priority (automated checkout versus analytics), end-user format (supermarket versus convenience store), and regional regulatory cluster (EU AI Act versus SAMR versus FDA oversight). CAGRs derived from deployment velocity curves weighted by SKU density and labor cost structure, with inputs from edge inference latency requirements and GPU supply constraints.
Material uncertainties — supply chain disruptions, regulatory divergence between Brussels and Beijing, and vision-language model displacement timelines — sit outside the modeled envelope. Forecasts reflect assumptions about edge hardware cost curves and biometric data localization enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Self-Service Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
E-Retail Market
Retail Technology
AR in Retail Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Digital Kiosk Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Self-Checkout System Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Smart Grocery Cart Market