
 Alternative Retailing Technologies Market | 2026-2036
Alternative Retailing Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Retailing Technologies Market Outlook
Grocery and convenience retail is expanding its share of alternative retailing technology deployments as labor costs and speed-of-service pressures mount. Amazon.com, Inc. leverages its Just Walk Out computer vision platform to anchor frictionless store formats across multiple verticals. JD.com, Inc. sustains heavy R&D intensity in automated warehouse-to-shelf robotics. Alibaba Group Holding Limited dominates live-stream commerce integration with its unified payment and fulfillment stack.
Alternative retailing technologies encompass hardware and software systems that automate or augment consumer transactions, inventory management, and personalized merchandising through sensor fusion, edge computing, and biometric authentication protocols. These systems process real-time shopper behavior data to optimize stock levels, reduce shrinkage, and enable dynamic pricing in physical and digital environments. Mobile Payment and Self-Checkout product types currently occupy the largest installed base, while Smart Carts with integrated scales and screens are capturing margin pools in premium grocery formats. Artificial Intelligence and Cloud Computing technology segments lead deployment velocity, whereas Blockchain applications in supply chain traceability remain niche but structurally important for luxury and pharmaceutical retail.
The EU AI Act, GDPR, and China's SAMR algorithmic recommendation provisions are reshaping how retailers collect, process, and monetize consumer behavioral data across jurisdictions. FDA guidelines on biometric data in health-adjacent retail settings and Japan's METI standards for IoT device interoperability add further compliance layers for multinational operators. Stakeholders must monitor evolving cross-border data localization mandates and decide whether to architect region-specific technology stacks or pursue modular platforms with jurisdictional plug-ins.
Market Dynamics
Frictionless checkout architectures are compressing labor dependency ratios across grocery and convenience formats, forcing incumbents to reconfigure store footprints around sensor density and edge compute placement rather than traditional POS terminal layouts.
Growth Catalysts
- EU AI Act compliance mandates:Retailers in Germany and France are accelerating deployment of privacy-preserving computer vision systems to satisfy algorithmic transparency requirements ahead of enforcement deadlines.
- Self-checkout hardware:Supermarket chains in the United States are replacing legacy lanes with hybrid belted and scan-as-you-shop configurations to reduce queue abandonment.
- China's SAMR algorithmic recommendation provisions:Cross-border e-commerce platforms are restructuring personalization engines to maintain access to consumer markets while satisfying data governance protocols.
Market Restraints
- Semiconductor supply concentration:Edge AI chipsets for retail computer vision depend heavily on Taiwan-based foundry capacity, creating vulnerability to geopolitical disruption.
- GDPR biometric data friction:Facial recognition deployment in European stores faces extended legal review timelines and consent architecture costs that delay ROI realization.
- Legacy POS integration complexity:ERP systems from incumbent vendors resist API-native connectivity with cloud-based inventory management platforms, forcing expensive middleware development.
Strategic Opportunities
- India's DPI infrastructure:The country's unified payments interface and digital public goods stack enable low-cost entry for mobile-first retail automation without proprietary hardware dependency.
- Live-stream commerce convergence:Integration of real-time video shopping with automated fulfillment is opening white space in beauty and fresh grocery verticals.
- Japan METI IoT interoperability standards:Compliance with device certification protocols creates preferential access to convenience store networks seeking standardized sensor deployments.
Industry Challenges
- Edge AI engineering talent scarcity:Retailers struggle to recruit computer vision specialists capable of optimizing inference latency on constrained hardware budgets.
- Multi-jurisdiction data localization:Operators must architect separate inference pipelines for EU, Chinese, and US consumer data, fragmenting technology stacks and multiplying compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Retailing Technologies Market |
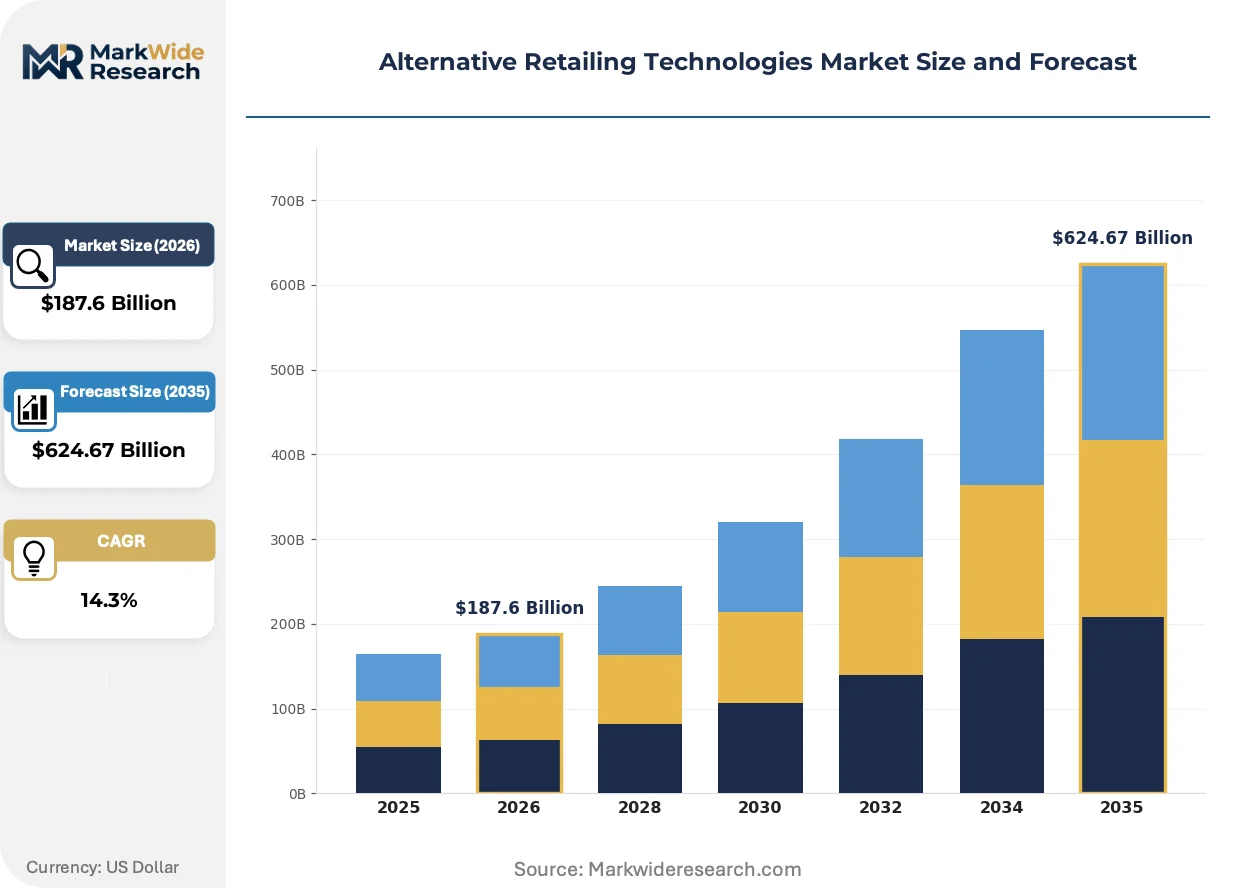
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Payment, Self-Checkout, Smart Carts, Virtual Try-On Technology: Augmented Reality, Artificial Intelligence, Blockchain, Cloud Computing End User: Supermarkets, E-commerce Platforms, Convenience Stores, Specialty Retailers Distribution Channel: Online Marketplaces, In-Store Solutions, Wholesale, Direct Sales |
| Companies Covered | Amazon.com, Inc., Alibaba Group Holding Limited, Walmart Inc., Shopify Inc., JD.com, Inc., PayPal Holdings, Inc., Zalando SE, Rakuten, Inc., eBay Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Retailing Technologies Market Strategic Shifts
Retail automation is shifting from labor substitution toward predictive merchandising, with sensor networks now capturing behavioral signals that feed dynamic pricing and micro-fulfillment orchestration in real time.
Computer vision with embedded weight-sensing fusion is electrifying the smart cart category, enabling item-level recognition without barcode scanning. Premium grocery chains in South Korea and the United Arab Emirates are piloting these units at scale, with deployment timelines compressing from eighteen-month pilots to six-month rollouts. The technology is electrifying margin capture by eliminating shrinkage at self-service fresh produce sections and enabling personalized promotion delivery based on basket composition.
The EU AI Act's risk classification framework for biometric identification systems is forcing retailers to segregate facial recognition deployments into high-risk and limited-risk categories with corresponding audit obligations. Grocery operators in France and the Netherlands are restructuring vendor contracts to transfer compliance liability to technology providers. Health-adjacent retail formats including pharmacies face additional FDA and EMA scrutiny when biometric data intersects with wellness product recommendations.
Buyer concentration among hard discount grocery banners is compressing vendor negotiation cycles and unbundling after-sales service from hardware procurement. German and Polish retail cooperatives are shifting toward outcome-based contracts that tie payment to uptime metrics and shrinkage reduction rather than capital expenditure transfers. This procurement evolution is most visible in automated warehouse-to-store replenishment systems where labor savings must demonstrate payback within twenty-four months to secure committee approval.
Alternative Retailing Technologies Market Segmentation
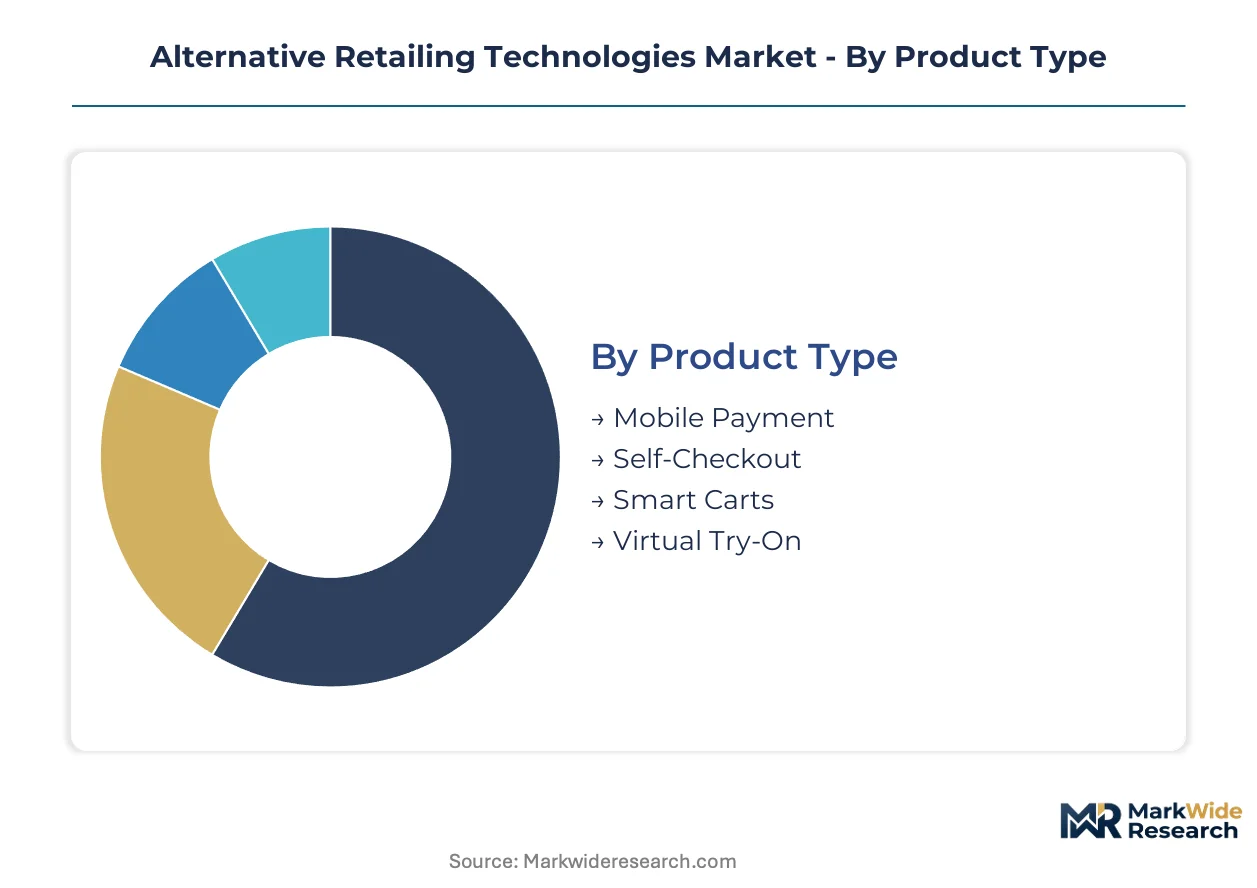
Alternative retailing technologies fragment across hardware form factors, software intelligence layers, and fulfillment modalities. Procurement committees evaluate segments through distinct lenses: capital intensity for product types, latency requirements for technology stacks, and throughput economics for end-user applications.
Product Type:
Capital deployment cycles and labor substitution economics drive buyer prioritization across checkout modalities.
- Mobile Payment:Near-field communication and QR-code protocols embedded in smartphone wallets process transactions without proprietary terminal hardware. Supermarket chains in the United States and China deploy these systems to reduce per-lane infrastructure costs while accelerating throughput during peak hours.
- Self-Checkout:Hybrid belted and scan-as-you-shop configurations combine barcode scanning with weight-verification sensors to minimize shrinkage. German grocery cooperatives favor these units for their twenty-four-month payback profiles against rising minimum wage mandates.
- Smart Carts:Computer vision and integrated scale arrays enable item-level recognition without manual scanning. South Korean premium formats pilot these for fresh produce sections where barcode adherence proves unreliable.
- Virtual Try-On:Augmented reality overlays render apparel and cosmetics on consumer devices or in-store mirrors. Beauty retailers deploy these to reduce return rates in online channels.
Volume sits with Mobile Payment; growth tilts toward Smart Carts.
Technology:
Inference latency and data sovereignty requirements shape architecture decisions across intelligence layers.
- Artificial Intelligence:Edge-deployed computer vision models process shopper behavior in real time for inventory optimization and dynamic pricing. Cloud Computing platforms host training pipelines and cross-store analytics while EU AI Act compliance mandates accelerate privacy-preserving federated learning architectures in France and Germany.
- Cloud Computing:Distributed compute fabrics enable centralized inventory visibility and predictive demand forecasting across multi-banner retail portfolios. China's SAMR algorithmic recommendation provisions force architectural bifurcation between domestic and international data residency zones.
- Augmented Reality:Spatial computing layers overlay product information and promotional content onto physical store environments. Japanese convenience stores leverage METI-certified IoT interoperability standards for sensor fusion deployments.
- Blockchain:Distributed ledger protocols enable supply chain provenance tracking for luxury goods and pharmaceutical cold chains. Deployment remains concentrated in high-value verticals where counterfeit exposure carries reputational liability.
Artificial Intelligence captures the largest deployment share; Cloud Computing exhibits the steepest expansion trajectory.
End User:
Throughput velocity and basket composition dictate technology matching across retail formats.
- Supermarkets:Full-format grocery operators deploy integrated stacks spanning self-checkout, smart carts, and automated replenishment to compress labor ratios across high-SKU environments. Polish retail cooperatives negotiate outcome-based contracts tying vendor payment to shrinkage reduction metrics.
- E-commerce Platforms:Pure-play digital retailers invest in warehouse robotics and last-mile orchestration algorithms rather than in-store automation. Live-stream commerce convergence in China demands real-time inventory synchronization with video shopping interfaces.
- Convenience Stores:Small-footprint operators prioritize frictionless checkout density and rapid replenishment cycles. Japanese chains seek METI-standardized sensor deployments to minimize vendor lock-in.
- Specialty Retailers:Vertical-specific formats including pharmacies and luxury boutiques deploy biometric authentication and provenance tracking for high-value transactions. FDA guidelines constrain health-adjacent biometric data collection in US pharmacy settings.
Supermarkets dominate installed base; E-commerce Platforms are climbing the fastest.
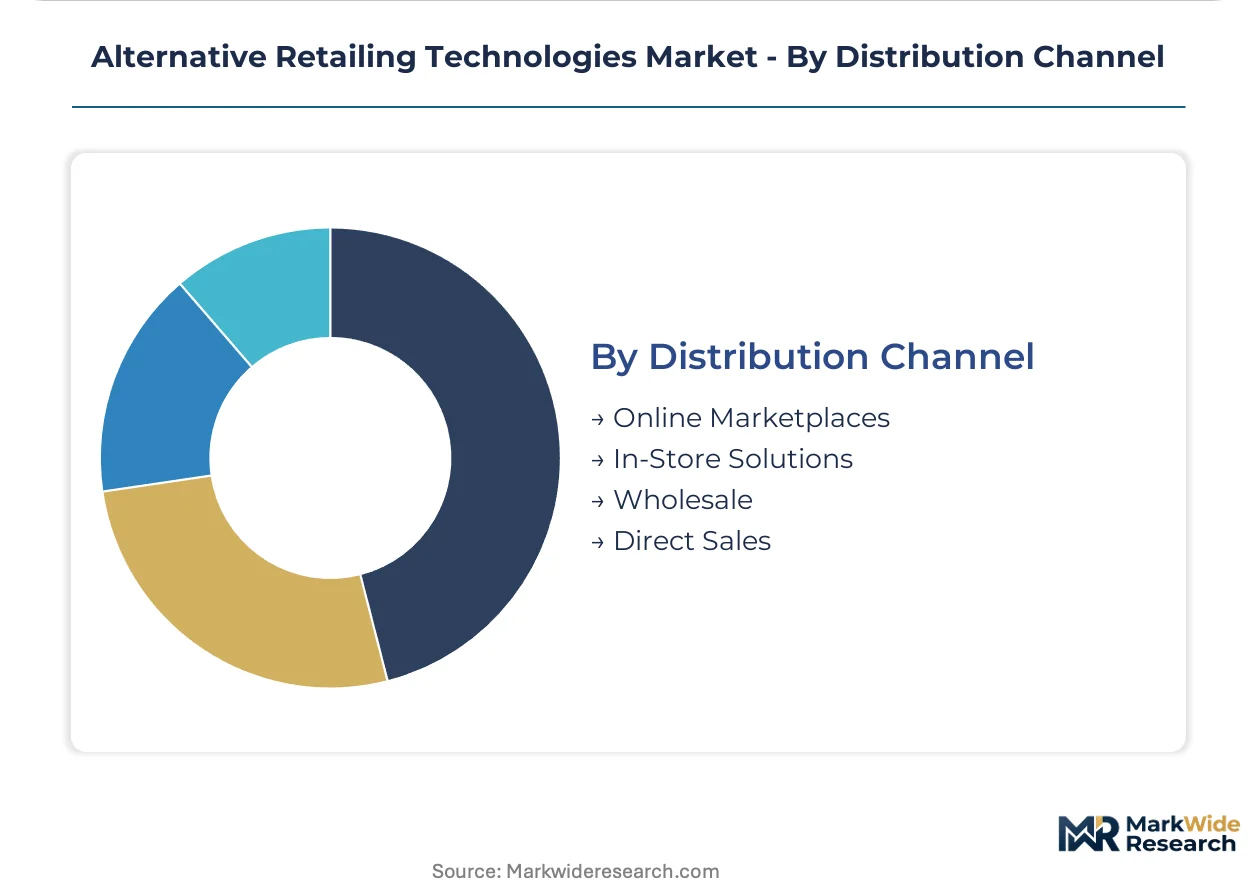
Distribution Channel:
Integration complexity and service bundling shape procurement modality selection.
- In-Store Solutions:Turnkey hardware-software bundles include installation, calibration, and maintenance contracts. German hard discount banners unbundle after-sales service to compress negotiation cycles.
- Online Marketplaces:Cloud-native platforms deliver software-as-a-service inventory management and personalization engines without physical deployment. India's DPI infrastructure enables low-cost UPI-integrated solutions.
- Direct Sales:Vendor field organizations engage enterprise retail headquarters for customized multi-banner rollouts. Relationship depth proves decisive in automated warehouse-to-shelf robotics procurement.
- Wholesale:Distributor networks aggregate demand from mid-tier retailers to achieve volume pricing on standardized hardware configurations. Polish cooperatives leverage collective purchasing power for replenishment automation.
In-Store Solutions anchor revenue; Online Marketplaces gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates concentrate retail technology pilot programs, while Special Economic Zones in Shenzhen and Bengaluru anchor hardware-software integration clusters for frictionless commerce infrastructure.
United States
Supermarket chains deploy hybrid self-checkout configurations to compress labor ratios amid rising minimum wage mandates. The FDA constrains biometric data collection in health-adjacent retail formats including pharmacies. California's Bay Area hosts dense clusters of edge AI startups supplying computer vision modules for cashierless store formats.
China
Live-stream commerce platforms demand real-time inventory synchronization with automated fulfillment systems. SAMR algorithmic recommendation provisions force architectural bifurcation between domestic and cross-border data residency zones. Shenzhen's hardware ecosystem supplies sensor fusion components for smart cart deployments across Asia-Pacific grocery formats.
Germany
Hard discount grocery cooperatives negotiate outcome-based contracts tying vendor payment to shrinkage reduction metrics. The EU AI Act accelerates deployment of privacy-preserving computer vision systems ahead of enforcement deadlines. Berlin-Brandenburg clusters host retail automation R&D facilities serving pan-European banner operators.
Japan
Convenience store networks seek METI-standardized sensor deployments to minimize vendor lock-in across small-footprint formats. METI IoT interoperability standards create preferential access for certified device manufacturers. Tokyo's Kanto region anchors pilot programs for frictionless checkout density in high-throughput urban locations.
India
The Unified Payments Interface enables low-cost entry for mobile-first retail automation without proprietary hardware dependency. RBI guidelines govern data localization requirements for payment system providers. Bengaluru's technology corridor concentrates startups integrating UPI protocols with cloud-native inventory management platforms.
Alternative Retailing Technologies Market Competitive Environment
Top-tier vendors anchor integrated platform ecosystems, while mid-tier specialists concentrate on single-modality hardware or regional software deployments. The vendor base stratifies across three archetypes: cloud-native commerce platforms, legacy retail operators with captive technology divisions, and pure-play automation hardware fabricators. Competitive moves center on strategic partnerships between grocery banners and technology providers, plus geographic licensing of frictionless store formats.
Within the cloud-native platform tier, Amazon.com, Inc. and Alibaba Group Holding Limited exemplify divergent regional dominance patterns, with the former anchoring North American frictionless commerce and the latter integrating live-stream shopping with automated fulfillment stacks. JD.com, Inc. occupies a position between these archetypes, representing heavy R&D intensity in warehouse-to-shelf robotics that supplies both proprietary retail operations and third-party logistics contracts.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Alibaba Group Holding Limited |
| Walmart Inc. |
| Shopify Inc. |
| JD.com, Inc. |
| PayPal Holdings, Inc. |
| Zalando SE |
| Rakuten, Inc. |
| eBay Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive integration into Taiwan-based foundry capacity for edge AI chipsets anchors both supply security and pricing power for computer vision hardware vendors serving grocery and convenience formats. German hard discount banners exploit this concentration by negotiating outcome-based contracts that transfer silicon cost volatility to technology providers while compressing hardware margins.
Pricing Analysis
Short lead-time premiums command pricing separation from spot inventory channels in edge AI chipset procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by inference latency specifications and EU AI Act compliance certification. Cost compression in standard-tier sensor modules is intensifying because buyer concentration among Polish and German retail cooperatives unbundles after-sales service from hardware procurement. Hard discount grocery banners exhibit highest price sensitivity; luxury pharmacy formats demonstrate lowest sensitivity due to FDA-constrained biometric authentication requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for frictionless checkout systems while wholesale distributors aggregate mid-tier retailer volume. Manufacturing concentrates in Taiwan for edge AI chipsets, China for sensor fusion components, and South Korea for smart cart display modules. Raw material dependencies span silicon wafers, rare earth magnets for robotic actuators, and lithium-ion cells for mobile payment terminals. Single-source vulnerability in Taiwan-based foundry capacity creates exposure to geopolitical disruption. Distribution runs through vendor field organizations for enterprise multi-banner rollouts and cloud-native platforms for SaaS personalization engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase where computer vision platforms displace legacy barcode scanning infrastructure across grocery formats. Edge-deployed inference models are replacing centralized cloud processing for real-time inventory optimization.
For Market Incumbents: Hedge against semiconductor supply concentration by diversifying foundry relationships across Taiwan and South Korea while accelerating privacy-preserving federated learning R&D to satisfy EU AI Act audit obligations. Outcome-based contract proliferation among German cooperatives threatens hardware margin structures; vertical integration into edge AI chip design offers cost control leverage against this pressure. For New Entrants and Emerging Players: India's DPI infrastructure opens a window for UPI-integrated mobile-first automation without proprietary hardware dependency. Target Bengaluru's technology corridor for cloud-native inventory management partnerships. Live-stream commerce convergence in China represents the most penetrable white space; pursue white-label fulfillment orchestration software for beauty and fresh grocery verticals. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by cloud-native commerce platforms seeking computer vision capabilities. Long-term viability favors vendors with jurisdictional plug-in architectures that fragment technology stacks across EU, Chinese, and US data residency zones. Watch for inflection in METI IoT interoperability certification adoption rates among Japanese convenience store networks.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Computer Vision Deployment | EU AI Act compliance mandates in France and Germany accelerate vendor contract restructuring. |
| Smart Cart Hardware Scale-Up | South Korean premium grocery pilots compress rollout timelines from eighteen months to six months. |
| Live-Stream Commerce Platform Integration | Alibaba's unified payment and fulfillment stack demands real-time inventory synchronization capabilities. |
| Outcome-Based Contract Transition | Polish and German cooperatives tie vendor payment to shrinkage reduction and uptime metrics. |
| Jurisdictional Data Architecture Modularity | SAMR algorithmic provisions and GDPR force architectural bifurcation between domestic and cross-border zones. |
Study Parameters
SEC filings, hyperscaler capex disclosures, and METI IoT certification databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with grocery chain CTOs, convenience store operations directors, edge AI platform engineers, and retail procurement committee members validated deployment timelines and contract structure evolution. Bottom-up unit economics for self-checkout hardware and smart cart deployments were triangulated against top-down retail technology budget forecasts across the analysis window.
Bottom-up modeling of installed base expansion by product type and technology segment was cross-referenced against top-down retail automation capital expenditure surveys. Segmentation dimensions spanned checkout modality, inference latency tier, deployment scale, and regional regulatory cluster. CAGRs were derived from trend extrapolation of hardware shipment volumes and SaaS subscription growth rates. Forecast inputs incorporated EU AI Act enforcement timeline assumptions and India's UPI transaction velocity trends.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures would alter the outlook if privacy-preserving computation achieves regulatory equivalence with centralized processing at lower latency. Forecasts reflect assumptions regarding semiconductor supply normalization and cross-border data localization mandate stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Retail Inventory Software Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
AR in Retail Market
Retail Technology
Global Kiosk Market
Retail Technology
Connected Retail Market
Retail Technology
Self-Checkout System Market
Retail Technology
E-Retail Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Ticket Machine Market
Retail Technology
Smart Shelves Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Global Smart Retail Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Internet of Things (IoT) in Retail Market