
 Global Advanced Shopping Technology Market | 2026-2036
Global Advanced Shopping Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Shopping Technology Market Foresight
Enterprise grocery retail chains are unwinding legacy procurement patterns as convenience stores and pop-up shops gain share as technology buyers. Amazon.com Inc leverages captive cloud infrastructure to control checkout automation deployments. Walmart Inc anchors its position through backward integration into in-store sensor networks. Nvidia Corporation dominates AI training workloads for real-time customer analytics.
Advanced shopping technology encompasses augmented reality overlays, RFID tagging systems, beacon proximity networks, and facial recognition platforms that process shopper behavior data at the edge. These systems integrate computer vision algorithms with millimeter-scale location accuracy to automate inventory tracking, personalize in-store displays, and eliminate friction at payment terminals. Artificial Intelligence applications for customer analytics command the deepest margin pools, while augmented reality for user experience enhancement represents the fastest-expanding segment as hardware costs decline. RFID and beacon technology for inventory management remains structurally mature with stable procurement volumes from large retail chains.
The EU AI Act, GDPR, and China's SAMR algorithm recommendation provisions collectively impose divergent compliance burdens on facial recognition and automated decision systems deployed in retail environments. The FCC in the United States governs spectrum allocation for beacon and RFID transmissions, directly shaping hardware certification timelines. Stakeholders must monitor regulatory fragmentation across Washington, Brussels, and Beijing to determine where pilot deployments face the lowest compliance drag.
Market Dynamics
AI-powered inventory systems are compressing replenishment cycles across grocery retail chains, forcing legacy procurement patterns to unwind as convenience stores and pop-up shops emerge as technology buyers alongside traditional enterprises.
Growth Catalysts
- EU AI Act compliance mandates:Retailers across Germany, France, and the Netherlands are accelerating facial recognition platform upgrades to meet algorithmic transparency requirements before enforcement deadlines.
- Edge computing infrastructure:Millimeter-scale location accuracy systems are enabling real-time shopper behavior analytics that personalize in-store displays and automate payment terminals.
- Urban fulfillment network density:China and the United States are scaling smart store deployments fastest, concentrating demand for beacon proximity networks and RFID tagging systems.
Market Restraints
- GDPR data processing constraints:Facial recognition platforms face structural friction in European retail environments due to biometric data consent requirements and cross-border transfer restrictions.
- Cloud infrastructure concentration:Captive cloud providers control checkout automation deployments, creating supplier power asymmetries for mid-size retail chains.
- Hardware certification timelines:FCC spectrum allocation processes for beacon and RFID transmissions extend hardware approval cycles in the United States.
Strategic Opportunities
- India's retail modernization:BIS standards for electronic payment systems and the PLI scheme for semiconductor manufacturing are creating regulatory tailwinds for smart store technology adoption.
- AR-VR convergence:Augmented reality overlays are merging with virtual reality training platforms to create immersive product visualization experiences for furniture and apparel retailers.
- SAMR algorithm provisions:China's recommendation algorithm regulations are mandating interpretability standards that favor domestic AI training workload providers over foreign competitors.
Industry Challenges
- Computer vision engineering scarcity:Edge AI deployment requires specialized talent in real-time video analytics that retail technology vendors struggle to recruit at scale.
- Legacy POS integration complexity:Sensor networks must interface with decades-old payment terminal infrastructure, creating middleware development bottlenecks.
- Cross-jurisdictional compliance fragmentation:Divergent requirements across Washington, Brussels, and Beijing force retailers to maintain parallel deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Shopping Technology Market |
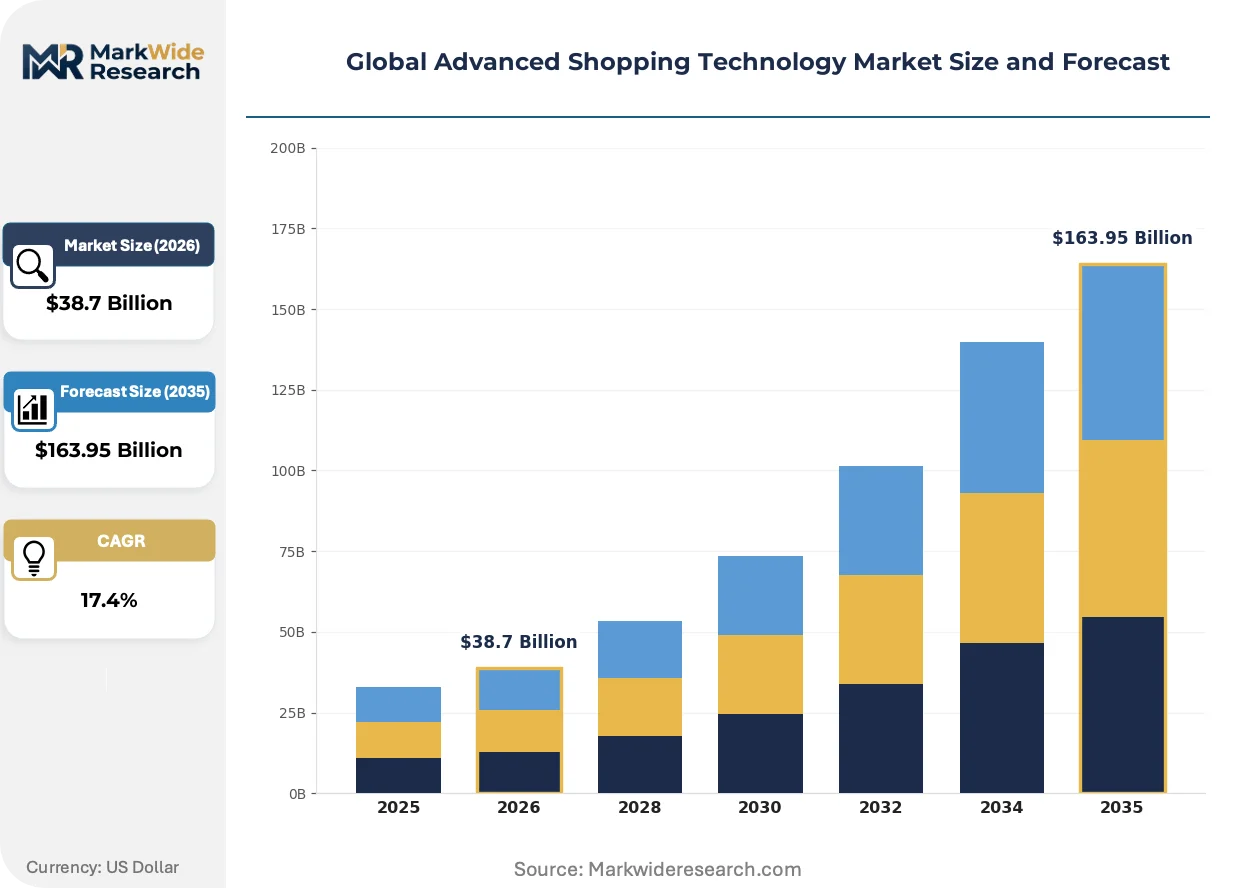
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Augmented Reality, Virtual Reality, Artificial Intelligence, RFID, Beacon Technology, Facial Recognition Application: User Experience Enhancement, Inventory Management, Personalized Marketing, Checkout Automation, Customer Analytics, Supply Chain Optimization Customer Type: Retail Chains, Specialty Stores, Supermarkets, E-commerce Platforms, Convenience Stores, Pop-up Shops Distribution Channel: Online Marketplaces, Direct Sales, Resellers, Mobile Applications, Physical Outlets, Social Commerce |
| Companies Covered | Amazon.com Inc, Walmart Inc, Google LLC, Nvidia Corporation, Intel Corporation, Samsung Electronics, Qualcomm, Huawei Technologies, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Shopping Technology Market Shifts & Advancements
Computer vision algorithms are actively compressing the boundary between physical and digital retail, enabling automation layers that were technically infeasible five years ago.
Millimeter-wave radar sensing is supplanting traditional camera-based people-counting systems in high-traffic retail environments. German supermarket chains are adopting these platforms to maintain shopper privacy while capturing footfall patterns. The technology is enabling GDPR-compliant analytics that camera systems cannot deliver, reshaping competitive positioning for European retail technology vendors.
REACH substance restrictions and RoHS compliance deadlines are forcing hardware manufacturers to reformulate solder compositions and battery chemistries in beacon devices. Component suppliers serving European retail chains face compressed redesign cycles. RFID tag producers are accelerating halogen-free substrate adoption to maintain market access across EU member states.
Outcome-based service contracts for inventory management systems are displacing perpetual license models among North American grocery chains. Retailers in California and Texas now prefer performance-linked fees tied to stockout reduction metrics. This procurement evolution favors vendors with captive sensor manufacturing over pure software providers lacking hardware control.
Global Advanced Shopping Technology Market Segmentation
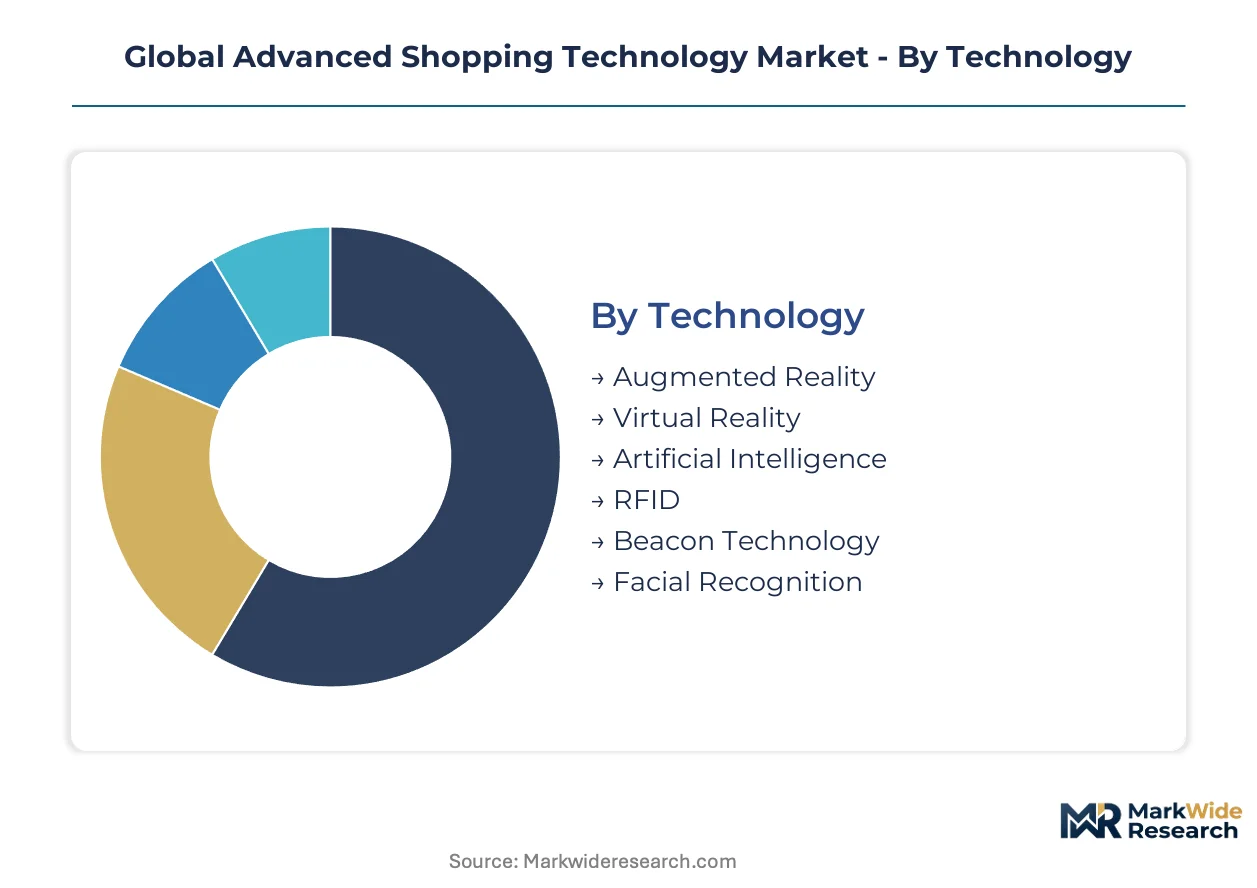
Technology substitution pressures are fragmenting procurement patterns across the Global Advanced Shopping Technology Market as legacy systems face displacement from edge computing architectures. Retailers must navigate overlapping technology stacks where computer vision, millimeter-wave sensing, and AR overlays compete for capital allocation within the same fulfillment budget.
Technology:
Facial recognition platforms confront the steepest substitution threat from millimeter-wave radar and privacy-preserving computer vision alternatives that bypass biometric consent requirements.
- Artificial Intelligence:Machine learning models process real-time shopper behavior data at the network edge, enabling predictive inventory replenishment and dynamic pricing adjustments. Demand concentrates among United States and Chinese grocery retail chains deploying captive cloud infrastructure for customer analytics workloads.
- Augmented Reality:Spatial computing overlays merge digital product information with physical shelf environments through smartphone cameras and smart glasses. Furniture and apparel retailers in Germany and the United States are scaling AR visualization tools as hardware costs decline and 5G latency improves.
- RFID:Passive and active radio-frequency identification tags enable millimeter-scale inventory tracking across warehouse and store-floor environments.
- Beacon Technology:Bluetooth Low Energy proximity networks trigger location-aware promotions and indoor navigation assistance.
- Facial Recognition:Biometric identification systems automate payment authentication and demographic analytics.
- Virtual Reality:Immersive training simulations and virtual showroom environments support employee onboarding and remote product demonstrations.
Artificial Intelligence anchors the volume base while Augmented Reality gains share at the steepest rate.
Application:
Margin concentration varies sharply across use cases, with backend automation commanding premium pricing relative to customer-facing experience layers.
- Customer Analytics:Edge-deployed computer vision algorithms extract footfall patterns, dwell times, and conversion funnels from video feeds. United States and Chinese urban fulfillment networks are scaling these systems fastest as retailers compete on same-day delivery precision.
- Inventory Management:Sensor fusion platforms combining RFID, computer vision, and weight-sensing shelves automate stock-level monitoring and shrinkage detection. German supermarket chains are deploying these systems under EU AI Act compliance timelines that mandate algorithmic transparency.
- Checkout Automation:Computer vision-enabled grab-and-go systems eliminate traditional payment terminals.
- Personalized Marketing:Beacon-triggered promotions and AI-curated product recommendations adapt to individual shopper profiles.
- Supply Chain Optimization:Predictive demand forecasting and automated replenishment algorithms reduce working capital requirements.
- User Experience Enhancement:AR wayfinding, virtual try-on, and interactive digital signage reduce friction in product discovery.
Inventory Management captures the deepest margin pools while Checkout Automation expands most quickly among convenience store deployments.
Customer Type:
Procurement authority is migrating downward from enterprise headquarters toward regional operators and temporary retail formats.
- Retail Chains:National and multinational operators deploy integrated technology stacks across hundreds of locations, leveraging scale economies in sensor hardware and cloud analytics subscriptions. Walmart and Amazon anchor United States demand through backward integration into proprietary sensor networks.
- Convenience Stores:Small-format urban retailers are emerging as unexpected technology adopters, deploying compact checkout automation and inventory tracking systems that compensate for limited staff availability. Operators in Japan and South Korea are scaling unmanned store formats fastest.
- Supermarkets:Large-format grocery operators balance customer experience investments with backend efficiency priorities.
- E-commerce Platforms:Pure-play digital retailers are extending into physical touchpoints through pop-up and showroom formats.
- Specialty Stores:Niche retailers in apparel, electronics, and cosmetics deploy AR visualization and personalized recommendation engines.
- Pop-up Shops:Temporary retail formats prioritize rapid-deployment technology bundles with minimal infrastructure requirements.
Retail Chains dominate current procurement volumes while Convenience Stores are climbing the fastest as technology buyers.
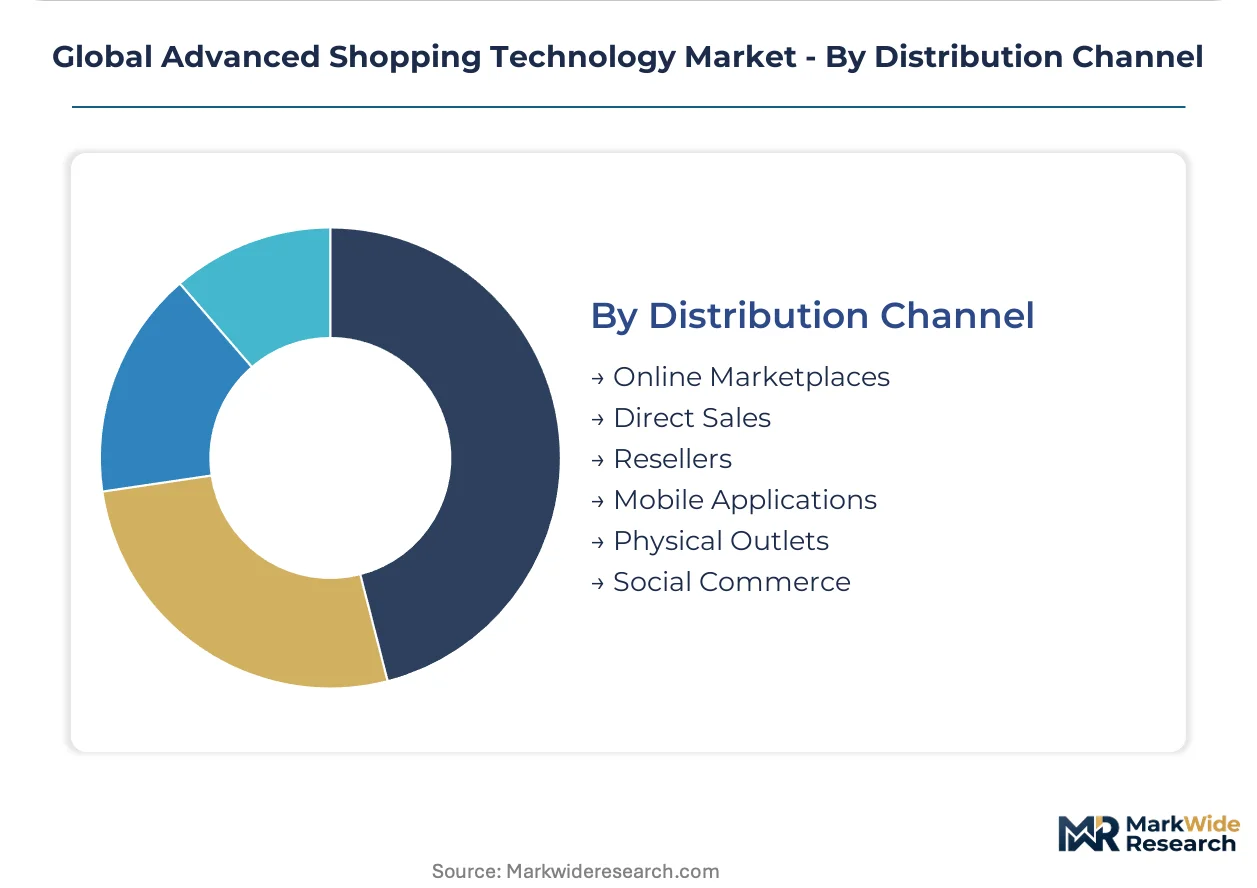
Distribution Channel:
Channel power asymmetries favor vertically integrated technology vendors that control both hardware manufacturing and software deployment.
- Direct Sales:Technology vendors maintain captive salesforces for enterprise retail accounts, offering outcome-based contracts tied to inventory accuracy or shrinkage reduction metrics. North American grocery chains in California and Texas are shifting procurement toward performance-linked fee structures.
- Online Marketplaces:Cloud infrastructure providers and hardware aggregators are consolidating access to AI training workloads and edge computing devices. Amazon Web Services controls substantial United States checkout automation deployment pipelines.
- Resellers:Regional systems integrators bundle hardware installation with middleware development for legacy POS integration.
- Mobile Applications:AR and beacon technology reach consumers through retailer-branded smartphone software.
- Physical Outlets:Traditional technology distributors maintain showroom and demonstration capabilities for tactile product evaluation.
- Social Commerce:Live-streaming and influencer-integrated purchasing platforms embed shopping technology directly into content consumption environments.
Direct Sales maintains the largest revenue contribution while Online Marketplaces are expanding most rapidly as procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise grocery chains in the United States, China, and Germany anchor procurement volumes for AI-powered inventory systems. Convenience store operators in Japan and South Korea are emerging as unexpected technology adopters. Regulatory fragmentation across Washington, Brussels, and Beijing is forcing parallel deployment architectures.
United States
Walmart and Amazon deploy proprietary sensor networks across urban fulfillment centers in California and Texas. FCC spectrum allocation processes govern beacon and RFID hardware certification timelines. The Greater Boston cluster houses computer vision engineering talent pools that retail technology vendors recruit aggressively.
China
SAMR algorithm recommendation provisions mandate interpretability standards for facial recognition platforms in Shanghai and Shenzhen smart store deployments. MIIT governs spectrum allocation for proximity network hardware. The Yangtze River Delta concentrates domestic AI training workload providers scaling edge computing infrastructure.
Germany
Supermarket chains accelerate facial recognition platform upgrades under EU AI Act compliance deadlines. ECHA REACH substance restrictions force beacon device manufacturers to reformulate solder compositions and battery chemistries. The Munich-Stuttgart corridor anchors millimeter-wave radar sensing adoption for GDPR-compliant footfall analytics.
Japan
Convenience store operators scale unmanned store formats fastest in Tokyo and Osaka metropolitan areas. METI standards govern electronic payment system interoperability for checkout automation. The Kanto region concentrates compact inventory tracking system deployments compensating for limited staff availability.
India
BIS standards for electronic payment systems and the PLI scheme for semiconductor manufacturing create regulatory tailwinds in Maharashtra and Karnataka. TRAI governs spectrum allocation for beacon proximity networks. The Delhi-NCR cluster attracts smart store technology pilots from domestic retail chains modernizing procurement infrastructure.
Global Advanced Shopping Technology Market Competitive Landscape
Player mix skews toward cloud infrastructure providers controlling checkout automation deployment pipelines. Market structure concentrates around three strategic tiers: captive cloud operators with backward integration into sensor hardware, AI training workload specialists dominating real-time customer analytics, and retail chains developing proprietary technology stacks. Dominant competitive moves include outcome-based service contracts displacing perpetual license models and strategic partnerships bridging legacy POS integration gaps.
Among United States-based technology providers, Amazon.com Inc, Walmart Inc, and Nvidia Corporation occupy distinct archetype positions. Amazon represents the captive cloud operator model leveraging infrastructure control over automation deployments. Walmart exemplifies retail chain backward integration into in-house sensor network development. Nvidia anchors the AI training workload specialization tier for edge-deployed customer analytics.
| Leading Market Players |
|---|
| Amazon.com Inc |
| Walmart Inc |
| Google LLC |
| Nvidia Corporation |
| Intel Corporation |
| Samsung Electronics |
| Qualcomm |
| Huawei Technologies |
| IBM |
| Others |
Supply & Pricing Matrix
Outcome-based service contracts with performance-linked fee indexation lock in multi-year supply access for AI-powered inventory systems while capping price exposure for North American grocery chains. These arrangements tether vendor compensation to stockout reduction metrics rather than hardware unit volumes, reshaping procurement economics across California and Texas urban fulfillment networks.
Pricing Analysis
Cost-plus contracts with semiconductor component indexation dominate sensor hardware procurement for beacon and RFID systems. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-compliant facial recognition platforms from GDPR-constrained alternatives and basic inventory tracking modules. Pricing pressure stems from cloud infrastructure concentration as Amazon Web Services and captive operators squeeze middleware vendors on checkout automation deployment margins. Convenience store operators exhibit highest price sensitivity due to limited capital budgets, while enterprise retail chains absorb premium tiers for algorithmic transparency certification.
Supply Chain Analysis
TSMC fabrication capacity in Taiwan serves as the critical chokepoint for edge AI chip supply to computer vision platform vendors. Hardware manufacturing concentrates in China, South Korea, and Taiwan for millimeter-wave radar sensors, Bluetooth Low Energy modules, and GPU training clusters. Component sourcing draws from rare earth processors in Inner Mongolia, lithium cell producers in South Korea, and advanced substrate fabricators in Japan. Single-source vulnerability persists for 7nm and below AI inference chips. Distribution runs through direct vendor salesforces for enterprise accounts and cloud marketplace aggregators for mid-size retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from algorithmic transparency auditing and edge model retraining is expanding faster than hardware sales as EU AI Act enforcement deadlines approach. Recurring compliance subscription layers now command higher margin multiples than initial sensor network deployment.
For Market Incumbents: Compound defensive moats through backward integration into captive sensor manufacturing and exclusive cloud infrastructure partnerships that lock out middleware competitors. Millimeter-wave radar alternatives threaten camera-based facial recognition platforms with GDPR-compliant substitutes. Priority investment targets edge computing talent pools in the Greater Boston corridor and Munich-Stuttgart corridor where computer vision engineering scarcity concentrates. For New Entrants and Emerging Players: Lead with privacy-preserving sensing modalities that bypass biometric consent requirements in European retail environments. India's BIS standards alignment and PLI scheme incentives create the most penetrable regulatory entry point for semiconductor-integrated smart store bundles. Go-to-market positioning should emphasize rapid-deployment kits for pop-up shops and convenience stores with minimal legacy POS integration burden. For Investors and Strategic Acquirers: Capital is best deployed toward AI training workload specialists with edge deployment capabilities and outcome-based contract portfolios. Long-term viability favors vendors controlling both sensor hardware manufacturing and cloud analytics infrastructure rather than pure software layers. Watch for inflection when SAMR algorithm interpretability mandates in China force foreign facial recognition platform exits, creating acquisition opportunities for domestic-compliant technology stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Sensor fusion combining RFID, computer vision, and weight-sensing shelves reduces stockout rates for German supermarket chains under EU AI Act timelines. |
| Strategic Partnership | Legacy POS middleware bridges enable checkout automation deployment without terminal replacement, accelerating convenience store adoption in Japan. |
| Acquisition of Specialist Firm | Millimeter-wave radar sensing capabilities address GDPR footfall analytics demand that camera systems cannot serve in Munich-Stuttgart corridor retail. |
| Geographic Expansion | India's PLI scheme for semiconductor manufacturing and BIS payment standards create regulatory tailwinds for smart store technology pilots in Delhi-NCR cluster. |
| Product Launch | AR visualization tools for furniture and apparel retailers leverage declining hardware costs and 5G latency improvements in Germany and United States. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and regulatory agency enforcement calendars preceded structured interviews with retail technology procurement directors, cloud platform engineers, computer vision engineering leads, and EU regulatory compliance officers. Primary fieldwork validated secondary data from FCC spectrum allocation records, ECHA REACH substance restriction updates, and SAMR algorithm recommendation guidance documents. Bottom-up unit deployment estimates triangulated against top-down retail capital expenditure projections across the analysis window.
Variance decomposition separates volume growth from price realization and mix shift effects throughout the forecast period. Segmentation dimensions modeled include technology type, application use case, customer format, and regional regulatory cluster. CAGRs derive from fitted growth curves anchored to disclosed deployment pipelines and vendor backlog data. Edge computing infrastructure buildout schedules and EU AI Act compliance deadline phasing serve as industry-specific forecast inputs.
Underlying assumptions cover stable FCC spectrum allocation timelines, REACH substance restriction enforcement continuity, and SAMR algorithm interpretability standard finalization, with deviation risk concentrated in cross-jurisdictional compliance fragmentation forcing parallel deployment architectures. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and cloud infrastructure concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Self-Service Market
Retail Technology
Ticket Machine Market
Retail Technology
Global Smart Retail Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Connected Retail Market
Retail Technology
Global Kiosk Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
E-Retail Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Internet of Things (IoT) in Retail Market