
 Global Bladder Disorders Market | 2026-2036
Global Bladder Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bladder Disorders Market Foresight
Modular therapy bundling is pivoting how urology clinics procure bladder disorder treatments, combining diagnostic tools with medication protocols into single-contract offerings. Astellas Pharma leverages its neuromodulation portfolio to anchor premium positioning in overactive bladder segments. Pfizer competes through sustained R&D intensity across urinary incontinence drug formulations. Medtronic controls the surgical devices channel with sacral nerve stimulation systems that dominate interventional urology.
Bladder disorders encompass pathological conditions affecting urinary storage and voiding function, including overactive bladder, urinary incontinence, interstitial cystitis, and neurogenic dysfunction, typically diagnosed through urodynamic testing, cystoscopy, and urine cytology with treatment spanning pharmaceutical, interventional, and behavioral modalities. Medication categories command established revenue pools through long-acting antimuscarinics and beta-3 agonists, while surgical devices represent the fastest-expanding segment as minimally invasive neuromodulation gains procedural share. Diagnostic tools occupy concentrated margin positions where advanced urodynamics systems integrate AI-assisted pressure-flow analysis.
The FDA's 510(k) and PMA pathways govern device commercialization, while the EMA's MDR framework and Japan's PMDA standards shape parallel market access requirements across major jurisdictions. The EU AI Act increasingly affects diagnostic tools incorporating machine learning for cystoscopic image interpretation. Stakeholders must monitor reimbursement parity between pharmaceutical and interventional therapies as health technology assessments evolve.
Market Dynamics
Modular therapy bundling is compressing procurement cycles across urology clinics, forcing device and pharmaceutical suppliers to integrate diagnostic platforms with treatment protocols into single-contract offerings rather than standalone product sales.
Growth Catalysts
- Home Healthcare Infrastructure:Patients in the United States, Germany, and Japan are migrating from institutional settings to home-based continence management, expanding demand for portable neuromodulation devices and remote monitoring systems.
- FDA Accelerated Pathways:The FDA's breakthrough device designation and priority review vouchers are compressing commercialization timelines for sacral nerve stimulation systems and AI-assisted urodynamics platforms.
- Minimally Invasive Migration:Percutaneous tibial nerve stimulation and botulinum toxin intradetrusor injection protocols are displacing open surgical correction as first-line interventional options across outpatient surgical centers.
Market Restraints
- Reimbursement Parity Gaps:Health technology assessments in Germany and Japan create asymmetric coverage between pharmaceutical antimuscarinics and interventional neuromodulation, limiting procedural volume expansion.
- Supply Concentration Risk:Sacral nerve stimulation pulse generators rely on concentrated lithium-ion battery supply chains centered in East Asian manufacturing clusters, exposing procurement to geopolitical friction.
- Technical Limitation:Current urodynamics systems lack standardized pressure-flow calibration across manufacturer platforms, complicating multi-site clinical trial data aggregation and regulatory submission packages.
Strategic Opportunities
- Underpenetrated Markets:Brazil and Saudi Arabia exhibit significant diagnosis-treatment gaps for overactive bladder, with continence care infrastructure concentrated in tertiary urban centers while rural access remains limited.
- Technology Convergence:Machine learning cystoscopic image interpretation is converging with cloud-based urodynamics data lakes, enabling predictive voiding dysfunction modeling before symptom onset.
- EU AI Act Tailwind:The EU AI Act's risk-classification framework for diagnostic software creates compliance roadmaps that early-mover AI-embedded urodynamics vendors can leverage for competitive differentiation.
Industry Challenges
- Specialized Workforce Scarcity:Urodynamics technologists and interventional urology nurse specialists require certification pathways that lag behind device innovation cycles, constraining clinic expansion.
- Legacy System Integration:Electronic health record interoperability between proprietary urodynamics workstations and hospital IT architectures demands costly middleware development, delaying AI diagnostic deployment.
- IP Licensing Complexity:Patent thickets surrounding sacral nerve stimulation electrode geometries and pulse algorithms complicate new entrant market access and increase litigation exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bladder Disorders Market |
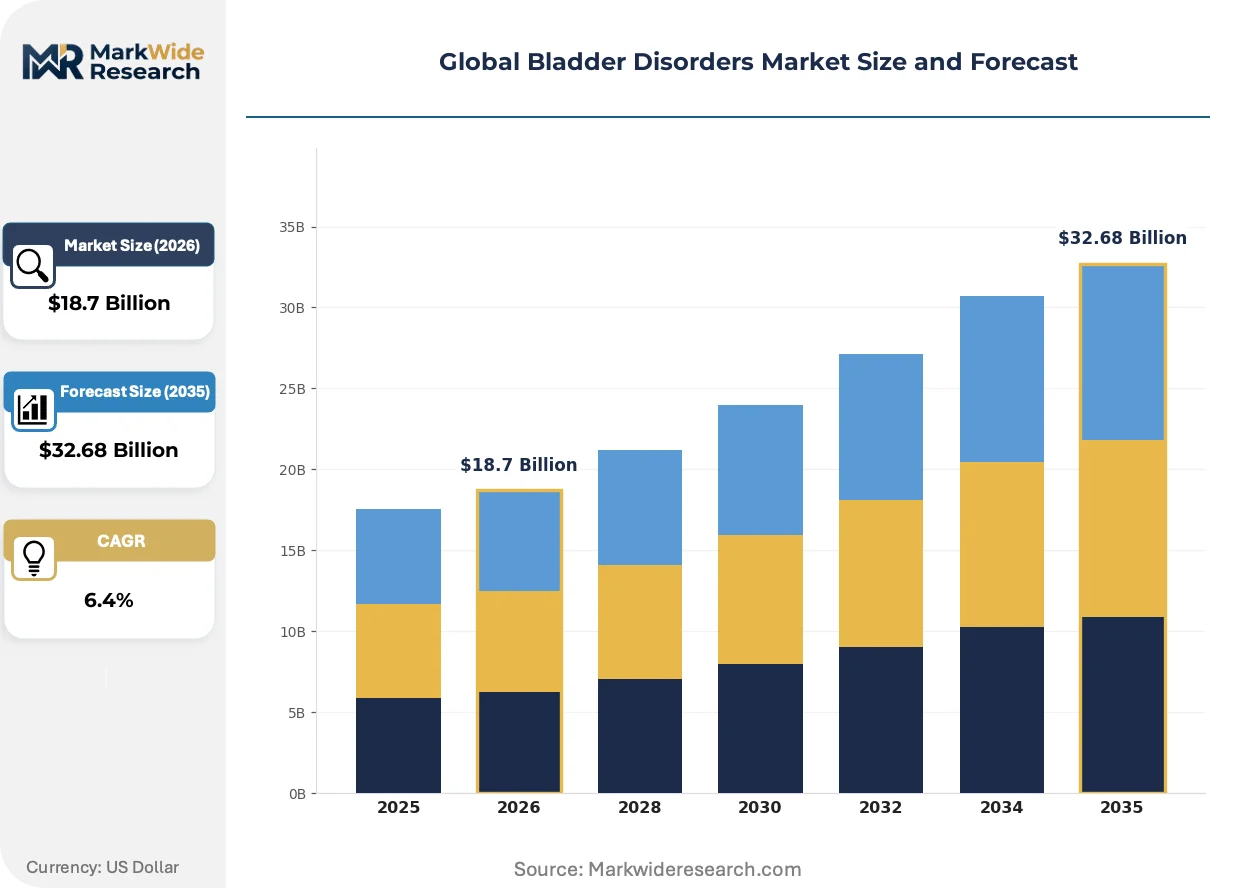
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Surgical Devices, Diagnostic Tools, Therapies, Supportive Care Therapy Area: Urinary Incontinence, Interstitial Cystitis, Bladder Cancer, Overactive Bladder, Neurogenic Bladder End User: Specialty Clinics, Rehabilitation Centers, Home Healthcare, Research Institutes, Diagnostic Laboratories Distribution Channel: Hospital Pharmacies, Online Pharmacies, Retail Pharmacies, Direct Sales, Medical Distributors |
| Companies Covered | Astellas Pharma, Pfizer, AbbVie, Teva Pharmaceutical Industries, Medtronic, Viatris, Johnson & Johnson, Endo International, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bladder Disorders Market Shifts & Advancements
Artificial intelligence is penetrating diagnostic workflows while regulatory frameworks accelerate device approval timelines and patient demand shifts toward non-pharmaceutical interventions.
AI-assisted pressure-flow analysis is converging with conventional urodynamics hardware, enabling real-time detrusor contractility quantification without manual tracing. Academic medical centers in the United States and Japan are piloting these integrated platforms for complex neurogenic bladder cases. The technology is compressing specialist interpretation bottlenecks while standardizing diagnostic consistency across multi-site urology networks.
The EU AI Act's risk-based classification system is mandating conformity assessments for machine learning modules embedded in cystoscopic imaging systems. Device manufacturers must now document training data provenance and algorithmic performance metrics before CE marking. Diagnostic tool vendors with existing quality management systems under the MDR framework are adapting faster than software-native entrants lacking medical device regulatory experience.
Patients are demanding non-pharmaceutical first-line therapies, compressing switching cycles from antimuscarinic trials to interventional neuromodulation. Urology clinics in Germany and Japan are responding by unbundling behavioral therapy, physiotherapy, and device trials into sequential care pathways rather than parallel pharmaceutical protocols. This preference shift is visible most acutely among employed populations aged 45-65 seeking symptom control without cognitive side effect profiles.
Global Bladder Disorders Market Segmentation
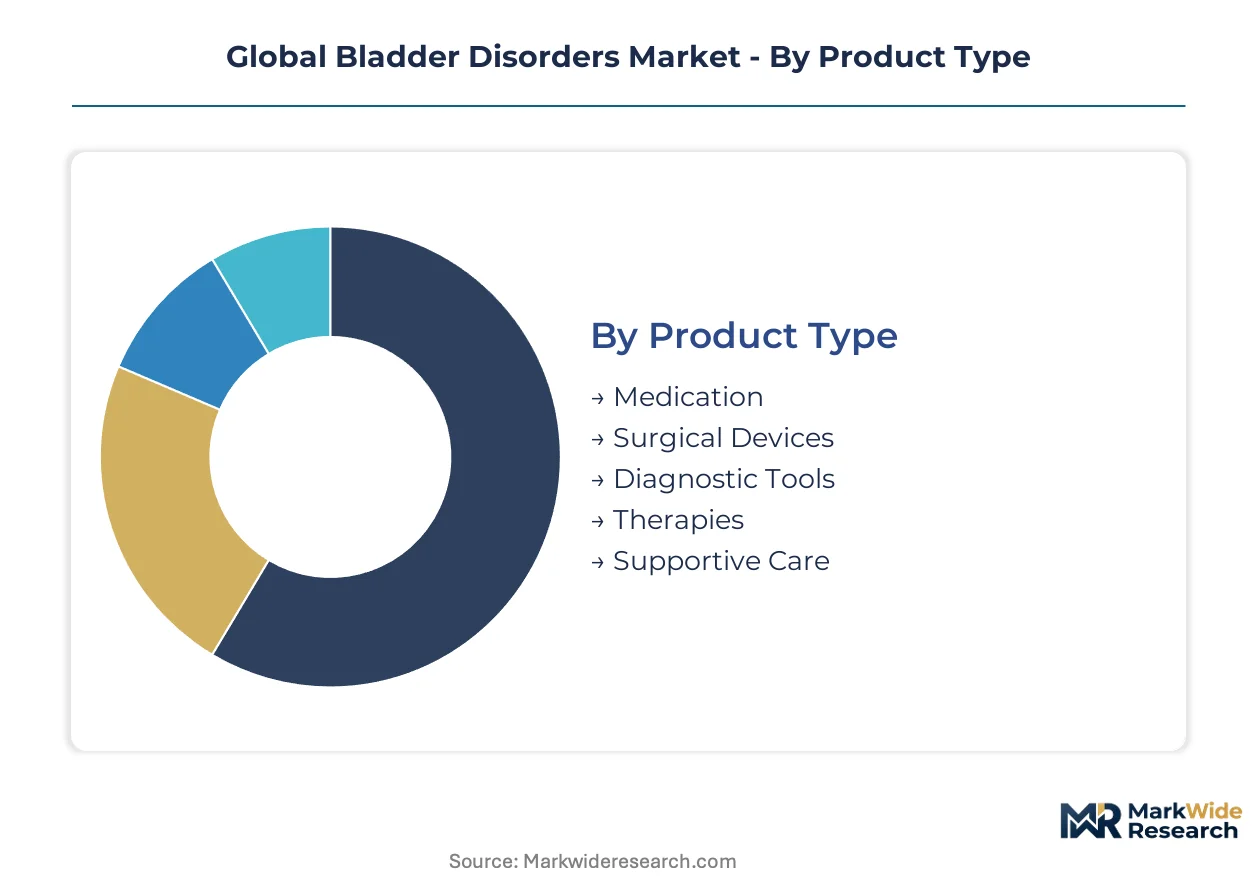
Segmentation in bladder disorders reveals how procurement power concentrates across institutional buyers and how therapy modality preferences split between pharmaceutical, interventional, and diagnostic pathways. Understanding these divides exposes where margin pools accumulate and where competitive positioning shifts most rapidly.
Product Type:
Technology sophistication separates segments into those governed by chemical formulation patents versus those controlled by hardware miniaturization and algorithmic performance.
- Medication:Long-acting antimuscarinics and beta-3 agonists dominate outpatient prescribing through established safety profiles and oral administration convenience. Demand concentrates in Germany and Japan where health technology assessments favor pharmaceutical first-line protocols over interventional alternatives, though cognitive side effect concerns are compressing switching cycles to device-based options.
- Surgical Devices:Sacral nerve stimulation systems and percutaneous tibial nerve stimulators anchor the interventional portfolio through rechargeable pulse generators and minimally invasive implantation techniques. United States outpatient surgical centers are displacing hospital-based implantation as site-of-care shifts toward lower-acuity settings, accelerating volume growth.
- Diagnostic Tools:Urodynamics workstations with pressure-flow analysis and AI-assisted cystoscopic imaging systems serve complex neurogenic and refractory cases.
- Therapies:Behavioral modification protocols and pelvic floor physiotherapy represent non-invasive first-line options.
- Supportive Care:Continence pads, catheter systems, and skin protection products serve chronic management needs.
Mature deployment sits with Medication. Newer deployment is concentrated in Surgical Devices.
Therapy Area:
Clinical complexity and reimbursement intensity vary sharply across conditions, with benign functional disorders commanding different procurement pathways than oncologic indications.
- Overactive Bladder:Idiopathic detrusor overactivity affects millions of working-age adults, creating sustained demand for both pharmaceutical and neuromodulation interventions. United States employer-sponsored insurance plans are expanding coverage for sacral nerve stimulation as productivity impact data strengthens, shifting procedural volume toward earlier intervention.
- Urinary Incontinence:Stress, urge, and mixed subtypes span age demographics from postpartum women to elderly populations with pelvic floor dysfunction. Germany's statutory health insurance system maintains asymmetric reimbursement between antimuscarinic trials and interventional escalation, constraining neuromodulation penetration despite patient preference for non-pharmaceutical options.
- Interstitial Cystitis:Chronic bladder pain syndrome with Hunner's lesions requires specialized diagnostic workup and multimodal management.
- Bladder Cancer:Oncologic staging drives cystoscopic surveillance and intravesical therapy demand.
- Neurogenic Bladder:Spinal cord injury, multiple sclerosis, and diabetic neuropathy create complex voiding dysfunction requiring urodynamic characterization.
Volume concentration favors Urinary Incontinence. Steepest expansion trajectory belongs to Overactive Bladder.
End User:
Site-of-care economics and patient acuity determine where capital equipment investments concentrate versus where consumable replenishment cycles dominate.
- Specialty Clinics:Urology and urogynecology practices anchor diagnostic and interventional service delivery through dedicated procedure rooms and certified technologist staffing. Japan's aging demographics are expanding clinic networks beyond tertiary academic centers into prefectural capitals, extending geographic access.
- Home Healthcare:Portable neuromodulation devices and remote monitoring platforms enable chronic condition management outside institutional settings. United States Medicare reimbursement for home-based continence care is expanding as hospital-at-home waivers persist, accelerating demand for patient-operated therapeutic systems.
- Rehabilitation Centers:Post-acute and neurorehabilitation facilities manage neurogenic bladder sequelae.
- Diagnostic Laboratories:Urine cytology and biomarker testing support screening and surveillance protocols.
- Research Institutes:Academic medical centers pilot AI-assisted diagnostics and novel neuromodulation algorithms.
Revenue concentration remains with Specialty Clinics. Fastest share gains are occurring in Home Healthcare.
Distribution Channel:
Channel control reflects whether procurement authority sits with pharmacy benefit managers, capital equipment committees, or direct manufacturer relationships.
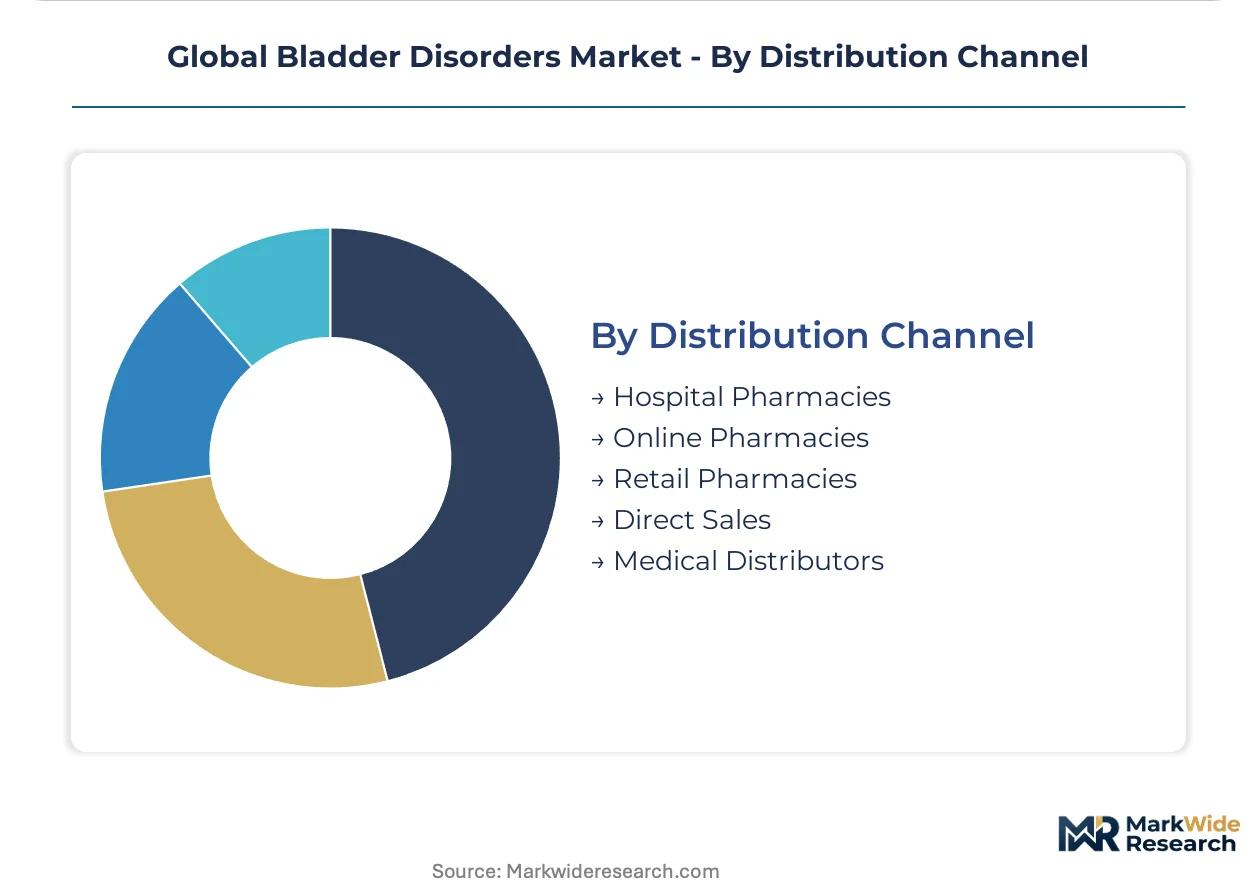
- Hospital Pharmacies:Inpatient and affiliated outpatient dispensing captures acute interventional cases and complex diagnostic workups. United States health system consolidation is centralizing formulary decisions across integrated delivery networks, compressing vendor diversity.
- Direct Sales:Implantable neuromodulation systems and high-end urodynamics platforms require field clinical specialist support and long-term service contracts. Germany's hospital procurement law (Krankenhausversorgungsgesetz) encourages direct manufacturer negotiation for capital equipment above threshold values, bypassing distributor markups.
- Medical Distributors:Regional and national distributors handle consumables, catheters, and continence products.
- Retail Pharmacies:Community dispensing serves oral medication maintenance therapy.
- Online Pharmacies:E-commerce platforms are gaining traction for replenishment of chronic care supplies.
Established volume flows through Hospital Pharmacies. Emerging volume is concentrating in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in the United States, Germany, and Japan while patient demand spreads across aging populations in Western Europe and East Asia. Consumption patterns diverge between pharmaceutical-first markets and those embracing interventional neuromodulation.
United States
Employer-sponsored insurance plans are expanding sacral nerve stimulation coverage as productivity impact data strengthens, shifting procedural volume toward earlier intervention. The FDA's breakthrough device designation compresses commercialization timelines for neuromodulation systems. Outpatient surgical centers in Texas and Florida are displacing hospital-based implantation as site-of-care shifts accelerate.
Germany
Statutory health insurance maintains asymmetric reimbursement between antimuscarinic trials and interventional escalation, constraining neuromodulation penetration despite patient preference for non-pharmaceutical options. The Krankenhausversorgungsgesetz encourages direct manufacturer negotiation for capital equipment above threshold values. Bavaria's hospital procurement networks are consolidating urodynamics platform purchasing across integrated delivery systems.
Japan
Aging demographics are expanding urology clinic networks beyond Tokyo and Osaka into prefectural capitals, extending geographic access to continence care. PMDA standards shape market access requirements parallel to FDA pathways. Nagoya's medical device manufacturing corridor anchors domestic production of portable neuromodulation systems for home healthcare export.
United Kingdom
NHS England's integrated care systems are piloting bundled payment models combining diagnostic urodynamics with behavioral therapy protocols. MHRA post-Brexit regulatory autonomy is diverging from EMA MDR timelines for AI-assisted cystoscopic devices. London's academic medical centers are leading multi-site trials for machine learning pressure-flow analysis platforms.
Brazil
Diagnosis-treatment gaps for overactive bladder persist with continence care infrastructure concentrated in São Paulo and Rio de Janeiro while rural access remains limited. ANVISA regulatory pathways for imported neuromodulation devices create extended approval timelines versus domestic pharmaceutical registration. Southeast regional hospital networks are negotiating direct distribution agreements to bypass distributor markups on surgical devices.
Global Bladder Disorders Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across pharmaceutical, device, and diagnostic segments, creating a tiered structure where scale advantages in regulatory affairs clash with agility in therapy bundling. Large-cap pharmaceutical houses anchor medication revenue pools through established antimuscarinic and beta-3 agonist portfolios. Interventional device specialists control hardware miniaturization and rechargeable pulse generator technology. Diagnostic platform vendors are consolidating around AI-assisted urodynamics integration. Dominant competitive moves include strategic partnerships between pharmaceutical and device suppliers for therapy bundling, plus geographic expansion into underpenetrated Latin American and Middle Eastern markets.
Within the pharmaceutical archetype, Astellas Pharma and Pfizer occupy positions exemplifying contrasting strategic postures toward neuromodulation adjacencies. Astellas leverages its established urology presence to anchor premium positioning in overactive bladder segments. Pfizer competes through sustained R&D intensity across urinary incontinence drug formulations while monitoring interventional migration trends. Medtronic represents the device-specialist archetype, controlling the surgical devices channel with sacral nerve stimulation systems that dominate interventional urology procurement decisions.
| Leading Market Players |
|---|
| Astellas Pharma |
| Pfizer |
| AbbVie |
| Teva Pharmaceutical Industries |
| Medtronic |
| Viatris |
| Johnson & Johnson |
| Endo International |
| Bayer |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States and Germany's statutory health insurance funds anchor procurement power through volume-commitment contracts, compressing margins for standalone product vendors and rewarding therapy-bundling suppliers with pricing stability.
Pricing Analysis
Margin tightening in sacral nerve stimulation systems reflects concentrated lithium-ion battery sourcing and rechargeable pulse generator miniaturization costs. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded urodynamics platforms from conventional pressure-flow systems and basic catheter-based diagnostics. Cost-down pressure on antimuscarinic formulations accelerates because Japanese health technology assessments favor pharmaceutical first-line protocols. Employer-sponsored insurance plans in the United States exhibit lowest price sensitivity for neuromodulation devices, while retail pharmacy channels for oral medications face highest substitution elasticity.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing clusters to Western European distribution hubs complicates just-in-time delivery for implantable pulse generators. Component manufacturing concentrates in Japan, South Korea, and China for lithium-ion cells, microelectronic assemblies, and biocompatible polymers. Raw material dependencies include rare earth elements for magnet components, medical-grade silicone for electrode insulation, and high-purity titanium for implant housings. Single-source vulnerability in specialized battery cell production creates supply continuity exposure. Distribution runs through direct manufacturer relationships for capital equipment and regional medical distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular therapy bundling is forcing consolidation as standalone pharmaceutical and device vendors lose procurement access to integrated delivery networks.
For Market Incumbents: Acquire AI-assisted diagnostic platforms to anchor therapy-bundling contracts against pure-play software entrants. Secure backward integration into lithium-ion battery cell production to insulate sacral nerve stimulation margins from East Asian supply concentration. Expand certified urodynamics technologist training programs to overcome workforce scarcity constraining clinic network expansion. For New Entrants and Emerging Players: The EU AI Act's risk-classification framework in Europe opens a window for compliance-first AI-embedded cystoscopic imaging vendors to differentiate against established players adapting legacy quality systems. Target Brazil's diagnosis-treatment gap for overactive bladder in secondary cities beyond São Paulo and Rio de Janeiro. Pursue hospital-at-home waiver pathways in the United States for portable neuromodulation device reimbursement. For Investors and Strategic Acquirers: The window for entry favors device-specialist platforms with FDA breakthrough device designation momentum. Long-term viability hinges on neuromodulation hardware miniaturization capabilities and cloud-based urodynamics data integration. Watch for Medicare reimbursement parity decisions between pharmaceutical and interventional therapies as the inflection signal for procedural volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses commercialization timelines for sacral nerve stimulation systems in the United States. |
| CE Marking Pathway Under MDR | Shapes market access requirements for AI-assisted urodynamics platforms across European markets. |
| Hospital System Partnership | Secures bundled procurement contracts combining diagnostic and interventional service delivery. |
| Software Companion Development | Enables predictive voiding dysfunction modeling through machine learning cystoscopic integration. |
| Reimbursement Strategy | Navigates asymmetric coverage between antimuscarinics and neuromodulation in Germany and Japan. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EMA MDR conformity assessments, and PMDA approval trajectories anchored the trend analysis, supplemented by interviews with urodynamics technologists, interventional urology nurse specialists, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segmentation modeling triangulated against top-down epidemiological prevalence estimates.
The input-output matrix mapped patient population segments, therapy modality preferences, site-of-care shifts, and regional regulatory clusters to derive volume and value estimates across the projection horizon. Segmentation dimensions included product type, therapy area, end user, and distribution channel, with additional modeling of health technology assessment pathways and reimbursement parity evolution. CAGRs were computed from fitted growth curves calibrated to historical approval-to-adoption lags. Forecast inputs incorporated neuromodulation procedure migration rates and AI diagnostic penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for percutaneous tibial nerve stimulation versus sacral nerve stimulation would alter the outlook. Forecasts reflect assumptions about regulatory pathway efficiency, supply chain continuity, and reimbursement policy evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Tonsil Cancer Market