
 Mitochondrial Disorders Treatment Market | 2026-2036
Mitochondrial Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mitochondrial Disorders Treatment Market Insights
The FDA orphan drug designation framework is broadening the cost-of-entry calculus for developers of mitochondrial therapies, lowering clinical trial barriers and extending market exclusivity windows for qualified candidates. PTC Therapeutics leverages its regulatory expertise across rare disease categories to sustain pipeline momentum in mitochondrial indications. BioMarin Pharmaceutical Inc. anchors its position through deep manufacturing scale in enzyme-based modalities. Stealth BioTherapeutics specializes in small-molecule mitochondrial-targeted compounds, competing on mechanism specificity rather than platform breadth.
Mitochondrial disorders treatment encompasses therapeutic interventions designed to restore, replace, or compensate for dysfunctional mitochondrial function arising from genetic mutations in nuclear or mitochondrial DNA. These interventions span biologics, small molecules, and genetic constructs administered to modify disease progression or alleviate multi-system symptoms affecting energy-intensive organs. Genetic therapy commands the deepest R&D investment pools as vector delivery technologies mature, while symptomatic treatment retains the largest installed revenue base due to its immediate addressability across undiagnosed populations. Enzyme replacement therapy occupies a narrower but defensible niche where specific mitochondrial enzyme deficiencies have been biochemically characterized.
The FDA, EMA, and national health technology assessment bodies across Germany, France, and the United Kingdom collectively shape market access through divergent evidentiary standards for rare disease therapies, creating a fragmented reimbursement landscape that demands geographic-specific clinical strategies. The EU AI Act and GDPR impose additional constraints on algorithm-driven patient identification tools that manufacturers increasingly deploy to locate eligible subjects for ultra-rare mitochondrial trials. Stakeholders must monitor evolving payer evidence requirements and vector manufacturing capacity constraints as determinants of which therapeutic modalities achieve scalable commercial traction.
Market Dynamics
Vector manufacturing capacity constraints are compressing clinical trial timelines for gene-based mitochondrial therapies, forcing developers to secure GMP-compliant production slots years before regulatory submission. This supply bottleneck is reshaping competitive positioning toward those with captive manufacturing assets or long-term CDMO partnerships.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits covering 50% of clinical trial costs and seven-year market exclusivity accelerate rare disease program viability for mitochondrial indications.
- Next-generation sequencing:Expanded newborn screening panels in academic medical centers are shortening diagnostic odysseys from years to months.
- Pediatric hospital networks:Specialized mitochondrial clinics at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center concentrate treatment-ready patient populations.
Market Restraints
- Plasmid DNA scarcity:Limited GMP-grade plasmid suppliers in North America create single-source dependencies for AAV vector production.
- EMA evidence thresholds:Divergent health technology assessment requirements across Germany, France, and the United Kingdom fragment reimbursement pathways.
- Small-molecule substitution:Generic metabolic supplements compete on price against novel mitochondrial-targeted compounds in symptomatic care.
Strategic Opportunities
- Undiagnosed populations in India:Rising genetic testing penetration in tier-1 cities creates first-mover advantage for patient identification platforms.
- AAV capsid engineering:Tissue-specific targeting technologies reduce immunogenicity and enable repeat dosing.
- Digital therapeutics integration:Remote patient monitoring tools capture real-world evidence for payer negotiations.
Industry Challenges
- Gene therapy manufacturing talent:Shortage of GMP bioprocessing specialists with viral vector experience extends facility qualification timelines.
- Multi-system endpoint validation:Lack of standardized outcome measures across neurologic, cardiac, and metabolic manifestations complicates trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitochondrial Disorders Treatment Market |
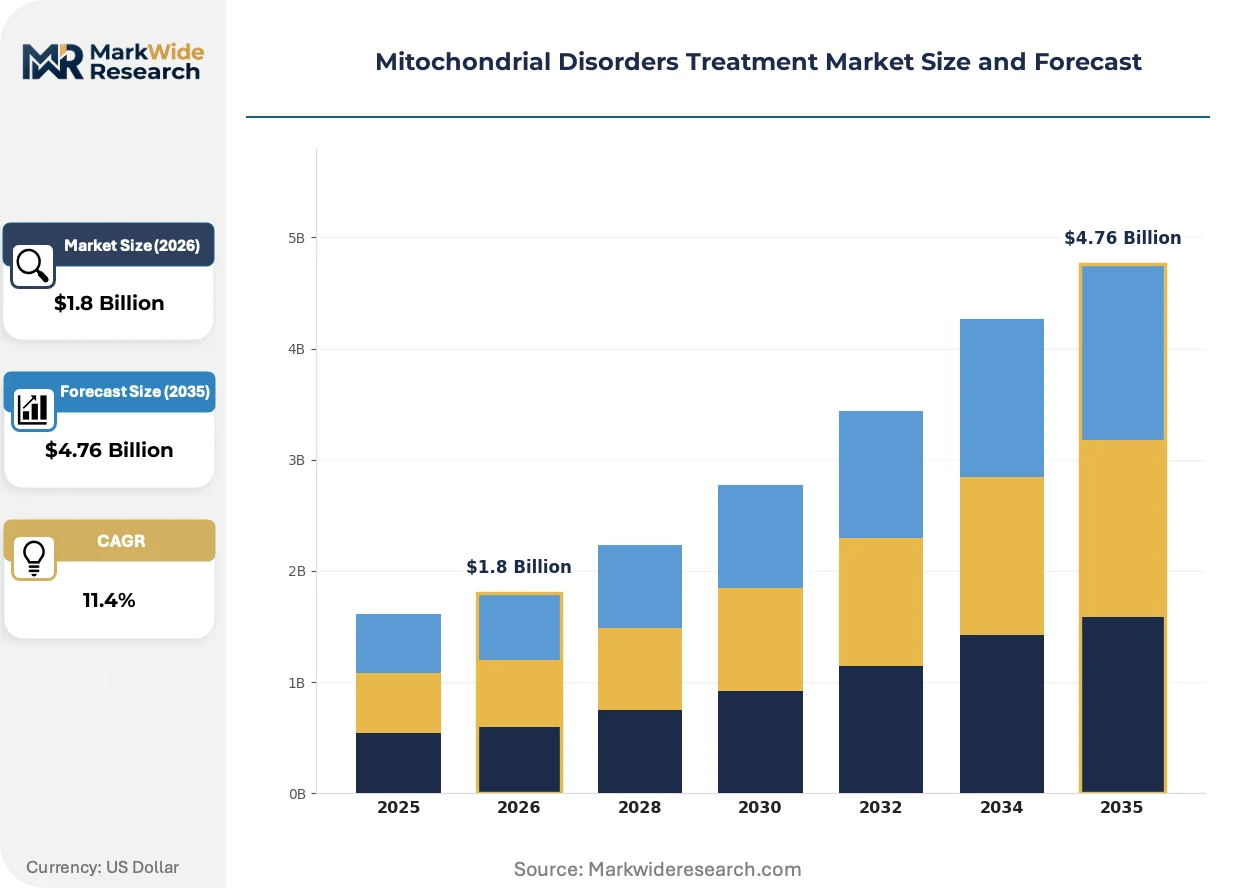
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Genetic Therapy, Enzyme Replacement Therapy, Symptomatic Treatment, Antioxidant Therapy Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Patient Age Group: Pediatric, Adolescent, Adult, Geriatric End User: Hospitals, Clinics, Homecare, Specialty Centers |
| Companies Covered | PTC Therapeutics, BioMarin Pharmaceutical Inc., Ultragenyx Pharmaceutical Inc., Novartis AG, Horizon Therapeutics, Sarepta Therapeutics, Sanofi Genzyme, Pfizer Inc., Stealth BioTherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitochondrial Disorders Treatment Market Trends and Innovations
Gene therapy delivery technologies are advancing faster than regulatory frameworks can adapt, creating temporary competitive windows for first movers with established manufacturing relationships. The convergence of synthetic biology and precision medicine is opening new therapeutic modalities previously considered inaccessible for mitochondrial disorders.
Base editing technologies are expanding into mitochondrial DNA correction, offering permanent single-nucleotide fixes without double-strand breaks that trigger cellular stress responses. Academic medical centers in the United States and United Kingdom are establishing dedicated manufacturing suites to accelerate IND-enabling studies. This capability compression is collapsing the traditional gap between discovery and clinical proof-of-concept.
The EU AI Act imposes algorithmic transparency requirements on patient identification tools that manufacturers deploy to locate eligible subjects for ultra-rare trials. Compliance costs are diverting R&D investment toward explainable AI architectures. Small-cap developers with limited regulatory affairs bandwidth are partnering with specialized consultancies to navigate conformity assessment procedures.
Hospital procurement committees are consolidating vendor relationships for high-cost rare disease therapies, favoring integrated service packages over standalone product contracts. This concentration is displacing traditional specialty pharmacy distribution in favor of direct-to-hospital logistics with embedded clinical support. The shift is most visible in United States academic medical centers managing complex mitochondrial patient cohorts.
Mitochondrial Disorders Treatment Market Segmentation
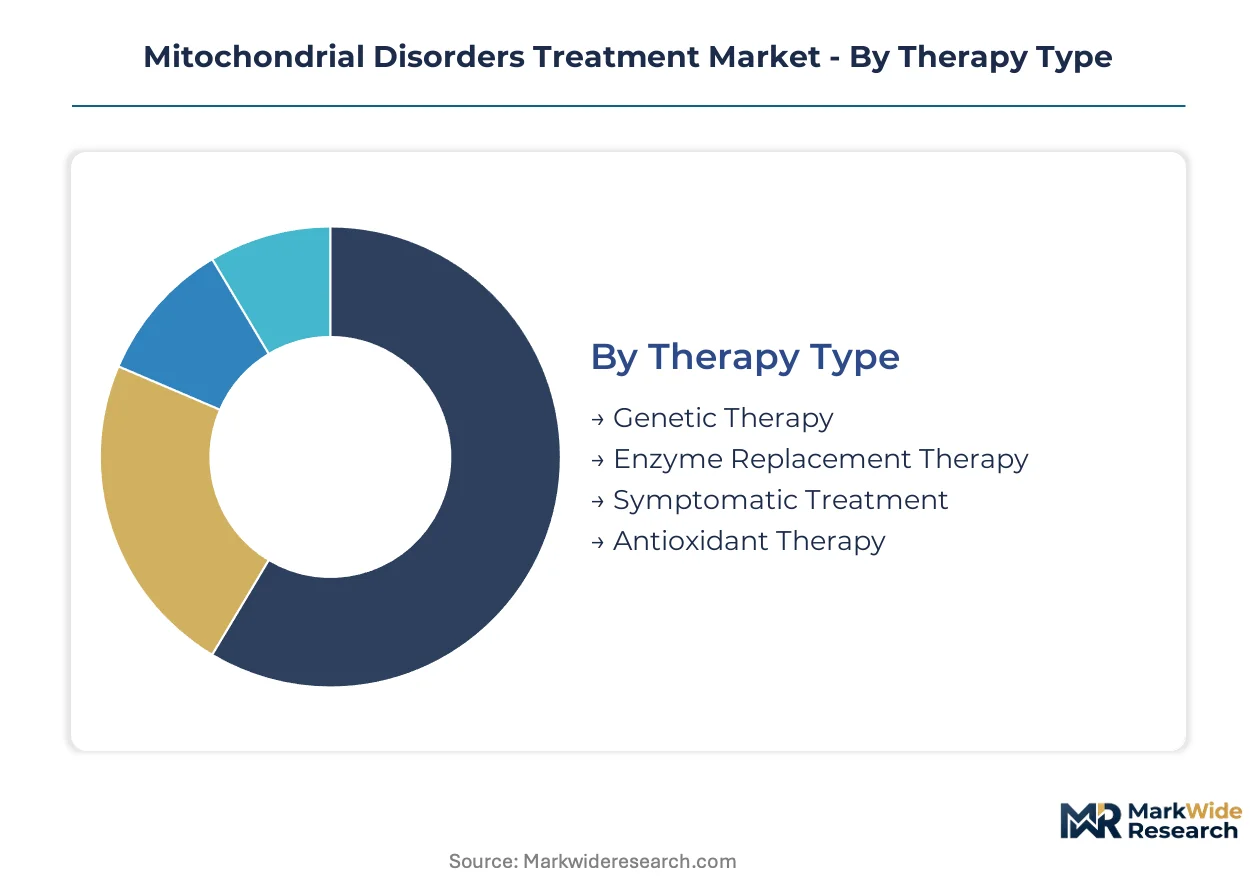
Mitochondrial disorders span heterogeneous genetic etiologies and organ system manifestations, requiring therapeutic approaches calibrated to disease mechanism, patient physiology, and care setting infrastructure. Segmentation reveals where R&D investment concentrates versus where commercial revenue currently flows.
Therapy Type:
Cost tier separates curative intent from chronic management, with gene therapy commanding premium pricing against symptomatic alternatives.
- Genetic Therapy:Adeno-associated viral vectors deliver functional mitochondrial DNA or nuclear-encoded mitochondrial proteins directly to affected tissues. Academic medical centers in the United States anchor early-phase demand as Boston Children's Hospital and Cincinnati Children's Hospital Medical Center establish dedicated manufacturing suites for IND-enabling studies.
- Symptomatic Treatment:Metabolic supplements, cofactor replacement, and organ-specific interventions manage multi-system manifestations without altering disease trajectory. Generic metabolic supplements compete aggressively on price, compressing margin for novel mitochondrial-targeted compounds in undiagnosed populations.
- Enzyme Replacement Therapy:Recombinant enzymes address specific mitochondrial enzyme deficiencies with biochemically characterized substrates.
- Antioxidant Therapy:Small-molecule scavengers target oxidative stress downstream of electron transport chain dysfunction.
Volume sits with Symptomatic Treatment; growth tilts toward Genetic Therapy.
Administration Route:
Patient compliance and care setting capacity dictate route selection, with hospital-based infusion competing against home-administered oral regimens.
- Intravenous:Enables direct systemic delivery of biologics and gene therapy vectors with controlled pharmacokinetics. United States pediatric hospital networks concentrate demand as specialized mitochondrial clinics manage complex infusion protocols for rare disease cohorts.
- Oral:Small-molecule mitochondrial-targeted compounds and metabolic supplements allow chronic outpatient management. Homecare settings in Germany and France absorb volume as reimbursement pathways for rare disease oral therapies stabilize under national health technology assessment frameworks.
- Subcutaneous:Offers intermediate convenience for enzyme replacement and selected biologics.
- Intramuscular:Localized delivery for tissue-specific mitochondrial myopathies with limited systemic exposure.
Oral administration captures the largest patient volume; intravenous routes are expanding most quickly alongside gene therapy pipeline maturation.
Patient Age Group:
Disease onset timing and organ system plasticity create distinct therapeutic windows across developmental stages.
- Pediatric:Early-onset mitochondrial disorders present with catastrophic energy failure in neurologic, cardiac, and hepatic systems. Expanded newborn screening panels at academic medical centers in the United States are shortening diagnostic odysseys from years to months, concentrating treatment-ready populations.
- Adult:Later-onset presentations with progressive myopathy, neuropathy, or neurodegeneration require chronic management protocols. The United Kingdom's National Health Service specialist mitochondrial centers manage adult transition from pediatric services with coordinated multi-system care.
- Adolescent:Represents a critical transition window for therapy optimization before irreversible organ damage.
- Geriatric:Age-related mitochondrial dysfunction overlaps with primary mitochondrial disease, complicating differential diagnosis.
Pediatric segments dominate current clinical trial enrollment; adult populations offer the steepest expansion trajectory as diagnostic awareness penetrates primary care.
End User:
Care complexity and therapy cost determine whether treatment localizes in academic centers or disperses to community settings.
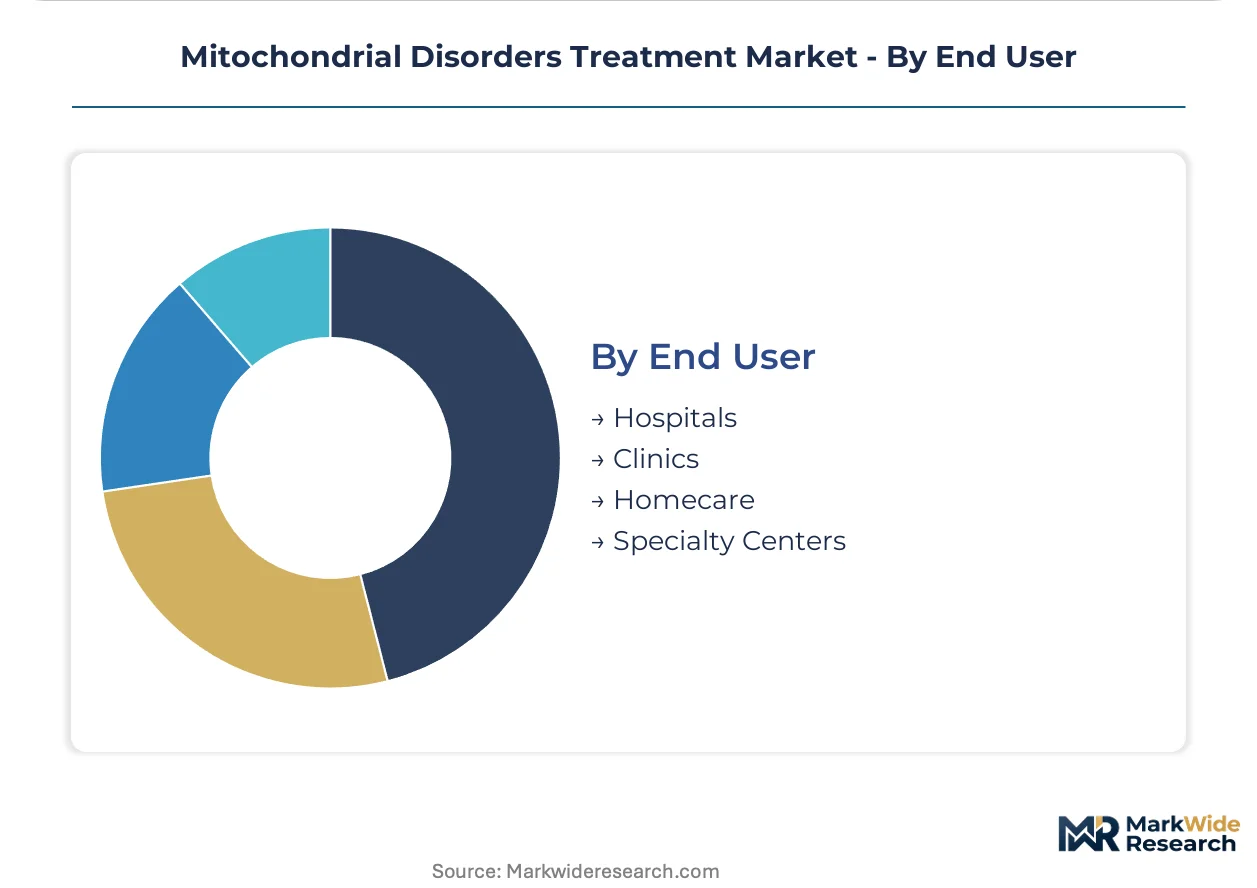
- Hospitals:Academic medical centers with dedicated mitochondrial clinics manage gene therapy administration, multi-system monitoring, and emergency interventions for metabolic decompensation. Hospital procurement committees in the United States are consolidating vendor relationships for high-cost rare disease therapies, favoring integrated service packages.
- Specialty Centers:Concentrated expertise in neuromuscular and metabolic disease enables protocolized care for complex phenotypes. France's national network of reference centers for rare diseases coordinates cross-border patient flows under European Union rare disease frameworks.
- Clinics:Community-based management for stable patients on established symptomatic regimens.
- Homecare:Oral therapy administration and remote patient monitoring tools capture real-world evidence for payer negotiations.
Hospitals anchor revenue concentration today; specialty centers are gaining share fastest as regional hub models prove economically sustainable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in the United States channel capital toward rare disease biomanufacturing, while European Union cohesion funds accelerate mitochondrial research infrastructure in member states with established genetic medicine clusters.
United States
Academic medical centers in Boston and Cincinnati anchor specialized mitochondrial clinic networks. FDA orphan drug tax credits covering half of clinical trial costs accelerate program viability. Boston Children's Hospital and Cincinnati Children's Hospital Medical Center concentrate treatment-ready pediatric populations through expanded newborn screening.
Germany
Reference centers for rare diseases coordinate cross-border patient flows under European Union frameworks. The country's national pharmaceutical regulator enforces divergent health technology assessment requirements that fragment reimbursement pathways. Munich and Heidelberg host concentrated expertise in neuromuscular and metabolic disease management.
United Kingdom
National Health Service specialist mitochondrial centers manage adult transition from pediatric services with coordinated multi-system care. The Medicines and Healthcare products Regulatory Agency shapes market access through evidentiary standards for rare disease therapies. London and Oxford academic medical centers establish dedicated manufacturing suites for IND-enabling studies.
France
National networks of reference centers for rare diseases enable protocolized care for complex phenotypes. The French national pharmaceutical regulator coordinates with health technology assessment bodies to determine coverage eligibility. Paris-based academic hospitals absorb volume as reimbursement pathways for rare disease therapies stabilize.
India
Rising genetic testing penetration in tier-1 cities creates first-mover advantage for patient identification platforms. The Central Drugs Standard Control Organization regulates clinical trial conduct and marketing authorization for investigational therapies. Mumbai and Bangalore medical centers expand newborn screening capabilities to shorten diagnostic odysseys.
Mitochondrial Disorders Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the mitochondrial disorders treatment landscape. The market structure tilts toward consolidation as hospital procurement committees favor integrated service packages over standalone contracts. Three archetypes dominate: platform-agnostic rare disease developers, mechanism-specific small-molecule specialists, and gene therapy vector manufacturers. Competitive moves center on strategic partnerships for GMP-compliant production slots and geographic expansion into undiagnosed populations.
Among rare disease-focused developers, PTC Therapeutics and BioMarin Pharmaceutical Inc. exemplify distinct strategic postures. PTC Therapeutics occupies a position leveraging regulatory expertise across multiple rare disease categories to sustain pipeline momentum. BioMarin Pharmaceutical Inc. anchors the enzyme replacement archetype through manufacturing scale in biologics modalities. Stealth BioTherapeutics represents the small-molecule specialist tier, competing on mechanism specificity rather than platform breadth.
| Leading Market Players |
|---|
| PTC Therapeutics |
| BioMarin Pharmaceutical Inc. |
| Ultragenyx Pharmaceutical Inc. |
| Novartis AG |
| Horizon Therapeutics |
| Sarepta Therapeutics |
| Sanofi Genzyme |
| Pfizer Inc. |
| Stealth BioTherapeutics |
| Others |
Pricing and Supply Chain Analysis
GMP bioprocessing specialists with viral vector experience cluster in the United States and United Kingdom, where labor-cost differentials between Boston-Cambridge and emerging European hubs widen pricing-tier spreads for gene therapy manufacturing services.
Pricing Analysis
Lead-time-driven pricing premiums attach to GMP-compliant AAV vector production slots secured under 18-month windows, while spot inventory of plasmid DNA trades at discounts due to quality variability. Three-tier pricing structure across premium, standard, and economy levels separates validated cGMP batches from research-grade materials and uncharacterized residuals. Price differentiation rests on FDA master file status and EMA certification grade. Pricing pressure stems from generic metabolic supplements competing against novel mitochondrial-targeted compounds in symptomatic care. Pediatric hospitals exhibit lowest price sensitivity due to orphan drug reimbursement guarantees; community clinics face highest sensitivity where metabolic supplements dominate.
Supply Chain Analysis
Single-source vulnerability sits with North American plasmid DNA suppliers, where limited GMP-grade producers create dependency bottlenecks for AAV vector manufacturing. Geographic supply concentration centers on the United States, Germany, and Switzerland for viral vector production; China and India for metabolic supplement APIs. Raw material dependencies include HEK293 cell lines, transfection reagents, and synthetic DNA templates. Supply chain risk manifests as regulatory restriction exposure from EU AI Act algorithmic transparency requirements on patient identification tools. Distribution runs through direct-to-hospital logistics with embedded clinical support, displacing traditional specialty pharmacy channels in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mitochondrial disorders treatment market occupies a technology-transition phase where base editing platforms displace conventional gene therapy vectors for permanent mitochondrial DNA correction without double-strand breaks.
For Market Incumbents: Deploy captive manufacturing assets to secure GMP-compliant production slots years ahead of regulatory submission, insulating against CDMO capacity compression. Acquire specialized consultancies with EU AI Act conformity assessment bandwidth to navigate algorithmic transparency requirements on patient identification tools. Threat substitution emerges from small-molecule mitochondrial-targeted compounds competing on mechanism specificity against platform breadth. For New Entrants and Emerging Players: Begin with undiagnosed populations in India's tier-1 cities, where rising genetic testing penetration creates first-mover advantage for patient identification platforms before established players consolidate. Target adult transition services from pediatric care as diagnostic awareness penetrates primary care. Go-to-market angle centers on remote patient monitoring tools capturing real-world evidence for payer negotiations in European national health technology assessment frameworks. For Investors and Strategic Acquirers: Re-rating potential sits with small-cap developers possessing explainable AI architectures for patient identification, given EU AI Act compliance costs diverting R&D investment toward algorithmic transparency. Long-term viability favors platform-agnostic rare disease developers with established manufacturing relationships over mechanism-specific specialists. Signal to watch: hospital procurement committee consolidation favoring integrated service packages over standalone product contracts.| Strategic Initiative | Industry Significance |
|---|---|
| AAV Capsid Engineering Partnership | Tissue-specific targeting technologies reduce immunogenicity and enable repeat dosing in pediatric populations. |
| EU AI Act Compliance Investment | Algorithmic transparency requirements on patient identification tools demand explainable AI architecture redirection. |
| Academic Medical Center Manufacturing Suite | Dedicated GMP facilities at Boston Children's Hospital and Cincinnati Children's compress IND-enabling timelines. |
| Digital Therapeutics Integration | Remote patient monitoring tools capture real-world evidence for German and French payer negotiations. |
| Indian Patient Identification Platform | Genetic testing penetration in Mumbai and Bangalore creates first-mover advantage in undiagnosed populations. |
Research Methodology
Independent corroboration across regulatory filings, clinical trial registries, and hospital procurement databases underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA orphan drug designations, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up patient population estimates and top-down market size triangulation cross-validate segmentation outputs.
Rate-of-change decomposition across therapy type, administration route, patient age group, and end-user setting structures the analytical framework over the projection horizon. Segmentation dimensions modeled include treatment mechanism, care setting infrastructure, and regional regulatory cluster. CAGRs derive from patient population growth, diagnostic penetration curves, and reimbursement pathway maturation. Industry-specific forecast inputs encompass vector manufacturing capacity expansion timelines and health technology assessment body evidentiary standard evolution.
Underlying measurement precision varies by segment; genetic therapy carries tighter precision than symptomatic treatment due to visible pipeline maturation and disclosed manufacturing partnerships. Forecasts reflect assumptions regarding FDA orphan drug incentive continuity, EMA evidence threshold stability, and plasmid DNA supply diversification. Specific risks that could revise projections include tariff exposure on imported cell culture media, sudden EMA evidence threshold elevation, and AI Act enforcement intensity variation across member states. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Metabolic Disorders Therapeutics Market