
 Asia-Pacific Uninterruptible Power Supply (UPS) Market | 2026-2036
Asia-Pacific Uninterruptible Power Supply (UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Uninterruptible Power Supply (UPS) Market Outlook
Project finance for hyperscale data center developments is tilting procurement power toward asset-light operators that lease rather than own UPS infrastructure. Schneider Electric SE leverages its integrated power distribution portfolio to bundle UPS systems with switchgear and software contracts across Australian mining camps. Eaton Corporation PLC anchors its position through service-centric revenue models that extend hardware lifecycles in India's telecom tower networks. Huawei Technologies Co Ltd competes aggressively on modular architectures that reduce footprint in space-constrained Singapore facilities.
An uninterruptible power supply is an electrical apparatus that provides emergency power through stored battery energy when mains input fails, with online double-conversion systems achieving output voltage regulation within two percent deviation. Industrial buyers deploy these systems to eliminate downtime costs in continuous-process manufacturing where even millisecond interruptions corrupt semiconductor wafer production. Online topology dominates enterprise procurement for data center applications where zero transfer time protects server racks from voltage sags. Modular technology represents the fastest-expanding architecture as facility operators scale capacity in incremental kilowatt blocks rather than oversized monolithic installations. Healthcare facilities sustain steady replacement demand for line-interactive units that balance cost against protection needs for imaging equipment and patient monitoring systems.
China's MIIT enforces GB/T 7260 efficiency standards that disqualify legacy transformer-based designs from government procurement tenders, compressing margins for non-compliant imports. India's CEA mandates power quality norms for grid-connected critical infrastructure that accelerate three-phase online UPS adoption across Mumbai and Bangalore financial districts. Japan's METI promotes JIS-compliant lithium-ion battery integration that displaces valve-regulated lead-acid chemistries in earthquake-prone installations. Stakeholders must monitor how BIS certification timelines and evolving GB standards reshape supplier qualification thresholds before committing to regional manufacturing partnerships.
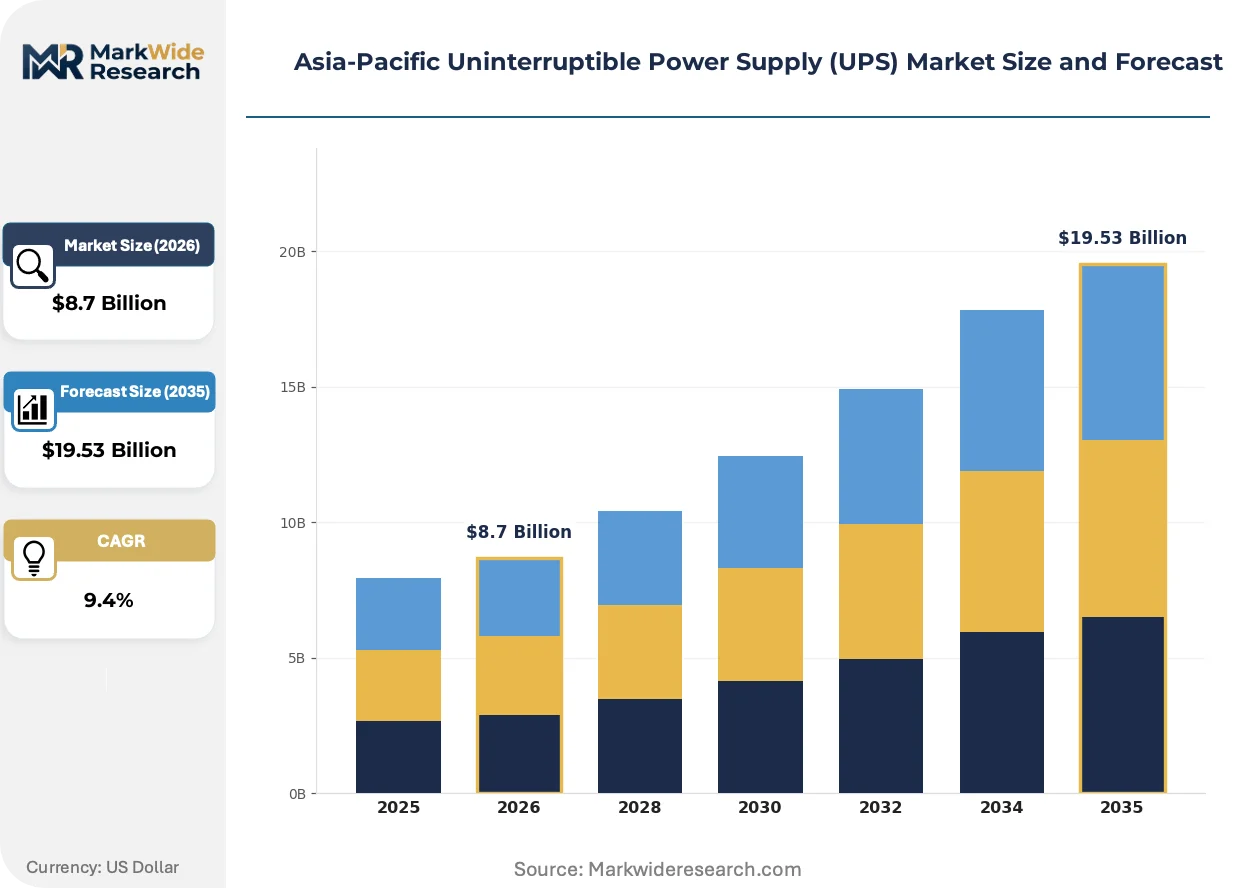
Market Dynamics
Data center operators across Southeast Asia are compressing UPS procurement cycles as cloud infrastructure expansion accelerates, forcing suppliers to reconfigure service networks around hyperscale deployment timelines rather than traditional enterprise replacement schedules.
Growth Catalysts
- Cloud Infrastructure Buildout:Hyperscale data center investments in Singapore and Sydney are pulling three-phase online UPS systems into multi-megawatt configurations. Facility operators prioritize zero-transfer-time architectures to protect server racks from grid instability.
- MIIT Efficiency Mandates:China's GB/T 7260 standards disqualify transformer-based designs from government tenders, creating replacement demand for high-frequency IGBT units across state-owned manufacturing facilities.
- Semiconductor Fab Expansion:Wafer production facilities in South Korea and Taiwan require mission-critical power protection where millisecond interruptions corrupt batch yields, driving procurement of modular scalable architectures.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in China's Fujian and Jiangsu provinces, exposing non-Chinese UPS assemblers to raw material allocation risk during export quota periods.
- BIS Certification Timelines:India's Bureau of Indian Standards testing backlog extends product qualification by four to six months, delaying market entry for imported units during peak infrastructure bidding windows.
- Valve-Regulated Lead-Acid Stranding:Legacy VRLA battery installations face accelerated depreciation as METI-promoted lithium-ion chemistries displace established maintenance contracts in Japanese earthquake-prone zones.
Strategic Opportunities
- Vietnam Manufacturing Corridor:Northern industrial zones around Hai Phong and Bac Ninh lack mature critical power infrastructure, creating first-mover advantage for modular UPS deployments in electronics assembly.
- Healthcare Electrification:India's tier-two cities are expanding diagnostic imaging capacity where line-interactive UPS units balance cost against protection needs for MRI and CT equipment.
- Grid-Connected Storage Convergence:Hybrid UPS-battery systems that participate in frequency regulation markets are penetrating Australian commercial installations where AEMO market rules reward fast frequency response.
Industry Challenges
- Power Electronics Talent Scarcity:Design engineers proficient in wide-bandgap semiconductor applications for high-frequency conversion remain concentrated in Shenzhen and Taipei, constraining R&D expansion elsewhere.
- Legacy Integration Complexity:Retrofitting static transfer switches into existing data center bus architectures requires customized engineering that extends project timelines and erodes margin on competitive tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Uninterruptible Power Supply (UPS) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standby, Line-Interactive, Online, Ferroresonant Application: IT, Telecommunications, Industrial, Healthcare Technology: Double Conversion, Delta Conversion, Flywheel, Modular End User: Data Centers, Healthcare Facilities, Manufacturing Plants, Retail Stores |
| Companies Covered | Eaton Corporation PLC, Mitsubishi Electric Corporation, Schneider Electric SE, Huawei Technologies Co Ltd, Toshiba Corporation, ABB Ltd, Fuji Electric Co Ltd, Kehua Data Co Ltd, Delta Electronics Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Uninterruptible Power Supply (UPS) Market Strategic Shifts
Silicon carbide power semiconductors are compressing converter footprints while liquid cooling architectures address thermal density limits in tropical deployments. These shifts are reshaping supplier R&D priorities and facility engineering specifications simultaneously.
Wide-bandgap semiconductor deployment is migrating from aerospace and military applications into commercial UPS designs. Data center operators in Singapore and Hong Kong are specifying silicon carbide-based rectifiers to reduce converter losses below three percent. This technology is migrating from niche high-reliability segments toward mainstream enterprise procurement, forcing incumbent suppliers to redesign core platforms or cede premium positioning.
India's CEA power quality mandates for grid-connected critical infrastructure are accelerating three-phase online UPS adoption across Mumbai and Bangalore financial districts. The regulations impose harmonic distortion limits that disqualify line-interactive topologies from new installations. Banking and securities exchange operators are responding by consolidating procurement specifications around IEC 62040-3 Class 1 compliance, compressing supplier qualification pools.
Asset-light leasing structures are displacing capital purchase models in Australian and Japanese hyperscale deployments. Colocation operators are bundling UPS infrastructure into power-as-a-service contracts that transfer operational risk to equipment vendors. This pattern is most visible in Sydney and Osaka markets where project finance for speculative data center builds requires off-balance-sheet treatment for mechanical and electrical plant.
Asia-Pacific Uninterruptible Power Supply (UPS) Market Segmentation
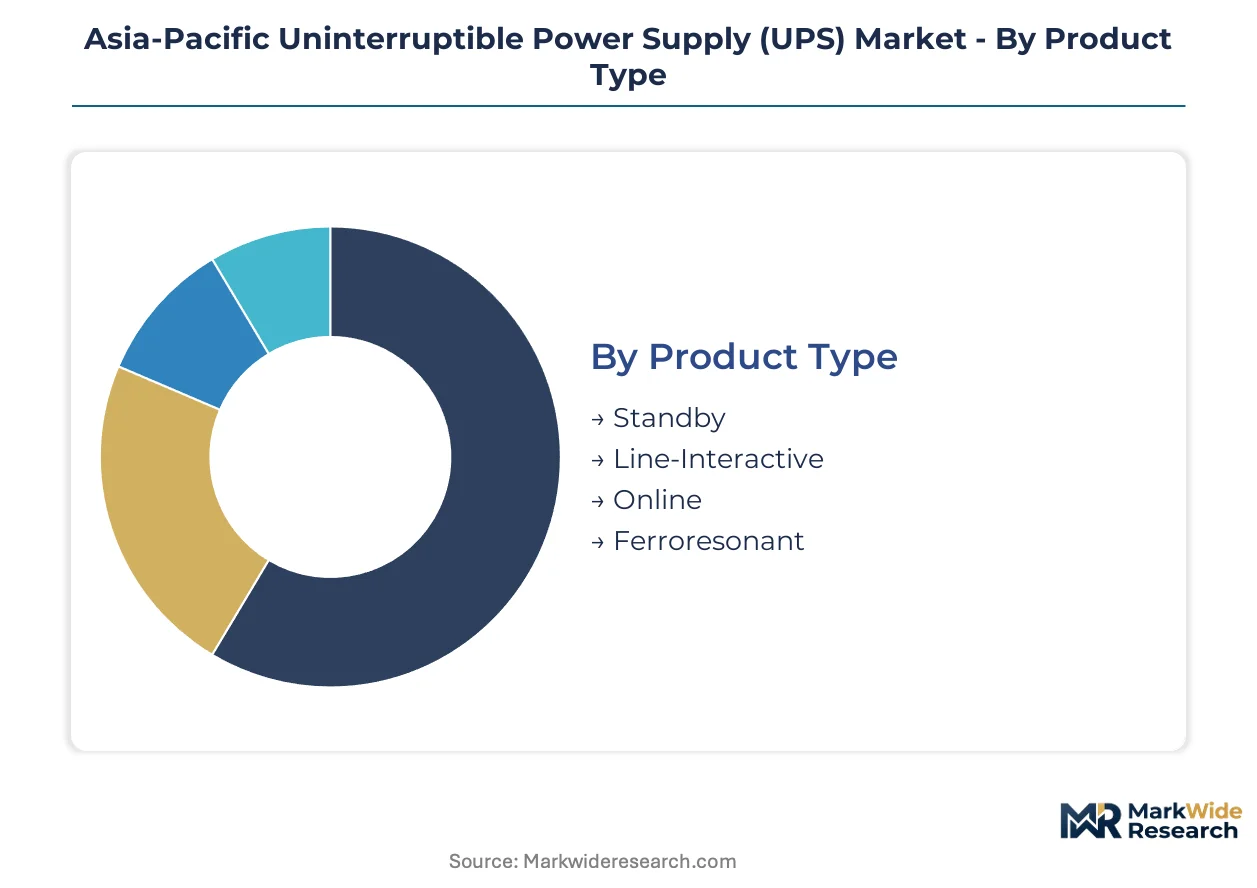
UPS procurement patterns across Asia-Pacific diverge sharply by power quality requirements and facility criticality. Buyers segment investments across topology sophistication, deployment scale, and operational risk tolerance rather than uniform capacity expansion.
Product Type:
Topology selection tracks cost sensitivity against power quality mandates, with procurement committees weighing initial capital outlay against lifecycle protection value.
- Standby:Basic offline designs engage battery backup only during complete grid failure, offering minimal conditioning for voltage fluctuations. Small retail outlets in India's tier-three cities deploy these units for point-of-sale terminals where brief transfer delays pose acceptable risk. BIS certification costs compress margins on entry-level imports.
- Line-Interactive:Buck-boost transformers regulate voltage sags without full conversion, balancing protection against acquisition cost. Healthcare imaging departments in Vietnam's provincial hospitals specify these for MRI suites where moderate conditioning suffices. METI efficiency guidelines in Japan are accelerating displacement toward lithium-ion compatible platforms.
- Online:Double-conversion architectures isolate loads from all grid anomalies through continuous AC-DC-AC transformation. Semiconductor fabs in Hsinchu and Pyeongtaek mandate these topologies where sub-cycle interruptions destroy wafer batches. MIIT GB/T 7260 standards now disqualify transformer-based variants from state procurement.
- Ferroresonant:Saturable transformer designs deliver inherent voltage regulation through magnetic flux limiting. Legacy industrial installations in Australia's Pilbara mining belt retain these for conveyor motor protection where harmonic tolerance is built into mechanical loads.
Online systems command the established base in mission-critical deployments. The steepest expansion runs through line-interactive units as healthcare electrification penetrates secondary cities.
Application:
End-use verticals impose distinct duty cycle profiles, thermal constraints, and redundancy architectures that reshape equipment specifications.
- IT:Server rack protection demands zero-transfer-time architectures with hot-swappable module designs. Hyperscale facilities in Singapore's Tuas data center cluster are consolidating procurement around IEC 62040-3 Class 1 compliance. Cloud operators compress deployment timelines from 18-month enterprise cycles to 6-month hyperscale sprints.
- Telecommunications:Base station continuity requires outdoor-rated enclosures with wide temperature operating ranges. India's tower infrastructure operators are shifting from capital purchase to power-as-a-service contracts that bundle battery replacement liability. TRAI mandates on network uptime are tightening procurement specifications.
- Industrial:Motor drive protection and process control continuity dominate specifications across continuous manufacturing. Battery gigafactories in China's Jiangsu corridor are specifying modular scalable architectures that track production line expansion. CEA power quality norms are accelerating three-phase online adoption.
- Healthcare:Patient safety systems and diagnostic imaging impose isolation requirements with leakage current limits below 500 microamps. Tier-two Indian cities expanding CT capacity are driving procurement of line-interactive units with medical-grade isolation transformers. CDSCO device regulations are tightening electromagnetic compatibility documentation.
IT applications anchor volume concentration. Healthcare is gaining share fastest as diagnostic infrastructure electrification accelerates across Southeast Asia.
Technology:
Conversion architecture determines efficiency curves, footprint constraints, and scalability boundaries that facility engineers weigh against expansion roadmaps.
- Double Conversion:Continuous AC-DC-AC transformation delivers the tightest voltage regulation with total harmonic distortion below three percent. Data centers in Sydney and Melbourne are specifying silicon carbide rectifier variants to compress converter losses. This architecture dominates where grid instability frequency exceeds 20 events annually.
- Delta Conversion:Partial power processing through delta transformers reduces conversion losses during normal operation. Large industrial campuses in Thailand's Eastern Economic Corridor deploy these for mixed criticality loads where energy efficiency trumps absolute isolation.
- Flywheel:Kinetic energy storage eliminates battery maintenance while providing 15-30 seconds of ride-through for generator startup. Australian frequency regulation markets are rewarding hybrid flywheel-battery installations with fast frequency response payments.
- Modular:Incremental capacity blocks enable right-sized deployment with N+1 redundancy scaling in 50kW increments. Space-constrained Singapore facilities are mandating these architectures where floor loading limits prohibit monolithic transformer-based designs.
Double conversion retains dominance in enterprise specifications. Modular architectures are climbing fastest as colocation operators prioritize deferred capital commitment.
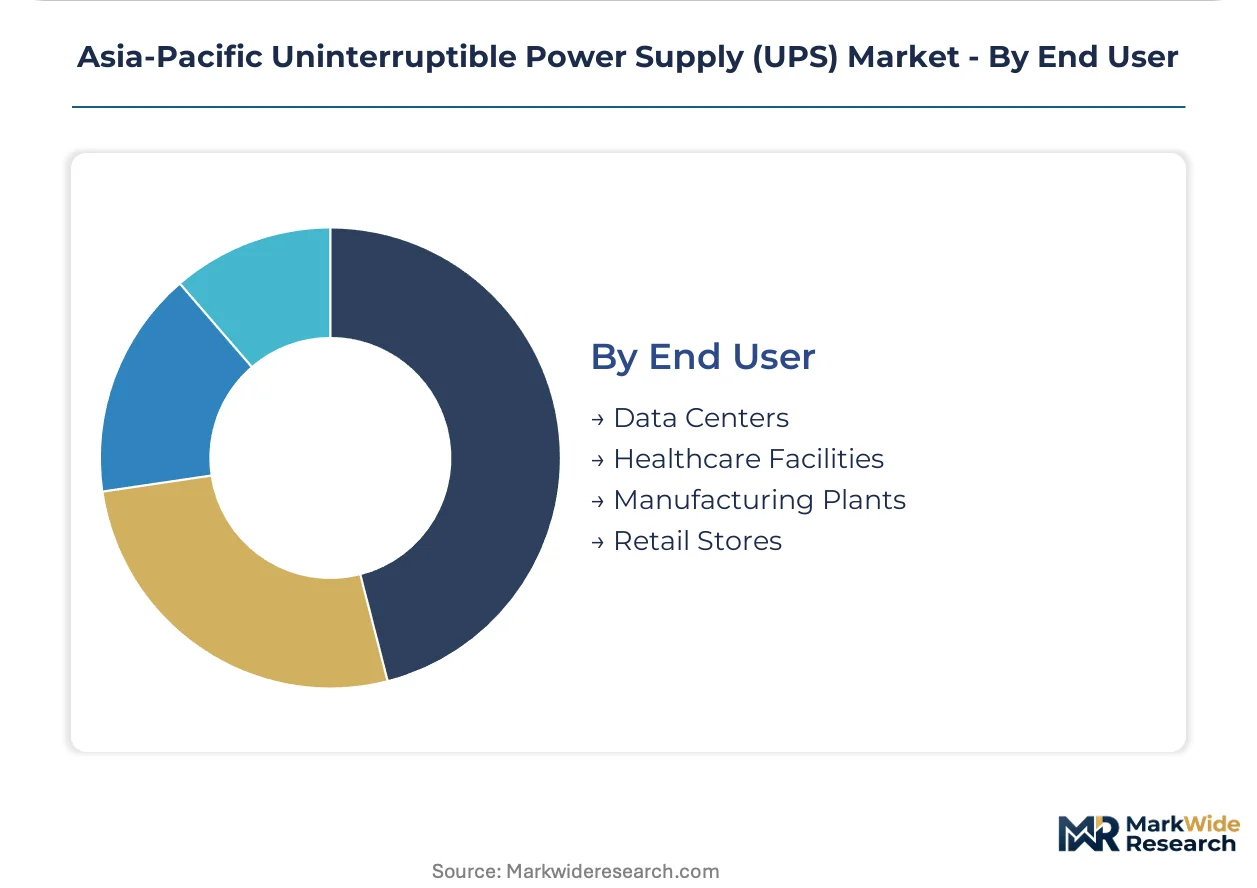
End User:
Facility type dictates redundancy tiering, maintenance access protocols, and lifecycle cost models that procurement committees evaluate.
- Data Centers:Tier III and IV facilities demand concurrently maintainable architectures with 2N or N+1 redundancy. Asset-light operators in Osaka and Sydney are bundling UPS into lease structures that transfer operational risk to vendors. Project finance for speculative builds requires off-balance-sheet treatment.
- Healthcare Facilities:Life safety branches and critical care circuits impose automatic transfer switch integration with generator synchronization. Japan's earthquake-prone zones are accelerating lithium-ion displacement of VRLA chemistries under METI promotion programs.
- Manufacturing Plants:Continuous process industries specify online topologies where millisecond interruptions corrupt batch integrity. Semiconductor fabs in South Korea require mission-critical power protection with mean time between failures exceeding 250,000 hours.
- Retail Stores:Distributed point-of-sale protection favors cost-optimized standby or line-interactive units with 15-30 minute runtime. India's organized retail expansion in Bengaluru and Hyderabad is pulling single-phase units into multi-outlet deployment.
Data centers concentrate the premium tier. Manufacturing plants are expanding most quickly as battery gigafactory and semiconductor fab investments multiply across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT efficiency mandates and CEA power quality regulations are accelerating equipment replacement cycles across the region. Cloud infrastructure investments and semiconductor fab expansions are compressing procurement timelines from traditional enterprise schedules to hyperscale deployment sprints.
China
Semiconductor fabs and battery gigafactories in Jiangsu and Fujian provinces are driving modular UPS procurement for mission-critical power protection. GB/T 7260 standards enforced by MIIT disqualify transformer-based designs from government tenders, forcing replacement of legacy installations. Eastern coastal manufacturing corridors concentrate demand where sub-cycle interruptions would destroy wafer batches.
India
Financial district operators in Mumbai and Bangalore are consolidating procurement around IEC 62040-3 Class 1 compliance following CEA mandates on harmonic distortion limits. BIS certification timelines extend product qualification by four to six months, delaying market entry during peak bidding windows. Tier-two cities expanding CT and MRI capacity are pulling line-interactive units into diagnostic infrastructure.
Japan
Earthquake-prone installations are accelerating lithium-ion displacement of valve-regulated lead-acid chemistries under METI promotion programs. Data center operators in Osaka are bundling UPS infrastructure into power-as-a-service contracts requiring off-balance-sheet treatment. JIS-compliant battery integration is reshaping maintenance contract structures across critical facilities.
South Korea
Wafer production facilities in Pyeongtaek require online double-conversion systems where millisecond interruptions corrupt batch yields. Memory and logic chip manufacturers are specifying mean time between failures exceeding 250,000 hours for continuous-process protection. Government incentives for domestic semiconductor capacity are expanding critical power infrastructure investment.
Australia
Hyperscale developments in Sydney are tilting procurement toward asset-light operators that lease rather than own UPS infrastructure. AEMO market rules rewarding fast frequency response are penetrating commercial installations with hybrid UPS-battery systems. Mining camps in the Pilbara retain legacy ferroresonant designs for conveyor motor protection where harmonic tolerance is built into mechanical loads.
Asia-Pacific Uninterruptible Power Supply (UPS) Market Competitive Environment
On the supply side, the industry is consolidating around integrated power distribution portfolios and service-centric revenue models that extend hardware lifecycles. Tiered competitive positioning separates full-suite electrical infrastructure providers from modular architecture specialists and regional battery-integrated assemblers. Dominant competitive moves include bundling UPS systems with switchgear and software contracts, and reconfiguring service networks around compressed hyperscale deployment timelines.
Within the integrated infrastructure tier, Schneider Electric SE and Eaton Corporation PLC exemplify portfolio breadth across power distribution and critical power protection. Huawei Technologies Co Ltd occupies a position among modular architecture specialists competing aggressively on footprint reduction in space-constrained facilities. Mitsubishi Electric Corporation and Toshiba Corporation anchor the Japan-based industrial electronics segment with established positions in high-reliability applications. Kehua Data Co Ltd represents Chinese-origin specialists in data center power infrastructure, while Delta Electronics Inc exemplifies Taiwan-based power electronics manufacturing scale.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Huawei Technologies Co Ltd |
| Toshiba Corporation |
| ABB Ltd |
| Fuji Electric Co Ltd |
| Kehua Data Co Ltd |
| Delta Electronics Inc |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo freight corridor's container cost dynamics compress margins for non-Chinese UPS assemblers while amplifying price spreads between certified and uncertified units. Battery cell allocation bottlenecks in Fujian and Jiangsu provinces force downstream price differentiation that favors suppliers with captive lithium-ion supply.
Pricing Analysis
Certification level under BIS and GB/T 7260 standards creates the primary spread between qualified and disqualified suppliers. Three-tier pricing structure across IEC 62040-3 Class 1 premium, standard online, and line-interactive economy levels segments procurement committees by risk tolerance. Cost compression in the economy tier intensifies as Indian tier-three retailers prioritize acquisition cost over lifecycle protection. Healthcare facilities in tier-two cities exhibit least price sensitivity where patient safety mandates override capital constraints.
Supply Chain Analysis
Export-control restrictions on wide-bandgap semiconductor fabrication equipment limit silicon carbide wafer flows from US and Japanese suppliers to Chinese converters. Battery cell production concentrates in China, South Korea, and Japan while power electronics talent clusters in Shenzhen and Taipei. Single-source vulnerability in IGBT module supply exposes non-Chinese assemblers to allocation risk during quota periods. Distribution runs through integrated electrical infrastructure providers bundling UPS with switchgear and software contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineers proficient in silicon carbide applications remain concentrated in fewer than five metropolitan clusters, constraining R&D scaling for suppliers outside these zones. This capability scarcity rewards early movers who secure talent pipelines or acquire distressed technical assets.
For Market Incumbents: Insulate service revenue streams by extending hardware lifecycles through predictive maintenance contracts that lock in Indian telecom tower operators. Capture backward integration into lithium-ion battery assembly to reduce exposure to Chinese cell allocation quotas. Deepen certification investments under evolving BIS timelines to disqualify import-dependent competitors from government tenders.
For New Entrants and Emerging Players: Vietnam's northern industrial zones around Hai Phong and Bac Ninh offer white-space deployment opportunities where critical power infrastructure remains immature. Target modular UPS architectures for electronics assembly facilities expanding in these corridors. Pursue power-as-a-service contract structures that transfer operational risk from capital-constrained facility operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming critical power divisions lacking service-centric revenue models. Long-term viability hinges on positioning acquired assets for hybrid UPS-battery systems participating in frequency regulation markets. Monitor AEMO rule modifications and METI lithium-ion promotion programs as inflection indicators for asset valuation recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Rectifier Integration | Reduces converter losses below three percent in Singapore data center specifications. |
| Power-as-a-Service Contract Launch | Transfers operational risk to vendors in Australian and Japanese hyperscale deployments. |
| BIS Certification Fast-Track Investment | Compresses four-to-six month qualification delays for Indian market entry. |
| Modular Architecture Platform Development | Enables right-sized deployment in space-constrained Singapore facilities. |
| Flywheel-Battery Hybrid System Deployment | Captures AEMO fast frequency response payments in Australian commercial installations. |
Study Parameters
Initial hypotheses were tested against primary input from data center engineering directors, electrical infrastructure procurement managers, and power electronics R&D leads and refined through secondary validation. Plant engineers at semiconductor fabs, tower infrastructure operators, and hospital biomedical equipment specialists contributed operational perspective. Customs trade records, MIIT equipment certification databases, CEA power quality filings, and hyperscaler capex disclosures provided quantitative grounding. Bottom-up installation tracking and top-down market sizing were triangulated against regional regulatory filings.
Demand-supply balance modeling across the projection horizon incorporated topology segmentation by conversion architecture, application vertical by criticality tier, and technology by semiconductor material. Power quality mandate enforcement timelines, cloud infrastructure deployment sprints, and battery chemistry transition curves informed growth trajectory calibration. CAGRs were derived from installed base turnover analysis and greenfield capacity absorption rates.
Practitioners should monitor BIS certification backlog fluctuations and GB standards revision schedules for early signals of competitive access shifts. Forecasts reflect assumptions on lithium-ion cell supply continuity and wide-bandgap semiconductor equipment licensing. Material shifts in export-control regime stringency or seismic event frequency in Japanese installation zones would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Thyristor Surge Protectors Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Shunt Capacitor Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
PV Micro Inverters Market
Power Systems
Charge Pumps Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Voltage Regulators Market
Power Systems
EV Power Module Market
Power Systems
Thermal Management Systems Market
Power Systems
Digital Inverter Market
Power Systems
Power Inverter Market
Power Systems
Voltage Stabilizer System Market