
 Aerospace Electrical Inserts Market | 2026-2036
Aerospace Electrical Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Electrical Inserts Market Analysis
High-density signal integration is narrowing the physical footprint required for avionics interconnects in modern cockpit architectures. TE Connectivity leverages its vertical integration in contact metallurgy to sustain qualification pipelines for next-generation platforms. Amphenol Corporation anchors its position through specialized hermetic sealing competencies that dominate military and space-grade applications. Collins Aerospace competes on the strength of its airframe OEM channel control across Boeing and Airbus programs.
Aerospace electrical inserts are precision-engineered electromechanical components—typically nickel-plated copper alloy contacts housed in thermoset composite or high-performance thermoplastic insulators—that establish reliable current and signal pathways between aircraft wiring harnesses and avionics, power distribution, or lighting subsystems. These components must maintain dielectric integrity across temperature excursions from minus 55 degrees Celsius to 175 degrees Celsius while resisting vibration, moisture, and electromagnetic interference in pressurized and unpressurized zones. Connectors command the largest installed base due to their ubiquity across every aircraft system, yet relays represent the fastest-expanding product category as electrified actuation replaces hydraulic control surfaces on new platforms. Avionics applications concentrate the highest value per unit given signal integrity requirements, while power distribution segments generate volume scale through repetitive harness termination points.
FAA airworthiness standards under 14 CFR Part 25, EASA CS-25 certification criteria, and RTCA DO-160 environmental test conditions collectively define the qualification barrier for electrical insert suppliers seeking OEM approval. These frameworks mandate flame resistance, smoke toxicity limits, and electromagnetic compatibility testing that extend product development cycles and concentrate procurement authority with tier-one interconnect houses. Stakeholders must monitor how emerging solid-state power distribution architectures and distributed avionics topologies reshape contact density requirements and qualification protocols for traditional insert form factors.
Market Dynamics
Electrified flight control architectures are compressing hydraulic system footprints across next-generation narrowbody and widebody platforms, forcing electrical insert suppliers to requalify contact densities and thermal management specifications under accelerated OEM timelines.
Growth Catalysts
- More Electric Aircraft mandates:Boeing 787 and Airbus A350 programs drive replacement of pneumatic and hydraulic systems with electromechanical actuation, expanding relay and contactor procurement volumes.
- FAA 14 CFR Part 25 Amendment 25-178:Enhanced fault-tolerant electrical system requirements tighten material specifications for flame resistance and smoke toxicity, filtering out non-compliant suppliers.
- China COMAC C919 production ramp:Final assembly line expansion in Shanghai concentrates demand for MIL-DTL-38999 qualified interconnects among domestic and foreign subsystem integrators.
Market Restraints
- Nickel price volatility:Contact metallurgy depends on stable nickel supply for plating thickness consistency, with LME price swings compressing margin buffers for mid-tier manufacturers.
- Duopoly supply concentration:Boeing and Airbus control 90 percent of large commercial airframe procurement, concentrating pricing power and extending payment terms to Tier 2 connector suppliers.
- Thermoplastic substitution limits:PEEK and PPS insulators face performance ceilings above 200 degrees Celsius, blocking adoption in engine-adjacent high-temperature zones where thermosets retain dominance.
Strategic Opportunities
- Urban air mobility electrification:eVTOL developers in Germany and the United States require miniaturized, lightweight interconnects for distributed propulsion architectures not served by legacy aerospace form factors.
- Solid-state power distribution convergence:Integration of silicon carbide switching with traditional contact technologies enables new product categories replacing electromechanical relays in secondary distribution.
- EU Green Deal sustainable aviation fuel linkage:EASA proposals to weight electrical system efficiency in airworthiness scoring create procurement preference for lower-resistance contact designs.
Industry Challenges
- RTCA DO-160G qualification timelines:Environmental test cycles for temperature, altitude, and electromagnetic interference extend 18-24 months, delaying revenue recognition for platform-specific development programs.
- Legacy 28VDC system integration:New 270VDC and 540VDC architectures must maintain backward compatibility with existing harness termination standards, complicating contact geometry optimization.
- Specialized workforce scarcity:Plating chemistry expertise and hermetic sealing technicians concentrate at retirement-age demographics, constraining capacity expansion at qualified facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Electrical Inserts Market |
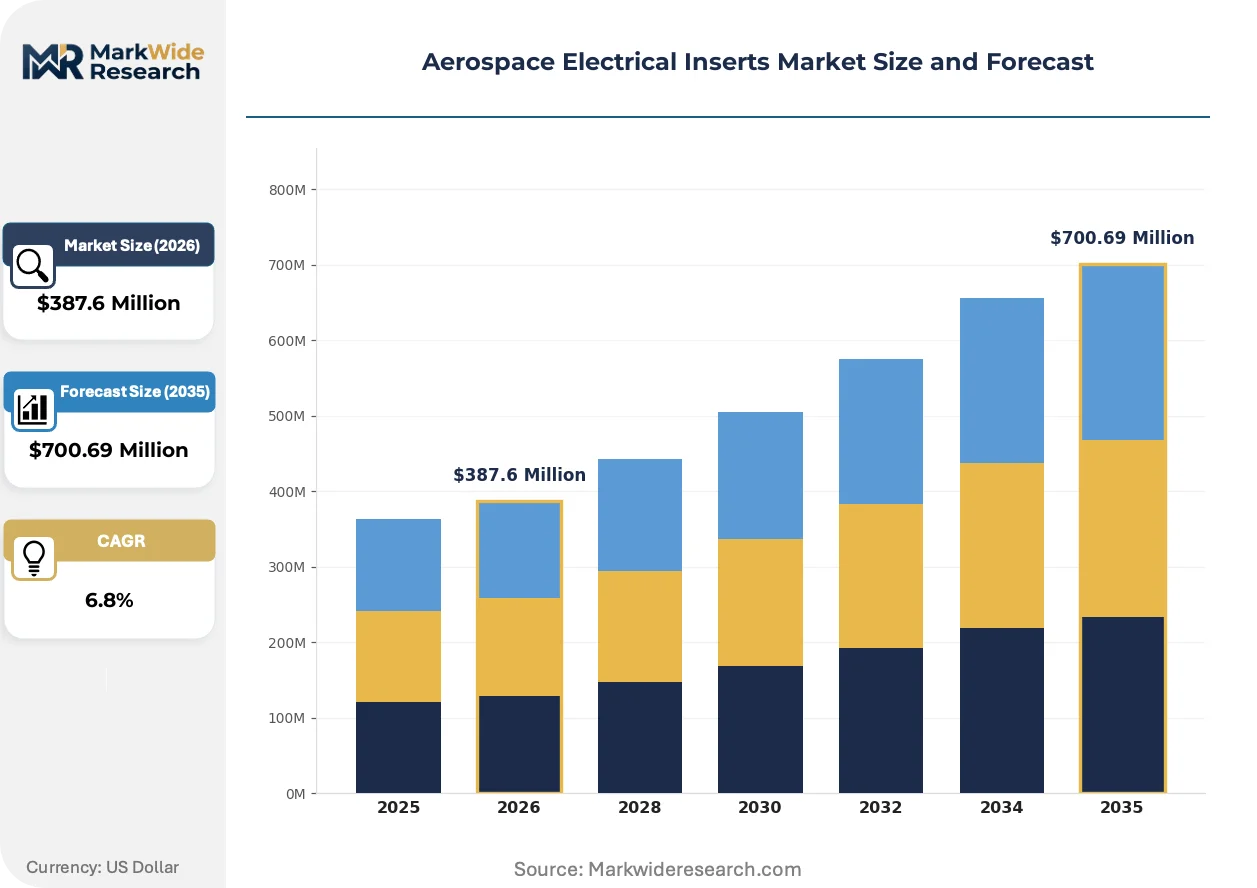
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Switches, Relays, Circuit Breakers Application: Avionics, Power Distribution, Lighting Systems, Communication Systems End User: Commercial Aircraft, Military Aircraft, UAVs, Spacecraft Installation Type: Embedded, Surface-Mounted, Through-Hole, Modular |
| Companies Covered | TE Connectivity, Amphenol Corporation, Collins Aerospace, Eaton Corporation, Safran Electronics & Defense, Diehl Stiftung & Co. KG, Bucher Leichtbau AG, Honeywell International Inc., AIM Altitude, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Electrical Inserts Market Emerging Trajectories
Contact metallurgy and insulator formulations are converging to address thermal cycling fatigue and signal integrity demands from distributed avionics topologies. Material science advances and regulatory pressure on system weight are accelerating form factor evolution.
Copper-beryllium contact alloys with selective gold-over-nickel plating are hybridizing with printed circuit board interconnects in integrated modular avionics racks. Collins Aerospace and Thales avionics divisions specify these hybrid assemblies for flight management system upgrades. The convergence is compressing discrete connector counts per line replaceable unit while raising qualification complexity for traditional insert suppliers.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings are forcing suppliers to adopt trivalent chromium or zirconium-based passivation for connector shells. The European Chemicals Agency enforcement timeline accelerates reformulation investments across German and French manufacturing facilities. Military-grade applications resist transition due to MIL-DTL-26482 specification lock-in, creating a two-track qualification burden for dual-use producers.
Airframe OEMs now mandate common part numbers across multiple platform variants to compress spare parts logistics costs. Boeing and Airbus procurement teams enforce this standardization through sole-source agreements with Tier 1 interconnect houses. The practice concentrates design authority with TE Connectivity and Amphenol while marginalizing specialized suppliers lacking multi-platform qualification histories.
Aerospace Electrical Inserts Market Segmentation
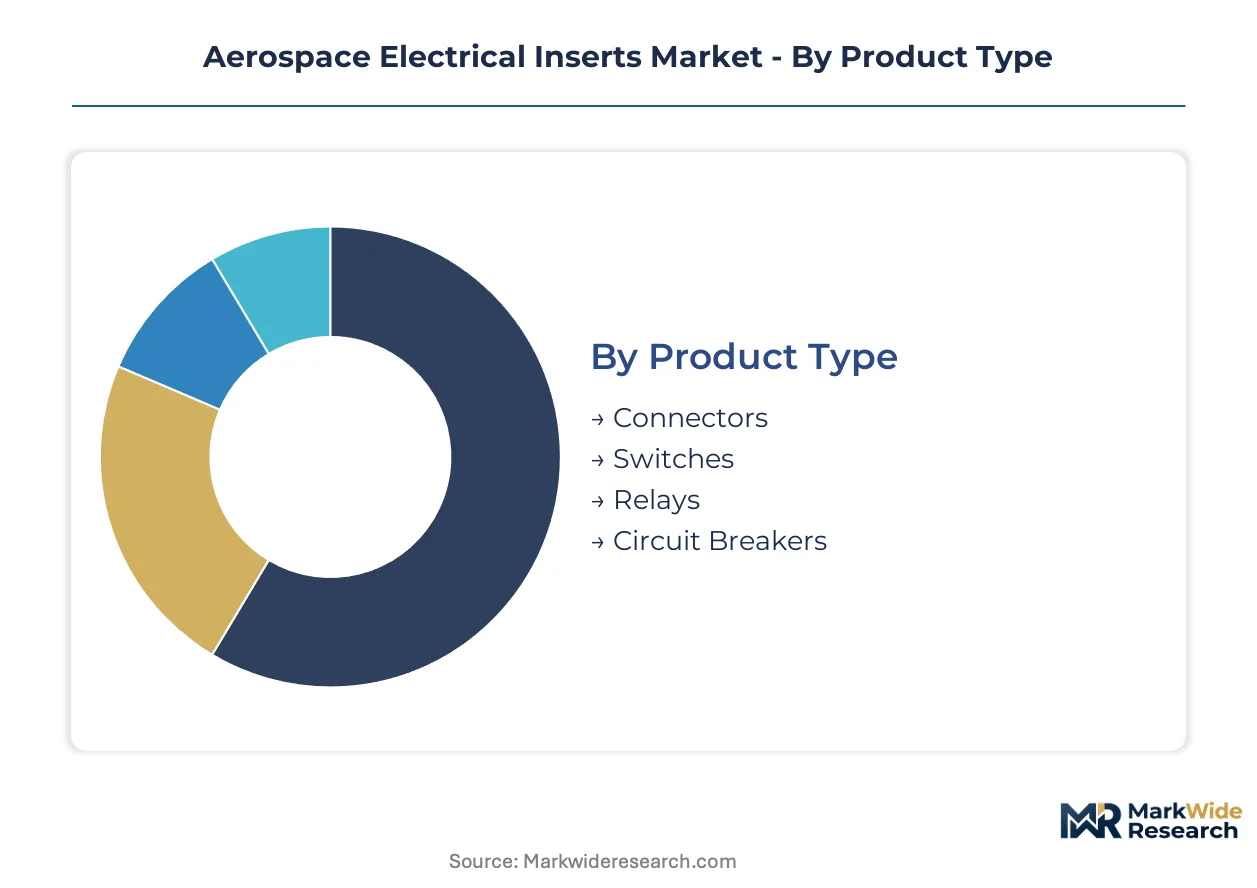
Segmentation in aerospace electrical inserts reveals how qualification requirements, thermal specifications, and platform architectures reshape procurement patterns across OEM supply chains. Each dimension exposes different competitive barriers and margin structures for suppliers seeking airframe approval.
Product Type:
Use-case spectrum spans signal integrity demands in cockpit avionics through high-current power distribution, with each product category carrying distinct metallurgy and insulator specifications.
- Connectors:Nickel-plated copper alloy contacts housed in thermoset composite or high-performance thermoplastic insulators establish current and signal pathways between wiring harnesses and subsystems. Commercial aircraft OEMs in the United States and Germany concentrate procurement for next-generation narrowbody and widebody programs, with FAA 14 CFR Part 25 and EASA CS-25 certification requirements tightening material specifications for flame resistance and smoke toxicity.
- Relays:Electromechanical switching devices manage load control in flight surface actuation and power distribution architectures. Electrified actuation replacing hydraulic control surfaces on new platforms drives the steepest expansion trajectory, with Boeing 787 and Airbus A350 programs expanding procurement volumes for electromechanical actuation systems.
- Switches:Manual or automated circuit control devices for cockpit and cabin systems. MIL-DTL-38999 qualified interconnects serve military and space-grade applications with hermetic sealing requirements.
- Circuit Breakers:Overcurrent protection devices safeguarding harness integrity against fault conditions. Thermal management specifications under 175 degrees Celsius ceiling constrain thermoplastic insulator adoption.
Established volume favors connectors; emerging adoption favors relays.
Application:
Functional deployment across aircraft systems determines contact density requirements and environmental test severity under RTCA DO-160G protocols.
- Avionics:Flight management systems and integrated modular avionics racks demand highest signal integrity with hybrid printed circuit board interconnects. Collins Aerospace and Thales divisions specify copper-beryllium contact alloys with selective gold-over-nickel plating for flight management system upgrades.
- Power Distribution:Harness termination points generate repetitive volume scale across 28VDC legacy systems and emerging 270VDC/540VDC architectures. Backward compatibility requirements complicate contact geometry optimization for new high-voltage platforms.
- Lighting Systems:Cabin and exterior illumination circuits require moderate current capacity with vibration resistance in pressurized zones.
- Communication Systems:RF signal pathways and antenna interconnects mandate electromagnetic interference shielding specifications.
Revenue concentration sits with avionics; installation growth concentrates in power distribution.
End User:
Platform type dictates qualification tier, with military and space applications imposing hermetic sealing and extended temperature range requirements beyond commercial specifications.
- Commercial Aircraft:Boeing and Airbus duopoly controls ninety percent of large airframe procurement, concentrating pricing power and extending payment terms to Tier 2 connector suppliers. Final assembly line expansion in the United States, Germany, and China drives demand concentration for next-generation programs.
- Military Aircraft:Defense procurement mandates MIL-DTL-26482 and MIL-DTL-38999 specification compliance with hexavalent chromium conversion coating lock-in resisting REACH Annex XVII transition. Amphenol Corporation anchors position through specialized hermetic sealing competencies.
- UAVs:Unmanned platforms require miniaturized interconnects with reduced weight profiles for extended endurance missions.
- Spacecraft:Vacuum and radiation-hardened specifications limit qualified supplier base to established aerospace interconnect houses.
Procurement volume leadership remains with commercial aircraft; technology premium extraction favors military aircraft.
Installation Type:
Mounting methodology determines repair accessibility, vibration resistance, and compatibility with distributed avionics topologies reshaping line replaceable unit designs.
- Embedded:Integral harness termination within airframe structure demands highest reliability qualification with limited field serviceability. Boeing and Airbus procurement teams enforce common part numbers across platform variants to compress spare parts logistics costs.
- Modular:Quick-disconnect architectures enable rapid line replaceable unit swap-out for maintenance efficiency. eVTOL developers in Germany and the United States specify miniaturized, lightweight interconnects for distributed propulsion architectures.
- Surface-Mounted:Exterior attachment for accessible subsystem interfaces with moderate environmental exposure.
- Through-Hole:Traditional penetration mounting retained for legacy platform sustainment and 28VDC system integration.
Design authority concentrates with embedded solutions; flexibility demands favor modular architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aircraft OEM procurement teams concentrate purchasing authority in three national markets where final assembly lines for next-generation platforms are expanding. Electrical insert suppliers secure airframe approval through qualification pipelines tied to specific regulatory jurisdictions and production clusters.
United States
Boeing's 737 MAX and 777X production lines in Washington state and South Carolina drive connector procurement for electrified flight control architectures. FAA 14 CFR Part 25 Amendment 25-178 mandates enhanced fault-tolerant electrical system requirements that filter supplier pools. TE Connectivity maintains qualification pipelines through its Pennsylvania-based contact metallurgy operations serving both commercial and military specifications.
Germany
Airbus A320 family final assembly in Hamburg and A350 production in Toulouse-adjacent supply chains concentrate demand for MIL-DTL-38999 qualified interconnects. EASA CS-25 certification criteria and REACH Annex XVII restrictions on hexavalent chromium force plating chemistry transitions at manufacturing facilities in Bavaria and Baden-Württemberg. Amphenol Corporation leverages specialized hermetic sealing competencies developed through German defense procurement relationships.
China
COMAC C919 production ramp in Shanghai concentrates demand for electrical distribution components as domestic narrowbody output scales. CAAC airworthiness certification alignment with FAA and EASA standards creates parallel qualification burdens for foreign subsystem integrators. Local suppliers in Jiangsu and Zhejiang provinces are acquiring plating chemistry expertise to serve state-directed import substitution programs.
France
Safran and Thales avionics divisions in the Île-de-France and Occitanie regions specify copper-beryllium contact alloys for flight management system upgrades. ANSM enforcement of REACH restrictions accelerates trivalent chromium passivation adoption at connector shell finishing facilities. The Toulouse aerospace cluster channels procurement authority for A350 electrical distribution architectures through established Tier 1 interconnect relationships.
Japan
Mitsubishi Heavy Industries and Subaru Corporation manufacturing in the Chubu and Tohoku regions sustain demand for space-grade hermetic interconnects. METI industrial policy supports domestic qualification for RTCA DO-160G environmental testing to reduce reliance on foreign certification bodies. Precision plating technicians in the Nagoya aerospace corridor concentrate expertise for high-reliability contact geometries.
Aerospace Electrical Inserts Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure concentrates design authority with Tier 1 interconnect houses holding multi-platform qualification histories, while mid-tier manufacturers face margin compression from OEM payment term extensions. Strategic archetypes include vertically integrated metallurgy specialists, hermetic sealing competency holders, and airframe OEM channel controllers. Dominant competitive moves involve backward integration into contact plating operations and strategic partnerships with solid-state power distribution developers.
Within the channel-control tier, TE Connectivity and Collins Aerospace occupy positions anchored by airframe OEM relationships across Boeing and Airbus programs. Amphenol Corporation exemplifies the hermetic sealing specialist archetype through military and space-grade application dominance. Among diversified industrial conglomerates, Eaton Corporation and Honeywell International Inc. sit within Tier 1 supplier networks leveraging electrical system integration capabilities. Diehl Stiftung & Co. KG represents the European family-owned manufacturer model with concentrated defense and commercial aerospace exposure.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Collins Aerospace |
| Eaton Corporation |
| Safran Electronics & Defense |
| Diehl Stiftung & Co. KG |
| Bucher Leichtbau AG |
| Honeywell International Inc. |
| AIM Altitude |
| Others |
Supply Flow & Price Mechanics
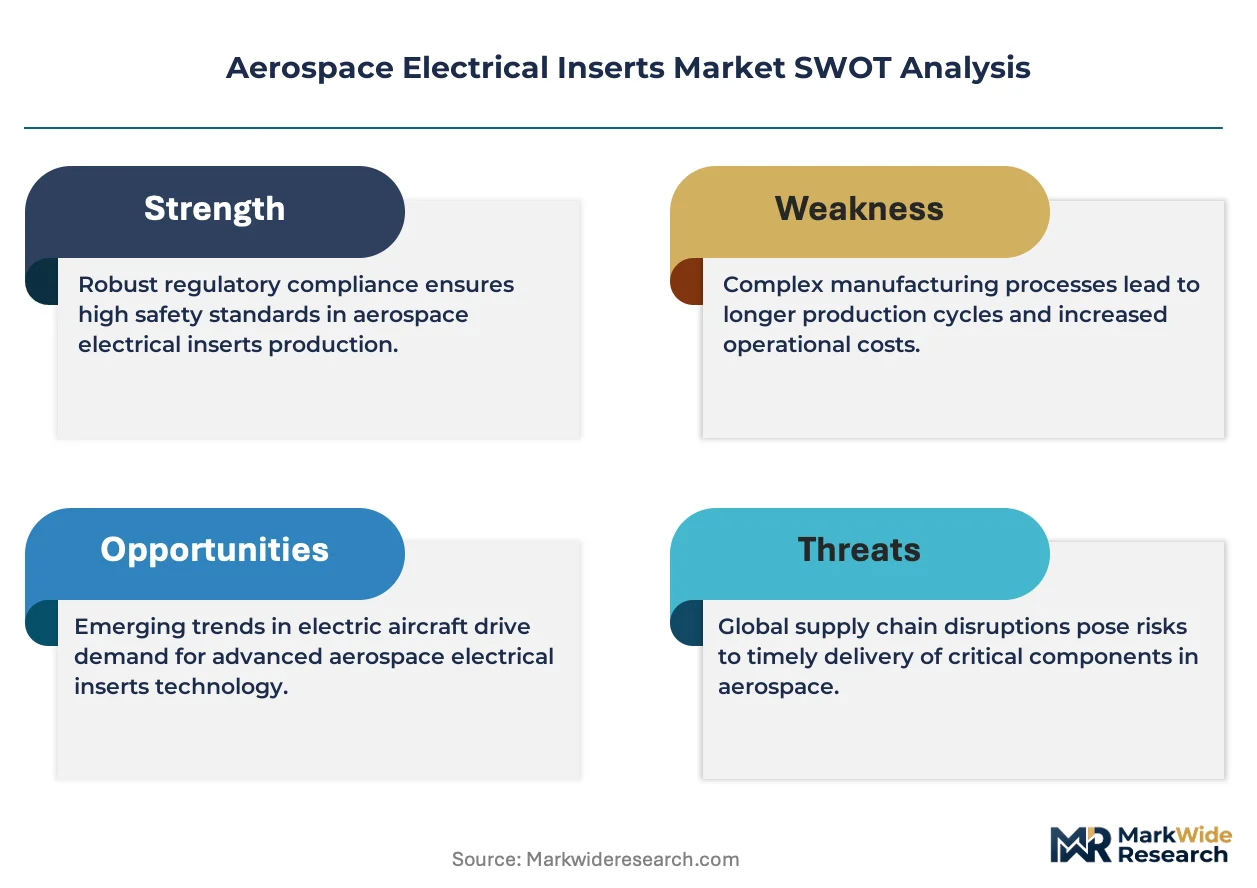
Undercapacity in precision plating facilities across Bavaria and Baden-Württemberg is compressing lead times for nickel-plated copper alloy contacts, forcing Tier 2 suppliers to absorb cost volatility while Boeing and Airbus procurement teams extend payment terms to ninety days. This utilization squeeze simultaneously elevates pricing power for qualified hermetic sealing specialists and erodes margin buffers for mid-tier connector houses lacking backward integration into contact metallurgy.
Pricing Analysis
Cost-plus contracts with LME nickel indexation dominate procurement agreements between airframe OEMs and Tier 1 interconnect suppliers, insulating TE Connectivity and Amphenol from spot price swings while exposing smaller manufacturers to margin compression. Price differentiation hinges on MIL-DTL-38999 certification tier and volume scale, with military-grade hermetic connectors commanding substantial premiums over commercial avionics variants. Pricing pressure stems from Boeing and Airbus duopoly concentration extending payment terms to Tier 2 suppliers. Regional carriers and aftermarket distributors exhibit highest price sensitivity, whereas prime defense contractors demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Extended payment terms from Boeing and Airbus procurement teams have triggered supply-chain finance facility adoption among German and French plating subcontractors, accelerating consolidation toward vertically integrated interconnect houses. Manufacturing concentrates in the United States, Germany, and China, with contact metallurgy drawing from nickel, copper-beryllium alloy, and gold plating feedstocks. Single-source vulnerability concentrates in specialized hermetic sealing technicians approaching retirement demographics. Distribution runs through airframe OEM sole-source agreements with Tier 1 suppliers, marginalizing specialized houses lacking multi-platform qualification histories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state power distribution architectures threaten electromechanical relay incumbents, compelling traditional insert suppliers to defend positioning through hybrid qualification strategies that bridge silicon carbide switching with legacy contact technologies.
For Market Incumbents: Build qualification moats around RTCA DO-160G test data archives accumulated across Boeing 787 and Airbus A350 programs, creating insurmountable requalification barriers for challengers. Deepen backward integration into contact plating operations to capture margin currently leaking to German and French specialty subcontractors. Prioritize R&D investment in hybrid PCB-interconnect assemblies specified by Collins Aerospace and Thales avionics divisions.
For New Entrants and Emerging Players: Build out distributed propulsion interconnect capabilities for eVTOL developers in Germany and the United States, where legacy aerospace form factors fail to address miniaturization requirements. Target urban air mobility electrification as the most penetrable white-space segment, exploiting qualification timeline gaps before FAA issues dedicated airworthiness criteria. Pursue strategic qualification partnerships with solid-state power distribution developers to bypass eighteen-month environmental test cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hermetic sealing competency holders as REACH Annex XVII compliance forces plating chemistry reformulation investments. Long-term viability favors acquiring mid-tier manufacturers with established FAA and EASA qualification pipelines rather than greenfield capacity builds. Monitor EASA proposals to weight electrical system efficiency in airworthiness scoring as the signal indicating procurement preference shifts toward lower-resistance contact designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Plating | Captures margin from German specialty subcontractors while securing supply continuity for Boeing and Airbus programs. |
| Hybrid PCB-Interconnect Qualification | Addresses Collins Aerospace and Thales specifications for integrated modular avionics rack convergence. |
| REACH Annex XVII Compliance Transition | Accelerates trivalent chromium adoption at French and German facilities ahead of ECHA enforcement timelines. |
| eVTOL Distributed Propulsion Development | Opens white-space revenue from Lilium and Joby specifications outside legacy aerospace form factors. |
| Solid-State Power Distribution Partnership | Positions traditional insert suppliers for silicon carbide switching integration in secondary distribution architectures. |
Methodological Framework
Cross-validation between primary interviews with aircraft electrical system engineers, Tier 1 supplier procurement directors, and plating facility operations managers anchors the qualitative findings against FAA 14 CFR Part 25 regulatory filings and EASA CS-25 certification databases. Secondary validation draws from SEC 10-K disclosures of publicly traded interconnect houses, customs records tracking nickel alloy imports, and RTCA DO-160G test laboratory accreditation files. Bottom-up platform build-ups for Boeing 737 MAX, 777X, Airbus A320 family, and A350 programs were triangulated against top-down OEM procurement spend estimates.
Calibration against historical production data from Boeing Commercial Airplanes and Airbus S.A.S. operational reports refined the analytical framework across the projection horizon. Segmentation modeling incorporated product type, application, end user, and installation type dimensions alongside voltage architecture transition from 28VDC legacy systems to 270VDC and 540VDC platforms. CAGRs were derived from platform-specific content-per-aircraft assumptions weighted by final assembly line expansion schedules in Washington state, Hamburg, and Shanghai.
Sensitivities concentrate around COMAC C919 production ramp delays, nickel price volatility transmitted through LME indexation clauses, and workforce demographics constraining plating chemistry expertise expansion. Forecasts reflect documented assumptions regarding electrified flight control adoption curves and solid-state power distribution penetration timelines. Macroeconomic contraction affecting commercial aircraft order books, regulatory acceleration of REACH restrictions, or breakthrough advances in printed electronics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market