
 Thrombophilia Testing Market | 2026-2036
Thrombophilia Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Thrombophilia Testing Market Analytics
Hospital end-user demand is expanding as perioperative thrombosis risk protocols tighten across integrated delivery networks. Siemens Healthineers leverages its installed base of coagulation analyzers to sustain recurring consumable revenue in high-throughput hospital labs. Abbott Laboratories anchors its position through point-of-care coagulation platforms that reduce turnaround time in emergency departments. Thermo Fisher Scientific differentiates via reference laboratory services that handle esoteric thrombophilia panels for smaller hospital systems.
Thrombophilia testing encompasses laboratory assays that detect inherited or acquired hypercoagulable conditions through functional, immunologic, or molecular analysis of coagulation factors, antithrombin levels, and genetic mutations such as factor V Leiden or prothrombin G20210A. These tests guide anticoagulant selection, duration of therapy, and family screening decisions in clinical practice. Genetic testing commands premium positioning due to its definitive diagnostic capability for heritable thrombophilias, while next-generation sequencing represents the fastest-growing technology segment as multiplex panels replace single-gene assays. Enzyme-linked immunosorbent assay retains volume dominance in antibody-based lupus anticoagulant and anticardiolipin testing due to established reimbursement and workflow familiarity.
FDA oversight of in vitro diagnostic devices shapes assay validation requirements and premarket notification pathways for novel thrombophilia tests, while Clinical Laboratory Improvement Amendments govern analytical performance standards in US hospital and reference laboratories. The Centers for Medicare and Medicaid Services reimbursement determinations directly influence test menu decisions by diagnostic laboratories. Stakeholders must monitor evolving pharmacogenomic guideline integrations by professional societies and corresponding coverage policy shifts by payers to anticipate volume migration between single-analyte and comprehensive thrombophilia panels.
Market Dynamics
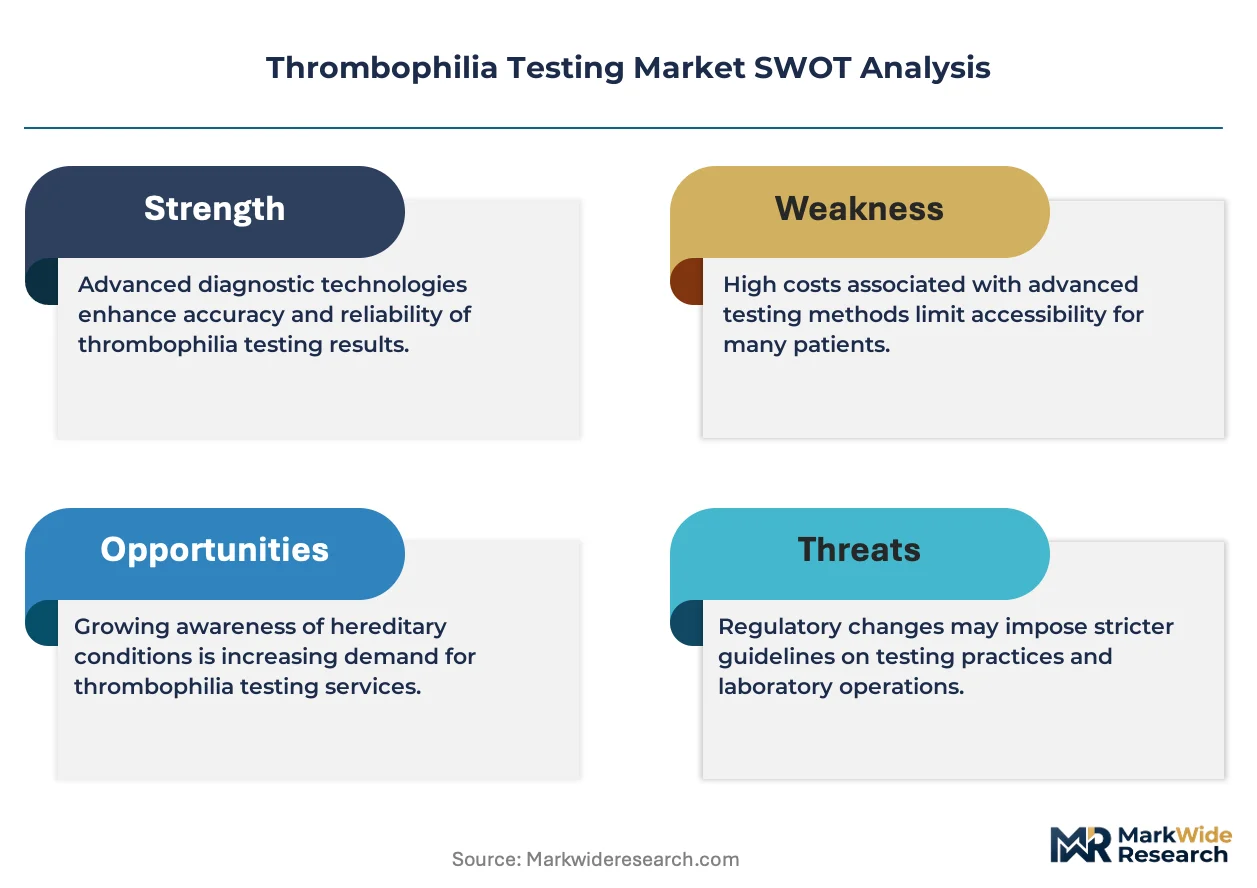
Integrated health networks are consolidating coagulation testing into centralized reference laboratories, compressing margins for standalone hospital labs while elevating throughput requirements for retained vendors. This structural concentration favors vendors with automated molecular platforms capable of processing high-volume factor V Leiden and prothrombin mutation panels under single CLIA certificates.
Growth Catalysts
- Pre-surgical screening mandates:Perioperative thrombosis risk protocols now require comprehensive coagulation panels before major orthopedic and cardiovascular procedures, driving panel volume in United States hospital systems.
- FDA pharmacogenomic guidance:Updated assay design standards for genetic thrombophilia detection accelerate validation timelines for multiplex PCR-based tests, reducing regulatory friction for novel panel submissions.
- Next-generation sequencing adoption:Multiplex gene panels are replacing single-analyte assays in academic medical centers, enabling simultaneous detection of rare prothrombin variants alongside common mutations.
Market Restraints
- Reimbursement compression:CMS coverage determinations for lupus anticoagulant testing have tightened, reducing allowable charges for functional coagulation assays in hospital outpatient settings.
- Specialist workforce constraints:Qualified hematopathologists and molecular diagnostic technologists concentrate in major metropolitan academic centers, limiting test menu expansion in community hospital laboratories.
- Anticoagulant substitution effects:Direct oral anticoagulants reduce the clinical utility of antithrombin and protein C/S functional assays, compressing demand for traditional hypercoagulability workups.
Strategic Opportunities
- Point-of-care expansion:Emergency departments in rural United States health systems seek cartridge-based coagulation platforms that deliver genetic thrombophilia results within hours rather than days.
- Pharmacogenomic integration:Warfarin sensitivity testing combined with factor V Leiden screening creates bundled reimbursement opportunities under value-based care contracts with Medicare Advantage plans.
- Reference laboratory outsourcing:Smaller integrated delivery networks lack capital for NGS infrastructure, creating white space for esoteric panel providers to capture send-out volume.
Industry Challenges
- CLIA high-complexity certification timelines:New laboratory entrants face 12-18 month validation periods for molecular thrombophilia assays, delaying revenue recognition and straining startup capital.
- Legacy analyzer interoperability:Hospital laboratories operate mixed fleets of coagulation instruments from different vendors, complicating data integration for longitudinal patient monitoring across health system mergers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrombophilia Testing Market |
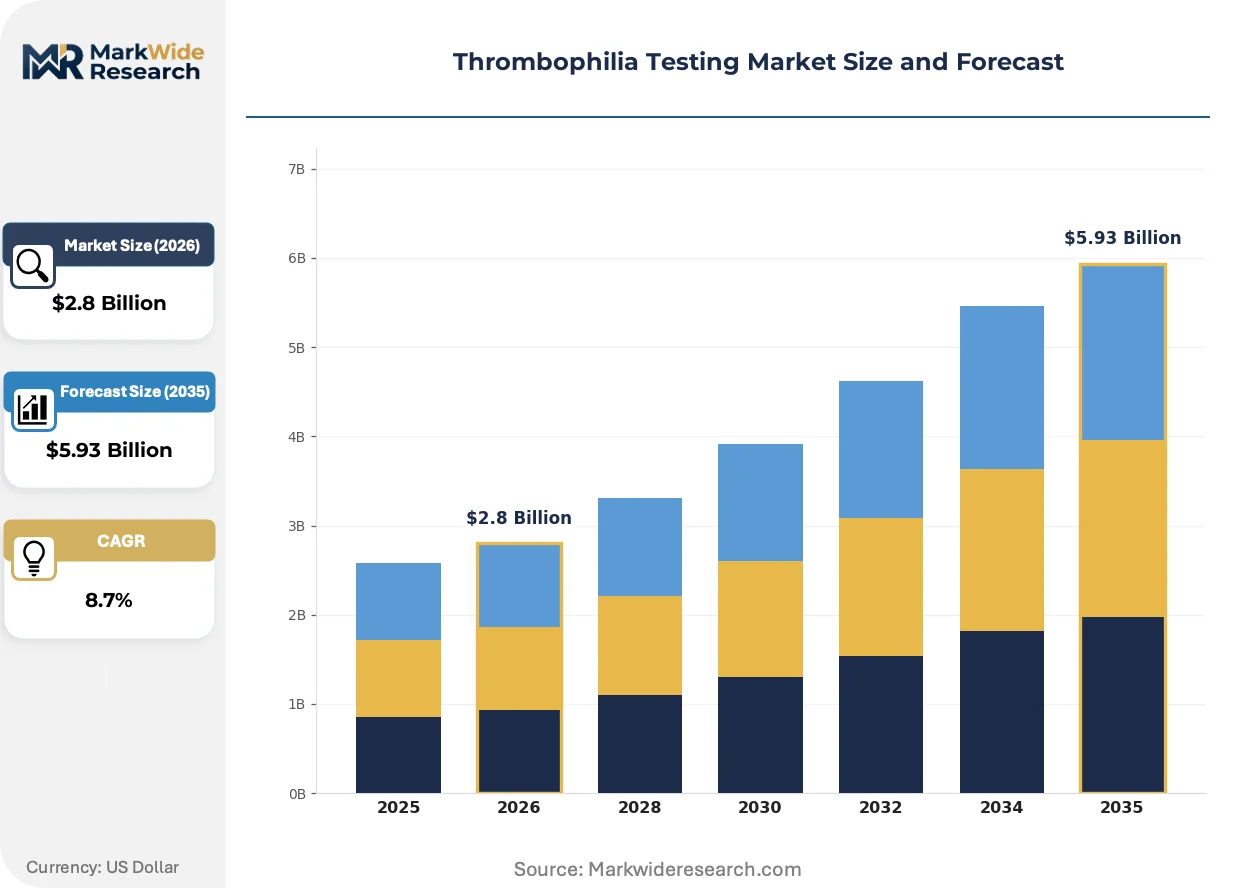
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Genetic Testing, Blood Tests, Antibody Tests, Functional Tests Application: Drug Development, Diagnostic Testing, Research, Clinical Studies End User: Hospitals, Diagnostic Laboratories, Research Institutions, Physicians Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing, Mass Spectrometry |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, QIAGEN, Werfen, Helena Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrombophilia Testing Market Evolving Landscape
Technological substitution and regulatory recalibration are compressing the traditional separation between functional coagulation testing and molecular diagnostics, creating pressure for unified platform architectures.
Next-generation sequencing is overtaking single-gene PCR for heritable thrombophilia workups in academic medical centers. These institutions process complex cases requiring simultaneous detection of factor V Leiden, prothrombin G20210A, and rare SERPINC1 mutations. The technology is enabling comprehensive risk stratification that compresses the diagnostic timeline from multiple sequential tests to a single specimen submission.
The FDA's evolving pharmacogenomic labeling requirements for anticoagulant therapies are reshaping assay development priorities. Manufacturers must now demonstrate clinical validity across diverse populations to support test claims. Molecular diagnostic companies serving United States reference laboratories are responding by expanding variant databases and improving analytical specificity for heterozygous mutation detection.
Hospital procurement committees are unbundling coagulation testing contracts that previously locked them into single-vendor reagent agreements. Group purchasing organizations now negotiate separate agreements for high-volume routine assays and low-volume esoteric panels. This behavioral shift is most visible in Midwestern United States health systems where consolidated service lines demand flexible test menus without capital equipment commitments.
Thrombophilia Testing Market Segmentation
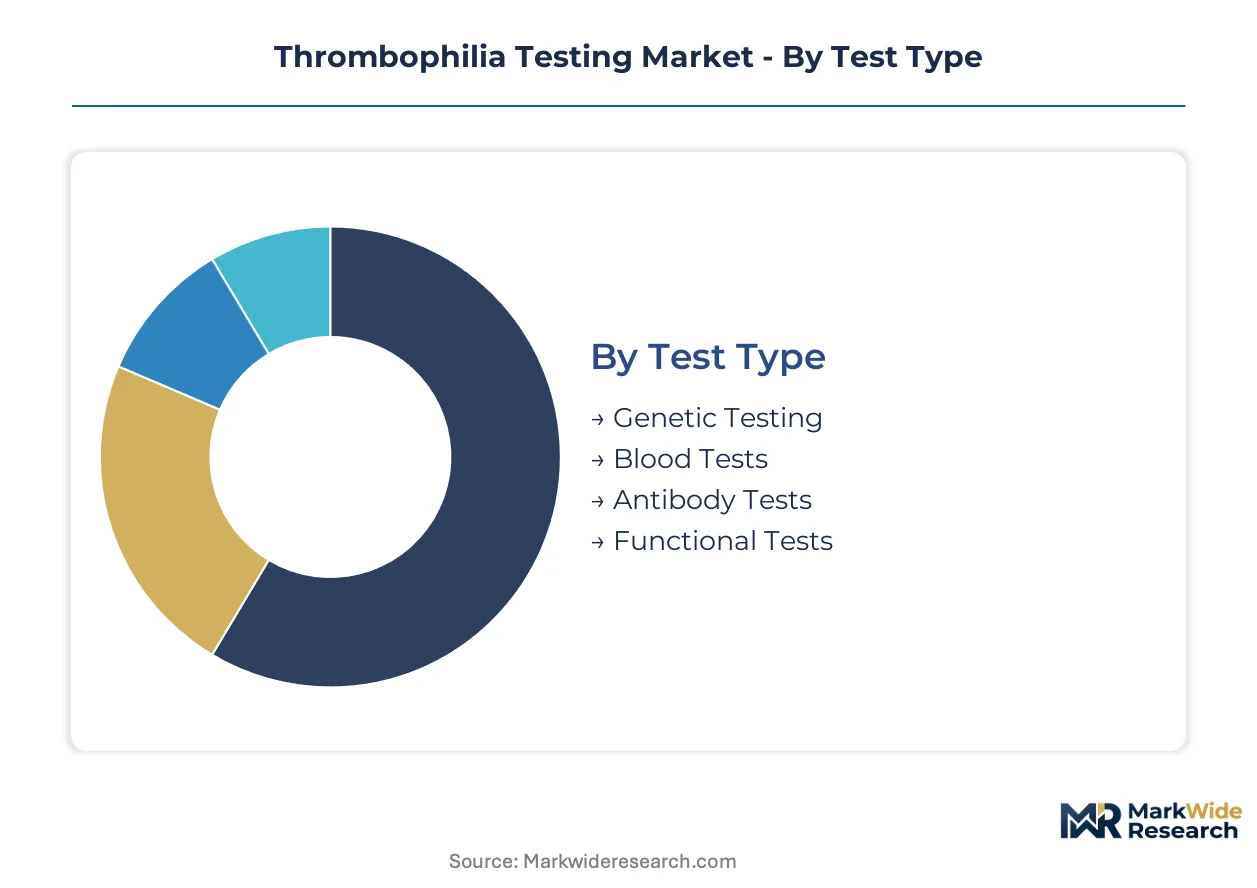
Thrombophilia testing segments reflect divergent margin structures and regulatory pathways. Genetic and molecular platforms command premium positioning against functional coagulation assays, while end-user consolidation reshapes vendor access points across health systems.
Test Type:
Volume concentrates in functional and antibody-based assays, while genetic testing captures the premium tier with definitive heritable thrombophilia diagnosis.
- Genetic Testing:Detects factor V Leiden, prothrombin G20210A, and SERPINC1 mutations through PCR or NGS methods. Academic medical centers in the United States drive demand as multiplex panels replace sequential single-gene assays under pharmacogenomic protocol expansion.
- Blood Tests:Quantify antithrombin, protein C, and protein S levels via chromogenic or clotting-based methods. Hospital laboratories process high volumes for pre-surgical screening, though direct oral anticoagulants have reduced clinical utility for some functional assays.
- Antibody Tests:Identifies lupus anticoagulant and anticardiolipin antibodies.
- Functional Tests:Measures coagulation cascade activity through activated protein C resistance and clotting time assays.
Today's leader: Genetic Testing. Tomorrow's challenger: Blood Tests.
Application:
Diagnostic testing dominates procedure volume, while drug development applications concentrate investment in biomarker discovery and anticoagulant trial enrollment.
- Diagnostic Testing:Guides anticoagulant selection, therapy duration, and family screening decisions. Integrated delivery networks in the United States centralize high-complexity panels into reference laboratories, compressing turnaround time for perioperative risk assessment.
- Drug Development:Supports pharmacogenomic stratification in warfarin and novel anticoagulant clinical trials. Contract research organizations leverage thrombophilia genotyping to reduce adverse event rates in Phase III cardiovascular studies.
- Research:Investigates novel thrombophilic variants and population genetics.
- Clinical Studies:Generates real-world evidence on testing utility and cost-effectiveness.
Diagnostic Testing anchors current revenue. Drug Development offers the steepest expansion trajectory as pharmacogenomic endpoints integrate into regulatory submissions.
End User:
Procurement authority is migrating from individual hospital labs toward consolidated service lines and outsourced reference arrangements.
- Hospitals:Perform pre-surgical coagulation panels and emergency department workups. Perioperative thrombosis risk protocols now mandate comprehensive screening before major orthopedic procedures, sustaining inpatient volume despite outpatient reimbursement compression.
- Diagnostic Laboratories:Process esoteric panels for smaller health systems lacking NGS infrastructure. Regional reference labs in the United States capture send-out volume through CLIA high-complexity certification and rapid turnaround guarantees.
- Research Institutions:Conduct population studies and variant discovery programs.
- Physicians:Order testing through hospital or laboratory channels.
Diagnostic Laboratories gain procurement influence. Hospitals defend retained testing through point-of-care platform investments.
Technology:
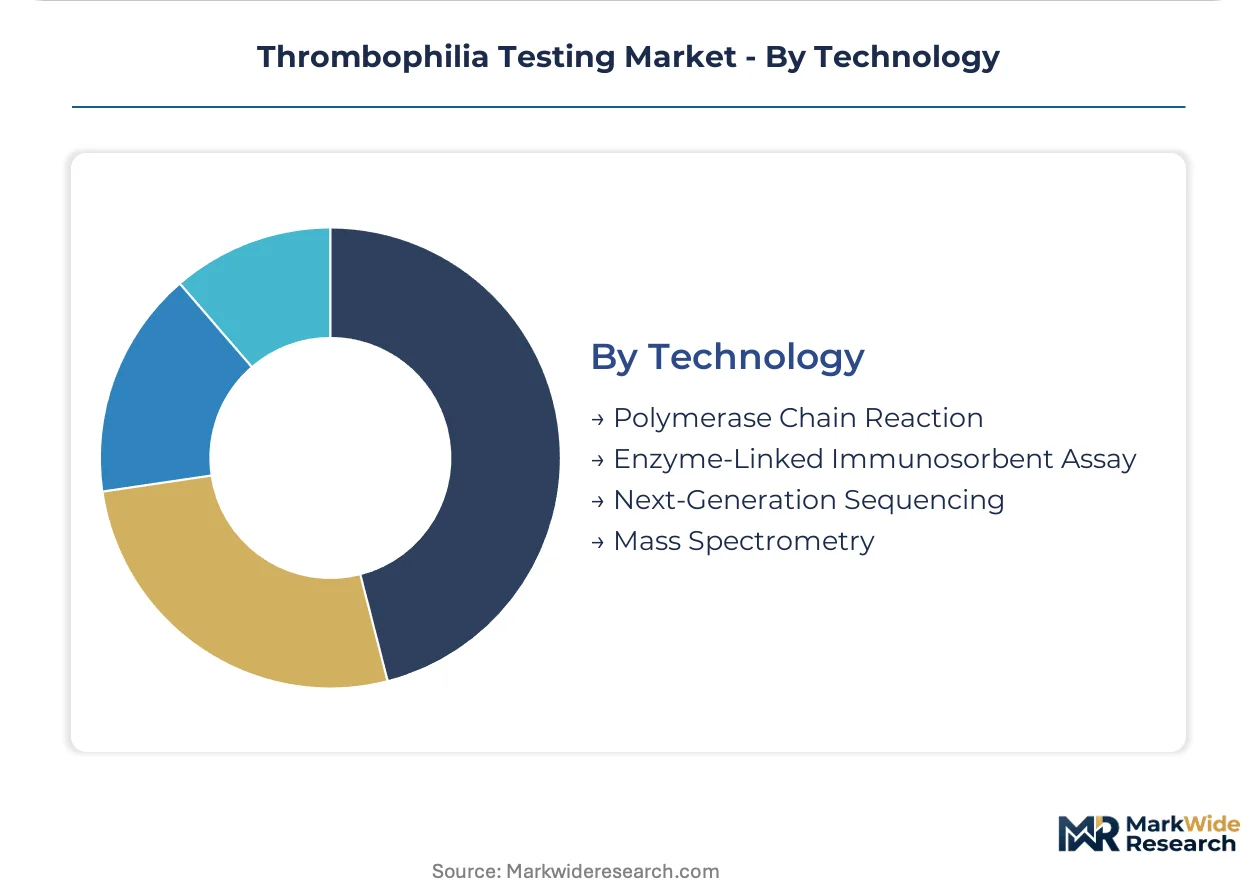
Established immunologic methods retain volume dominance, while sequencing platforms displace single-analyte molecular assays in academic settings.
- Next-Generation Sequencing:Enables simultaneous detection of common and rare thrombophilic variants in single specimen submissions. United States academic medical centers adopt NGS panels to compress diagnostic timelines for complex heritable thrombosis cases.
- Enzyme-Linked Immunosorbent Assay:Retains workflow familiarity and established reimbursement for lupus anticoagulant and anticardiolipin antibody detection. Hospital laboratories continue high-volume ELISA processing due to capital efficiency and technologist training depth.
- Polymerase Chain Reaction:Delivers rapid factor V Leiden and prothrombin mutation detection.
- Mass Spectrometry:Quantifies coagulation factor levels with high analytical specificity.
Enzyme-Linked Immunosorbent Assay maintains installed base dominance. Next-Generation Sequencing is gaining share fastest as panel costs decline and interpretation pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks drive the dominant share of thrombophilia testing volume through centralized reference laboratory consolidation and perioperative screening mandates.
United States
Integrated delivery networks in the Midwest and Northeast centralize high-complexity coagulation panels under single CLIA certificates. FDA pharmacogenomic guidance accelerates multiplex PCR validation timelines for factor V Leiden detection. The Boston-Cambridge corridor anchors esoteric testing infrastructure serving academic medical centers nationwide.
Germany
University hospitals in Bavaria and Baden-Württemberg process complex heritable thrombosis cases through NGS-equipped molecular pathology departments. EMA oversight of in vitro diagnostic devices shapes assay performance standards for cross-border laboratory networks. The Rhine-Main metropolitan region concentrates reference laboratory capacity for Central European health systems.
United Kingdom
NHS England's specialized commissioning frameworks consolidate thrombophilia testing into designated haemostasis and thrombosis centres. MHRA post-market surveillance requirements influence quality management systems for molecular diagnostic platforms. London's academic hospital trusts operate the largest volume of next-generation sequencing panels for rare prothrombin variants.
Japan
PMDA regulatory pathways for companion diagnostics create structured entry channels for pharmacogenomic coagulation assays. Metropolitan Tokyo hospitals integrate automated coagulation analyzers with electronic medical record systems for perioperative risk stratification. The Kansai region's medical device manufacturing cluster supplies reagent kits for domestic and export markets.
Australia
TGA conformity assessment procedures determine market access timelines for imported molecular diagnostic instruments. State-based pathology services in New South Wales and Victoria standardize thrombophilia panel menus across public hospital networks. Melbourne's biomedical research precinct generates real-world evidence on testing utility for national reimbursement determinations.
Thrombophilia Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as diagnostic manufacturers align with health system consolidators to secure long-term consumable contracts. The vendor base separates into three tiers: multinational conglomerates with full coagulation platform portfolios, molecular specialists with NGS interpretation capabilities, and regional reference laboratories with CLIA high-complexity certification. Competitive positioning hinges on installed base retention through reagent lock-in agreements and rapid test menu expansion via technology licensing rather than internal R&D.
Among diversified diagnostic conglomerates, Roche Diagnostics, Abbott Laboratories, and Siemens Healthineers occupy positions defined by installed base scale and recurring revenue from consumable streams. These entities exemplify the platform-leasing archetype where capital equipment placement precedes multi-year reagent supply commitments. Thermo Fisher Scientific represents the reference laboratory services model, capturing send-out volume from health systems lacking in-house molecular infrastructure. Werfen and QIAGEN sit within the specialized reagent and molecular assay segment, supplying components and workflows rather than integrated systems. The competitive dynamic rewards vendors capable of bundling genetic and functional testing under unified ordering and reporting platforms.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| QIAGEN |
| Werfen |
| Helena Laboratories |
| Others |
Value Network & Pricing Analysis
Reagent kit manufacturing costs in the United States and Germany cascade through three distinct pricing tiers as multiplex PCR panels displace single-analyte assays downstream. Hospital laboratories absorb premium positioning for NGS-based thrombophilia workups while reference laboratories compete on turnaround time rather than unit economics alone.
Pricing Analysis
Distributor margins on molecular diagnostic consumables compress as integrated delivery networks negotiate direct purchasing agreements with assay manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification tier, panel complexity, and interpretation service bundling. Pricing pressure stems from CMS reimbursement compression for functional coagulation assays, forcing mid-tier laboratories toward economy positioning. Community hospital systems exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize analytical specificity over per-test cost.
Supply Chain Analysis
Refurbished coagulation analyzer placements in secondary United States health systems extend equipment lifecycle and delay new capital procurement decisions. Critical reagent manufacturing concentrates in the United States, Germany, and Japan, with thermostable polymerase enzymes and fluorogenic probe chemistries drawing from specialized biotech suppliers. Single-source vulnerability persists for rare SERPINC1 mutation detection reagents produced by limited qualified vendors. Distribution runs through regional reference laboratory networks and direct-to-hospital contracts rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thrombophilia testing functions as a stable compounder sustained by perioperative screening mandates that embed coagulation panels into standard surgical protocols across integrated health networks.
For Market Incumbents: Anchor installed base retention through multi-year reagent lock-in agreements that bundle routine functional assays with esoteric genetic panels. Defend against NGS platform substitution by accelerating automated molecular assay menu expansion. Prioritize CLIA high-complexity certification support services for captive reference laboratory customers. For New Entrants and Emerging Players: Begin with point-of-care cartridge development for rural emergency departments lacking same-day genetic testing access. Target send-out volume from Midwestern United States health systems that consolidated service lines without internal NGS infrastructure. Pursue pharmacogenomic protocol integration as the primary go-to-market pathway. For Investors and Strategic Acquirers: Consolidation pressure builds where reference laboratory networks lack molecular diagnostic interpretation capabilities and depend on outsourced bioinformatics pipelines. Long-term viability favors platforms combining genetic and functional testing under unified ordering systems. Acquisition targets include regional reference laboratories with established CLIA certificates and rapid turnaround guarantees. Monitor FDA pharmacogenomic guidance expansion for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| NGS Platform Integration | Multiplex panels compress diagnostic timelines for complex heritable thrombosis cases in academic centers. |
| Point-of-Care Cartridge Development | Rural emergency departments gain same-day genetic results without reference laboratory send-out delays. |
| CLIA Certification Services | Startup laboratories reduce 12-18 month validation timelines through outsourced compliance support. |
| Pharmacogenomic Protocol Integration | Bundled warfarin sensitivity and factor V Leiden screening unlocks Medicare Advantage contract value. |
| Reference Laboratory Outsourcing | Smaller health systems capture esoteric panel access without capital-intensive NGS infrastructure investment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hematopathologists, molecular diagnostic technologists, hospital procurement managers, and GPO contracts specialists with secondary validation against FDA 510(k) filings, CMS reimbursement determinations, CLIA certification databases, and hospital procurement records. Bottom-up test volume estimates triangulated against top-down health system expenditure data.
Comparable-period anchoring established baseline utilization rates from pre-pandemic surgical volumes through perioperative protocol expansion phases across the modeling period. Segmentation dimensions included test type, technology platform, end-user setting, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trajectories and protocol penetration assumptions, with specific inputs for NGS cost curves and pharmacogenomic guideline adoption rates.
Several conditions sit outside the modeled scope, including novel anticoagulant substitution effects on functional assay demand and potential FDA reclassification of direct-to-consumer genetic testing. Forecasts reflect assumptions about stable CMS reimbursement and continued perioperative screening mandate expansion. Practitioners should monitor pharmacogenomic guideline updates and CLIA regulatory modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
US Viral Clearance Market
Testing Services
Blood Sugar Tester Market
Testing Services
Global GMP Testing Service Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Solid Tumor Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Global Bilirubin Colorimeter Assay Market