
 Serine Amino Acid Market | 2026-2036
Serine Amino Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Serine Amino Acid Market Analytics
Specialized fermentation engineering talent is bifurcating the competitive landscape as facilities requiring GMP-grade serine struggle to hire operators trained in continuous bioprocessing. Ajinomoto Co., Inc. leverages decades of amino acid fermentation expertise to dominate pharmaceutical-grade supply chains. Evonik Industries AG anchors European production through backward integration into precursor chemicals. KYOWA HAKKO BIO CO., LTD. specializes in high-purity L-serine for cell culture media, occupying a defensible niche in biopharmaceutical raw materials.
Serine is a non-essential proteinogenic amino acid with the chemical formula HO₂CCH(NH₂)CH₂OH, produced industrially via microbial fermentation of glucose or enzymatic conversion of glycine, and serves as a critical building block for phospholipid synthesis, pyrimidine metabolism, and recombinant protein production. Pharmaceutical applications command premium pricing due to USP-grade certification requirements for injectable formulations and cell culture media. Nutritional supplements represent the volume-leading segment, though powder formats face margin compression from commoditized Chinese supply. Food & Beverages applications are accelerating fastest as clean-label fortification trends drive reformulation of functional beverages and infant nutrition products.
FDA enforces ICH Q7 guidelines for active pharmaceutical ingredient manufacturing, while EMA's REACH compliance mandates traceability of fermentation-derived inputs into European pharmaceutical supply chains. China's NMPA has aligned domestic drug master file requirements with PIC/S standards, reshaping export qualification pathways for Chinese serine producers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs, as diverging purity specifications threaten to fragment contract manufacturing arrangements and force dual-qualification investments.
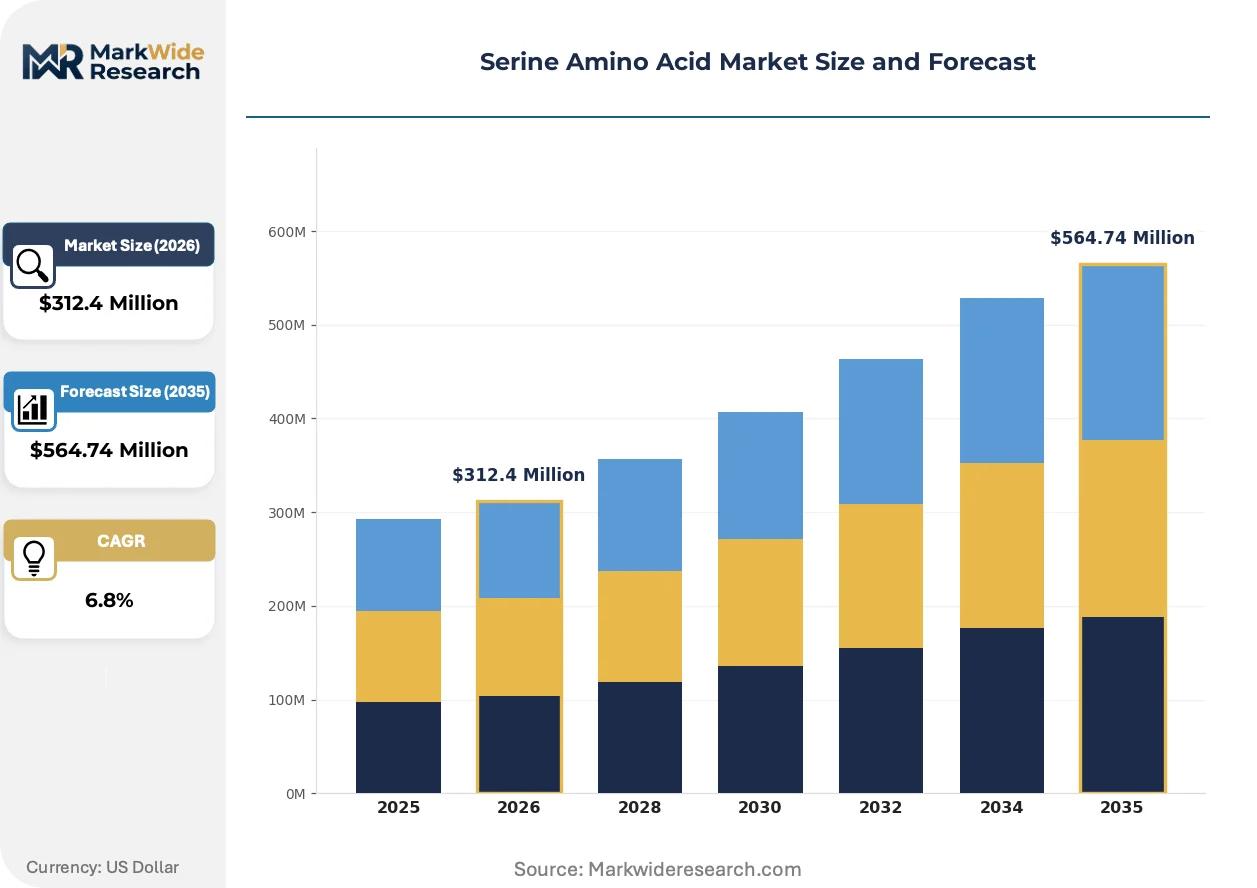
Market Dynamics
Fermentation capacity concentration in China is bifurcating the Serine Amino Acid Market into GMP-certified and industrial-grade supply tiers, forcing Western buyers to dual-source or absorb qualification delays.
Growth Catalysts
- Peptide synthesis protocol advancement:Biologics manufacturers are expanding serine procurement for recombinant protein production, with FDA tightening purity specifications for injectable formulations.
- REACH compliance mandates:EMA traceability requirements for fermentation-derived inputs are accelerating European investment in qualified serine supply chains.
- Clean-label fortification:Functional beverage reformulation across North America and Western Europe is pulling food-grade serine volumes upward.
Market Restraints
- Glucose feedstock volatility:Corn price swings directly compress fermentation margins, with Chinese producers most exposed to input cost spikes.
- Single-region supply concentration:Overreliance on Shandong and Jiangsu province fermentation clusters creates geopolitical and logistics risk for pharmaceutical buyers.
- Enzymatic conversion substitution:Glycine-to-serine biocatalysis at industrial scale threatens to displace traditional fermentation for non-pharmaceutical grades.
Strategic Opportunities
- Cell culture media specialization:High-purity L-serine for biopharmaceutical raw materials remains underpenetrated relative to peptide synthesis demand.
- India PLI scheme alignment:Contract fermentation investment under the country's pharmaceutical incentives could diversify API-grade supply origins.
- Continuous bioprocessing convergence:Integration of perfusion fermentation with real-time analytics is opening qualification pathways for next-generation GMP facilities.
Industry Challenges
- Continuous bioprocessing talent scarcity:Facilities requiring GMP-grade serine struggle to hire operators trained in automated fermentation control systems.
- Dual pharmacopeial qualification timelines:Diverging USP, EP, and ChP monograph specifications force redundant validation investments for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serine Amino Acid Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Granules Application: Nutritional Supplements, Pharmaceutical, Animal Feed, Food & Beverages End User: Healthcare Professionals, Fitness Enthusiasts, Pet Owners, Food Manufacturers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, KYOWA HAKKO BIO CO., LTD., Merck KGaA, Tokyo Chemical Industry Co., Ltd., Mitsui Chemicals, Thermo Fisher Scientific Inc., Sichuan Tongsheng Amino Acid Co., Ltd., Lipotec S.A.U., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serine Amino Acid Market Evolving Landscape
Process intensification and regulatory harmonization pressures are compressing the technology lifecycle for serine production, while end-use verticals fragment procurement specifications.
Continuous manufacturing platforms for amino acid fermentation are miniaturizing unit operations previously requiring batch-scale infrastructure. Biologics CDMOs in Switzerland and Massachusetts are piloting these systems for GMP serine production. The technology is miniaturizing capital requirements for qualified pharmaceutical-grade supply, enabling mid-scale entrants to challenge incumbent fermentation titans.
EMA's evolving REACH compliance for fermentation-derived API inputs is forcing traceability investments back to glucose sourcing. European pharmaceutical manufacturers now require chain-of-custody documentation through precursor chemicals. Cell culture media suppliers face the steepest compliance burden, with several reformulating around serine sources with pre-qualified REACH dossiers.
Specification-driven procurement is consolidating buyer power among top-tier biopharmaceutical manufacturers. Long-term offtake agreements with embedded quality audits are displacing spot-market purchasing for USP-grade material. Switzerland and Singapore host the most concentrated contract negotiations, with procurement teams demanding dual-source redundancy and pharmacopeial flexibility clauses.
Serine Amino Acid Market Segmentation
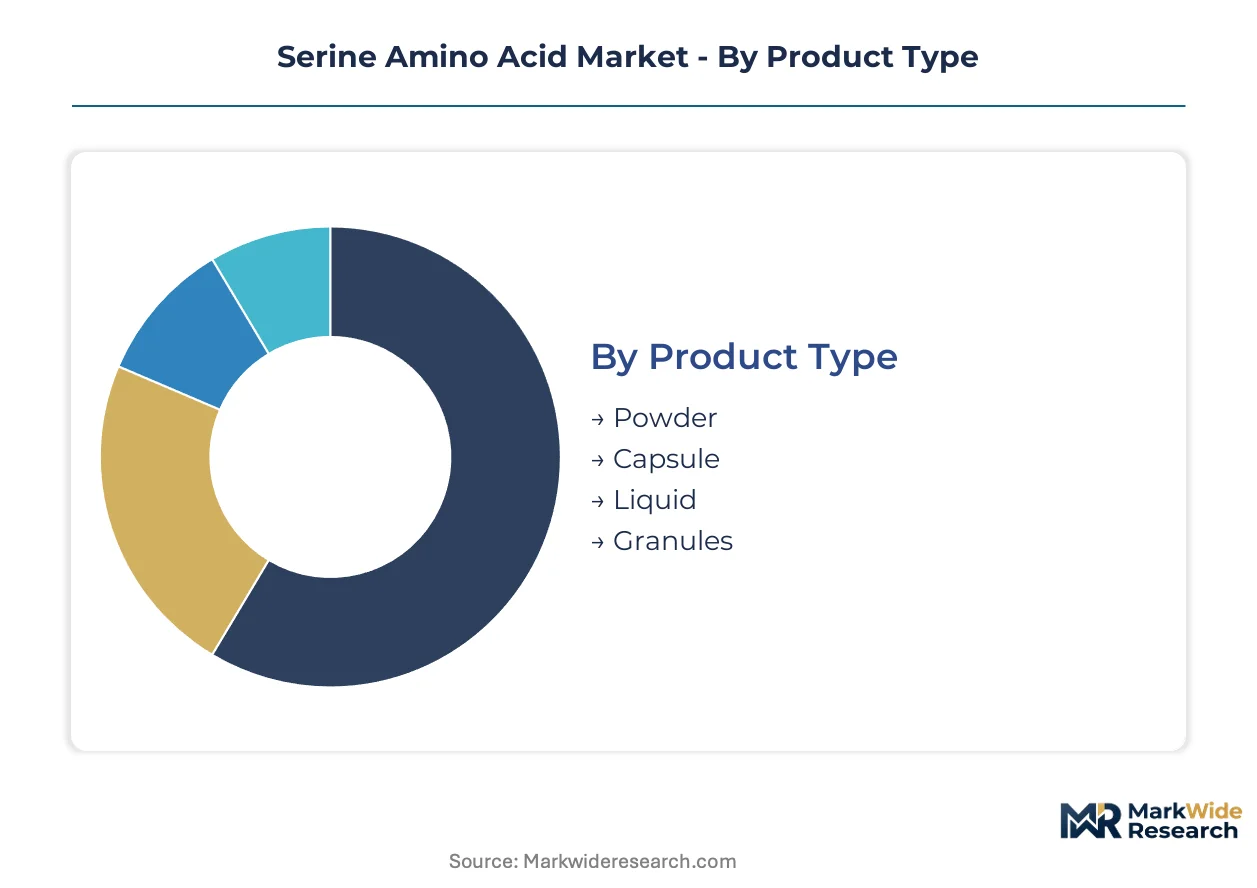
Serine procurement channels bifurcate sharply between bulk fermentation contracts for pharmaceutical manufacturers and packaged formats reaching end consumers through retail networks. Specification tiers create distinct margin profiles that reshape competitive positioning across each segment boundary.
Product Type:
Powder formats dominate institutional procurement through fermentation tolling agreements, while finished dosage forms flow through branded supplement channels with embedded quality certifications.
- Powder:Bulk crystalline L-serine serves cell culture media and peptide synthesis protocols. Biologics CDMOs in Switzerland and Massachusetts concentrate procurement here under long-term offtake agreements with embedded USP-grade audits.
- Capsule:Encapsulated formats target fitness enthusiasts and clinical nutrition protocols. Demand concentrates through direct-to-consumer subscription models, with NSF and Informed Sport certifications commanding shelf placement premiums in specialty retail.
- Liquid:Ready-to-dispense solutions serve pediatric and geriatric compliance segments. Functional beverage manufacturers in North America and Western Europe reformulate with liquid serine for clean-label fortification claims.
- Granules:Free-flowing agglomerated forms suit high-speed tableting operations. Animal feed compounders source granules through agricultural distribution cooperatives with volume-tiered pricing.
Powder dominates installed base. Capsule is where expansion concentrates.
Application:
Cost tiers separate fermentation-grade pharmaceutical supply from commoditized nutritional volumes, with regulatory burden determining margin retention.
- Nutritional Supplements:Sports nutrition and cognitive health positioning drive consumer-facing volumes. E-commerce direct sales in the US and UK bypass traditional wholesale markups, compressing brand margins against private-label competition.
- Pharmaceutical:USP-grade serine for injectable formulations and cell culture media commands the steepest purity premiums. FDA ICH Q7 compliance and EMA REACH traceability force dedicated supply chain investments with limited qualified sources.
- Animal Feed:Lysine-methionine balanced rations incorporate serine for monogastric optimization. Chinese fermentation capacity feeds regional livestock operations through integrated feed mill procurement.
- Food & Beverages:Infant formula and functional beverage fortification accelerate fastest. Clean-label positioning in North America and Western Europe pulls food-grade volumes upward despite formulation stability challenges.
Nutritional Supplements anchor volume scale. Food & Beverages is climbing the fastest.
End User:
Customer type determines specification stringency, from GMP-grade pharmaceutical procurement to commodity feed additive purchasing.
- Healthcare Professionals:Clinical nutritionists and metabolic specialists prescribe pharmaceutical-grade serine for specific patient populations. Hospital formulary access requires pharmacopeial documentation that industrial grades cannot satisfy.
- Fitness Enthusiasts:Strength athletes and biohackers drive nootropic and recovery supplement demand. Social media influencer marketing reshapes brand discovery, with subscription retention metrics determining customer lifetime value.
- Pet Owners:Premium companion animal nutrition incorporates serine for coat and cognitive health claims. Veterinary-exclusive channels maintain higher margins than mass retail pet supplies.
- Food Manufacturers:Reformulation teams at infant nutrition and beverage companies source food-grade serine with FSSAI, FDA, or EFSA compliance dossiers. Supplier qualification timelines stretch 12-18 months for new raw material approvals.
Healthcare Professionals dominate premium tier procurement. Fitness Enthusiasts is gaining share fastest.
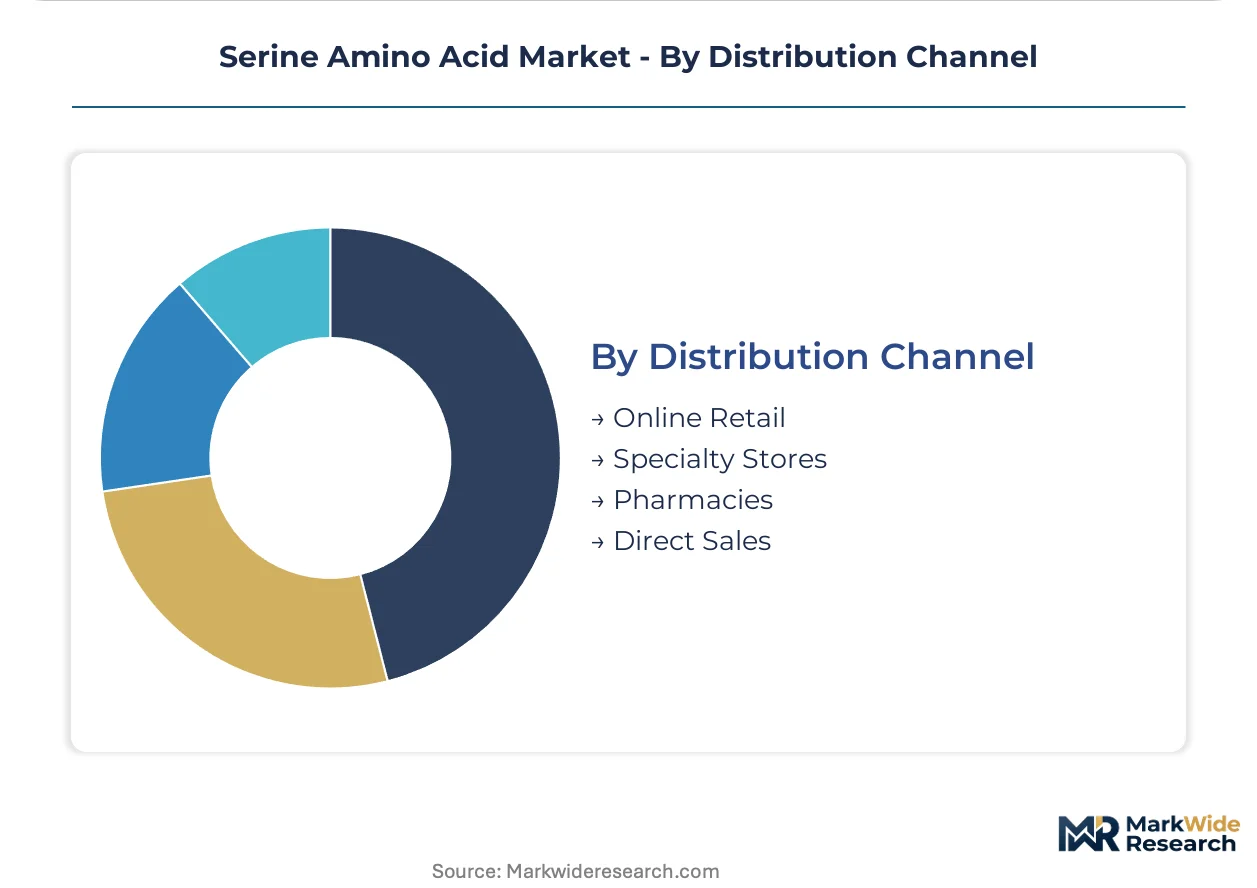
Distribution Channel:
Channel mix reflects specification tier, with qualified pharmaceutical supply bypassing retail entirely while consumer formats fragment across digital and physical touchpoints.
- Online Retail:Amazon, iHerb, and direct brand sites capture supplement volumes with subscription mechanics. Search engine optimization and influencer partnerships determine customer acquisition costs in this channel.
- Specialty Stores:GNC, Vitamin Shoppe, and regional health food chains maintain curated assortments with trained staff consultation. These outlets preserve premium pricing against e-commerce discounting pressure.
- Pharmacies:CVS, Walgreens, and Boots stock pharmacist-recommended brands with USP verification. Clinical credibility positioning supports price premiums over mass-market alternatives.
- Direct Sales:Fermentation tolling agreements and long-term offtake contracts connect API-grade producers directly to biopharmaceutical manufacturers. Procurement teams in Switzerland and Singapore negotiate these arrangements with dual-source redundancy clauses.
Direct Sales dominates pharmaceutical value capture. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and Singaporean procurement hubs while Chinese fermentation clusters absorb margin compression from glucose feedstock volatility. Pharmaceutical buyers in Basel and Singapore negotiate long-term offtake agreements with embedded quality audits. Industrial-grade volumes flow through spot markets where Shandong and Jiangsu province producers compete on cost.
China
Shandong and Jiangsu province fermentation clusters supply the majority of industrial-grade serine for nutritional supplements and animal feed. NMPA alignment with PIC/S standards has reshaped export qualification pathways for pharmaceutical-grade producers. Domestic CDMOs in Jiangsu are upgrading facilities to capture cell culture media demand from biopharmaceutical manufacturers.
United States
FDA ICH Q7 enforcement drives USP-grade serine procurement for injectable formulations and peptide synthesis protocols. Massachusetts and North Carolina biologics manufacturing clusters source through direct sales channels with dual-source redundancy requirements. Continuous bioprocessing pilot programs in Cambridge are miniaturizing GMP fermentation infrastructure.
Switzerland
Basel-based pharmaceutical procurement teams anchor European demand for high-purity L-serine in cell culture media applications. Swissmedic certification requirements exceed standard pharmacopeial specifications, creating qualification barriers for non-European suppliers. The Basel-Lucerne corridor hosts concentrated contract negotiations with embedded quality audit clauses.
India
Pharmaceutical-grade demand from biologics manufacturers is accelerating as CDMOs expand peptide synthesis capacity. PLI scheme incentives for contract fermentation investment could diversify API-grade supply origins beyond Chinese sources. Maharashtra and Telangana states are attracting fermentation engineering talent for GMP facility operations.
Germany
EMA REACH compliance mandates traceability of fermentation-derived inputs through precursor chemical sourcing. Evonik Industries anchors European production through backward integration into precursor supply chains. Frankfurt and Ludwigshafen chemical clusters enforce chain-of-custody documentation requirements that extend back to glucose feedstock origins.
Serine Amino Acid Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. GMP-certified pharmaceutical-grade supply concentrates among fermentation specialists with decades of amino acid expertise, while industrial-grade volumes fragment across Chinese producers competing on scale. Three archetypes dominate: integrated chemical conglomerates with backward integration into precursors, pure-play amino acid fermentation specialists, and diversified life science suppliers leveraging distribution reach. Competitive moves center on pharmacopeial qualification investments and continuous bioprocessing capability acquisition.
Within the fermentation specialist tier, Ajinomoto Co., Inc. and KYOWA HAKKO BIO CO., LTD. exemplify archetypes differentiated by application focus. Evonik Industries AG represents the integrated chemical conglomerate model with European production anchoring. These three companies occupy positions across the premium-mid-economy spectrum, with their geographic origins and corporate structures reflecting distinct strategic postures toward regulatory compliance and customer qualification requirements.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| KYOWA HAKKO BIO CO., LTD. |
| Merck KGaA |
| Tokyo Chemical Industry Co., Ltd. |
| Mitsui Chemicals |
| Thermo Fisher Scientific Inc. |
| Sichuan Tongsheng Amino Acid Co., Ltd. |
| Lipotec S.A.U. |
| Others |
Value Network & Pricing Analysis
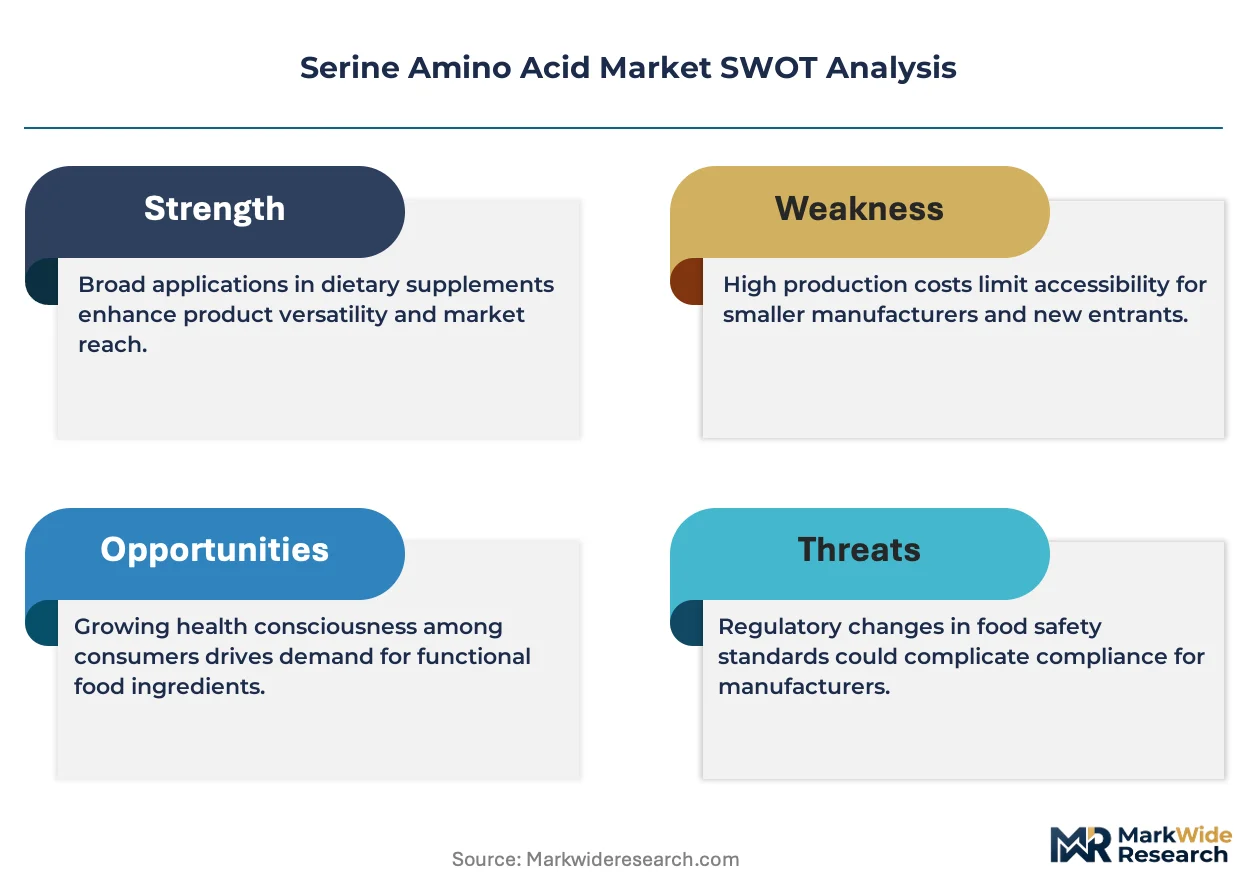
Ninety-day inventory buffers at Swiss biopharmaceutical procurement hubs signal procurement teams' response to supply chain bifurcation, with GMP-grade serine commanding configured-to-order premiums while industrial-grade volumes trade on spot-market glucose cost indices. This lead-time stratification concentrates pricing power among fermentation specialists with validated pharmacopeial dossiers, forcing dual-sourcing investments from buyers seeking qualification redundancy.
Pricing Analysis
Configured-to-order premiums for USP-grade serine with embedded ICH Q7 compliance audits spread three-to-five-fold above standard food-grade crystalline powder. Certification tier and volume scale drive price differentiation, with cell culture media specifications commanding the steepest premiums due to Swissmedic and FDA traceability requirements. Pricing pressure stems from enzymatic glycine-to-serine biocatalysis threatening fermentation economics in non-pharmaceutical tiers. Nutritional supplement buyers exhibit highest price sensitivity, while biologics CDMOs absorb premium differentials for qualified supply security.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Rotterdam ports concentrate risk for glucose-derived fermentation inputs, with container availability swings amplifying working capital requirements for spot-market buyers. Supply concentrates in China, Germany, and Japan, with Shandong province fermentation clusters feeding industrial-grade demand while Basel and Singapore anchor pharmaceutical procurement. Corn glucose and precursor glycine feedstock dependencies tether margins to agricultural commodity cycles. Single-region concentration in Jiangsu and Shandong provinces creates geopolitical vulnerability for Western pharmaceutical buyers. Distribution runs through direct sales channels for API-grade material and e-commerce platforms for consumer formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in qualified supply chain documentation and pharmacopeial compliance consulting expand faster than base serine volumes, with biopharmaceutical buyers outsourcing REACH dossier maintenance and dual-qualification management.
For Market Incumbents: Fortify pharmacopeial qualification portfolios against enzymatic substitution threats by embedding continuous bioprocessing capabilities and securing backward integration into glucose sourcing. Ajinomoto and KYOWA HAKKO BIO should deepen captive fermentation engineering talent pipelines while pre-qualifying alternative supply origins under India's PLI scheme to mitigate Shandong concentration risk. For New Entrants and Emerging Players: Lead with cell culture media specialization as the most penetrable premium tier, where high-purity L-serine demand outstrips qualified supply from established fermentation specialists. Target Swiss and Singaporean biologics CDMOs with perfusion-compatible serine formats and pre-assembled USP-EP-ChP dossier packages to compress 12-18 month supplier qualification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fermentation assets and dormant pharmacopeial certifications. Five-to-ten year viability hinges on regulatory harmonization trajectories between FDA, EMA, and NMPA standards. Monitor EMA REACH enforcement intensity as the signal indicating acceleration in qualified supply chain investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion fermentation with real-time analytics miniaturizes GMP capital requirements for mid-scale entrants. |
| Backward Integration into Precursors | Evonik's captive glycine sourcing anchors European REACH compliance through chain-of-custody documentation. |
| Pharmacopeial Dossier Pre-Qualification | Pre-assembled USP-EP-ChP packages compress supplier onboarding timelines for biopharmaceutical procurement teams. |
| India PLI Scheme Alignment | Contract fermentation investment under pharmaceutical incentives diversifies API-grade supply beyond Chinese clusters. |
| Cell Culture Media Specialization | High-purity L-serine for biopharmaceutical raw materials remains underpenetrated relative to peptide synthesis demand. |
Research Methodology
Operator-level perspectives from fermentation plant managers, biopharmaceutical procurement leads, cell culture media formulators, and regulatory affairs directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA ICH Q7 guidance documents, EMA REACH compliance filings, NMPA PIC/S alignment notices, and customs trade data from Chinese amino acid export clusters. Bottom-up volume modeling triangulated against top-down pharmaceutical production forecasts.
Sensitivity analysis tested forecast robustness across glucose price volatility bands, enzymatic substitution penetration scenarios, and regulatory harmonization timelines. Segmentation dimensions modeled include product format, application tier, end-user specification stringency, and regional regulatory cluster. CAGRs derived from regression analysis against biologics manufacturing capacity expansion and peptide synthesis protocol adoption curves. Forecast inputs incorporated fermentation yield improvement trajectories and continuous bioprocessing adoption rates.
Forecasts assume regulatory continuity in FDA ICH Q7, EMA REACH, and NMPA PIC/S regimes; material policy shifts would require re-modeling. Corn price volatility, geopolitical disruption to Shandong-Jiangsu supply corridors, and step-change enzymatic conversion economics constitute primary revision triggers. Recalibration cycles align with material shifts in pharmacopeial harmonization, biologics manufacturing capacity, and fermentation technology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Global Adiponitrile Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Serine Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Phthalimide Market