
 Acrylamide Monomer Market | 2026-2036
Acrylamide Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylamide Monomer Market Intelligence
Modular supply contracts for liquid acrylamide solutions is shifting procurement patterns among municipal water authorities and oilfield service firms. BASF SE leverages backward integration into propylene feedstocks to secure margin control across European polymer chains. SNF Group dominates bulk flocculant supply to Middle Eastern desalination projects through captive manufacturing in Saudi Arabia. Kemira Oyj specializes in tailor-made polymer grades for Nordic pulp mills with strict adsorbable organic halogen limits.
Acrylamide monomer is an unsaturated amide synthesized primarily through catalytic hydration of acrylonitrile, typically yielding a white crystalline solid with molecular weight 71.08 g/mol and purity grades ranging from technical to specialty specifications below 0.05% residual monomer content. It serves as the fundamental building block for polyacrylamide polymers used in water clarification, enhanced oil recovery, and paper retention systems. Specialty grade formulations command premium positioning in pharmaceutical synthesis and food-grade polymer applications where residual monomer thresholds fall under pharmacopeial limits. Powder and granular forms retain structural dominance in oilfield logistics, while liquid solutions capture share in continuous-feed water treatment installations requiring minimal handling steps.
EPA drinking water regulations and REACH registration requirements in Europe enforce stringent residual monomer caps in polyacrylamide applications, directly elevating demand for ultra-low residual grades. China's SAMR and NMPA coordinate GB standard updates that restrict acrylamide migration in food-contact materials, compressing technical grade margins while expanding specialty certification programs. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging purity thresholds and disclosure obligations.
Market Dynamics
Water treatment utilities and oilfield operators are consolidating procurement around liquid acrylamide solutions, compressing spot markets for powder grades while elevating long-term contract structures. This shift is restructuring supplier relationships across municipal and industrial buyer segments.
Growth Catalysts
- EPA residual monomer caps:Drinking water regulations mandate ultra-low residual content in polyacrylamide flocculants, forcing upgrades to specialty-grade acrylamide feedstocks across US municipal systems.
- Enhanced oil recovery:Polymer flooding programs in mature reservoirs consume high-molecular-weight polyacrylamide, driving acrylamide demand through captive supply chains in petrochemical corridors.
- Shandong chemical corridor:China's concentrated acrylamide production base achieves scale economies that undercut dispersed manufacturing, capturing export volume into Southeast Asian water treatment markets.
Market Restraints
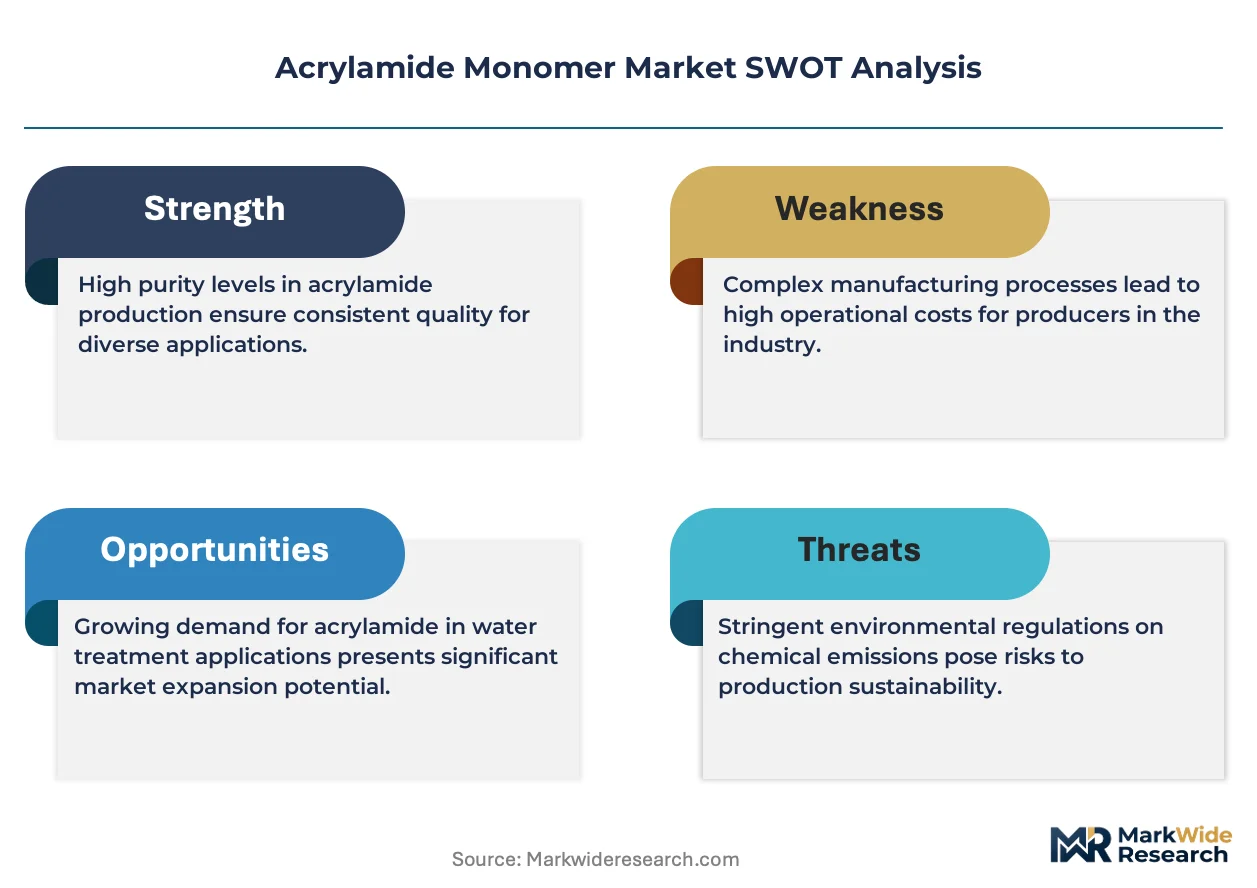
- Propylene feedstock volatility:Acrylonitrile production costs track propylene pricing from steam cracker operations, squeezing monomer margins during olefin cycle downturns.
- REACH registration friction:ECHA substance evaluation timelines extend market entry for new acrylamide suppliers, entrenching incumbent positions across European polymer chains.
- Biopolymer flocculants:Chitosan and starch-based alternatives gain traction in food-processing wastewater where acrylamide residuals face strictest scrutiny.
Strategic Opportunities
- Pharmaceutical synthesis:Ultra-high-purity grades below 0.01% residual monomer unlock peptide coupling and hydrogel applications under pharmacopeial certification.
- Modular liquid delivery:Continuous-feed skids at municipal plants eliminate powder handling, creating service-integrated supply models with multi-year contract locks.
- EU Green Deal chemistry:Bio-based acrylonitrile pathways from glycerol fermentation align with renewable carbon mandates in European polymer specifications.
Industry Challenges
- Process safety expertise:Acrylamide's neurotoxicity and polymerization hazards require specialized handling protocols that constrain workforce mobility between chemical sectors.
- Dual certification timelines:Food-contact and pharmaceutical grades demand parallel GB standard, FDA, and REACH compliance audits that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylamide Monomer Market |
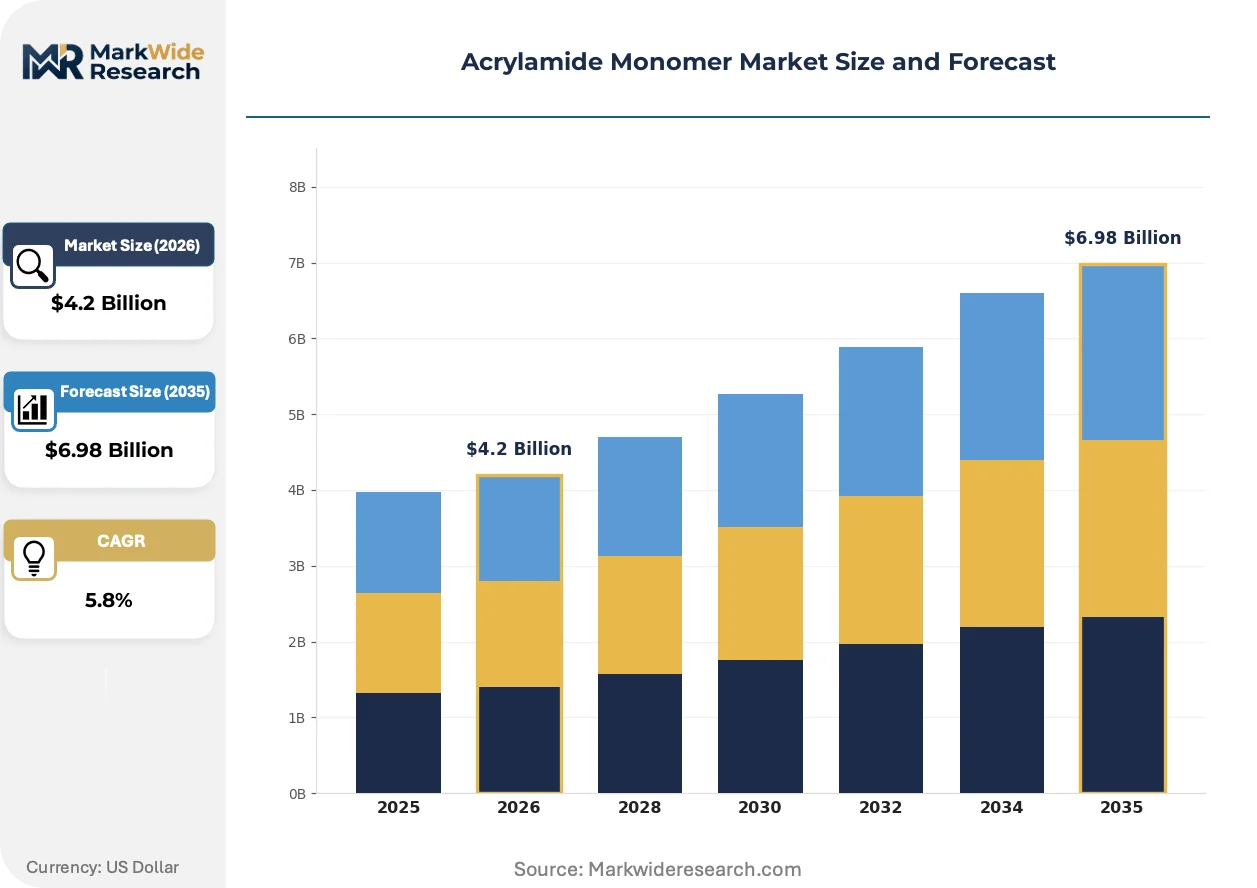
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Large Scale, Small Scale, Specialty Grade, Technical Grade Application: Coating, Adhesives, Textiles, Paper End User: Food Industry, Water Treatment, Oil & Gas, Pharmaceuticals Form: Liquid, Powder, Granular, Solution |
| Companies Covered | Beijing Hengju Chemical Group Corporation, Ashland, SNF Group, Ecolab Inc, INEOS, BASF SE, Kemira Oyj, Dia-Nitrix Co., Ltd, Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylamide Monomer Market Strategic Shifts & Innovations
Manufacturing and application technologies are converging around continuous processes and real-time quality verification, displacing batch-oriented production and offline testing protocols that dominated legacy supply chains.
Membrane bioreactor-integrated polymer dosing is converging with automated residual monitoring systems. Municipal water authorities in Germany and Japan are piloting closed-loop flocculation control that adjusts acrylamide-based polymer feed rates based on turbidity sensors. This convergence is compressing chemical consumption rates while tightening effluent compliance windows.
REACH authorization requirements for acrylamide monomer are tightening downstream disclosure obligations across European polymer formulators. Industrial users must now document residual content across supply tiers, elevating demand for certified low-monomer grades in paper retention and mining applications. Nordic pulp mills with strict adsorbable organic halogen limits are accelerating qualification of specialty-grade suppliers.
Specification-driven procurement is consolidating buyer power among national water utilities and integrated oilfield service firms. Long-term offtake agreements with fixed purity tiers are displacing spot purchasing for standard grades in North American and Middle Eastern markets. This concentration is most visible in Saudi desalination projects where captive manufacturing locks in decade-scale supply relationships.
Acrylamide Monomer Market Segmentation
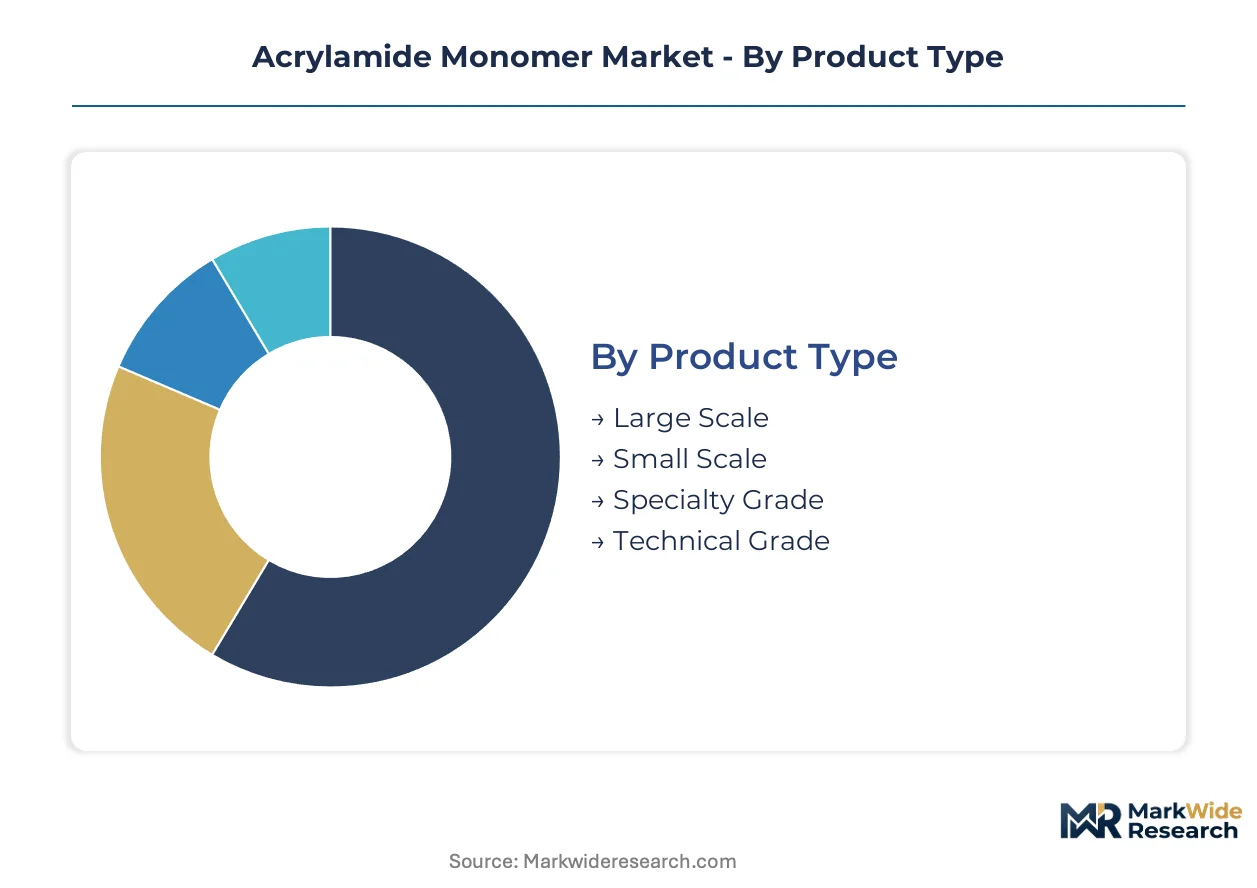
Acrylamide monomer specifications diverge sharply between commodity bulk supply and certified low-residual grades. Procurement patterns track these divides, with municipal water authorities favoring liquid delivery systems while oilfield operators retain powder logistics for remote deployment.
Product Type:
Integration depth varies substantially: large-scale and technical grades flow through standalone bulk chemical distribution, while specialty grades embed into tightly controlled pharmaceutical and food-contact supply chains with audit requirements.
- Large Scale:Bulk production volumes serve polymer manufacturers with continuous acrylonitrile hydration processes. Water treatment utilities across the US Gulf Coast petrochemical belt anchor procurement through multi-year offtake agreements with fixed purity tiers.
- Specialty Grade:Ultra-low residual formulations below 0.05% monomer content meet pharmacopeial and food-contact specifications. FDA and REACH compliance audits compress supplier pools to certified manufacturers with dedicated production lines.
- Small Scale:Batch quantities support research institutions and specialty polymer developers.
- Technical Grade:Standard purity serves industrial applications where residual thresholds remain less stringent.
Volume placements concentrate in large-scale bulk supply; the faster expansion belongs to specialty grade certification programs.
Application:
Cost tier stratification separates commodity coating applications from premium paper retention systems with strict adsorbable organic halogen limits.
- Coating:Surface treatment formulations for construction materials and industrial substrates. China's Shandong chemical corridor dominates export volume into Southeast Asian coating markets through scale economies.
- Paper:Retention and drainage aids for pulp mills with environmental compliance mandates. Nordic mills with strict adsorbable organic halogen limits drive qualification of specialty-grade suppliers.
- Adhesives:Pressure-sensitive and structural bonding applications across packaging and automotive assembly.
- Textiles:Sizing agents and finishing treatments for yarn strength and fabric hand modification.
Revenue concentration sits with paper processing chemicals; coating applications are climbing fastest on construction sector recovery.
End User:
Customer type maturity splits between established industrial sectors and emerging pharmaceutical synthesis with pharmacopeial certification barriers.
- Water Treatment:Municipal flocculation and industrial effluent clarification. EPA residual monomer caps mandate ultra-low content in polyacrylamide flocculants across US municipal systems.
- Oil & Gas:Enhanced oil recovery through polymer flooding in mature reservoirs. Captive supply chains in the US Gulf Coast and Middle Eastern desalination projects lock in decade-scale relationships.
- Food Industry:Food-contact polymers with strict migration limits under China's GB standards and FDA regulations.
- Pharmaceuticals:Peptide coupling reagents and hydrogel matrices requiring ultra-high purity below 0.01% residual monomer.
Contract value pools deepest in oil and gas procurement; pharmaceutical synthesis shows the steepest expansion trajectory.
Form:
Supply concentration favors liquid solutions for continuous-feed installations, while powder and granular forms retain structural importance in logistics-constrained environments.
- Liquid:Ready-to-use solutions eliminate handling steps at municipal treatment plants. Modular continuous-feed skids in Germany and Japan pilot closed-loop flocculation control with automated residual monitoring.
- Powder:Concentrated solid form optimizes transport economics to remote oilfield locations. Powder handling protocols address acrylamide's neurotoxicity hazards through specialized workforce training.
- Granular:Free-flowing particulate form for controlled dissolution in batch processing operations.
- Solution:Pre-diluted formulations for direct injection without on-site preparation infrastructure.
Procurement volume tilts toward liquid delivery systems; granular forms are gaining share fastest in automated dosing installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of acrylamide monomer feedstock while the United States and Germany absorb the highest-value polymer formulations. This production-consumption asymmetry shapes trade flows and regulatory arbitrage strategies across supplier networks.
China
Shandong Province's chemical corridor hosts concentrated acrylamide production serving water treatment and oilfield polymer demand. SAMR and NMPA coordinate GB standard updates that restrict residual monomer migration in food-contact materials, compressing technical grade margins. Qingdao and Weifang manufacturing clusters export bulk volumes into Southeast Asian flocculant markets.
United States
EPA residual monomer caps in drinking water regulations force municipal utilities toward ultra-low residual polyacrylamide grades. The US Gulf Coast petrochemical belt anchors captive supply chains for enhanced oil recovery polymer flooding programs. Houston-area formulators lock in multi-year offtake agreements with fixed purity tiers.
Germany
REACH registration requirements and ECHA substance evaluation timelines entrench incumbent suppliers across European polymer chains. BASF SE leverages backward integration into propylene feedstocks from Ludwigshafen operations to secure margin control. Municipal water authorities in Bavaria and North Rhine-Westphalia pilot membrane bioreactor-integrated polymer dosing with automated residual monitoring.
Saudi Arabia
SNF Group dominates bulk flocculant supply to Middle Eastern desalination projects through captive manufacturing in the Eastern Province. SFDA and national water authority procurement concentrates buyer power among integrated oilfield service firms. Jeddah and Riyadh municipal systems deploy specification-driven procurement with decade-scale supply relationships.
Japan
METI industrial standards and PMDA oversight elevate certification barriers for pharmaceutical-grade acrylamide applications. Kanto region water utilities in Tokyo and Yokohama implement closed-loop flocculation control systems with real-time turbidity sensors. Osaka-area pulp mills with strict adsorbable organic halogen limits accelerate qualification of specialty-grade suppliers.
Acrylamide Monomer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The supplier base stratifies into three tiers: integrated petrochemical majors with captive acrylonitrile supply, regional polymer formulators with formulation expertise, and specialty-grade pure-plays serving pharmaceutical and food-contact certifications. Capacity expansion and backward integration into propylene feedstocks constitute the dominant competitive moves, alongside modular liquid delivery service models that lock in municipal contract structures.
Among diversified chemical conglomerates, BASF SE and INEOS exemplify scale-driven positions anchored in European petrochemical infrastructure. SNF Group represents the focused specialist archetype with concentrated desalination and water treatment exposure. Kemira Oyj occupies a Nordic positioning tied to pulp and paper retention chemistry. These three entities span the strategic spectrum from feedstock-integrated majors to application-specific formulators.
| Leading Market Players |
|---|
| Beijing Hengju Chemical Group Corporation |
| Ashland |
| SNF Group |
| Ecolab Inc |
| INEOS |
| BASF SE |
| Kemira Oyj |
| Dia-Nitrix Co., Ltd |
| Mitsui Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
Specialized process safety expertise concentrated in Germany's Ludwigshafen chemical cluster and China's Shandong Province feeds labor-cost differentials that widen spreads between premium specialty grades and bulk technical formulations.
Pricing Analysis
Margin tightening in technical-grade tiers reflects propylene feedstock volatility from steam cracker operations. Pricing stratifies across specialty, standard, and economy tiers based on residual monomer certification and volume commitment scale. Cost-down pressure on bulk powder grades accelerates because municipal utilities are consolidating procurement around liquid delivery contracts. Water treatment authorities show highest price sensitivity, while pharmaceutical synthesis buyers absorb premiums for pharmacopeial certification.
Supply Chain Analysis
Single-source vulnerability sits with propylene supply from Gulf Coast petrochemical complexes. Manufacturing concentrates in China, the United States, and Germany. Production draws from acrylonitrile hydration processes tethered to olefin feedstock economics. Tariff exposure on acrylonitrile imports into Europe poses structural risk. Distribution runs through integrated polymer formulators with captive monomer supply and bulk chemical distributors serving spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into propylene feedstocks and forward integration into formulated polymer solutions constitute the dominant competitive race, with margin control hinging on captive acrylonitrile supply.
For Market Incumbents: Anticipate biopolymer flocculant substitution in food-processing wastewater by deepening certification investments for ultra-low residual grades. Lock in decade-scale offtake agreements with Saudi desalination authorities and US Gulf Coast oilfield operators to defend contract value pools against Chinese scale competitors. For New Entrants and Emerging Players: Launch via modular liquid delivery service models targeting municipal water authorities in Japan and Germany piloting closed-loop flocculation systems. Penetrate pharmaceutical synthesis segments where pharmacopeial barriers limit incumbent expansion. White-space exists in bio-based acrylonitrile pathways aligned with EU Green Deal mandates. For Investors and Strategic Acquirers: Re-rating potential sits with specialty-grade pure-plays given REACH authorization timelines entrenching incumbent positions. Long-term viability favors manufacturers with dedicated production lines for sub-0.01% residual monomer grades. Watch ECHA substance evaluation progress as inflection indicator for European market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene supply from Ludwigshafen operations secures margin control for BASF across European polymer chains. |
| Long-term Supply Agreement | Decade-scale contracts with Saudi national water authorities lock in flocculant volume for SNF Group's Eastern Province manufacturing. |
| Capacity Expansion | Shandong corridor scale economies undercut dispersed manufacturing and capture Southeast Asian export volume. |
| Green Manufacturing Transition | Bio-based acrylonitrile from glycerol fermentation aligns with renewable carbon mandates in EU polymer specifications. |
| Joint Venture | Captive manufacturing partnerships with Middle Eastern desalination projects concentrate buyer power among integrated oilfield service firms. |
Research Approach
Independent corroboration across plant managers at acrylamide manufacturing facilities, procurement leads at municipal water utilities, distribution channel partners serving oilfield operators, and technical R&D directors at polymer formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up demand modeling triangulates against top-down production capacity assessments.
Historical reference periods anchor volume and value trajectories across the analysis window. Segmentation dimensions include grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from slope-log analysis of normalized growth vectors. Forecast inputs incorporate propylene price cycle assumptions and regulatory approval timelines for specialty-grade certifications.
Feedstock price volatility, REACH authorization delays, and biopolymer substitution rates are the dominant revision risks. Forecasts reflect documented assumptions about olefin cycle positioning and purity standard convergence across jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Imidazole Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Serine Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Threonine Acids Market