
 2-Propylheptanol Market | 2026-2036
2-Propylheptanol Market Size, Share, and Industry Trends Forecast 2026-2036
2-Propylheptanol Market Analytics
Multi-source procurement among downstream plasticizer makers is consolidating around integrated C8-C10 alcohol suppliers. BASF SE leverages backward integration into oxo-synthesis to secure feedstock margins. Evonik Industries specializes in high-purity grades for pharmaceutical intermediates. Sinopec anchors regional supply through its coal-to-olefins platform in East China.
2-Propylheptanol is a branched C10 oxo-alcohol produced via hydroformylation of valeraldehyde or oligomerized propylene, yielding a primary alcohol with a boiling point near 215°C and low pour-point characteristics. Manufacturers deploy it primarily as a precursor for diester plasticizers and surfactant feedstocks where linear C9-C11 alcohols prove too crystalline. The plasticizers application leads volume absorption due to PVC compounding demand in wire insulation and flooring, while the surfactants segment registers faster expansion driven by personal care formulators seeking low-foam emulsifiers. Solvents occupy a mature niche with stable but thinning margins as waterborne coating systems displace solventborne formulations.
REACH registration obligations in Europe compel full toxicological dossiers for C10 alcohol imports, elevating compliance costs for non-EU producers. China's MEE enforces dual carbon goals that tighten energy intensity benchmarks at coal-based oxo plants, pushing capacity toward natural gas and bio-based routes. The EU F-Gas Regulation indirectly shapes demand by accelerating non-fluorinated polymer adoption in HVAC seals, where 2-propylheptanol-derived plasticizers substitute. Stakeholders must track feedstock carbon intensity disclosures as Scope 3 reporting under CSRD and China's emerging emissions trading scheme reshape supplier qualification criteria.
Market Dynamics
Feedstock carbon intensity disclosures are reshaping supplier qualification across the 2-propylheptanol value chain as Scope 3 reporting mandates from the EU CSRD and China's emerging emissions trading scheme force plasticizer manufacturers to document upstream emissions from oxo-synthesis routes.
Growth Catalysts
- REACH compliance pressures:European plasticizer formulators are pivoting toward C10 alcohols with established toxicological dossiers, favoring producers with pre-registered substances under ECHA frameworks.
- China's dual carbon goals:MEE energy intensity benchmarks at coal-based oxo plants are accelerating capacity migration toward natural gas and bio-based feedstock routes, improving lifecycle credentials for export-oriented derivatives.
- HVAC polymer substitution:The EU F-Gas Regulation is compressing fluorinated polymer adoption in sealing applications, expanding addressable demand for 2-propylheptanol-derived plasticizers in non-fluorinated compounds.
Market Restraints
- Propylene oligomerization cost volatility:Feedstock exposure to naphtha-cracking margins and propylene contract pricing creates margin compression for non-integrated oxo-alcohol producers.
- East China supply concentration:Coal-to-olefins platforms in Shandong and Jiangsu provinces control disproportionate C8-C10 alcohol capacity, amplifying disruption risk from regional energy rationing or environmental inspections.
- Waterborne coating displacement:Solventborne formulation decline in architectural and industrial coatings is thinning margins for 2-propylheptanol solvent grades as formulators migrate to aqueous systems.
Strategic Opportunities
- Pharmaceutical intermediate purity grades:High-purity C10 alcohol specifications for active pharmaceutical ingredient synthesis remain underpenetrated relative to commodity plasticizer applications.
- Personal care emulsifier expansion:Low-foam surfactant demand from premium skincare formulators in South Korea and Japan offers faster volume expansion than mature PVC compounding segments.
- Bio-based hydroformylation routes:Renewable naphtha and bio-propylene feedstocks are enabling carbon-intensity certifications that qualify suppliers for EU Green Deal procurement preferences.
Industry Challenges
- Oxo-synthesis process engineering expertise:Rhodium catalyst optimization and ligand selection for branched C10 selectivity require specialized technical talent concentrated at legacy European and US chemical engineering centers.
- REACH dossier maintenance timelines:ECHA substance evaluation procedures and updated toxicological endpoint requirements demand sustained regulatory affairs investment from non-EU exporters.
- Multi-tier supplier audit complexity:CSRD Scope 3 disclosure rules necessitate emissions verification across propylene oligomerization, syngas generation, and hydroformylation stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Propylheptanol Market |
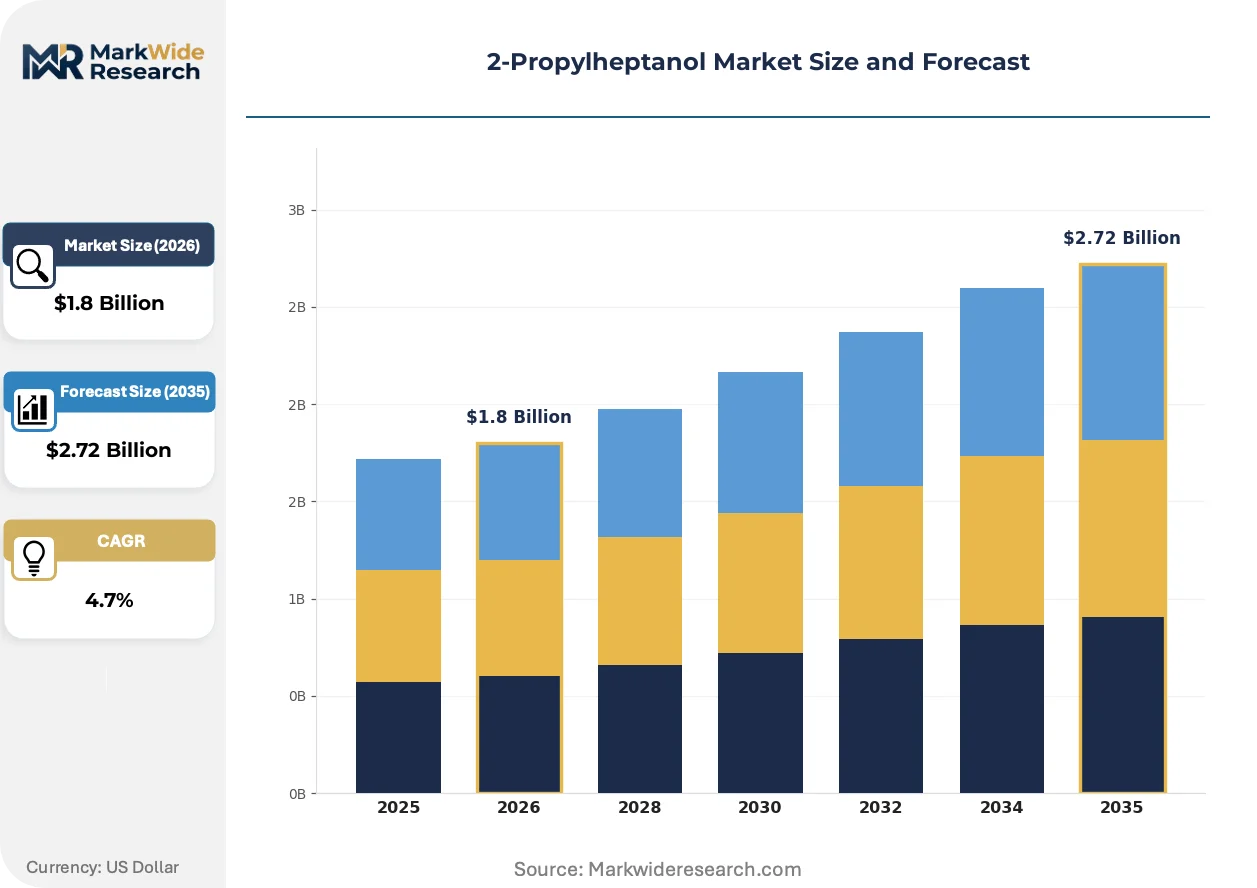
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Chemicals, Intermediates, Additives Application: Coatings, Plasticizers, Surfactants, Lubricants End User: Automotive, Personal Care, Consumer Goods, Pharmaceuticals Distribution Channel: Direct Sales, Online Sales, Distributors, Exporters |
| Companies Covered | Dow Chemical Company, PETRONAS Chemicals Group Berhad, Evonik Industries, Elekeiroz, Suzhou Vosun Chemical, BASF SE, Sinopec, Shandong Hanshen Chemical Technology, Perstorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Propylheptanol Market Evolving Landscape
Process intensification and feedstock diversification are compressing the traditional boundaries between petrochemical and bio-based oxo-alcohol production, while regulatory disclosure requirements are embedding carbon accounting into procurement specifications.
Modular hydroformylation reactor designs are decentralizing production economics for C10 alcohols. Mid-scale plasticizer compounders in Southeast Asia are adopting skid-mounted oxo units to reduce dependence on bulk import logistics. This distributed manufacturing model is compressing working capital requirements and enabling just-in-time derivative synthesis.
The EU F-Gas Regulation is accelerating refrigerant containment polymer reformulation. HVAC seal manufacturers are qualifying non-fluorinated elastomer compounds that rely on 2-propylheptanol-derived plasticizers for low-temperature flexibility. German automotive suppliers are responding fastest, driven by KBA type-approval timelines for climate-friendly vehicle architectures.
Carbon-intensity scoring is penetrating chemical procurement specifications. Wire and cable compounders in the Netherlands and Denmark are requiring documented Scope 3 emissions from C10 alcohol suppliers, with contract terms indexed to verified lifecycle assessments. This behavioral shift is most visible in Nordic markets where public infrastructure procurement mandates early adoption of CSRD-aligned supplier qualification protocols.
2-Propylheptanol Market Segmentation
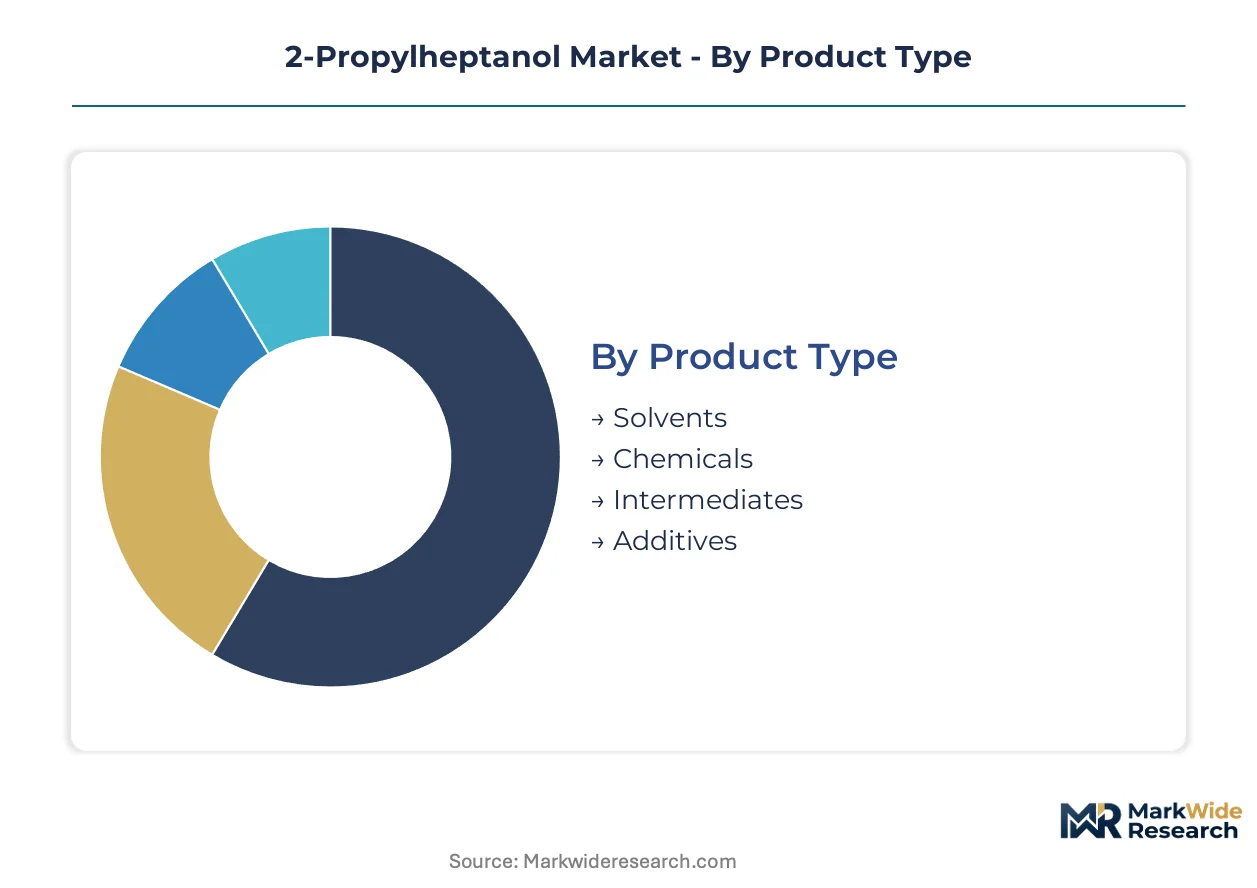
Segmentation in the 2-propylheptanol market reveals how capital deployment and technical specifications diverge across derivative grades. Manufacturers prioritize integrated production assets for high-volume plasticizer precursors while reserving batch capacity for pharmaceutical-grade specifications.
Product Type:
Capital intensity peaks at hydroformylation reactor clusters and distillation trains for high-purity grades, with intermediates commanding the heaviest fixed-asset commitments.
- Chemicals:Bulk oxo-alcohol output destined for commodity plasticizer synthesis requires continuous hydroformylation units with rhodium catalyst recovery systems. Demand concentrates at integrated petrochemical complexes in Germany and China where propylene feedstock arrives via pipeline.
- Intermediates:Purified C10 alcohol feedstocks for diester manufacturing absorb the largest share of dedicated tankage and analytical infrastructure. Automotive wire compounders in Japan and South Korea specify tight moisture specifications that constrain supplier qualification.
- Solvents:Technical-grade material for coating thinners carries lower purity thresholds and modest capital barriers.
- Additives:Functionalized derivatives for lubricant formulations occupy niche toll-manufacturing arrangements.
Most installed capacity flows through Chemicals. Expansion is steepest in Intermediates.
Application:
Volume concentration and margin structure split sharply between mature coating solvents and emerging surfactant formulations.
- Plasticizers:Di-2-propylheptyl phthalate and adipate esters dominate PVC compounding for wire insulation, flooring, and automotive seals. REACH-registered dossiers from ECHA-pre-registered suppliers command procurement preference at European compounders facing compliance audits.
- Surfactants:Low-foam emulsifiers derived from C10 alcohol ethoxylates are gaining formulation share at premium skincare manufacturers in South Korea. MFDS cosmetic ingredient notifications are accelerating qualification timelines for imported alcohol feedstocks.
- Coatings:Solventborne architectural and industrial applications face displacement pressure from waterborne systems.
- Lubricants:Synthetic ester base stocks for high-temperature applications remain a stable but limited outlet.
Plasticizers retain the dominant share of committed capacity. Surfactants are climbing the fastest.
End User:
Customer technical requirements range from pharmaceutical GMP compliance to commodity automotive specifications, fragmenting supplier service models.
- Automotive:HVAC seal and wire harness compounders specify low-temperature flexibility performance that 2-propylheptanol-derived plasticizers deliver in non-fluorinated elastomers. KBA type-approval timelines in Germany are compressing reformulation cycles.
- Pharmaceuticals:High-purity C10 alcohol for active pharmaceutical ingredient synthesis requires dedicated production lines with validated cleaning protocols. CDSCO import drug master file requirements in India are extending qualification lead times.
- Personal Care:Premium emulsifier demand from formulators in Japan favors low-foam surfactant specifications.
- Consumer Goods:Flexible PVC applications in packaging and household products absorb standard-grade material.
Automotive offtake commands the largest committed volumes. Pharmaceutical qualification represents the steepest expansion trajectory.
Distribution Channel:
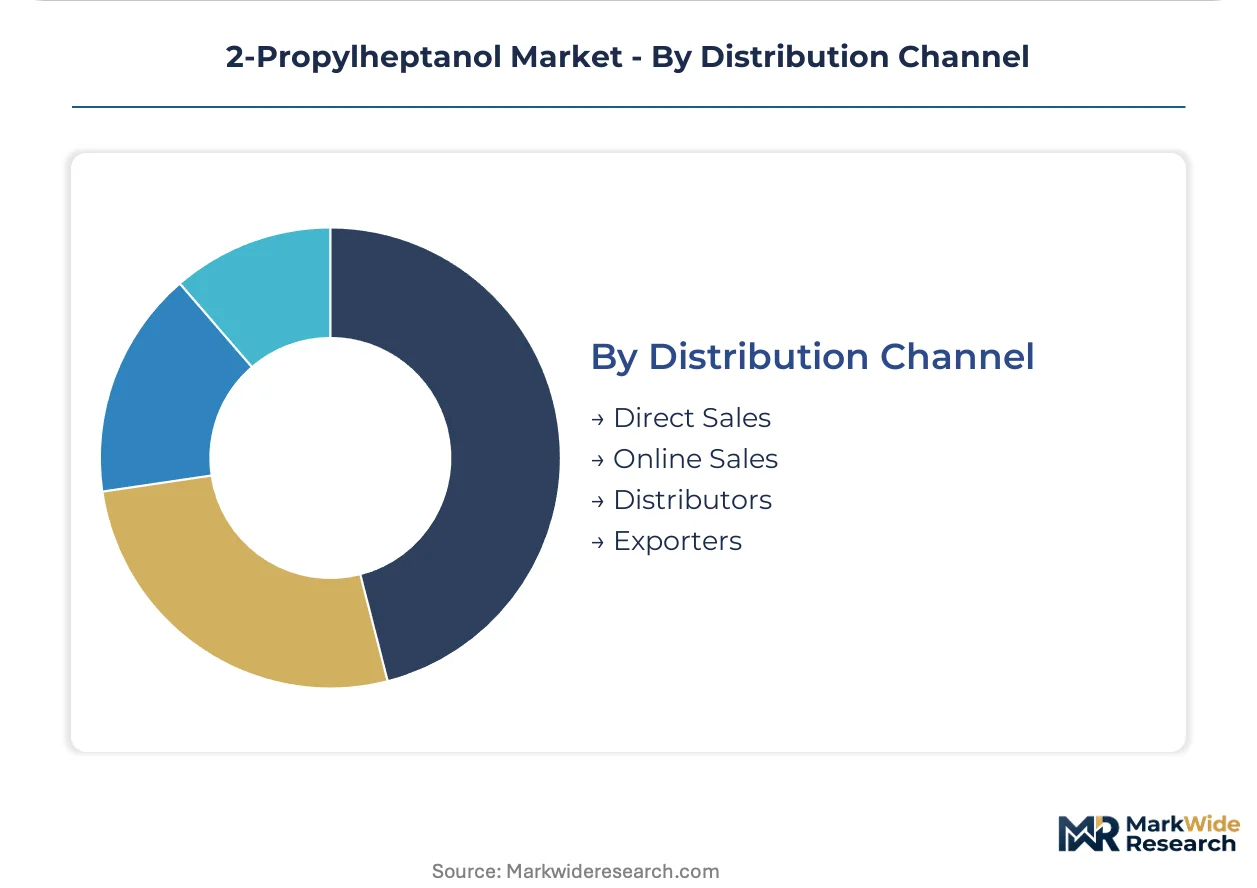
Logistics configuration and working capital intensity vary with shipment scale and geographic reach.
- Direct Sales:Bulk tanker deliveries from integrated producers to plasticizer compounders eliminate intermediary margins and enable just-in-time inventory management. Sinopec's coal-to-olefins platforms in East China leverage dedicated pipeline networks to downstream derivative plants.
- Distributors:Regional chemical distributors hold buffer stocks for mid-scale formulators lacking dedicated tankage. European distributors with ECHA-compliant documentation systems are consolidating share as REACH enforcement tightens.
- Exporters:Containerized shipments of drum-packaged material serve dispersed specialty chemical markets.
- Online Sales:Sample and small-lot procurement for R&D laboratories operates through B2B platforms.
Direct Sales channels handle the majority of volume throughput. Distributor networks are expanding most quickly in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's coal-to-olefins corridor commands the dominant share of installed oxo-alcohol capacity, with Shandong and Jiangsu provinces anchoring regional supply chains. German automotive compounders drive premium-grade demand through KBA-mandated refrigerant containment reforms. The United States maintains specialized production for pharmaceutical-grade specifications.
China
Shandong province's coal-to-olefins platforms absorb the majority of domestic C10 alcohol output for plasticizer synthesis. MEE energy intensity benchmarks are accelerating capacity migration toward natural gas feedstocks at Ningbo and Tianjin complexes. Yangtze River Delta compounders are consolidating procurement around integrated suppliers with verified carbon disclosures.
Germany
KBA type-approval timelines for climate-friendly HVAC architectures are compressing reformulation cycles at seal manufacturers. ECHA REACH dossier requirements favor pre-registered C10 alcohol suppliers with established toxicological endpoints. BASF's Ludwigshafen complex anchors European supply through backward integration into oxo-synthesis.
United States
EPA oversight of chemical manufacturing under TSCA shapes import qualification protocols for pharmaceutical-grade alcohols. Gulf Coast petrochemical corridors maintain specialized capacity for high-purity C10 intermediates. Dow Chemical's Texas operations exemplify integrated production models serving domestic plasticizer compounders.
South Korea
MFDS cosmetic ingredient notifications are accelerating qualification timelines for C10 alcohol ethoxylates in premium skincare formulations. Yeosu and Ulsan industrial clusters host surfactant manufacturers seeking low-foam emulsifier feedstocks. Domestic formulators are diversifying procurement away from single-source dependencies.
Japan
METI carbon accounting guidelines are embedding Scope 3 disclosure requirements into chemical procurement contracts. Chubu region automotive wire harness producers specify tight moisture thresholds for plasticizer-grade materials. Osaka-based surfactant specialists are expanding ethoxylate capacity for personal care applications.
2-Propylheptanol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based hydroformylation routes and modular reactor deployments. The supplier base concentrates around integrated petrochemical conglomerates with captive propylene feedstock access. Three archetypes dominate: backward-integrated majors with oxo-synthesis assets, regional specialists in high-purity grades, and toll manufacturers serving pharmaceutical specifications. Capacity expansion and carbon-intensity certification represent the primary competitive vectors.
Within the integrated majors tier, BASF SE and Sinopec exemplify divergent feedstock strategies—European natural gas-based routes versus Chinese coal-to-olefins platforms. Evonik Industries occupies a position among specialty-grade suppliers focused on pharmaceutical intermediate specifications. Among Asia-Pacific fabricators, PETRONAS Chemicals Group Berhad and Shandong Hanshen Chemical Technology represent national champion archetypes with regional supply chain anchoring.
| Leading Market Players |
|---|
| Dow Chemical Company |
| PETRONAS Chemicals Group Berhad |
| Evonik Industries |
| Elekeiroz |
| Suzhou Vosun Chemical |
| BASF SE |
| Sinopec |
| Shandong Hanshen Chemical Technology |
| Perstorp |
| Others |
Value Network & Pricing Analysis
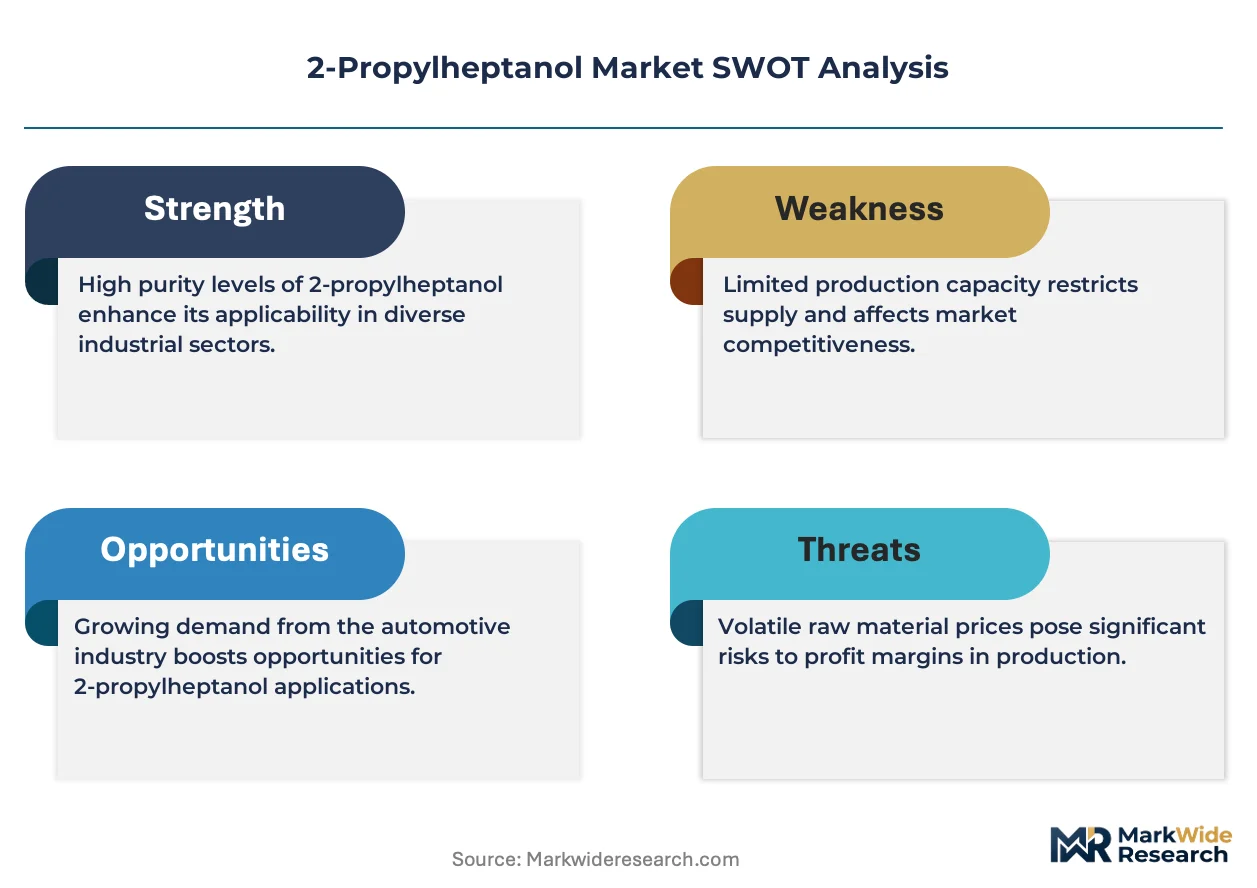
Rhodium catalyst costs cascade through hydroformylation economics into three distinct pricing tiers for C10 alcohol derivatives. Propylene feedstock volatility at naphtha-cracking margins compresses spot-market quotations for non-integrated compounders while contract-of-take agreements shield backward-integrated majors.
Pricing Analysis
Input-cost pass-through from propylene oligomerization and syngas generation governs contract negotiations between oxo-alcohol producers and downstream plasticizer compounders. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity solvent specifications reflects purity thresholds and certification burdens. Pricing pressure stems from waterborne coating displacement eroding solvent-grade margins. Commodity PVC compounders exhibit highest price sensitivity; pharmaceutical API manufacturers accept substantial premiums for validated supply chains.
Supply Chain Analysis
Reverse-logistics flows for spent rhodium catalyst recovery concentrate at specialized refiners in Germany and Belgium, closing the loop on precious-metal inputs. Manufacturing gravity centers on China, Germany, and the United States for divergent grade specifications. Feedstock dependencies span propylene from steam crackers, synthesis gas from coal gasification or natural gas reforming, and specialized phosphite ligands. Single-source vulnerability concentrates at East China coal-to-olefins platforms. Distribution runs through direct tanker delivery for bulk plasticizer precursors and regional distributor networks for drum-packaged specialty grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate at the premium-grade tier where pharmaceutical and personal care specifications command pricing power unavailable to commodity plasticizer suppliers.
For Market Incumbents: Lock in feedstock security through captive propylene access or long-term natural gas supply agreements as MEE energy intensity benchmarks squeeze coal-based competitors. Prioritize ECHA REACH dossier maintenance against substance evaluation timelines that threaten market access. Carbon-intensity certification investments qualify integrated producers for EU Green Deal procurement preferences emerging at Nordic wire and cable compounders. For New Entrants and Emerging Players: The premium-economy price-point gap in pharmaceutical-grade C10 alcohols offers white-space entry below Evonik Industries' positioning. Modular hydroformylation skids serving Southeast Asian surfactant manufacturers bypass capital barriers at integrated complexes. Bio-based hydroformylation routes using renewable naphtha qualify for EU procurement preferences with faster regulatory approval than petrochemical incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and CSRD Scope 3 disclosure requirements exceed standalone capabilities of regional distributors and toll manufacturers. Acquisition targets include mid-scale European compounders with ECHA-registered dossiers and verified carbon accounting systems. Monitor KBA type-approval timelines for climate-friendly HVAC architectures as inflection indicators for non-fluorinated elastomer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Synthesis | BASF SE's Ludwigshafen complex demonstrates margin capture from propylene pipeline access. |
| Bio-Based Hydroformylation Scale-Up | Renewable naphtha routes enable EU Green Deal procurement qualification for premium derivatives. |
| Modular Reactor Deployment | Skid-mounted units in Southeast Asia compress working capital for mid-scale surfactant producers. |
| Pharmaceutical-Grade Certification | Validated cleaning protocols and CDSCO drug master files extend qualification lead times as defensive moats. |
| Carbon-Intensity Verification | Scope 3 disclosure systems at Sinopec's Ningbo complex meet CSRD-aligned supplier protocols at Dutch compounders. |
Research Methodology
Coverage spans China, Germany, the United States, South Korea, and Japan, with primary inputs from each jurisdiction's oxo-alcohol production clusters and downstream derivative markets. Plant managers at coal-to-olefins complexes, procurement leads at PVC compounders, technical R&D directors at surfactant manufacturers, and regulatory affairs specialists at ECHA-registered suppliers provided operational data. Secondary validation drew from customs trade records, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and ECHA substance registration databases. Bottom-up capacity assessments triangulated against top-down demand modeling across plasticizer, surfactant, and pharmaceutical applications.
Granularity-level modeling distinguished pharmaceutical-grade, technical-grade, and commodity solvent specifications within product-type segmentation. End-use industries split across automotive wire harness compounders, personal care formulators, and HVAC seal manufacturers. Geographic production hubs tracked capacity at Shandong coal-to-olefins platforms, Ludwigshafen integrated complexes, and Gulf Coast petrochemical corridors. CAGRs derived from segment-level volume projections indexed to propylene supply growth and regulatory-driven substitution patterns. Feedstock carbon intensity disclosures and REACH registration status served as qualification filters in supplier share allocation.
Caveats apply where MEE energy rationing or environmental inspections at East China facilities could materially shift the outlook for C10 alcohol supply availability. Forecasts reflect assumptions about sustained KBA-mandated HVAC reformulation timelines and continued F-Gas Regulation enforcement accelerating non-fluorinated polymer adoption. Practitioners should monitor ECHA substance evaluation procedures and updated toxicological endpoint requirements for early signals of registration renewal burdens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Serine Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Tartrazine Market