
 Portable Milling Machine Market | 2026-2036
Portable Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Milling Machine Market Analytics
Remote diagnostics subscriptions bundled with portable milling units is rebalancing how vendors monetize equipment ownership. CLIMAX Portable Machining Tools Inc. anchors the high-reliability segment for energy sector field repairs. Enerpac Tool Group Corp. leverages its hydraulic tool ecosystem to cross-sell portable milling packages. Mactech Europe dominates aftermarket service contracts across North Sea offshore installations.
A portable milling machine is a transportable metal-cutting device that mounts directly onto workpieces in situ, typically achieving tolerances within 0.001 inches per foot and operating via electric, hydraulic, or pneumatic power sources for on-site machining of flanges, pads, and keyways. CNC portable units command premium positioning due to programmable repeatability in complex geometries, while manual variants retain share in cost-sensitive maintenance environments. Repair applications generate the deepest margin pools as turnaround-time penalties far exceed equipment rental costs for petrochemical and maritime clients.
OSHA lockout/tagout rules and the EU Machinery Directive shape guarding and interlock requirements for portable equipment sold into transatlantic markets. China's GB standards and Japan's METI technical conformity framework add compliance layers for Asian sourcing and certification paths. Stakeholders must weigh regional certification divergence against platform standardization when configuring global product portfolios.
Market Dynamics
Remote diagnostics subscriptions bundled with portable milling units is rebalancing how vendors monetize equipment ownership, shifting revenue from upfront sales toward recurring service streams anchored by predictive maintenance algorithms.
Growth Catalysts
- On-site maintenance contracts:Shipyards and offshore energy operators are expanding long-term service agreements that embed portable milling capacity within turnaround schedules.
- ISO 8528 certification tightening:Machinery safety codes in Germany, Japan, and the United States are elevating entry barriers for uncertified equipment, favoring established suppliers with compliance infrastructure.
- Electric powertrain maturation:Battery-electric portable mills are penetrating indoor petrochemical maintenance environments where hydraulic fluid containment poses operational risks.
Market Restraints
- High-precision spindle supply concentration:German and Japanese bearing manufacturers control critical component supply, exposing assemblers to extended lead times.
- Skilled field machinist scarcity:The specialized trade certification pipeline in North America and Europe cannot match replacement demand from retiring technicians.
- EU Machinery Directive compliance costs:Guarding and interlock requirements for transatlantic sales add engineering overhead that manual-variant producers struggle to absorb.
Strategic Opportunities
- Floating offshore wind installation surge:Foundation flange machining at sea creates demand for stabilized portable milling platforms in the North Sea and US Atlantic lease areas.
- India's PLI scheme for capital goods:Domestic manufacturing incentives are drawing component suppliers to establish spindle and drive assembly capacity near Mumbai-Pune industrial corridor.
- AR-guided setup protocols:Augmented reality overlays are reducing technician training time for complex keyway alignment procedures in remote maintenance environments.
Industry Challenges
- CNC programming skill gaps:Field technicians with manual machining backgrounds require substantial retraining to operate programmable portable units effectively.
- Multi-jurisdiction certification lag:Simultaneous compliance with OSHA lockout/tagout rules, EU Machinery Directive, and Japan's METI technical conformity framework extends product launch timelines.
- Legacy equipment integration friction:Retrofitting digital telemetry onto hydraulic portable mills in existing rental fleets demands hardware redesign without obsoleting installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Milling Machine Market |
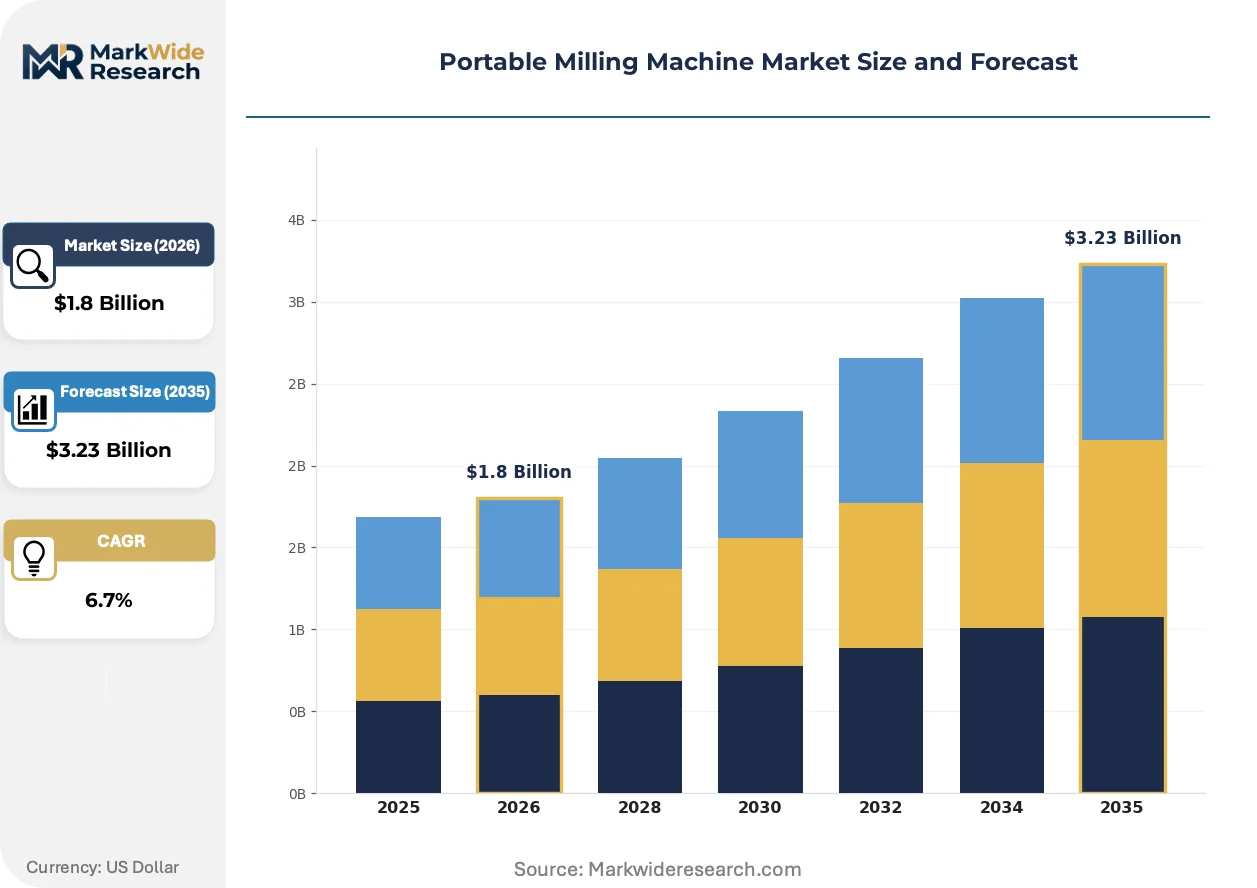
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, CNC, Manual End User: Aerospace, Automotive, Construction, Metalworking Technology: Conventional, Laser, Ultrasonic, Plasma Application: Repair, Fabrication, Maintenance, Prototyping |
| Companies Covered | CLIMAX Portable Machining Tools Inc., Enerpac Tool Group Corp., Mactech Europe, CS Unitec, Tri Tool Inc., Thermotech AS, Normaco, Field Machine Tools (FMT), Dongguan Portable Tools Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Milling Machine Market Evolving Landscape
Electrification of portable milling platforms is compressing the performance gap between field-deployable units and fixed-shop machining centers, while regulatory harmonization pressures and subscription-based service models are restructuring competitive differentiation.
Brushless DC spindle drives with integrated variable frequency control are electrifying portable milling performance envelopes. Offshore wind turbine maintenance contractors in the North Sea are adopting these systems for nacelle flange repair campaigns. The technology is electrifying what had been pneumatic-dependent applications, expanding electric unit addressable market share in previously hydraulic-dominated segments.
REACH substance restrictions on lubricating oils are forcing reformulation of bearing greases used in portable milling spindles sold into European markets. German component suppliers are certifying synthetic alternatives that maintain temperature stability under intermittent duty cycles. Portable mill assemblers serving EU energy sector clients are qualifying these lubricants to avoid machinery registration delays.
Condition-monitoring telemetry is unbundling after-sales service from equipment ownership. Petrochemical operators on the US Gulf Coast are subscribing to vibration-analysis dashboards rather than purchasing standalone maintenance packages. This shift is most visible among integrated refinery operators seeking to standardize turnaround planning across multiple facility sites.
Portable Milling Machine Market Segmentation
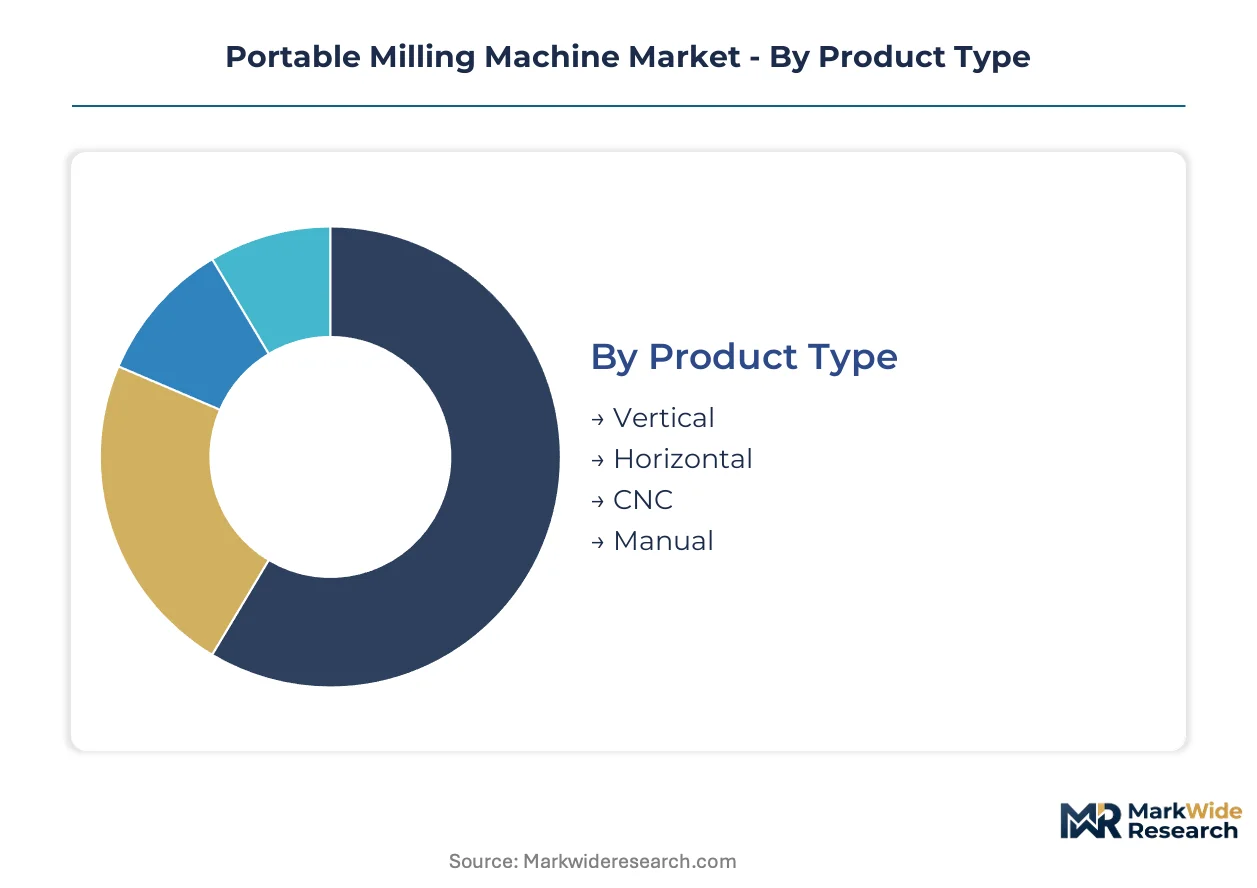
Portable milling machine segmentation reveals how equipment specifications align with distinct operational environments and compliance burdens. Each dimension—product architecture, end-user vertical, cutting technology, and application purpose—carries unique supply chain and certification implications that shape vendor positioning.
Product Type:
Spindle and bearing supply concentrates among German and Japanese manufacturers, elevating procurement leverage for CNC-capable platforms over manual variants.
- CNC:Programmable repeatability enables complex geometry machining with tolerances within 0.001 inches per foot. Demand clusters among North Sea offshore wind contractors facing tight turnaround windows where rework penalties exceed rental premiums.
- Manual:Mechanical simplicity reduces field failure modes and technician certification requirements. Cost-sensitive maintenance environments in US Gulf Coast petrochemical clusters retain substantial share due to faster technician deployment.
- Vertical:Gravity-assisted chip evacuation suits flange-facing applications on horizontal mounting surfaces common in shipyard deck repairs.
- Horizontal:Arbor-mounted cutters access vertical workpiece faces for keyway machining in turbine foundation installations.
Today's leader: CNC. Tomorrow's challenger: Manual variants with AR-guided setup bridging skill gaps.
End User:
Margin capture varies sharply by vertical, with aerospace and offshore energy commanding premium positioning against construction's price-sensitive rental economics.
- Aerospace:Nadcap-accredited field machining for airframe jigs and landing gear bores demands traceable calibration chains. German industrial corridor operators prioritize ISO 8528-compliant units for turbine casing repairs.
- Metalworking:General fabrication shops drive volume but compress pricing through competitive tendering for standard keyway and pad machining contracts.
- Automotive:Press die maintenance and prototype tooling fixes require rapid spindle speed adjustment for hardened steel alloys.
- Construction:Infrastructure steel erection tolerances accept wider margins, favoring rental-fleet economics over precision specifications.
Aerospace claims the steepest expansion trajectory as OEMs outsource more field repair capacity. Construction faces margin compression from equipment-as-a-service pricing.
Technology:
Power source selection determines regulatory exposure, with electric architectures penetrating environments where hydraulic fluid containment imposes operational risk.
- Conventional:Electric, hydraulic, and pneumatic mechanical drives dominate installed base with proven field service infrastructure.
- Laser:Thermal cutting without mechanical contact enables thin-walled component machining where spindle deflection risks distortion.
- Ultrasonic:High-frequency vibration-assisted cutting reduces cutting forces for hardened superalloys in turbine blade repair applications.
- Plasma:High-velocity ionized gas suits roughing operations on thick plate where precision tolerance is secondary to material removal rate.
Conventional systems anchor current revenue. Ultrasonic methods are climbing the fastest as superalloy machining demands intensify.
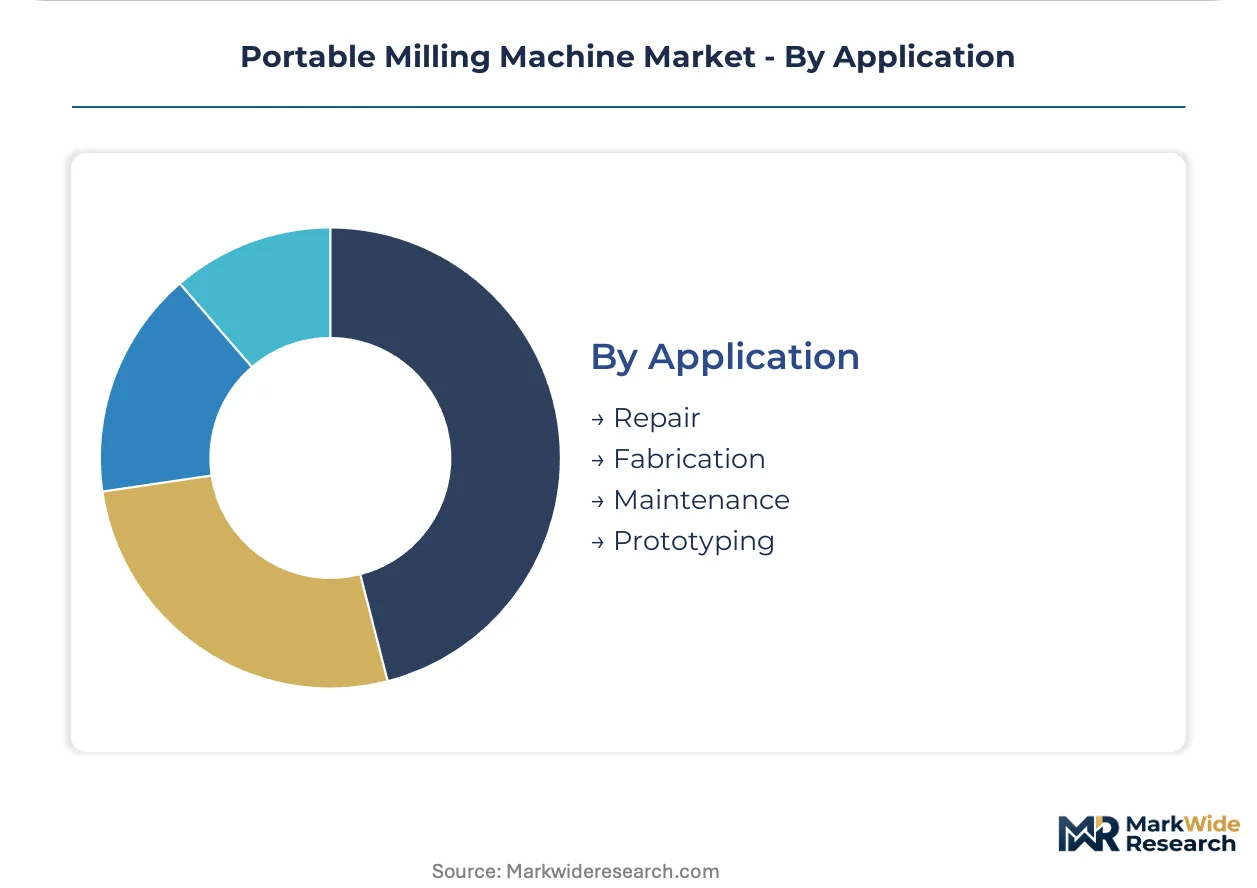
Application:
Repair applications generate the deepest margin pools as turnaround-time penalties for petrochemical and maritime clients far exceed equipment rental costs.
- Repair:In-situ flange resurfacing and keyway restoration eliminates workpiece transport to fixed machine shops. US Gulf Coast refineries embed portable milling capacity within turnaround contracts to avoid production loss.
- Maintenance:Scheduled preventive machining of mounting pads and wear surfaces extends asset life without process interruption.
- Fabrication:Greenfield construction projects use portable units for field-fit adjustments where shop tolerances prove insufficient.
- Prototyping:Low-volume validation machining allows design iteration without dedicated fixture investment.
Repair commands premium positioning. Prototyping is gaining share fastest as digital twin validation reduces physical iteration cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing portable milling machine assembly capacity toward jurisdictions with streamlined machinery certification pathways, particularly as EU Machinery Directive compliance costs widen the cost-of-compliance gap against Asian manufacturing bases.
Germany
Offshore wind turbine foundation machining and shipyard flange repair contracts drive demand concentration along the North Sea and Baltic coasts. The country's Federal Institute for Occupational Safety and Health enforces ISO 8528 certification requirements that elevate entry barriers for imported equipment. Industrial clusters in Hamburg and Bremerhaven host specialized field machining service providers serving North Sea energy installations.
United States
Petrochemical turnaround schedules on the Gulf Coast and aerospace field repair contracts generate premium pricing for rapid-deployment portable mills. OSHA lockout/tagout rules govern guarding and interlock specifications for equipment sold into domestic energy sector applications. The Houston-Galveston maintenance corridor concentrates rental fleet operators and on-site machining contractors.
Japan
Precision component remanufacturing for automotive press dies and turbine casing repairs sustains demand for high-tolerance portable machining. METI technical conformity framework adds certification layers for equipment sourced from non-Japanese suppliers. Nagoya's industrial corridor hosts precision spindle manufacturers supplying domestic portable mill assemblers.
China
Domestic infrastructure steel erection and shipbuilding maintenance programs absorb volume-oriented portable milling capacity. GB standards machinery safety codes are tightening parallel to international certification requirements for export-bound equipment. The Yangtze River Delta manufacturing belt concentrates component suppliers producing drive assemblies and spindle housings.
India
Refinery maintenance contracts and port infrastructure repair projects are expanding addressable demand for cost-optimized portable machining solutions. The PLI scheme for capital goods is drawing spindle and drive assembly suppliers to establish production near the Mumbai-Pune industrial corridor. Domestic fabrication yards in Gujarat and Maharashtra are qualifying local portable mill equipment for petrochemical client specifications.
Portable Milling Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated tool conglomerates capturing premium positioning in energy sector applications while regional fabricators dominate price-sensitive rental markets. The vendor base organizes into three tiers: precision specialists with Nadcap-accredited field machining capabilities, diversified industrial tool groups leveraging cross-selling infrastructure, and volume-oriented regional assemblers serving emerging market maintenance sectors. Consolidation pressure concentrates among mid-scale operators facing certification cost absorption challenges, while technology licensing agreements and strategic distribution partnerships represent the dominant competitive moves for market access expansion.
Within the precision-specialist tier, CLIMAX Portable Machining Tools Inc. and Mactech Europe exemplify archetypes anchored in high-reliability energy sector positioning, with the former representing North American field repair infrastructure and the latter occupying a position within North Sea offshore maintenance ecosystems. Enerpac Tool Group Corp. sits within the diversified industrial tool group archetype, leveraging hydraulic tool ecosystem integration to cross-sell portable milling packages. Among regional fabricators, Dongguan Portable Tools Co., Ltd. represents the volume-oriented Asian manufacturing base archetype.
| Leading Market Players |
|---|
| CLIMAX Portable Machining Tools Inc. |
| Enerpac Tool Group Corp. |
| Mactech Europe |
| CS Unitec |
| Tri Tool Inc. |
| Thermotech AS |
| Normaco |
| Field Machine Tools (FMT) |
| Dongguan Portable Tools Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ISO 8528-compliant units and uncertified alternatives manifests in both margin capture and procurement patterns, with German and Japanese spindle suppliers commanding premium positioning while Asian component assemblers feed cost-optimized manual variants. This bifurcation concentrates pricing power upstream with bearing manufacturers and downstream with rental fleet operators who bundle predictive maintenance subscriptions.
Pricing Analysis
Distributor margins on CNC portable milling units typically absorb 15-25 points before reaching end-users, while direct-to-OEM contracts for shipyard maintenance fleets trade volume discounts for multi-year service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-accredited aerospace suppliers from Gulf Coast petrochemical rental operators and emerging market construction fabricators. Pricing pressure stems from battery-electric powertrain commoditization as brushless DC drives penetrate hydraulic-dominated segments. Construction rental fleets exhibit highest price sensitivity, while offshore wind contractors prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements from North Sea energy operators mandate qualification of both German and Japanese spindle suppliers, extending procurement cycles but mitigating single-source vulnerability during bearing allocation crunches. Component assembly concentrates in Germany, Japan, and China, with precision grinding and heat treatment remaining captive to established industrial corridors. Critical inputs include high-speed steel cutters, ceramic hybrid bearings, and synthetic lubricants reformulated for REACH compliance. Tariff exposure on Chinese-manufactured drive housings threatens cost structures for volume-oriented manual variants. Distribution runs through specialized industrial tool distributors and OEM-direct service contracts, bypassing generalist retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable milling machine demand functions as a stable compounder anchored by irreplaceable in-situ machining requirements across energy infrastructure maintenance cycles. Regulatory certification tightening and skilled technician scarcity create durable competitive moats for established suppliers.
For Market Incumbents: Lock in long-term spindle supply agreements with German and Japanese bearing manufacturers before allocation constraints intensify, while embedding remote diagnostics subscriptions into standard rental contracts to capture recurring revenue streams. Battery-electric product line expansion and AR-guided technician training modules address emerging substitute threats from simplified manual variants. For New Entrants and Emerging Players: India's PLI scheme for capital goods opens a window for domestic spindle and drive assembly capacity near the Mumbai-Pune corridor, bypassing import duty exposure on complete units. Target refinery maintenance contracts in Gujarat and Maharashtra with cost-optimized manual variants qualified to petrochemical client specifications, leveraging local fabrication relationships as the primary go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-specialist field machining service providers holding Nadcap accreditation and North Sea offshore maintenance relationships, given consolidation pressure on mid-scale operators facing ISO 8528 compliance cost absorption challenges. Watch floating offshore wind foundation installation timelines as the inflection indicator for stabilized platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AR-Guided Setup Protocol Deployment | Augmented reality overlays reduce technician training time for complex keyway alignment in remote maintenance environments. |
| Remote Diagnostics Subscription Bundling | Vibration-analysis dashboards shift revenue from equipment sales toward recurring service streams anchored by predictive algorithms. |
| Battery-Electric Powertrain Certification | Brushless DC spindle drives penetrate indoor petrochemical environments where hydraulic fluid containment poses operational risks. |
| Dual-Spindle Supplier Qualification | Parallel German and Japanese bearing sourcing mitigates allocation vulnerability during high-precision component crunches. |
| PLI Scheme Manufacturing Localization | Domestic spindle and drive assembly capacity near Mumbai-Pune reduces import duty exposure for Indian market penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Gulf Coast refineries, plant engineers in German industrial corridors, aftermarket service heads at North Sea offshore operators, and OEM procurement teams at shipyard clusters with secondary validation. Secondary sources included customs and trade data on spindle and bearing imports, SEC filings from diversified industrial tool groups, energy sector turnaround scheduling databases, and machinery safety certification registries. Bottom-up equipment shipment tracking and top-down maintenance contract value analysis were triangulated to anchor market sizing.
Comparable-period anchoring linked forward projections to historical equipment deployment patterns across petrochemical turnaround cycles and offshore wind installation timelines. Segmentation modeling spanned product architecture, end-user vertical, power source technology, and application purpose, with regional regulatory clusters treated as distinct demand determinants. CAGRs were derived from equipment replacement rates, subscription service attach trends, and emerging application penetration curves across the projection horizon. Industry-specific inputs included skilled machinist certification pipeline data and floating offshore wind foundation deployment schedules.
Revisions become necessary when floating offshore wind installation timelines accelerate or stall, when REACH substance restrictions expand to additional lubricant categories, or when battery-electric powertrain performance envelopes compress further against hydraulic alternatives. Deviation in German and Japanese spindle manufacturer capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Asia Pacific Power Tools Market
Tools
Multi Wire Cutting Machine Market
Tools
Manual Cutting Equipment Market
Tools
Gear Hobbing Cutter Market
Tools
Sand Control Tools Market
Tools
Press Machine Market
Tools
Metal Cutting Machine Market
Tools
Global DC Torque Tool Market
Tools
Woodworking CNC Tools Market
Tools
Key Cutting Machine Market
Tools
Gear Cutting Machines Market
Tools
Rotary Tools Market
Tools
Europe Power Tools Market
Tools
Turning Tools Market
Tools
Gas Cutting Machine Market
Tools
Dumpy Level Market