
 Canning Jars Market | 2026-2036
Canning Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Canning Jars Market Outlook
Artisan food production is consolidating as the fastest-growing end-use vertical for canning jars, displacing traditional household bulk purchasing. Ball Corporation leverages its century-old brand heritage to dominate North American retail channels for home preserving supplies. Owens-Illinois sustains manufacturing scale across multiple continents, supplying standardized glass containers to industrial food packagers. Ardagh Group competes through specialized decoration and lightweighting technologies that appeal to premium commercial buyers.
Canning jars are rigid cylindrical containers, typically manufactured from soda-lime glass or food-grade polyethylene terephthalate, designed to withstand thermal processing temperatures up to 250°F while maintaining vacuum or pressure-sealed integrity for shelf-stable food preservation. Glass jars retain dominant share among artisan and household end users due to chemical inertness and reusability, though plastic jars gain traction in commercial settings where weight reduction and shatter resistance reduce logistics costs. Wide mouth jars command premium positioning in the artisan segment because they accommodate whole fruits and facilitate hand-filling operations that small-batch producers prefer.
FDA food contact substance regulations govern migration limits for glass and plastic jar materials in the United States, while the EU Packaging and Packaging Waste Directive shapes recyclability mandates for European suppliers. OSHA workplace standards influence industrial-scale filling and capping line configurations that jar manufacturers must accommodate. Stakeholders should monitor evolving extended producer responsibility frameworks and state-level deposit return schemes that could reshape material economics between glass and plastic alternatives.
Market Dynamics
The artisan food sector's pivot toward premium glass packaging is compressing traditional household bulk purchasing, while FDA food contact substance regulations and tightening state-level cottage food laws force material compliance upgrades across the supply chain.
Growth Catalysts
- Artisan food production:Small-batch producers in the Pacific Northwest United States drive demand for wide mouth and decorated glass formats that support hand-filling operations and premium shelf presence.
- FDA food contact regulations:Migration limit standards for glass and plastic materials are pushing manufacturers toward higher-purity soda-lime formulations that command price premiums from safety-conscious buyers.
- Craft food culture clustering:Urban preserving workshops and farmers market distribution networks in Portland, Seattle, and Vancouver are normalizing reusable glass as a brand differentiator for specialty food startups.
Market Restraints
- Natural gas price volatility:Soda-lime glass manufacturing depends on fossil fuel-fired furnaces, exposing producers to input cost swings that erode margin stability at mid-tier price points.
- Single-source silica sand concentration:High-purity sand deposits in specific Midwestern United States counties create geographic supply vulnerability for domestic glass manufacturers.
- Polyethylene terephthalate substitution:Commercial food packagers are migrating toward plastic jars where weight reduction and shatter resistance outweigh reusability premiums in logistics economics.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging state-level deposit return schemes in Oregon and Maine create circular economy infrastructure that favors reusable glass over single-use alternatives.
- Lightweighting technology convergence:Advanced forming techniques combined with thin-wall structural design enable material cost reductions without sacrificing thermal processing integrity.
- Direct-to-consumer subscription channels:Specialty food brands are bypassing retail intermediaries through jar-return programs that lock in recurring revenue and capture end-of-life container value.
Industry Challenges
- Hot-end coating technician shortage:Specialized furnace operators who manage tin oxide surface treatments for scratch resistance are retiring faster than training programs replace them.
- OSHA compliance capex burden:Industrial-scale filling line configurations require capital-intensive guarding and ventilation upgrades that strain smaller glass fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canning Jars Market |
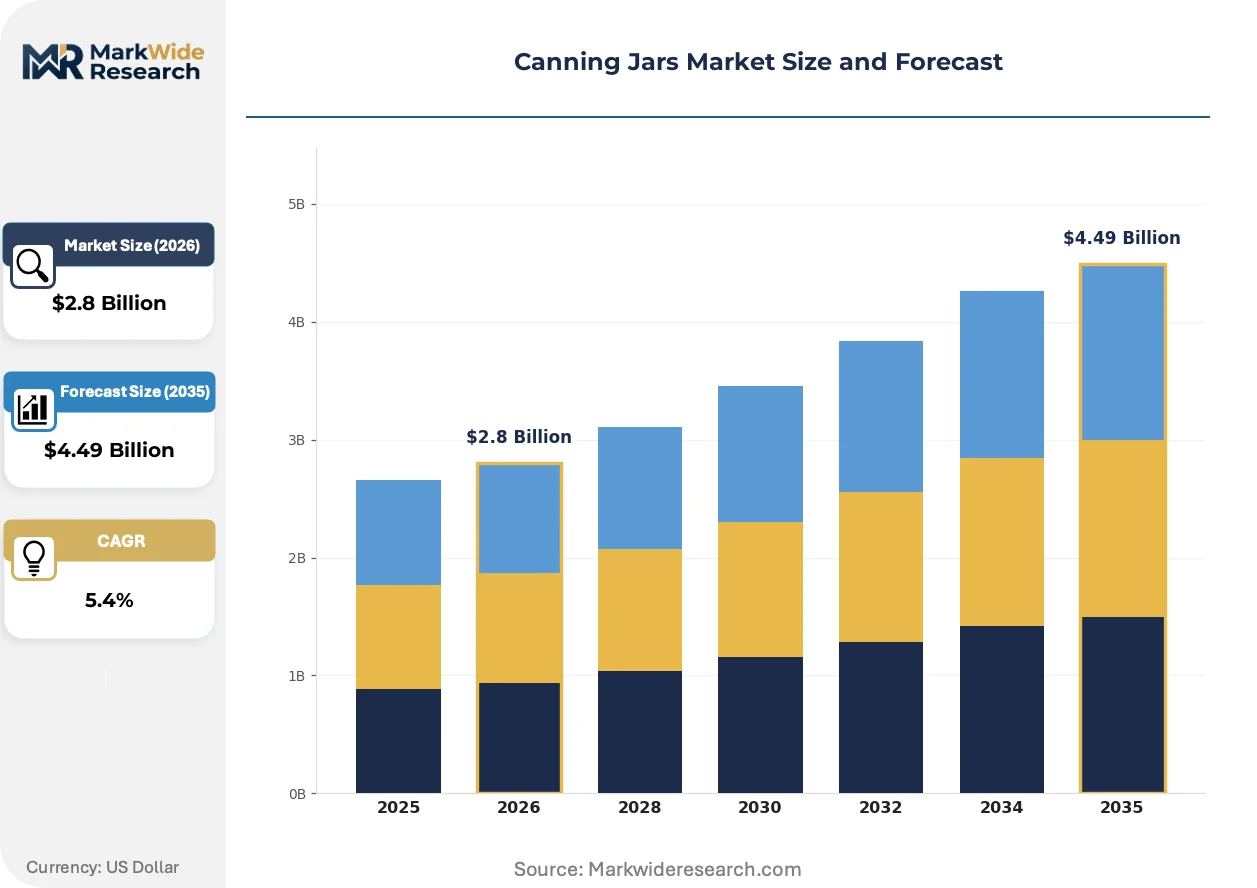
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Jars, Plastic Jars, Wide Mouth Jars, Regular Mouth Jars End User: Household, Commercial, Industrial, Artisan Capacity: 8 oz, 16 oz, 32 oz, 64 oz Closure Type: Metal Lids, Plastic Lids, Vacuum Seals, Twist-off Caps |
| Companies Covered | Verallia, Anchor Hocking, Ball Corporation, Berlin Packaging, Libbey, Owens-Illinois, Newell Brands, Fillmore Container, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canning Jars Market Strategic Shifts
Digital printing and smart labeling technologies are transforming how canning jars communicate provenance and handling instructions, while lightweighting advances compress material intensity without sacrificing performance thresholds.
Laser-etched batch coding is rewriting traceability standards for artisan food producers. Small-batch operations in Washington State and Oregon are adopting direct-to-glass marking systems that eliminate paper label adhesives and enable infinite design variations per production run. This technology is compressing minimum order quantities and enabling hyper-local branding strategies that were previously uneconomical at small scale.
The EU Packaging and Packaging Waste Directive is mandating recyclability thresholds that reshape supplier qualification criteria for European glass exporters. Industrial food packagers must now document closed-loop recovery rates and recycled content percentages to maintain shelf access in member states. German and French retail chains are responding by preferencing lightweighted glass formats that reduce transport emissions and packaging mass per unit.
Subscription-based jar return programs are disrupting traditional procurement patterns among specialty food startups. Direct-to-consumer brands in the Pacific Northwest are replacing one-time bulk purchases with circular service models where consumers pay per use and return empties via mail or drop-off networks. This behavior is most visible in fermented foods and preserves categories where brand loyalty and environmental positioning overlap.
Canning Jars Market Segmentation
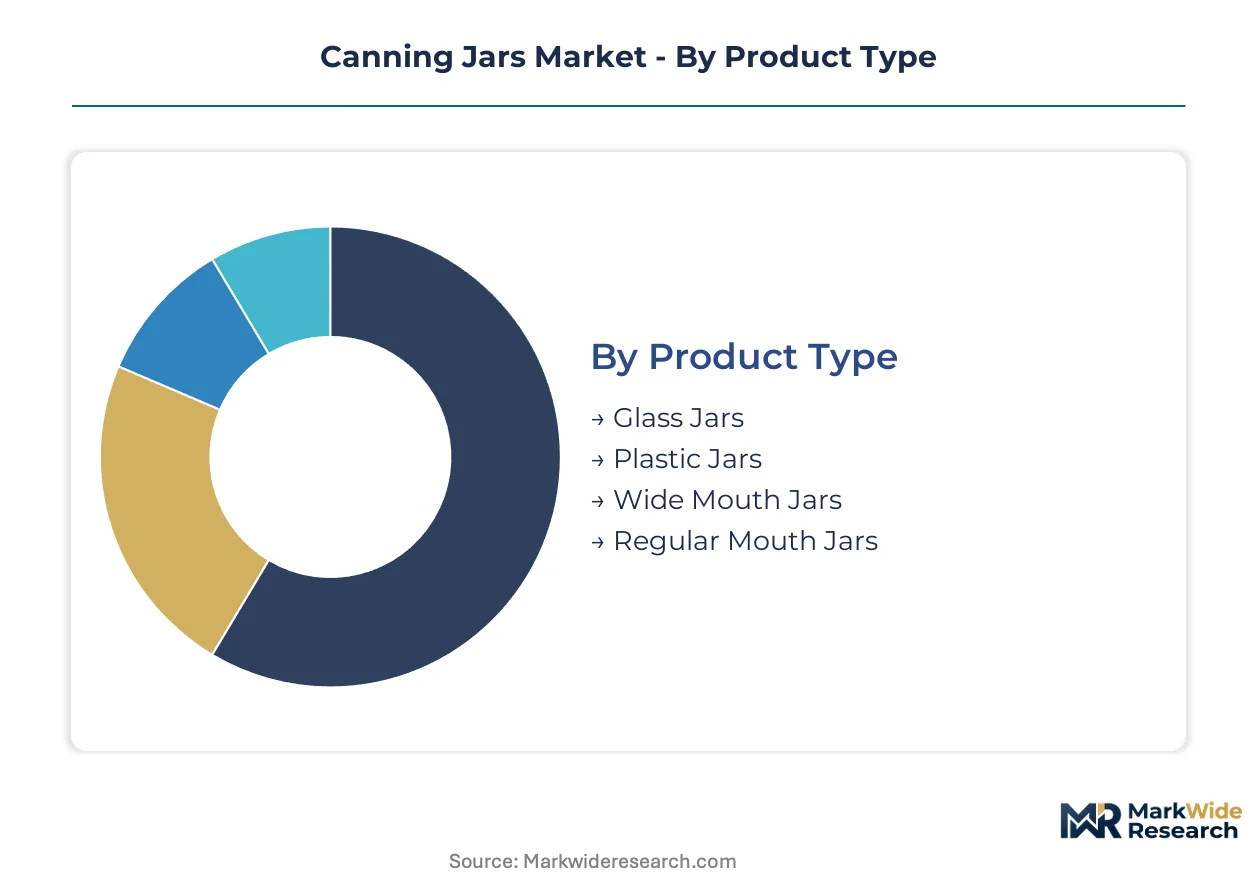
Canning jar procurement patterns diverge sharply across product specifications, with FDA food contact regulations and state-level cottage food laws creating tiered compliance burdens that reshape supplier selection. Segmentation reveals how artisan producers, commercial packagers, and industrial operators prioritize different performance attributes and certification requirements.
Product Type:
FDA migration limit standards apply differentially across material compositions, with soda-lime glass formulations facing distinct testing protocols versus polyethylene terephthalate alternatives. EFSA food contact regulations in Europe impose parallel substance restrictions that shape cross-border qualification criteria.
- Glass Jars:Soda-lime silicate construction delivers chemical inertness and thermal shock resistance to 250°F, supporting vacuum-sealed preservation cycles. Demand concentrates among Pacific Northwest artisan producers in Portland and Seattle, where craft food culture prioritizes reusability and premium shelf differentiation.
- Plastic Jars:Food-grade polyethylene terephthalate formulations reduce shipping weight by 60-70% versus glass equivalents while eliminating shatter risk in logistics handling. Commercial food packagers in California and Texas are migrating toward plastic formats where distribution economics outweigh reusability premiums.
- Wide Mouth Jars:86mm aperture diameters accommodate whole fruit preservation and hand-filling operations preferred by small-batch producers.
- Regular Mouth Jars:70mm standard apertures optimize material efficiency and automated capping line throughput for industrial-scale operations.
Glass Jars sits at the top of the volume ranking, with Plastic Jars climbing the fastest.
End User:
Customer type determines order scale, customization requirements, and regulatory exposure, with artisan and industrial segments operating at opposite ends of the margin spectrum.
- Artisan:Small-batch producers purchasing 500-5,000 unit lots with decorated, wide-mouth specifications for farmers market and direct-to-consumer distribution. Washington State and Oregon cottage food law compliance drives demand for documented thermal processing integrity.
- Commercial:Mid-scale food manufacturers serving regional retail chains with standardized 16 oz and 32 oz formats. These buyers prioritize lightweighting and logistics efficiency over decoration complexity.
- Household:Bulk retail purchasers acquiring case quantities for home preservation, concentrated in seasonal surges preceding harvest periods.
- Industrial:High-volume packagers operating continuous filling lines requiring metal lid compatibility and precise dimensional tolerances for automated capping systems.
Commercial procurement dominates current volume, though Artisan segment expansion is gaining share fastest.
Capacity:
Size selection correlates with end-use application and distribution channel constraints, with smaller formats commanding per-ounce premiums.
- 16 oz:The versatile midpoint serving both single-serve retail and small-family household applications. Oregon specialty food startups favor this format for fermented vegetable and preserve lines distributed through subscription channels.
- 32 oz:Standard bulk preservation size for household tomato sauce and soup stock applications, optimized for shelf storage efficiency.
- 8 oz:Premium sampler and gift-format size, common in Washington State farm-to-table retail.
- 64 oz:Industrial-scale food service and institutional packaging format, requiring reinforced wall thickness for handling durability.
16 oz maintains volume leadership, with 8 oz formats seeing steepest expansion trajectory in premium positioning.
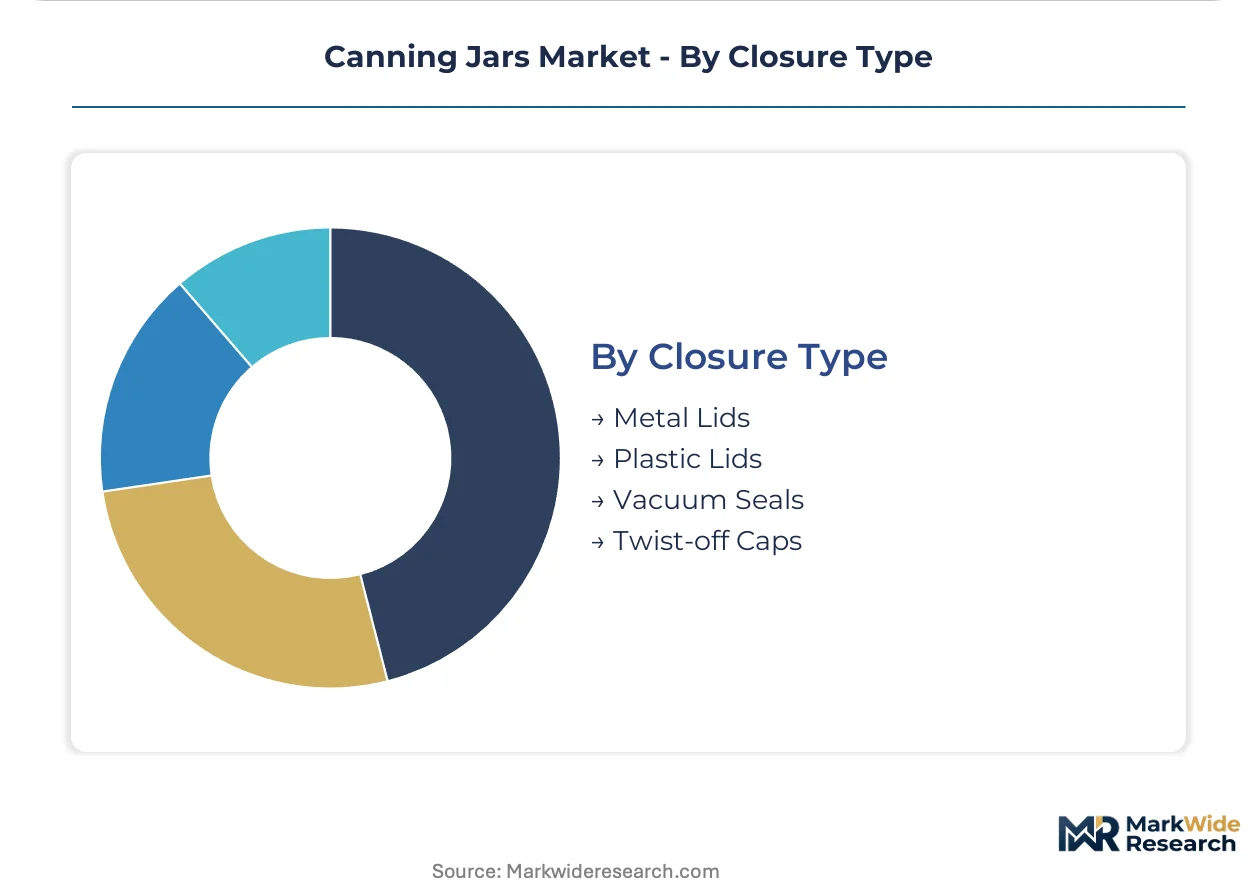
Closure Type:
Seal technology selection determines shelf stability, consumer convenience, and regulatory compliance pathways for vacuum preservation claims.
- Metal Lids:Two-piece vacuum seal systems with plastisol gaskets remain the household preservation standard, requiring thermal processing compatibility. FDA food contact substance regulations govern gasket migration limits, pushing suppliers toward higher-purity formulations.
- Vacuum Seals:Integrated one-piece designs with button-indicator tops that signal seal integrity, preferred by commercial packagers for tamper-evident retail presentation.
- Plastic Lids:Polypropylene screw-band alternatives for refrigerated short-term storage, avoiding metal corrosion in high-acid food contact.
- Twist-off Caps:Commercial lug-finish systems enabling tool-free opening, common in European-imported preserve lines distributed through US specialty retail.
Metal Lids retains dominant volume position, with Vacuum Seals expanding most quickly in commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with favorable energy costs and streamlined food-contact compliance pathways. Compliance cost differentials between EPA-regulated US states and EU REACH jurisdictions now exceed 15% for soda-lime glass formulations.
United States
Pacific Northwest craft food clusters in Portland and Seattle drive premium wide-mouth jar demand for small-batch producers. FDA migration limit standards for plastisol gaskets are forcing domestic lid suppliers toward higher-purity formulations. Natural gas price volatility in Midwestern manufacturing corridors is compressing margin stability for mid-tier fabricators.
Germany
EFSA food contact substance regulations and the EU Packaging and Packaging Waste Directive are mandating documented recyclability thresholds for glass exporters. Lightweighting technology adoption concentrates in Bavaria and North Rhine-Westphalia, where industrial packagers serve Central European retail chains. Berlin-based specialty food startups are piloting subscription jar-return programs.
France
ANSM food safety oversight and deposit return schemes in Île-de-France are creating circular economy infrastructure favoring reusable glass. Artisan preserve producers in Provence-Alpes-Côte d'Azur command premium positioning through decorated formats. Lyon industrial clusters supply standardized containers to North African export markets.
China
GB standards for food contact materials and MIIT industrial efficiency mandates are accelerating furnace technology upgrades in Shandong Peninsula glass corridors. Pearl River Delta manufacturers supply cost-optimized formats to Southeast Asian commercial packagers. Yangtze River Delta exporters face tightening EU import documentation requirements.
India
FSSAI food safety regulations and BIS quality certification requirements are reshaping supplier qualification for domestic and export markets. Maharashtra-based food processors in Mumbai-Pune corridor are adopting plastic jar formats for logistics efficiency. Gujarat glass manufacturing hubs serve Middle Eastern and African export demand.
Canning Jars Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heritage consumer brands dominating North American retail channels while industrial-scale fabricators capture commercial food service volumes. Market structure tilts toward consolidation at the premium artisan tier and fragmentation in commodity plastic formats. Three archetypes dominate: century-old heritage brands leveraging nostalgic positioning, multinational glass conglomerates optimizing furnace scale, and regional decorators serving localized craft producers. Capacity expansion and lightweighting technology licensing represent the dominant competitive vectors.
Among heritage-positioned specialists, Ball Corporation anchors the North American home-preserving segment through century-old brand recognition. Owens-Illinois exemplifies scale-driven multinational supply to industrial food packagers across multiple continents. Ardagh Group occupies a position within the premium commercial tier through specialized forming and decoration capabilities.
| Leading Market Players |
|---|
| Verallia |
| Anchor Hocking |
| Ball Corporation |
| Berlin Packaging |
| Libbey |
| Owens-Illinois |
| Newell Brands |
| Fillmore Container |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Lightweighting technology convergence across forming and thin-wall design is simultaneously compressing material intensity per unit and concentrating supply leverage among furnace-scale operators who amortize capital costs across broader output bases. This dual effect tightens margin structures for mid-tier fabricators while rewarding integrated producers with captive silica sand access.
Pricing Analysis
Distributor margin layering in North American retail channels absorbs 35-45 points before shelf placement, forcing artisan producers toward direct-to-consumer subscription models that bypass intermediaries. Three-tier pricing structure across premium decorated glass, standard soda-lime formats, and economy plastic alternatives stratifies by certification grade and thermal processing integrity. Cost compression in mid-tier glass is intensifying because natural gas price volatility erodes furnace economics. Commercial packagers exhibit highest price sensitivity due to logistics-weight tradeoffs, while Pacific Northwest artisan buyers absorb premiums for provenance-linked decoration.
Supply Chain Analysis
Freight cost differentials between heavy glass and lightweight plastic formats are reshaping procurement geography, with California and Texas commercial buyers preferring polyethylene terephthalate to avoid weight-based shipping penalties. Manufacturing concentrates in the United States, China, and Germany, with domestic production drawing from Midwestern high-purity silica sand deposits. Soda-lime glass rests on fossil fuel-fired furnace operations, tin oxide coating chemicals, and metal lid gasket formulations. Single-source vulnerability in specific Midwestern sand counties creates geographic concentration risk. Distribution runs through retail intermediaries for household segments, direct-to-brand relationships for artisan producers, and contract manufacturing networks for industrial packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canning jars market reads as a late-cycle quality story justified by artisan food producers' pivot toward premium decorated glass formats that command shelf differentiation and subscription loyalty.
For Market Incumbents: Deploy lightweighting technology licensing as a defensive lever against polyethylene terephthalate substitution threatening mid-volume glass demand. Ball Corporation and Owens-Illinois should deepen backward integration into silica sand reserves to defend margin position against natural gas volatility and single-source geographic risk. Capacity consolidation in Pacific Northwest corridor states captures proximity to fastest-growing artisan demand clusters. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for specialty food startups seeking jar-return program partnerships without legacy retail slotting commitments. White-space concentrates in decorated wide-mouth formats for Washington State and Oregon cottage food law compliance, and in lightweighted plastic alternatives for California commercial packagers prioritizing logistics efficiency. Go-to-market should anchor on hyper-local branding enabled by laser-etched batch coding that eliminates minimum order constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among regional decorators with specialized forming capabilities but limited furnace scale, presenting acquisition targets for multinational glass conglomerates seeking premium tier exposure. Long-term viability hinges on extended producer responsibility framework adoption creating circular economy infrastructure that favors reusable glass economics. Watch Oregon and Maine deposit return scheme implementation velocity as the signal indicating material economics shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Licensing | Enables material cost reduction without sacrificing FDA thermal processing compliance thresholds. |
| Direct-to-Consumer Subscription Launch | Bypasses retail margin layering while capturing end-of-life container value through return programs. |
| Backward Integration into Silica Sand | Secures supply against Midwestern deposit concentration risk and natural gas price volatility exposure. |
| Laser-Etched Decoration Investment | Eliminates paper label adhesives and enables infinite design variations for hyper-local artisan branding. |
| Extended Producer Responsibility Partnership | Positions glass formats favorably within emerging Oregon and Maine deposit return circular infrastructure. |
Study Parameters
Multiple input streams — primary interviews with glass furnace operators, artisan food producers, and retail category buyers, alongside secondary validation through FDA food contact substance filings, EPA emissions disclosures, and state-level cottage food law databases — were reconciled through bottom-up volume triangulation and top-down value reconciliation. Plant managers at Midwestern manufacturing facilities, procurement leads at Pacific Northwest specialty food startups, distribution channel partners serving farmers market networks, and technical R&D directors at coating chemical suppliers contributed operational data. SEC 10-K filings of publicly traded glass manufacturers, customs import records for European decorative formats, and Oregon Department of Agriculture cottage food registration statistics provided external anchors.
Data-stream reconciliation across product type, end-user segment, capacity tier, closure technology, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume buildups calibrated to macroeconomic drivers and regulatory implementation schedules. Forecast inputs included natural gas price trajectory assumptions for furnace economics, artisan food startup formation rates in Pacific Northwest corridor cities, and polyethylene terephthalate resin cost curves affecting substitution dynamics.
The model assumes a particular technology adoption path; alternative pathways for laser-etched direct-to-glass marking or accelerated lightweighting diffusion would alter the outlook for decoration minimum order economics and material intensity benchmarks. Forecasts reflect documented assumptions regarding EPR framework adoption timing, silica sand deposit access stability, and cottage food law expansion velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
EPS Shippers Market
Containers
Two Compartment Bottles Market
Containers
Container Market
Containers
HDPE Crates Market
Containers
Flexible Water Tanks Market
Containers
Compartment Trays Market
Containers
Soup Containers Market
Containers
Metal IBC Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Hinged Deli Containers Market
Containers
Clear Hinged Container Market
Containers
Global Styrene Compartment Boxes Market
Containers
Stock Clamshell Packaging Market
Containers
Tin Containers Market
Containers
Screw Top Pails Market
Containers
Rotomolded Containers Market