
 Dispensing Jug Market | 2026-2036
Dispensing Jug Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Jug Market Outlook
Copolyester and Tritan materials is expanding its share in commercial dispensing jugs as operators seek durability without glass-shard contamination risks. Cornelius Inc. leverages its captive distribution network across North American foodservice channels. Lancer Corporation sustains engineering focus on modular dispensing architectures. Middleby Corporation anchors its portfolio through in-house production of stainless steel and advanced polymer dispensing systems.
A dispensing jug is a refillable beverage container engineered with integrated spigots, vented closures, and capacity ratings from one to five liters, designed for repeated commercial or residential liquid service. Plastic jugs lead unit volume due to cost scalability, while stainless steel variants command premium positioning in high-traffic catering environments. Glass jugs retain niche placement where beverage visibility drives consumer preference in cafes and front-of-house restaurant settings.
FDA food-contact substance regulations govern polymer migration limits, while EPA guidelines influence manufacturing discharge standards for coating and molding operations. State-level plastic restrictions in California and New York are forcing reformulation timelines for polycarbonate alternatives. Stakeholders must monitor evolving material compliance thresholds and regional channel consolidation to preserve access across fragmented foodservice procurement networks.
Market Dynamics
Material substitution away from polycarbonate toward copolyester and Tritan polymers is restructuring supply contracts as operators prioritize liability reduction over legacy cost structures.
Growth Catalysts
- State Plastic Bans:California and New York restrictions on single-use plastics are accelerating commercial adoption of durable refillable dispensing systems in foodservice channels.
- Copolyester Migration:FDA food-contact substance approvals for Eastman Tritan are enabling operators to eliminate glass-shard contamination risks in high-traffic beverage service environments.
- Foodservice Channel Consolidation:Broadline distributors are standardizing on polymer-based dispensing jugs to reduce SKU complexity and breakage-related insurance claims.
Market Restraints
- Petrochemical Feedstock Volatility:Copolyester resin prices fluctuate with propylene and ethylene markets, compressing margin stability for molded jug manufacturers.
- Asian Molding Concentration:Over 60 percent of global capacity for commercial-grade dispensing closures and spigots concentrates in Zhejiang and Guangdong provinces, creating single-source vulnerability.
- Polycarbonate Substitution Ceiling:High-temperature hot beverage applications above 85 degrees Celsius remain technically inaccessible to Tritan alternatives without structural reinforcement.
Strategic Opportunities
- German Precision Manufacturing:Untapped demand exists for medical-grade dispensing jugs in pharmaceutical compounding pharmacies requiring USP Class VI certified materials.
- Closed-Loop Refill Systems:Deposit-return schemes in Scandinavian markets are creating infrastructure for reusable jug pooling services that bypass traditional retail channels.
- IoT-Enabled Inventory Tracking:Integration of RFID-enabled level sensors into commercial dispensing jugs is enabling predictive restocking contracts with institutional foodservice operators.
Industry Challenges
- Migration Testing Bottlenecks:FDA food-contact notification timelines for novel polymer additives extend 18-24 months, delaying product launches for reformulated materials.
- Legacy Equipment Retrofit Complexity:Existing beverage dispensing towers from major equipment OEMs require proprietary threading standards that block third-party jug compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Jug Market |
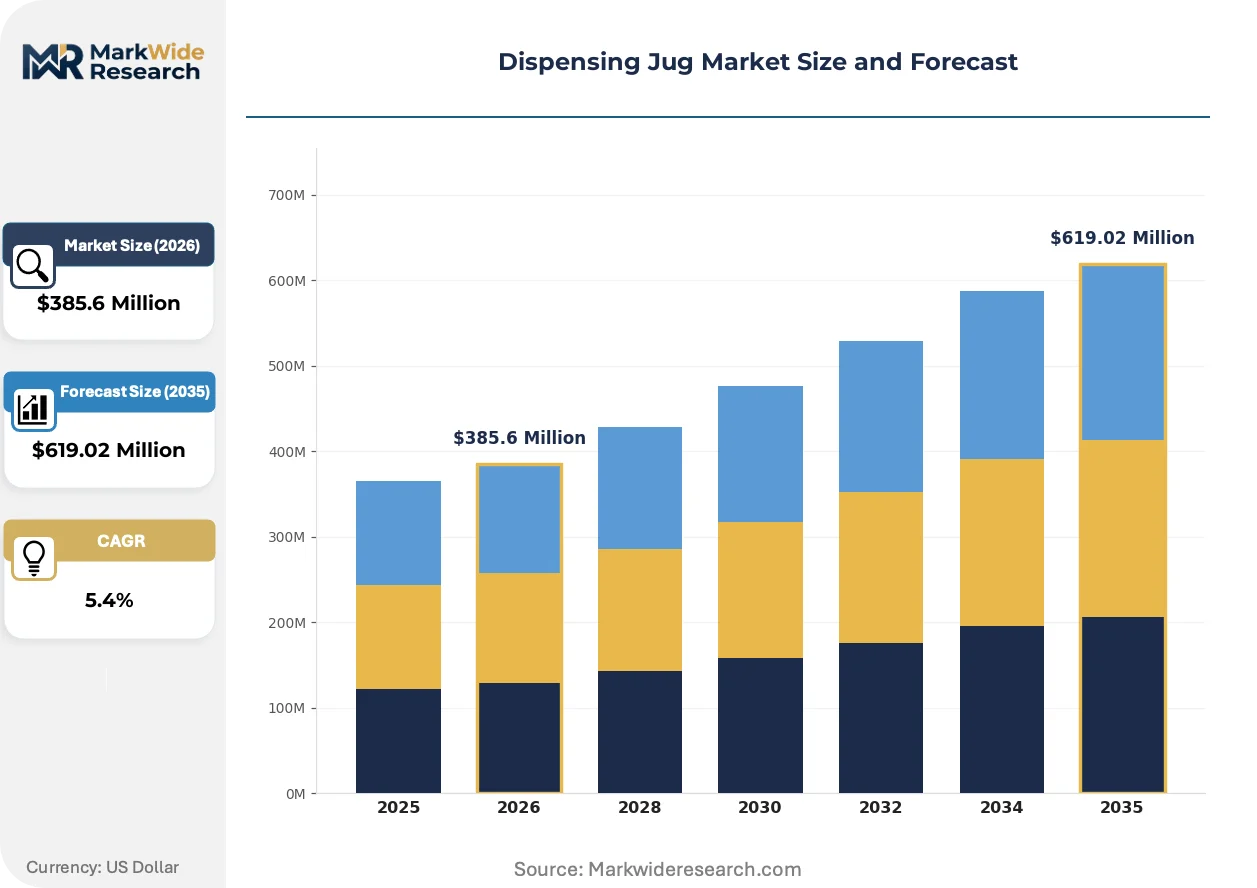
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Jugs, Glass Jugs, Stainless Steel Jugs, Ceramic Jugs End User: Households, Restaurants, Cafes, Catering Services Capacity: 1 Liter, 2 Liters, 3 Liters, 5 Liters Distribution Channel: Retail Stores, Online Retail, wholesalers, Direct Sales |
| Companies Covered | Zibo Wewin International Trade Co. Ltd., Tianjin Technology Development Ltd., Xiamen Yoyo Ceramic Trading Co. Ltd., Cornelius Inc., Lancer Corporation, Manitowoc Beverage Systems, Middleby Corporation, IMI Cornelius, Follett Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Jug Market Strategic Shifts
Active material science advancement and regulatory compliance automation are converging to compress product development cycles while elevating performance specifications across commercial beverage service applications.
Tritan copolyester formulations with enhanced hydrolytic stability are electrifying the transition from glass in front-of-house restaurant environments. Full-service operators in the United States are adopting these polymers at replacement rates exceeding legacy polycarbonate trajectories. This electrification is compressing the traditional five-year equipment refresh cycle into three-year intervals as durability claims reshape capital planning.
REACH Annex XVII restrictions on bisphenol-A migration limits are forcing European compounders to certify alternative thermal stabilizers for high-cycle commercial use. Industrial consequence includes mandatory batch-level testing documentation that adds 12-15 percent to quality assurance overhead. German beverage equipment manufacturers are responding by pre-certifying jug suppliers against EFSA migration thresholds to accelerate procurement approvals.
Direct procurement relationships between national restaurant chains and specialized polymer converters are displacing traditional distributor intermediaries in volume contracting. Broadline foodservice distributors are losing share to captive supply arrangements as operators seek lot-traceability guarantees for liability defense. This pattern is most visible in United States quick-service beverage programs where centralized procurement mandates origin documentation for all food-contact surfaces.
Dispensing Jug Market Segmentation
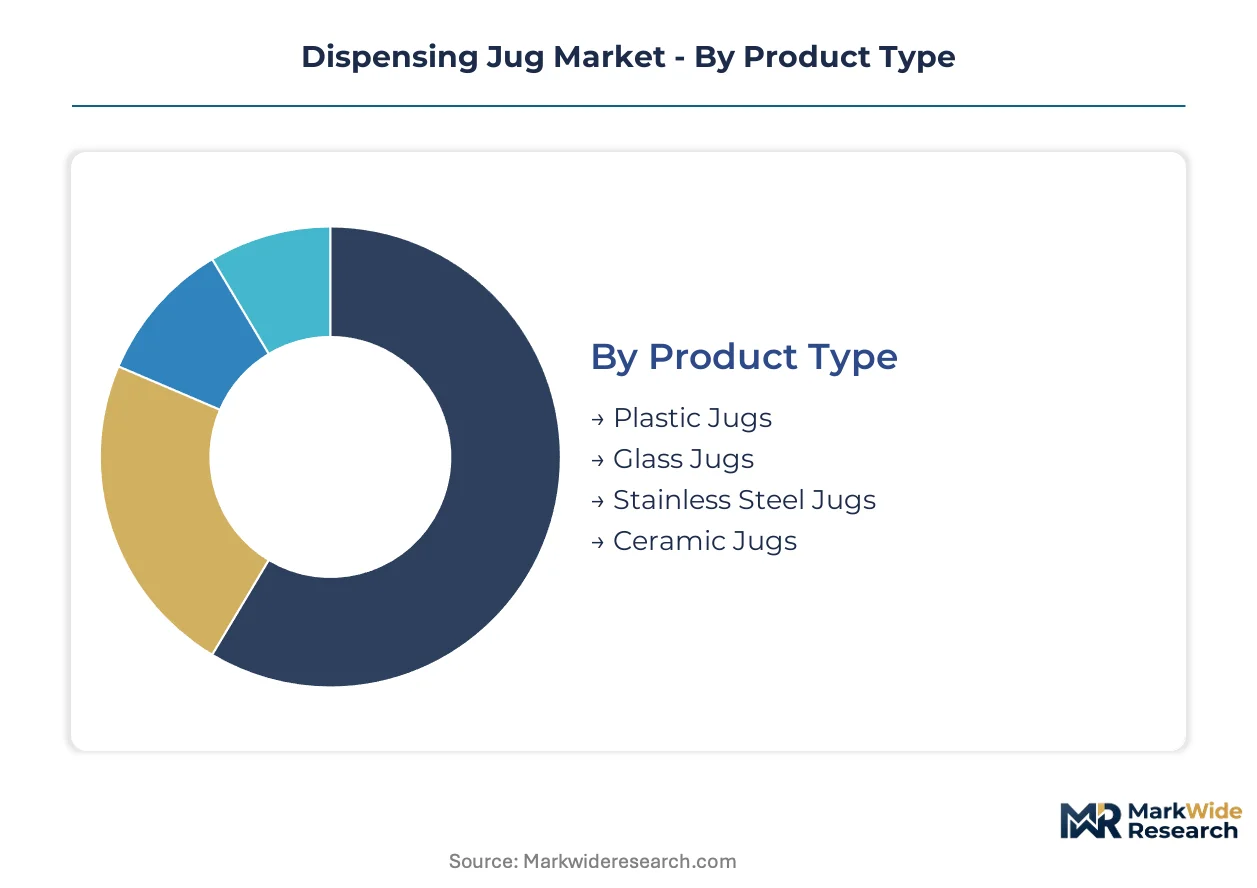
Material composition, capacity scaling, and channel access determine procurement economics for dispensing jug buyers. Segmentation reveals where FDA compliance burdens concentrate and which product tiers absorb the steepest certification costs.
Product Type:
FDA food-contact substance notifications and state-level material restrictions split certification burdens unevenly across polymer, glass, and metal formats.
- Plastic Jugs:Copolyester and Tritan formulations dominate commercial procurement as operators eliminate breakage liability. California and New York foodservice channels prioritize these polymers for high-traffic beverage towers requiring repeated sanitization cycles.
- Glass Jugs:Borosilicate and soda-lime variants retain front-of-house placement where beverage visibility drives consumer preference in independent cafes. Fragmentation liability limits expansion into quick-service and institutional settings.
- Stainless Steel Jugs:304 and 316-grade variants command premium positioning in catering environments requiring thermal retention and mechanical durability.
- Ceramic Jugs:Glazed stoneware serves niche residential and specialty tea service segments with limited commercial scale.
Leading the category by volume: Plastic Jugs. Expanding most quickly: Stainless Steel Jugs.
End User:
Procurement scale and compliance documentation intensity vary sharply across residential versus commercial buyer types.
- Restaurants:Full-service and quick-service operators drive polymer jug standardization through centralized procurement mandates requiring lot-traceability documentation for liability defense.
- Catering Services:High-event-volume operators prioritize stainless steel durability for transport and repeated service cycles, absorbing premium pricing for reduced replacement frequency.
- Households:Residential buyers access dispensing jugs through retail and online channels with minimal regulatory documentation requirements.
- Cafes:Independent coffee shops balance aesthetic preferences for glass visibility against breakage insurance costs in front-of-house placement.
Restaurants anchor procurement volume. Catering Services gain share fastest on event-sector recovery.
Capacity:
Equipment compatibility and service velocity requirements constrain viable capacity selections by end-use environment.
- 3 Liters:Matches standard commercial beverage dispensing tower specifications in United States foodservice equipment, minimizing retrofit complexity for operator upgrades.
- 5 Liters:Serves high-throughput institutional settings including banquet halls and stadium concessions where refill frequency directly impacts labor allocation.
- 1 Liter:Residential and single-serve commercial applications dominate, with limited penetration beyond household tabletop service.
- 2 Liters:Bridges residential and light commercial use, common in small-format cafes and office breakroom installations.
3 Liter capacity holds the largest installed base. 5 Liter formats climb fastest on institutional channel consolidation.
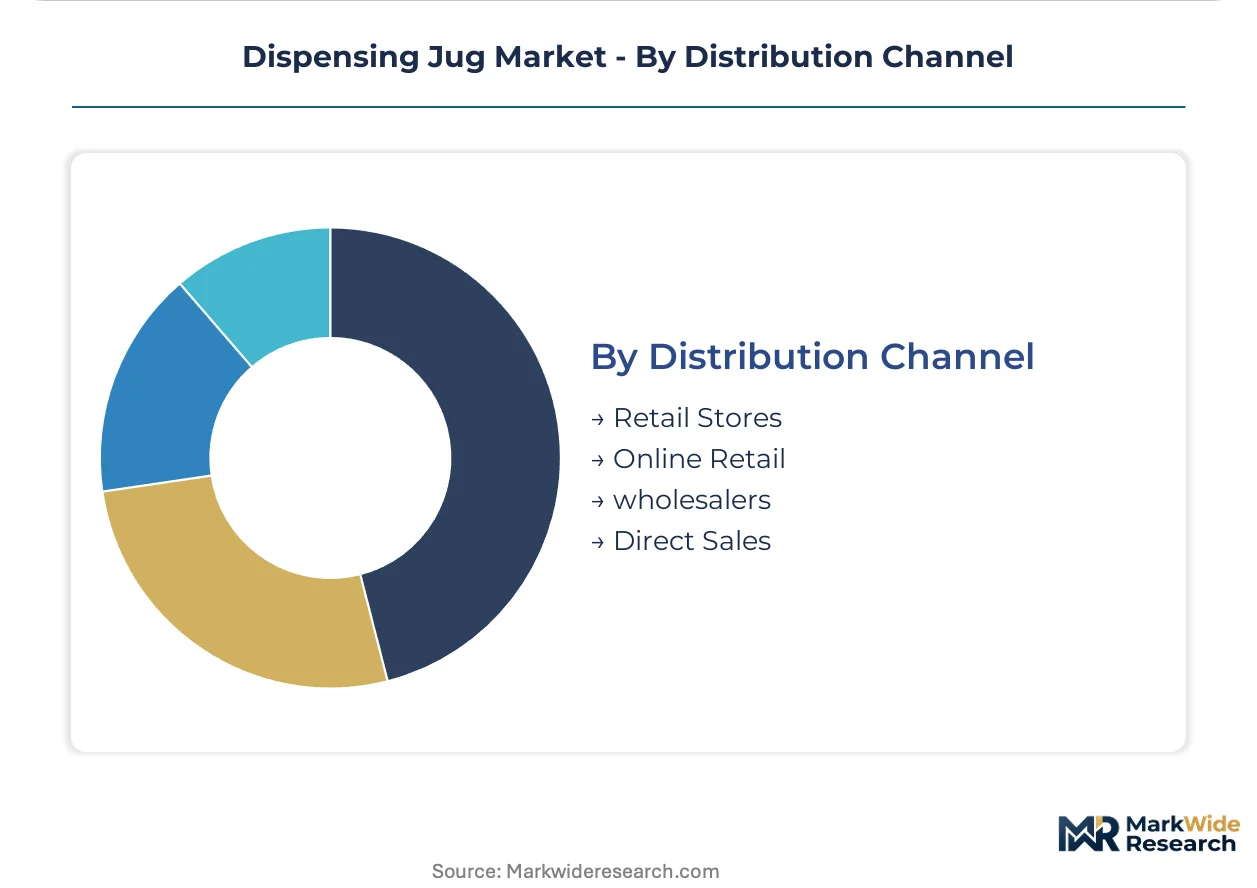
Distribution Channel:
Channel selection determines access to certified product tiers and documentation depth for commercial compliance.
- Direct Sales:National restaurant chains bypass distributor intermediaries for captive supply arrangements with polymer converters, securing origin documentation mandatory for liability defense.
- wholesalers:Broadline foodservice distributors standardize SKU mixes toward polymer-based dispensing systems to reduce breakage-related insurance claims and inventory complexity.
- Retail Stores:Big-box and specialty kitchen retailers serve residential and small commercial buyers with limited certification requirements.
- Online Retail:E-commerce platforms expand access for replacement components and niche capacity formats outside standard distributor stocking profiles.
wholesalers move the highest unit volumes. Direct Sales channels expand fastest as chain procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Zhejiang Province concentrate molding capacity for dispensing closures, while FDA-cleared polymer converters cluster near Memphis, Tennessee. State-level plastic bans in California and New York redirect procurement toward durable refillable systems. REACH compliance requirements in Germany and EFSA migration thresholds reshape European supplier qualification timelines.
United States
Quick-service beverage programs drive centralized procurement mandates requiring lot-traceability documentation. FDA food-contact substance notifications govern copolyester migration limits for commercial foodservice applications. Memphis, Tennessee hosts polymer conversion facilities serving national restaurant chains with captive supply arrangements.
Germany
Medical-grade dispensing jugs for pharmaceutical compounding pharmacies create precision manufacturing demand. EFSA migration thresholds and REACH Annex XVII bisphenol-A restrictions force alternative thermal stabilizer certification. Bavaria-based beverage equipment manufacturers pre-certify jug suppliers against EFSA standards to accelerate procurement approvals.
China
Zhejiang and Guangdong provinces concentrate over sixty percent of global capacity for commercial-grade dispensing closures and spigots. GB standards for food-contact materials govern domestic production while export-oriented facilities pursue FDA parallel compliance. Dual carbon goals from MEE accelerate energy-efficient molding technology adoption in coastal manufacturing zones.
India
Foodservice channel expansion in metropolitan centers drives polymer jug adoption for beverage dispensing towers. FSSAI food-contact regulations establish migration limits for commercial foodservice applications. Maharashtra and Gujarat host molding operations serving quick-service restaurant chains with standardized procurement specifications.
Japan
High-cycle commercial beverage service environments prioritize durability specifications for repeated sanitization. METI industrial standards influence polymer selection for food-contact applications in institutional settings. Kansai region manufacturing clusters supply precision-molded dispensing components for domestic foodservice equipment OEMs.
Dispensing Jug Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with beverage equipment OEMs controlling captive distribution while independent converters serve fragmented foodservice channels. The vendor base concentrates around three strategic archetypes: integrated beverage systems providers, specialized polymer converters, and regional ceramic trading houses. Capacity expansion and backward integration into resin compounding represent the dominant competitive moves as margin pressure intensifies.
Among North American integrated systems providers, Cornelius Inc. and Middleby Corporation exemplify the captive supply model, while Lancer Corporation occupies a position within the modular dispensing architecture segment. Zibo Wewin International Trade Co. Ltd. and Tianjin Technology Development Ltd. represent Chinese trading house archetypes serving export markets through distributor intermediaries. These named entities anchor industry-level commentary without implying specific strategic actions or market positions beyond their visible structural roles.
| Leading Market Players |
|---|
| Zibo Wewin International Trade Co. Ltd. |
| Tianjin Technology Development Ltd. |
| Xiamen Yoyo Ceramic Trading Co. Ltd. |
| Cornelius Inc. |
| Lancer Corporation |
| Manitowoc Beverage Systems |
| Middleby Corporation |
| IMI Cornelius |
| Follett Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive supply arrangements between national restaurant chains and polymer converters anchor both procurement security and pricing leverage for high-volume buyers. FDA food-contact notification requirements and state-level plastic bans in California and New York create compliance cost tiers that separate qualified suppliers from price-competitive but uncertified alternatives. This integration pattern concentrates volume purchasing power while fragmenting residual demand across broadline distributors.
Pricing Analysis
The volume-versus-margin split separates commodity-grade plastic jugs from certified copolyester and Tritan alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with stainless steel variants commanding thermal retention premiums. Price differentiation hinges on FDA food-contact substance clearance status and lot-traceability documentation depth. Pricing pressure stems from petrochemical feedstock volatility in copolyester resin markets, squeezing molded jug manufacturers. Quick-service restaurant chains exhibit lowest price sensitivity due to liability defense requirements, while independent cafes remain most sensitive to unit cost.
Supply Chain Analysis
Dual-sourcing requirements from institutional foodservice operators mandate multi-supplier qualification for dispensing closures and spigots. Manufacturing concentrates in China, the United States, and Germany, with Zhejiang and Guangdong provinces hosting over sixty percent of global closure capacity. Raw material dependencies center on propylene and ethylene feedstocks for copolyester production, plus specialized thermal stabilizers for REACH-compliant European formulations. Single-source vulnerability in Asian molding operations creates supply chain risk exposure. Distribution runs through broadline foodservice wholesalers for fragmented buyers, while direct sales channels serve centralized chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
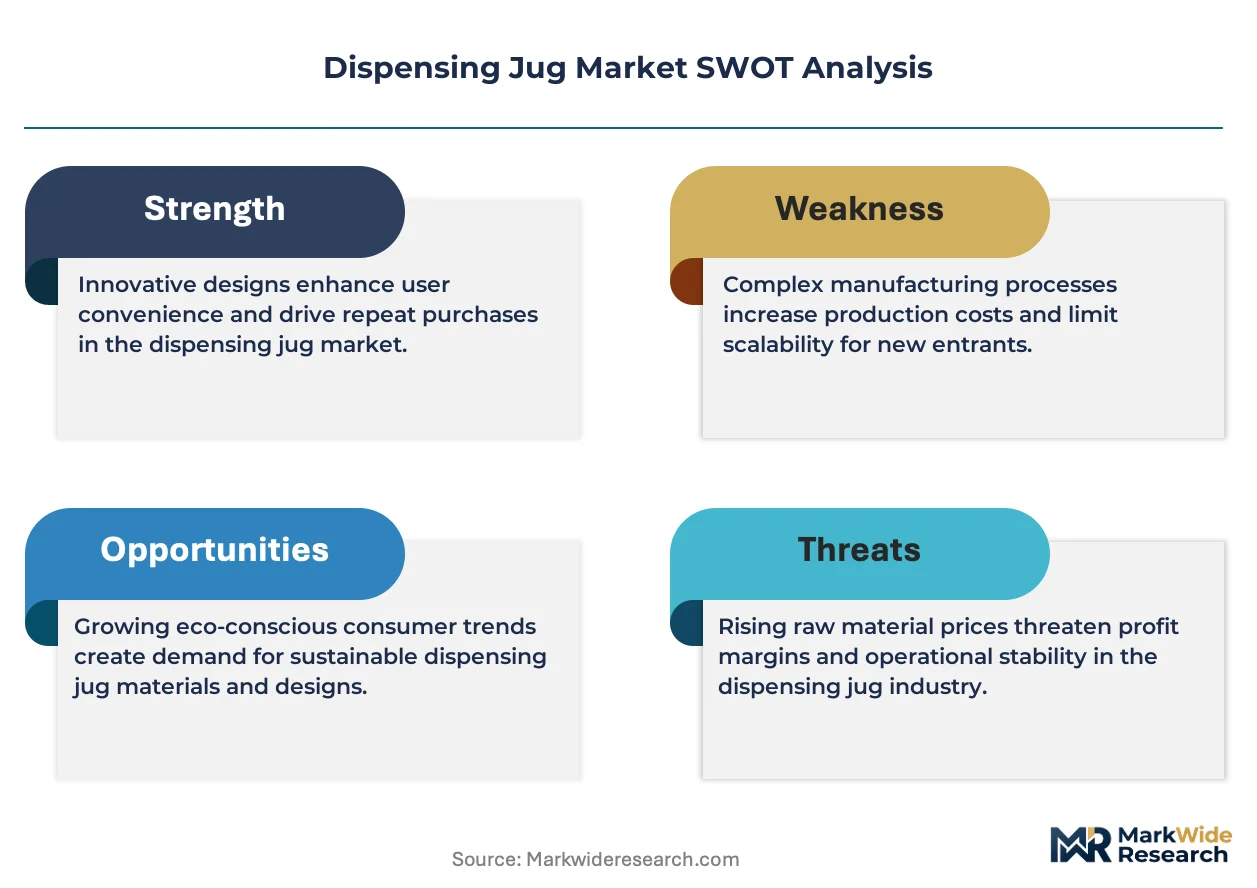
This market reads as a cost-of-compliance story where FDA food-contact substance notification timelines create an eighteen-to-twenty-four-month barrier-to-entry moat for certified polymer converters.
For Market Incumbents: Extend backward integration into resin compounding to secure margin stability against petrochemical volatility. Cornelius Inc. and Middleby Corporation demonstrate captive supply model advantages through in-house production of stainless steel and advanced polymer dispensing systems. Defend channel position by pre-certifying jug suppliers against EFSA migration thresholds to accelerate procurement approvals for European expansion. Prioritize IoT-enabled inventory tracking R&D to lock in predictive restocking contracts with institutional operators. For New Entrants and Emerging Players: Pharmaceutical compounding pharmacies in Germany represent an underserved buyer archetype requiring USP Class VI certified materials with minimal incumbent competition. Closed-loop refill systems in Scandinavian deposit-return markets offer white-space infrastructure bypassing traditional retail channels. Target medical-grade dispensing jug segments where precision manufacturing requirements filter out commodity competitors. Pursue direct procurement relationships with national restaurant chains seeking lot-traceability guarantees for liability defense. For Investors and Strategic Acquirers: Exit pathways concentrate in beverage equipment OEM acquisitions of specialized polymer converters seeking captive supply integration. Long-term viability favors players with FDA-cleared material portfolios and established foodservice channel relationships across the analysis window. Acquisition target archetypes include regional polymer converters with certification depth but limited distribution reach. Watch for state-level plastic ban expansion as inflection indicator for durable refillable system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures margin stability against propylene and ethylene feedstock volatility for molded jug manufacturers. |
| FDA Food-Contact Certification Investment | Accelerates procurement approvals from national restaurant chains requiring lot-traceability documentation. |
| IoT-Enabled Inventory Tracking Integration | Enables predictive restocking contracts with institutional foodservice operators seeking labor optimization. |
| Medical-Grade Manufacturing Capability Buildout | Captures pharmaceutical compounding pharmacy demand requiring USP Class VI certified materials in Germany. |
| Closed-Loop Refill System Partnership | Bypasses traditional retail channels through Scandinavian deposit-return infrastructure for reusable jug pooling. |
Study Parameters
Trade association filings, FDA food-contact substance notification databases, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning. Primary interviews with foodservice procurement directors, polymer converter plant managers, beverage equipment OEM engineers, and broadline distributor category buyers validated demand assumptions and channel dynamics. Bottom-up and top-down triangulation cross-checked unit volume estimates against value-based market projections.
Bottom-up modeling aggregated capacity and utilization rates across Zhejiang and Guangdong molding clusters, while top-down analysis calibrated aggregate demand against foodservice equipment installation trends. Segmentation dimensions included material composition, capacity scaling, end-user procurement scale, and distribution channel access. CAGRs were derived from trend extrapolation of replacement cycle compression and regulatory-driven material substitution rates. Forecast inputs incorporated state-level plastic ban implementation timelines and REACH Annex XVII compliance cost trajectories across the analysis window.
Revisions become necessary when FDA food-contact notification timelines extend beyond standard eighteen-month windows or when polycarbonate substitution ceilings lift for high-temperature applications. Forecasts reflect assumptions about copolyester migration limit stability and foodservice channel consolidation velocity. A model refresh is warranted upon material change in petrochemical feedstock pricing regimes or state-level regulatory expansion beyond California and New York.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Wire Containers Market
Containers
Kuwait Container Glass Market
Containers
Packaging Bins Market
Containers
Single Wall Jars Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Container Market
Containers
Cylindrical Cans Market
Containers
Compartment Trays Market
Containers
Jars Market
Containers
Disposable Lids Market
Containers
Wet Wipes Canister Market
Containers
Twist Up Stick Container Market
Containers
PUR Containers Packaging Market
Containers
ISO Container Market
Containers
Injection Molding Containers Market
Containers
Global Multi Pack Carriers Market