
 Tin Containers Market | 2026-2036
Tin Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Tin Containers Market Analytics
Asset-light leasing models for tinplate coating lines is tilting competitive dynamics toward firms that can access capital without owning heavy manufacturing infrastructure. Crown Holdings leverages vertical integration across aluminum and steel packaging substrates to sustain cost advantages in multi-material container systems. Ball Corporation anchors its position through R&D intensity in lightweighting technologies and surface treatment chemistry. Silgan Holdings competes via geographic dominance in North American food packaging channels, controlling shelf-space relationships with private-label retailers.
Tin containers are rigid metal vessels fabricated from electrolytic tinplate or tin-free steel, typically ranging from 0.15 mm to 0.49 mm in thickness, designed to provide oxygen barrier protection and corrosion resistance for packaged goods. The round product type dominates volume due to efficient stacking and uniform stress distribution during internal pressurization, while specialty shapes command margin pools in premium cosmetics and gift applications. Food industry end users represent the mature demand base, though pharmaceuticals is expanding fastest as aseptic filling requirements and child-resistant closure integration drive specification upgrades.
EPA hazardous waste rules and FDA food-contact substance notifications govern substrate approval pathways in the United States, while REACH and EU Packaging and Packaging Waste Directive shape material compliance obligations across European supply chains. India's BIS certification mandates for tinplate imports create non-tariff barriers that advantage domestic producers like Tinplate Company of India Limited. Stakeholders must monitor divergence between regional recycling rate targets and actual post-consumer tin collection infrastructure buildout.
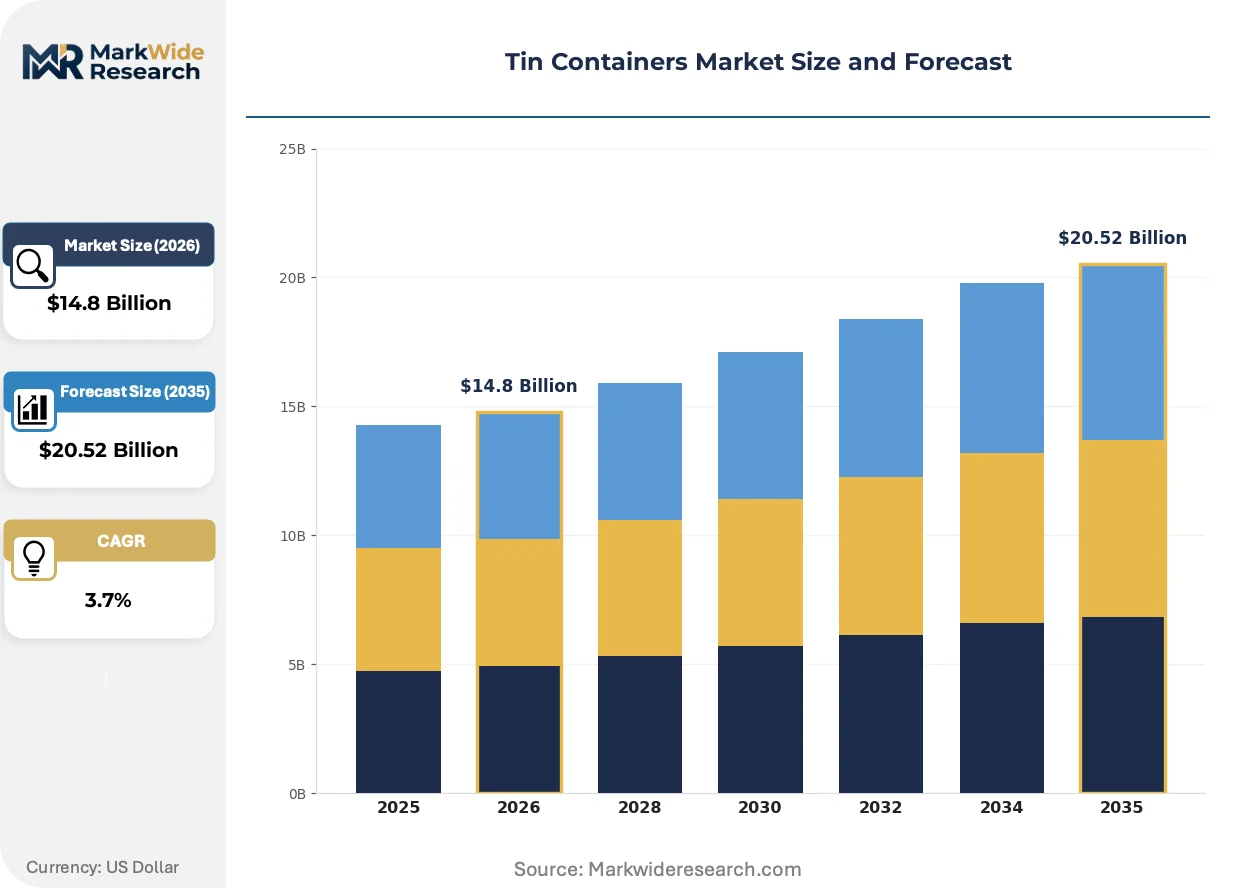
Market Dynamics
Asset-light leasing models for tinplate coating lines are compressing capital barriers for new entrants while fragmenting manufacturing control across third-party toll coaters in India and Southeast Asia.
Growth Catalysts
- Processed food sector expansion:Emerging economy buyers in India and Brazil are scaling shelf-stable packaging procurement as cold-chain infrastructure gaps persist.
- REACH substrate specifications:European compliance mandates are forcing coating chemistry upgrades that favor electrolytic tinplate over lower-grade alternatives in export-oriented supply chains.
- Aseptic filling integration:Pharmaceutical manufacturers are specifying tin containers with child-resistant closures for parenteral and oral solid dose formats.
Market Restraints
- Tin price volatility:London Metal Exchange tin contract fluctuations transmit directly to tinplate substrate costs, compressing converter margins on fixed-price annual contracts.
- Domestic capacity concentration:India's BIS certification requirements for imported tinplate advantage Tinplate Company of India Limited and Jindal Steel, limiting sourcing flexibility.
- Polymer substitution:Multi-layer plastic pouches and retortable cartons are capturing ambient soup and ready-meal segments where oxygen barrier requirements have loosened.
Strategic Opportunities
- Cosmetics premiumization:Specialty-shaped tin containers with embossed finishes are capturing gift-set and solid perfume applications in South Korea and Japan.
- FDA food-contact modernization:Evolving substance notification pathways in the United States are creating first-mover advantages for coating innovators with pre-submitted master files.
- Digital print convergence:Direct-to-metal inkjet systems are hybridizing with traditional offset, enabling short-run customization for craft food brands.
Industry Challenges
- Electroplating chemistry expertise:The workforce pipeline for sulfuric acid bath management and surface treatment quality control is thinning across Midwestern US manufacturing clusters.
- Post-consumer collection infrastructure:Actual tin recovery rates lag EU Packaging and Packaging Waste Directive targets, exposing producers to extended producer responsibility fee escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tin Containers Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.52 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round, Square, Rectangular, Specialty Size: Small, Medium, Large, Extra Large End User: Food Industry, Cosmetics, Pharmaceuticals, Beverages Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Crown Holdings Inc, Ball Corporation, Silgan Holdings Inc, Ardagh Group, Toyo Seikan Group Holdings Ltd, Can-Pack S.A., Tinplate Company of India Limited, Mitsubishi Materials Corporation, Hindalco Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tin Containers Market Evolving Landscape
Surface treatment chemistry and forming automation are compressing lead times while enabling specification differentiation previously reserved for aluminum and glass substrates.
Electrolytic chromium oxide coating is hybridizing with traditional tin plating to reduce metal content while maintaining corrosion resistance. Japanese canmakers are piloting these hybrid substrates for acidic food applications. The technology is compressing raw material intensity benchmarks across Southeast Asian export facilities.
EU Packaging and Packaging Waste Directive recycling rate mandates are forcing redesign of container-body-to-lid ratios to optimize material recovery. German sorting facilities are rejecting non-compliant formats. Premium cosmetics brands are responding with mono-material tin constructions that sacrifice hinge complexity for recyclability certification.
Buyer consolidation among North American private-label retailers is compressing supplier rosters and extending payment terms. Regional food co-packers are losing shelf-space access to vertically integrated container converters. The shift is most visible in Midwestern US grocery channels where retailer-owned brands dominate ambient vegetable and tomato segments.
Tin Containers Market Segmentation
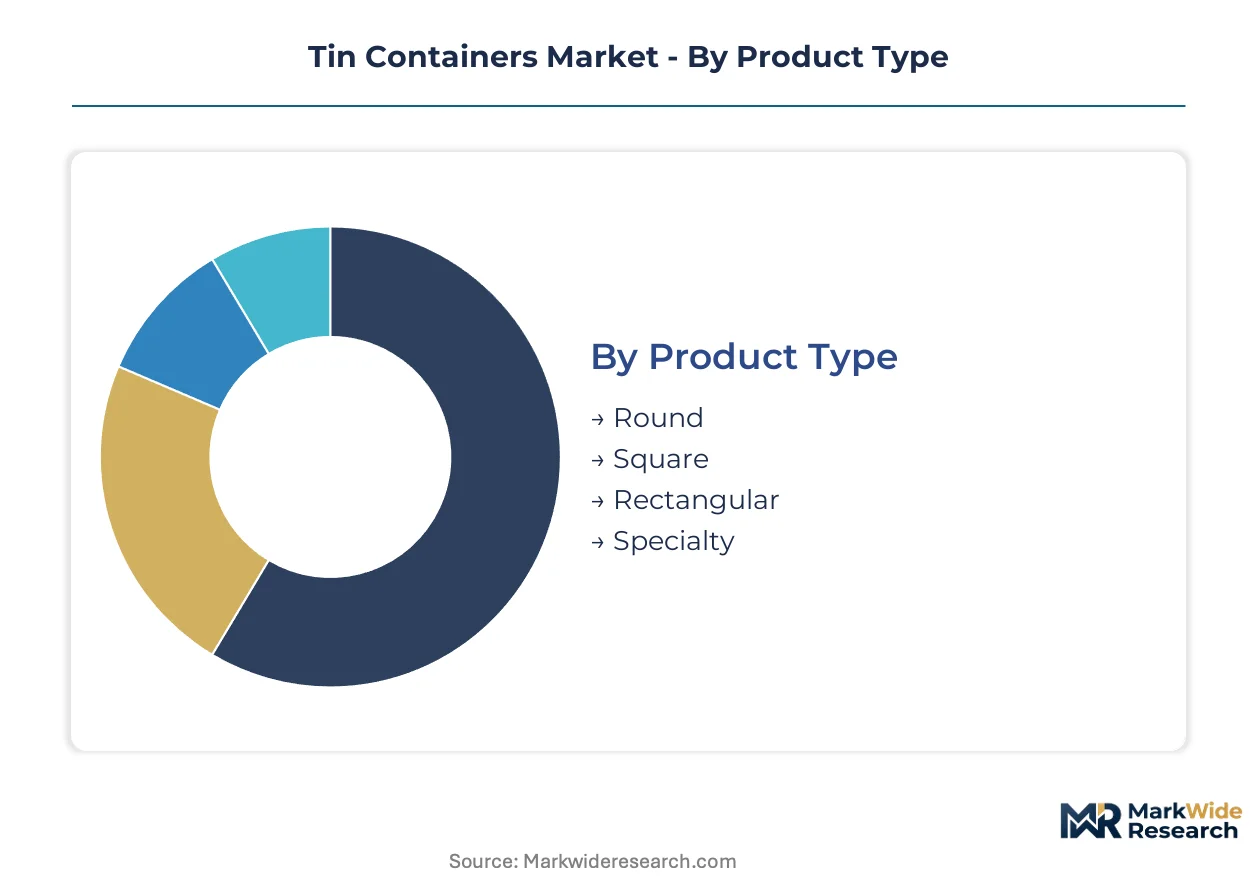
Tin container procurement cycles vary dramatically by application, with food industry buyers locking in annual contracts while cosmetics brands rotate packaging designs seasonally. Understanding these velocity differences helps converters align capacity planning with cash flow timing across customer portfolios.
Product Type:
Round containers turn inventory fastest due to standardized filling line compatibility, while specialty shapes sit in design approval queues for months.
- Round:Electrolytic tinplate construction with uniform stress distribution handles internal pressurization from carbonated beverages and vacuum-sealed foods. Indian processed food manufacturers are scaling round can procurement as domestic cold-chain gaps persist, though Ball Corporation's lightweighting patents force royalty considerations for thin-gauge variants.
- Specialty:Irregular geometries with embossed finishes and hinge-integrated lids serve premium cosmetics and gift applications. South Korean solid perfume brands are driving specification upgrades here, with mono-material constructions gaining favor under EU Packaging and Packaging Waste Directive recycling mandates.
- Square:Optimized pallet utilization in warehousing and retail shelf density for canned fish and meat products.
- Rectangular:Preferred for sardines, kippers, and other preserved seafood with efficient vertical stacking.
Round dominates installed base. Specialty is where expansion concentrates.
Size:
Cost tier stratification separates commodity volume plays from premium positioning, with substrate thickness and coating grade scaling non-linearly across size brackets.
- Small:Under 100ml capacity for single-serve pharmaceuticals, travel cosmetics, and sampler formats. Japanese pharmaceutical manufacturers are specifying child-resistant closures here, with aseptic filling requirements from PMDA driving coating chemistry upgrades.
- Large:1-5 liter industrial and institutional food service containers for cafeterias and catering. Brazilian ambient soup processors are expanding procurement as multi-layer plastic pouch substitution stalls on oxygen barrier failures in tropical humidity.
- Medium:Standard household sizes from 200ml to 1 liter for canned vegetables, fruits, and ready meals.
- Extra Large:Bulk institutional formats exceeding 5 liters for food service and industrial ingredient storage.
Medium sizes anchor revenue volume. Small formats are climbing the fastest on pharmaceutical demand.
End User:
Application maturity creates divergent margin profiles, with established food contracts compressing returns while pharmaceutical qualification processes sustain price premiums.
- Food Industry:Mature demand base for shelf-stable vegetables, fruits, meats, and ready meals requiring oxygen barrier protection. Indian buyers are expanding procurement as Tinplate Company of India Limited adds domestic capacity, though BIS certification requirements for imports limit sourcing flexibility.
- Pharmaceuticals:Aseptic filling requirements and child-resistant closure integration for oral solid dose and parenteral formats. German regulators under EMA guidelines are tightening extractables testing protocols, favoring converters with pre-submitted coating master files.
- Cosmetics:Premium gift sets and solid perfume applications in Japan and South Korea with embossed finishes.
- Beverages:Carbonated and still drinks in aluminum-competitive formats with internal pressurization requirements.
Food Industry dominates installed base. Pharmaceuticals is gaining share fastest on specification upgrades.
Distribution Channel:
Customer type fragmentation splits between consolidated retail chains with extended payment terms and fragmented specialty buyers demanding customization flexibility.
- Supermarkets:High-volume private-label procurement with annual contract structures and slotting fee arrangements. North American retailer consolidation is compressing supplier rosters, with Midwestern grocery chains dominating ambient vegetable and tomato segments.
- Online Retail:Direct-to-consumer craft food brands requiring short-run digital print customization. Direct-to-metal inkjet systems are hybridizing with offset here, enabling seasonal design rotations without plate changeover costs.
- Specialty Stores:Premium cosmetics and gift applications with design-intensive specifications and smaller order quantities.
- Wholesalers:Food service and institutional buyers with pallet-scale procurement and standardized formats.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping regional production footprints as converters balance proximity to tinplate substrate mills against access to processed food manufacturing clusters. Countries with domestic steel-tinning capacity command sourcing advantages, while import-dependent markets face BIS-equivalent certification barriers.
India
Domestic tinplate production from Jamshedpur-based mills is converging with processed food sector expansion in Pune and Ahmedabad. BIS certification mandates for imported tinplate advantage Tinplate Company of India Limited and Jindal Steel, limiting converter sourcing flexibility. The Mumbai-Pune corridor hosts growing toll-coating capacity serving regional ambient food processors.
Germany
EU Packaging and Packaging Waste Directive recycling mandates are forcing container-body-to-lid redesigns at Ruhr Valley manufacturing clusters. ECHA REACH compliance drives coating chemistry upgrades favoring electrolytic tinplate over lower-grade substrates. Hamburg sorting facilities are rejecting non-compliant formats, pressuring mono-material construction adoption.
United States
Midwestern food co-packers are losing shelf-space access to vertically integrated converters as private-label retailer consolidation compresses supplier rosters. EPA hazardous waste rules and FDA food-contact substance notifications govern substrate approval pathways. Ohio and Illinois manufacturing clusters face thinning workforce pipelines for sulfuric acid bath management expertise.
Japan
PMDA aseptic filling requirements are driving pharmaceutical tin container specification upgrades in Osaka and Nagoya pharmaceutical corridors. METI-supported pilot programs for electrolytic chromium oxide hybrid substrates are reducing metal content in acidic food applications. Tokyo-based canmakers are exporting these substrate innovations to Southeast Asian facilities.
Brazil
Ambient soup processors in São Paulo state are expanding tin container procurement as multi-layer plastic pouch substitution stalls on oxygen barrier failures in tropical humidity. ANVISA pharmaceutical packaging regulations are tightening extractables testing protocols. The Campinas industrial cluster hosts growing conversion capacity serving Mercosur food exporters.
Tin Containers Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated substrate-to-container systems and fragmenting across geographic toll-coating networks. Tiered competitive archetypes have emerged: capital-heavy integrated metal packagers, asset-light coating-line lessors, and regional food-channel specialists. Dominant competitive moves include backward integration into tinplate production and strategic licensing of lightweighting patents for thin-gauge variants.
Among North American metal packaging incumbents, Crown Holdings Inc, Ball Corporation, and Silgan Holdings Inc exemplify divergent strategic positions. Crown Holdings represents the vertically integrated archetype spanning aluminum and steel substrates. Ball Corporation anchors R&D-intensive positioning in surface treatment chemistry and lightweighting technologies. Silgan Holdings occupies the regional channel dominance archetype through private-label retailer relationships. These three structures illustrate how capital deployment choices—captive substrate production, technology licensing, or shelf-space control—determine competitive trajectories without requiring identical resource commitments.
| Leading Market Players |
|---|
| Crown Holdings Inc |
| Ball Corporation |
| Silgan Holdings Inc |
| Ardagh Group |
| Toyo Seikan Group Holdings Ltd |
| Can-Pack S.A. |
| Tinplate Company of India Limited |
| Mitsubishi Materials Corporation |
| Hindalco Industries Limited |
| Others |
Value Network & Pricing Analysis
Jamshedpur-based tinplate production concentration in India funnels margin capture toward converters with captive substrate access or BIS-certified import pathways, while London Metal Exchange tin price volatility transmits directly to annual contract renegotiations across food industry buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium electrolytic tinplate, standard tin-free steel, and economy-grade alternatives. Price differentiation rests on coating chemistry certification tier and volume scale commitments. Cost compression in standard grades is intensifying because multi-layer plastic pouches capture ambient soup segments. Private-label retailers exhibit highest price sensitivity due to consolidated procurement power, while pharmaceutical manufacturers show lowest sensitivity given aseptic filling qualification barriers.
Supply Chain Analysis
Tin feedstock draws from Indonesia, China, and Peru mining operations, with electrolytic tinplate substrate anchored in Indian, Japanese, and German mill complexes. Raw material dependencies center on refined tin ingots, cold-rolled steel coils, and chromium oxide coating chemicals. Single-source vulnerability concentrates in Indian BIS-certified import channels. Distribution runs through vertically integrated container converters, toll-coating networks in Southeast Asia, and regional food co-packers serving private-label retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tin container demand tracks processed food procurement cycles, with Indian cold-chain infrastructure gaps sustaining shelf-stable packaging pull through the recovery phase.
For Market Incumbents: Harden coating chemistry master file positions against FDA food-contact modernization timelines. Deepen backward integration into tinplate production at Jamshedpur-adjacent facilities to offset BIS import friction. Lock multi-year toll-coating agreements with emerging Southeast Asian converters before asset-light leasing models fragment manufacturing control. For New Entrants and Emerging Players: Establish a beachhead in South Korean solid perfume specialty containers where embossed finish premiums sustain margin pools. Capture online retail craft food brands through direct-to-metal inkjet customization capabilities. Lead with short-run seasonal design rotation speed against incumbent offset plate changeover constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Midwestern US food co-packers losing shelf-space access to integrated converters. Long-term viability hinges on substrate-to-container system consolidation rather than standalone conversion plays. Watch Indian domestic tinplate capacity utilization rates as inflection signal for regional sourcing advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Production | Captures margin pools at Jamshedpur mills while sidestepping BIS import certification friction. |
| Coating Chemistry Master File Submission | Secures first-mover positioning under FDA food-contact substance notification modernization pathways. |
| Direct-to-Metal Inkjet Deployment | Enables short-run craft brand customization without traditional offset plate changeover cost structures. |
| Electrolytic Chromium Oxide Hybrid Substrate Pilot | Reduces raw material intensity for acidic food applications per METI-supported Japanese programs. |
| Mono-Material Container Construction Redesign | Aligns with EU Packaging and Packaging Waste Directive recycling mandates at German sorting facilities. |
Research Methodology
Cross-validation between primary interviews and trade data anchors the qualitative findings. Conversations with tinplate mill procurement directors, container converter plant managers, food industry packaging engineers, and pharmaceutical regulatory affairs specialists informed substrate specification trends. Secondary sources included BIS certification registries, REACH substance restriction databases, FDA food-contact notification filings, and London Metal Exchange tin contract price series. Bottom-up capacity assessments triangulated against top-down processed food sector procurement estimates.
Calibration against historical tinplate production volumes and container shipment data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, size tier, end-use industry, and distribution channel complexity. CAGRs derived from substrate cost pass-through elasticity and buyer procurement cycle timing. Forecast inputs incorporated BIS certification pipeline delays and EU recycling mandate compliance cost assumptions.
Macroeconomic conditions sit as an overlay; deviation in tin price volatility regimes or processed food sector capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about coating chemistry upgrade adoption curves and toll-coating network expansion rates. Cross-checking against Indian processed food production indices and regional tinplate mill utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Laminated Bulk Bins Market
Containers
Wire Containers Market
Containers
Wooden Barrels Market
Containers
Laboratory Sample Container Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
North America Plastic Bottles and Containers Market
Containers
Global Food Containers Market
Containers
Conipack Pails Market
Containers
Global Multi Pack Carriers Market
Containers
Trigger Sprayer Market
Containers
Feeder Containers Market
Containers
Collapsible Sleeve Containers Market
Containers
Takeout Containers Market
Containers
Belgium Container Glass Market
Containers
Foldable Container Market
Containers
Straight Sided Glass Jar Market