
 Global Exosome Diagnostic and Therapeutic Market | 2026-2036
Global Exosome Diagnostic and Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exosome Diagnostic and Therapeutic Market Foresight
Microfluidic isolation technology is tilting exosome purification away from legacy ultracentrifugation toward chip-based platforms that cut processing time and sample volume. Thermo Fisher Scientific leverages its analytical instrument portfolio to anchor high-throughput exosome characterization workflows. QIAGEN competes through nucleic acid extraction expertise applied to exosomal RNA profiling. Lonza dominates contract manufacturing for exosome therapeutic candidates, extending its cell-and-gene therapy infrastructure into this adjacent modality.
Exosome diagnostic and therapeutic products comprise nanoscale extracellular vesicles, typically 30–150 nm in diameter, that shuttle proteins, lipids, and nucleic acids between cells and serve as minimally invasive biomarker sources for disease detection and targeted drug delivery. Isolation kits and microfluidic platforms capture the fastest-growing demand as labs prioritize speed over yield in clinical settings, while therapeutic agents command premium pricing due to complex GMP manufacturing requirements. Cancer diagnosis occupies the largest application share, though neurodegenerative disorder testing is gaining traction as blood-based tau and alpha-synuclein exosome assays advance toward validation.
FDA biomarker qualification programs and EMA's MDR framework for in vitro diagnostics shape product development timelines and market access conditions for exosome-based tests. Japan's PMDA has issued guidance on extracellular vesicle characterization standards that influence manufacturing protocols for companies targeting Asian markets. Stakeholders must monitor evolving regulatory convergence between diagnostic and therapeutic exosome classifications, as this boundary determines clinical trial design, reimbursement pathways, and partnership structures.
Market Dynamics
Microfluidic isolation platforms are compressing sample-to-result timelines from hours to minutes, forcing diagnostic labs to retire ultracentrifugation workflows and retrain personnel on chip-based protocols.
Growth Catalysts
- FDA Biomarker Qualification Programs:The streamlined validation pathway accelerates clinical adoption of exosome-based liquid biopsies in oncology clinics across the United States.
- Japan PMDA Characterization Guidance:Standardized extracellular vesicle protocols reduce manufacturing variability for companies targeting Asian therapeutic markets.
- Neurodegenerative Blood Assays:Tau and alpha-synuclein exosome detection methods are expanding addressable diagnostic volume beyond cancer into neurology practices.
Market Restraints
- GMP Manufacturing Cost Concentration:Therapeutic-grade exosome production requires specialized cleanroom infrastructure concentrated in Switzerland and Germany, limiting supplier diversity.
- EMA MDR Compliance Burden:The in vitro diagnostic recertification timeline creates cash flow pressure on smaller assay developers.
- Ultracentrifugation Input Volatility:High-purity sucrose and specialized rotor consumables face supply chain concentration from a limited base of precision manufacturers.
Strategic Opportunities
- India CDSCO Diagnostic Pathway:The emerging regulatory framework for advanced molecular diagnostics creates first-mover positioning for exosome assay developers in South Asia.
- Microfluidic-Nanopore Convergence:Integration of chip-based isolation with real-time nucleic acid sequencing is opening same-day diagnostic reporting in emergency medicine settings.
- Direct-to-Consumer Preventive Screening:Wellness platforms in Germany are piloting subscription-based exosome monitoring for early cancer signal detection.
Industry Challenges
- Exosome Characterization Talent Gap:The intersection of nanovesicle biology, microfluidics engineering, and clinical assay development requires cross-trained scientists scarce in both academic and commercial pipelines.
- ISO 13485 Certification Timeline:Diagnostic manufacturers face eighteen-month quality management system audits that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exosome Diagnostic and Therapeutic Market |
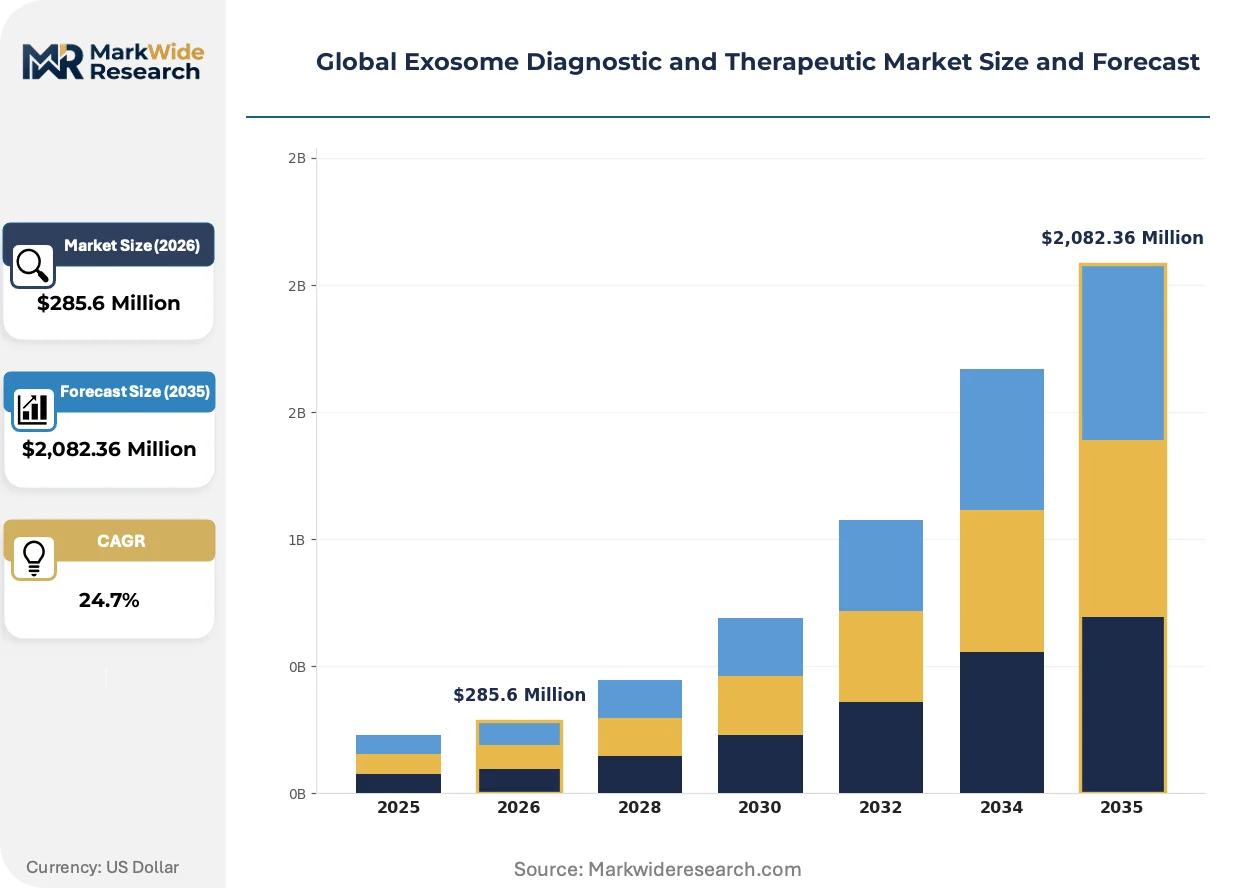
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $2,082.36 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolation Kits, Analysis Instruments, Labeling Reagents, Therapeutic Agents, Storage Solutions Application: Cancer Diagnosis, Neurodegenerative Disorders, Cardiovascular Diseases, Infectious Diseases, Personalized Medicine End User: Clinical Laboratories, Research Institutes, Pharma Companies, Diagnostic Centers, Contract Research Organizations Technology: Ultracentrifugation, Immunoaffinity Capture, Microfluidics, Polymer-Based Precipitation, Size Exclusion Chromatography |
| Companies Covered | Bio-Techne, System Biosciences, Thermo Fisher Scientific, QIAGEN, Evox Therapeutics, Capricor Therapeutics, Direct Biologics, Lonza, ILIAS Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exosome Diagnostic and Therapeutic Market Shifts & Advancements
Chip-based purification systems are collapsing the cost and time barriers that previously confined exosome analysis to research settings, opening clinical-grade workflows to hospital laboratories and point-of-care environments.
Immunoaffinity capture microfluidics is hybridizing surface marker specificity with continuous-flow processing. Oncology diagnostic centers in the United States are adopting these platforms for same-day circulating tumor DNA correlation. The technology is hybridizing previously separate isolation and detection steps into unified cartridge systems that eliminate manual transfer errors.
EMA's MDR framework for in vitro diagnostics is tightening post-market surveillance requirements for exosome-based cancer tests. Manufacturers must now maintain active safety monitoring databases that track assay performance across diverse patient populations. European reference laboratories are responding by consolidating validation partnerships with larger kit suppliers capable of sustaining regulatory infrastructure.
Hospital procurement departments are compressing vendor qualification cycles from multi-year frameworks to eighteen-month renewable contracts. This pattern favors exosome platform suppliers offering integrated instrumentation, consumables, and technical support under unified pricing. The shift is most pronounced in Japanese university medical centers rebuilding supply chains following pandemic-era disruptions.
Global Exosome Diagnostic and Therapeutic Market Segmentation
Exosome market segmentation reveals divergent margin profiles across product categories. Isolation technologies and clinical applications command fundamentally different pricing architectures based on regulatory burden and manufacturing complexity.
Product Type:
Cycle times vary dramatically: consumables turn monthly while therapeutic agents require multi-year GMP validation. Isolation kits and labeling reagents move fastest through procurement channels.
- Isolation Kits:Buffer-based systems and spin-column formats enable benchtop exosome capture from biofluids without specialized equipment. Clinical laboratories in the United States prioritize these for liquid biopsy workflows where FDA biomarker qualification programs accelerate validation timelines.
- Therapeutic Agents:GMP-grade exosome formulations for targeted drug delivery carry the highest manufacturing burden and regulatory scrutiny. Lonza's contract manufacturing infrastructure in Switzerland and Germany concentrates production for companies advancing candidates through EMA pathways.
- Analysis Instruments:Nanoparticle tracking analyzers and flow cytometry systems for exosome characterization.
- Labeling Reagents:Fluorescent dyes and conjugated antibodies for exosome surface marker detection.
- Storage Solutions:Cryopreservation media and temperature-controlled logistics for exosome stability.
Isolation kits dominate installed base. Therapeutic agents are where expansion concentrates.
Application:
Cost tiers separate research-grade screening from reimbursed diagnostic testing. Cancer applications absorb premium pricing while infectious disease testing competes on throughput.
- Cancer Diagnosis:Circulating tumor-derived exosomes enable minimally invasive monitoring of treatment response and recurrence. Oncology clinics across Germany and Japan are building dedicated liquid biopsy infrastructure around these assays.
- Neurodegenerative Disorders:Blood-based tau and alpha-synuclein exosome detection is advancing toward clinical validation for Alzheimer's and Parkinson's disease. Neurology practices represent the steepest expansion trajectory as non-invasive alternatives to cerebrospinal fluid collection emerge.
- Cardiovascular Diseases:Exosomal miRNA signatures for myocardial injury and heart failure risk stratification.
- Infectious Diseases:Pathogen-derived exosome detection for viral and bacterial infection monitoring.
- Personalized Medicine:Patient-specific exosome profiling to guide therapeutic selection.
Cancer diagnosis captures current revenue concentration. Neurodegenerative applications are climbing the fastest.
End User:
Volume concentration sits with high-throughput testing facilities, though margin pools favor specialized therapeutic developers. Procurement authority fragments across research, clinical, and commercial organizations.
- Clinical Laboratories:Hospital-based and independent reference labs processing exosome-based cancer tests under CLIA certification. Japanese university medical centers are consolidating vendor relationships into eighteen-month renewable contracts following pandemic supply chain disruptions.
- Pharma Companies:Biopharmaceutical developers leveraging exosomes as drug delivery vehicles and companion diagnostic platforms. These organizations command dedicated manufacturing slots at GMP facilities due to therapeutic-grade requirements.
- Research Institutes:Academic centers advancing exosome biology and assay development.
- Diagnostic Centers:Specialized imaging and pathology facilities integrating exosome testing.
- Contract Research Organizations:Service providers managing clinical trial sample processing and biomarker analysis.
Clinical laboratories anchor routine testing volume. Pharma companies drive therapeutic segment investment.
Technology:
Maturity curves separate legacy platforms from emerging chip-based systems. Ultracentrifugation retains research dominance while microfluidics captures clinical adoption.
- Microfluidics:Chip-based isolation platforms compress sample-to-result timelines from hours to minutes through continuous-flow processing. Immunoaffinity capture microfluidics specifically is hybridizing surface marker specificity with automation for same-day circulating tumor DNA correlation in United States oncology centers.
- Ultracentrifugation:Density-gradient centrifugation remains the gold standard for high-purity exosome isolation in research settings. Supply chain concentration in high-purity sucrose and specialized rotor consumables from limited precision manufacturers creates input volatility.
- Immunoaffinity Capture:Antibody-coated beads and plates for selective exosome subpopulation isolation.
- Polymer-Based Precipitation:PEG-based reagents for bulk exosome recovery without equipment.
- Size Exclusion Chromatography:Column-based separation by hydrodynamic radius for gentle isolation.
Ultracentrifugation dominates research installed base. Microfluidics is where clinical expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German exosome therapeutic developers export GMP-grade formulations to oncology centers across the United States and Japan, establishing a transatlantic trade corridor in clinical-grade nanovesicle supply.
United States
FDA biomarker qualification programs accelerate liquid biopsy adoption at Mayo Clinic and Memorial Sloan Kettering. The agency's streamlined validation pathway compresses clinical trial timelines for circulating tumor-derived exosome assays. Boston's Kendall Square biotech cluster concentrates diagnostic platform development alongside venture capital funding for microfluidic startups.
Germany
EMA's MDR framework shapes recertification strategies for in vitro diagnostic manufacturers in Cologne and Heidelberg. The regulatory burden favors larger kit suppliers capable of sustaining post-market surveillance databases. Bavaria's Munich biotech corridor anchors GMP manufacturing infrastructure for therapeutic-grade exosome production serving European oncology networks.
Japan
PMDA characterization guidance standardizes extracellular vesicle protocols for companies targeting Asian therapeutic markets. Tokyo and Osaka university medical centers consolidate vendor relationships into eighteen-month renewable contracts. The Kanto region rebuilds supply chain resilience following pandemic-era disruptions through dedicated exosome testing infrastructure.
Switzerland
Swissmedic oversight concentrates therapeutic-grade exosome manufacturing in Basel and Zurich. Lonza's contract manufacturing infrastructure dominates GMP production for biopharmaceutical developers advancing candidates through European regulatory pathways. The country's precision manufacturing heritage supports specialized cleanroom requirements for nanovesicle formulation.
India
CDSCO's emerging diagnostic pathway for advanced molecular testing creates first-mover positioning for assay developers in Hyderabad and Bengaluru. The regulatory framework attracts contract research organizations establishing exosome biomarker analysis capabilities. Maharashtra's Pune biotech cluster incubates platform companies targeting South Asian liquid biopsy demand.
Global Exosome Diagnostic and Therapeutic Market Competitive Landscape
On the supply side, the industry is bifurcated between analytical instrumentation conglomerates and specialized nanovesicle platform developers. Diagnostic-grade isolation kits flow through quarterly procurement cycles, while therapeutic agents command multi-year GMP validation timelines. Three archetypes dominate: diversified life science tools providers, dedicated exosome biotechnology specialists, and contract manufacturing organizations extending cell-and-gene therapy infrastructure. Competitive moves concentrate on microfluidic technology licensing and strategic partnerships bridging isolation platforms with downstream characterization workflows.
Within the diversified tools tier, Thermo Fisher Scientific and QIAGEN occupy positions anchoring high-throughput analytical workflows and nucleic acid extraction expertise respectively. Lonza exemplifies the contract manufacturing archetype, leveraging Swiss and German GMP infrastructure to serve therapeutic developers. Bio-Techne represents specialized biotechnology players advancing protein and reagent portfolios into exosome research applications. These three company types collectively span the value chain from benchtop isolation through clinical-grade production.
| Leading Market Players |
|---|
| Bio-Techne |
| System Biosciences |
| Thermo Fisher Scientific |
| QIAGEN |
| Evox Therapeutics |
| Capricor Therapeutics |
| Direct Biologics |
| Lonza |
| ILIAS Biologics |
| Others |
Supply & Pricing Matrix
Basel's GMP manufacturing cluster concentrates therapeutic-grade exosome production capacity, granting Swiss contract manufacturers substantial pricing leverage over biopharmaceutical developers seeking clinical-grade nanovesicle supply for oncology trials.
Pricing Analysis
Next-generation microfluidic platforms command 40-60% premiums over legacy ultracentrifugation workflows, while research-grade isolation kits compete on volume throughput. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified therapeutic agents from CLIA-grade diagnostics and research consumables. Pricing pressure stems from hospital procurement departments compressing vendor qualification cycles to eighteen-month renewable contracts. Academic research institutes exhibit highest price sensitivity, while pharma companies developing therapeutic candidates demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Export-control restrictions on advanced microfluidic fabrication equipment limit technology transfer to emerging diagnostic markets, constraining local production capacity in India and Southeast Asia. Supply concentrates in Switzerland, Germany, and the United States for GMP manufacturing, while China and South Korea dominate precision microfluidic chip fabrication. Raw material dependencies include high-purity sucrose for density gradients, specialized rotor consumables, and photoresist materials for chip production. Single-source vulnerability characterizes precision rotor manufacturing from German suppliers. Distribution runs through direct sales teams for therapeutic-grade products and distributor networks for research consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from circulating tumor DNA liquid biopsy platforms that compete for the same oncology diagnostic budgets and clinician attention.
For Market Incumbents: Insulate diagnostic revenue streams by deepening ISO 13485 certification investments that extend quality management system audits into automated manufacturing lines, while securing exclusive supply agreements with Japanese university medical centers rebuilding post-pandemic procurement frameworks. The eighteen-month vendor contract cycle represents the critical control point against emerging microfluidic platform developers. For New Entrants and Emerging Players: Mid-market clinical laboratories in India and Southeast Asia represent the most penetrable entry point, where CDSCO's emerging diagnostic pathway for advanced molecular testing lacks established incumbent relationships and local GMP manufacturing infrastructure remains underdeveloped. A go-to-market angle emphasizing same-day sample-to-result workflows for infectious disease monitoring bypasses entrenched oncology competition in developed markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science tools conglomerates seeking to divest non-core exosome research reagent portfolios amid strategic restructuring. Long-term viability hinges on therapeutic candidate pipelines advancing through EMA and FDA biomarker qualification pathways rather than diagnostic kit commoditization. The inflection signal to monitor is consolidation of microfluidic-nanopore convergence platforms into unified emergency medicine diagnostic systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biomarker Qualification Submission | Streamlined validation pathway accelerates clinical adoption at Mayo Clinic and Memorial Sloan Kettering. |
| Microfluidic Platform Licensing Agreement | Technology transfer enables same-day diagnostic reporting in Japanese university medical centers. |
| GMP Manufacturing Scale-Up | Lonza's Swiss and German infrastructure expansion serves therapeutic developers advancing EMA pathways. |
| Neurodegenerative Assay Pipeline Diversification | Tau and alpha-synuclein blood tests open neurology practices beyond saturated oncology markets. |
| Direct-to-Consumer Preventive Screening Launch | German wellness platforms pilot subscription-based exosome monitoring for early cancer signal detection. |
Research Methodology
The analysis maps isolation technology sub-sectors, therapeutic agent development stages, and diagnostic application areas, each validated through primary interviews with GMP manufacturing executives, clinical laboratory directors, regulatory affairs specialists, and hospital procurement managers, combined with secondary triangulation across FDA biomarker qualification filings, EMA MDR submission databases, PMDA guidance documents, and CDSCO regulatory circulars, integrating bottom-up segment sizing with top-down market validation.
Forecast assumptions held regulatory approval timelines and reimbursement pathway structures fixed while varying technology adoption curves and competitive entry patterns across the projection horizon. Segmentation dimensions modeled include product type, application area, end-user category, and technology platform, with CAGRs derived from fitted growth curves anchored to installed base expansion rates and replacement cycle dynamics. Industry-specific inputs encompassed microfluidic platform penetration rates and GMP manufacturing capacity utilization thresholds.
Stress conditions across FDA biomarker qualification pathway delays, EMA MDR recertification timeline extensions, and microfluidic chip supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in regulatory convergence between diagnostic and therapeutic exosome classifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market