
 Therapeutic Robots Market | 2026-2036
Therapeutic Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Robots Market Outlook
ISO 13485 certification is reorganizing competitive access across the therapeutic robots sector, raising barriers for new entrants in medical-grade hardware. Ekso Bionics Holdings leverages its FDA-cleared portfolio to dominate North American rehabilitation settings. Cyberdyne anchors its position through Japan's PMDA pathway for neurological assistive devices. Stryker Corporation extends its hospital robotics reach via integrated surgical-to-rehabilitation platform strategies.
Therapeutic robots encompass electromechanical systems engineered for clinical intervention, typically integrating force-feedback actuators operating at sub-Newton precision thresholds and real-time physiological monitoring arrays for adaptive patient response. These systems serve primary commercial purposes in restoring motor function, managing cognitive decline, and reducing caregiver burden across institutional and residential settings. Robotic exoskeletons currently occupy the highest-margin product tier due to reimbursement complexity and hardware intensity, while AI-powered robots within the technology dimension attract disproportionate R&D allocation from hospital end users seeking predictive analytics integration. Companion robots targeting elderly care applications demonstrate the steepest volume trajectory as nursing home operators prioritize non-pharmacological behavioral interventions.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements jointly determine which therapeutic robot platforms achieve commercial scale across regulated markets. Japan's METI subsidizes elderly care robot procurement through specified facility certification programs, directly shaping manufacturer geographic prioritization. Stakeholders must monitor evolving reimbursement coding for robot-assisted therapy sessions as payer decisions increasingly gate adoption velocity in rehabilitation centers and home care channels.
Market Dynamics
ISO 13485 certification requirements are restructuring competitive access in therapeutic robots, forcing hardware manufacturers to rebuild quality management systems around medical-grade traceability while non-certified vendors retreat to consumer wellness adjacent categories.
Growth Catalysts
- EU MDR compliance pathways:Harmonized technical documentation standards enable cross-border platform deployment across rehabilitation centers in Germany, France, and Italy, reducing redundant certification costs for exoskeleton manufacturers.
- Japan METI facility subsidies:Specified nursing home certification programs directly fund elderly care robot procurement, creating guaranteed demand channels for companion and assistive devices.
- AI-powered predictive analytics:Hospital end users allocate disproportionate R&D budgets toward therapeutic robots integrating real-time physiological monitoring with adaptive force-feedback actuators.
Market Restraints
- PMDA neurological pathway complexity:Japan's device approval framework for assistive technologies imposes extended clinical evidence requirements that delay commercialization timelines for novel exoskeleton platforms.
- Actuator supply concentration:Force-feedback components operating at sub-Newton precision thresholds depend on specialized German and Japanese component suppliers, creating vulnerability to regional production disruptions.
- Reimbursement coding fragmentation:Divergent payer classification for robot-assisted therapy sessions across US Medicare, German statutory health insurance, and Japanese long-term care insurance systems complicates pricing standardization.
Strategic Opportunities
- Home care channel expansion:Residential settings for motor function restoration remain underpenetrated relative to institutional rehabilitation centers, offering volume potential for lower-cost exoskeleton platforms.
- FDA 510(k) predicate pathway:Established clearance frameworks for therapeutic robot categories enable faster market entry compared to de novo classification routes, rewarding incremental innovation strategies.
- Convergence of haptic interfaces with VR:Integration of force-feedback actuators with immersive cognitive training environments creates new reimbursement categories for non-pharmacological behavioral interventions in elderly care.
Industry Challenges
- Biomechanical engineer scarcity:Specialized expertise spanning electromechanical systems, clinical rehabilitation protocols, and regulatory documentation remains concentrated among a limited pool of professionals in Massachusetts, Stuttgart, and Tokyo clusters.
- Legacy EMR integration friction:Therapeutic robot platforms face interoperability barriers with hospital electronic medical record systems, requiring custom API development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Robots Market |
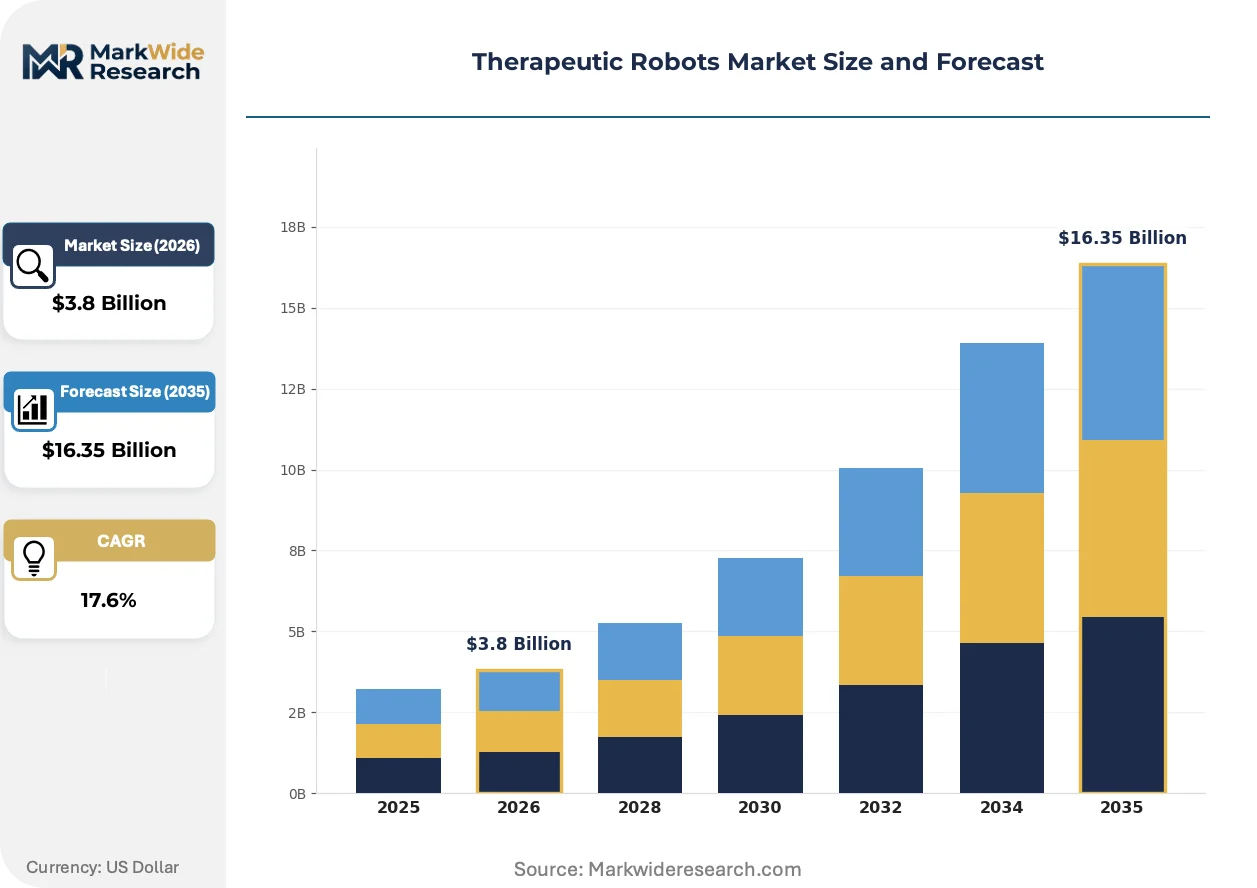
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humanoid Robots, Telepresence Robots, Companion Robots, Robotic Exoskeletons Application: Physical Rehabilitation, Mental Health Therapy, Elderly Care, Pediatric Therapy Technology: AI-Powered Robots, Remote-Controlled Robots, Machine Learning Robots, Sensor-Integrated Robots End User: Hospitals, Rehabilitation Centers, Nursing Homes, Home Care Providers |
| Companies Covered | Ekso Bionics Holdings, Cyberdyne, Intuitive Surgical, Lifeward, Bionik Laboratories, Stryker Corporation, Hocoma, Zimmer Biomet Holdings, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Robots Market Strategic Shifts
Adaptive control architectures are fragmenting the therapeutic robot landscape into precision rehabilitation platforms and volume-oriented assistive devices, with divergent hardware specifications and go-to-market strategies emerging between the two tracks.
Force-feedback actuator technology is bifurcating the exoskeleton segment into sub-Newton precision systems for neurological rehabilitation and higher-tolerance platforms for orthopedic recovery. Academic medical centers in the US and university hospitals in Germany prioritize the former for stroke patient protocols, while private rehabilitation chains favor the latter for cost efficiency. This technical division is compressing mid-range product viability and pushing manufacturers toward explicit tier specialization.
EU MDR technical documentation requirements are extending conformity assessment timelines for therapeutic robot platforms, particularly for devices incorporating AI-driven adaptive response algorithms. notified Bodies in Germany and the Netherlands report expanded audit scopes for software lifecycle processes, forcing manufacturers to restructure development workflows. Exoskeleton vendors with pre-MDR legacy certifications face the steepest transition burdens as they rebaseline clinical evidence packages.
Hospital procurement departments are unbundling after-sales service contracts from hardware acquisition agreements, shifting toward performance-based maintenance arrangements with explicit uptime guarantees. This contractual evolution pressures therapeutic robot manufacturers to build regional service networks or cede margin to third-party technical support providers. The trend is most pronounced in US integrated delivery networks and Japanese hospital groups with centralized purchasing authority.
Therapeutic Robots Market Segmentation
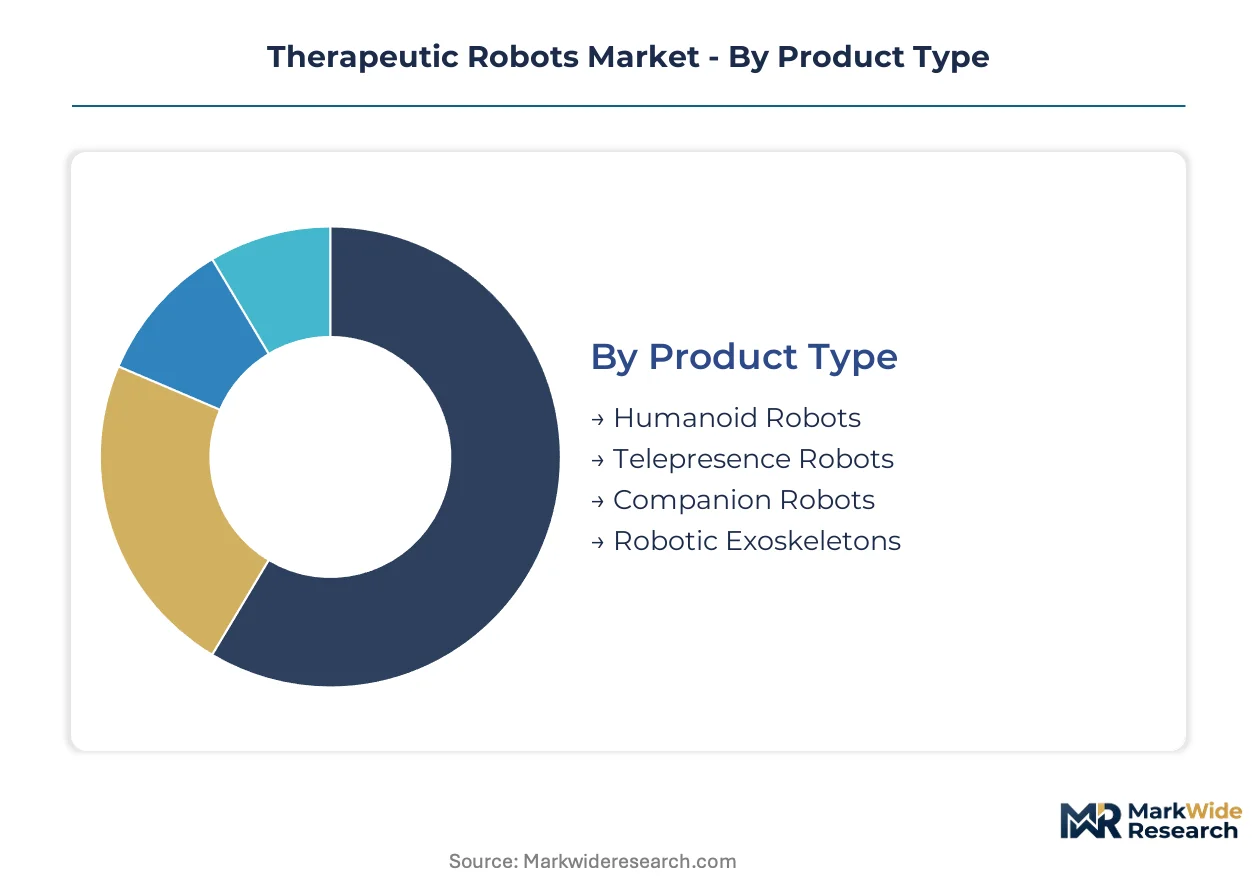
Therapeutic robots segment across hardware configurations, clinical applications, and care settings. Each dimension carries distinct regulatory pathways and reimbursement profiles that determine commercial viability.
Product Type:
Robotic exoskeletons concentrate manufacturing in Germany and Japan for medical-grade export markets, while companion robots serve domestic elderly care procurement in Japan and domestic nursing home channels in the US.
- Robotic Exoskeletons:Electromechanical systems with force-feedback actuators operating at sub-Newton precision thresholds for motor function restoration. Demand concentrates in German rehabilitation centers under EU MDR compliance requirements and US hospital systems seeking FDA 510(k) cleared platforms for stroke protocols.
- Companion Robots:Socially interactive devices engineered for non-pharmacological behavioral intervention in dementia care. Japan's METI facility subsidies drive domestic procurement concentration, while US nursing home operators pilot these systems for caregiver burden reduction.
- Humanoid Robots:Bipedal platforms with articulated manipulation capabilities for physical therapy assistance.
- Telepresence Robots:Mobile video-conferencing systems enabling remote clinician-patient interaction in institutional settings.
Robotic exoskeletons hold the largest share; momentum sits with companion robots.
Application:
Physical rehabilitation commands premium hardware investment, while elderly care applications scale through volume procurement and subsidized deployment programs.
- Physical Rehabilitation:Stroke recovery and orthopedic protocols utilizing adaptive force-feedback systems with real-time physiological monitoring. German statutory health insurance and US Medicare reimbursement coding increasingly covers robot-assisted therapy sessions in designated rehabilitation centers.
- Elderly Care:Cognitive decline management and mobility assistance through AI-powered adaptive response systems. Japan's specified nursing home certification programs create guaranteed demand channels, while European facilities pilot these interventions under CSRD-aligned staffing mandates.
- Mental Health Therapy:Anxiety and PTSD protocols employing haptic feedback and immersive environments.
- Pediatric Therapy:Developmental disorder interventions utilizing gamified interaction modalities.
Physical rehabilitation generates the highest unit economics; elderly care is expanding most quickly.
Technology:
AI-powered architectures attract disproportionate R&D allocation, while sensor-integrated platforms dominate current installed base through proven reliability.
- AI-Powered Robots:Machine learning algorithms enabling predictive patient response and adaptive therapy personalization. Hospital end users in the US and Germany prioritize these systems for integration with electronic medical record workflows and clinical decision support platforms.
- Sensor-Integrated Robots:Multi-modal physiological monitoring arrays capturing kinematic, electromyographic, and cardiovascular data. Established deployment in Japanese rehabilitation facilities under PMDA neurological pathway requirements.
- Machine Learning Robots:Pattern recognition systems for therapy outcome optimization and patient progression modeling.
- Remote-Controlled Robots:Clinician-directed operation for teletherapy and supervised intervention protocols.
Sensor-integrated robots anchor current deployment; AI-powered platforms show the steepest expansion trajectory.
End User:
Rehabilitation centers concentrate high-acuity exoskeleton demand, while home care channels remain underpenetrated relative to institutional settings.
- Rehabilitation Centers:Specialized facilities in Germany, Japan, and the US deploying FDA-cleared and EU MDR-compliant platforms for intensive motor function restoration. Reimbursement complexity favors established hardware vendors with predicate clearance pathways.
- Nursing Homes:Long-term care facilities prioritizing companion robots and assistive devices for behavioral intervention and staffing efficiency. Japanese METI subsidies and US Medicaid waiver programs shape procurement concentration.
- Hospitals:Acute care settings integrating therapeutic robots into surgical-to-rehabilitation platform strategies.
- Home Care Providers:Residential service organizations piloting lower-cost exoskeleton platforms for post-acute motor function maintenance.
Rehabilitation centers capture the highest hardware margins; home care providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rehabilitation centers and nursing home operators drive procurement concentration across Japan, Germany, and the United States, with facility certification programs and reimbursement pathways determining manufacturer geographic prioritization.
United States
FDA 510(k) clearance pathways attract exoskeleton manufacturers targeting stroke rehabilitation protocols in acute care settings. Medicare reimbursement coding for robot-assisted therapy sessions shapes hospital procurement decisions. The Boston-Cambridge cluster concentrates biomechanical engineering talent and venture capital deployment for therapeutic hardware startups.
Germany
EU MDR compliance requirements reorganize competitive access for medical-grade exoskeleton platforms serving statutory health insurance reimbursement channels. Notified Bodies in Stuttgart and Munich extend audit scopes for AI-driven adaptive response algorithms. The Stuttgart-Tübingen corridor anchors precision actuator manufacturing for sub-Newton force-feedback systems.
Japan
METI facility subsidies through specified nursing home certification programs create guaranteed demand channels for companion and assistive devices. PMDA neurological pathway complexity delays commercialization timelines for novel exoskeleton platforms. Tokyo-Osaka metropolitan areas concentrate deployment of elderly care robots in designated long-term care facilities.
South Korea
MFDS medical device approval frameworks enable export-oriented manufacturing of rehabilitation robotics for Asia-Pacific markets. National health insurance pilot programs for robot-assisted therapy expand institutional procurement in Seoul metropolitan hospitals. The Daegu-Gyeongbuk region hosts component suppliers for sensor-integrated therapeutic platforms.
Switzerland
Swissmedic certification requirements position the country as a gateway for EU market entry through mutual recognition agreements. University hospitals in Zurich and Geneva pilot AI-powered predictive analytics integration with rehabilitation protocols. The Basel-Zurich corridor concentrates R&D facilities for haptic interface and force-feedback technology development.
Therapeutic Robots Market Competitive Environment
Player mix skews toward medical device conglomerates with rehabilitation portfolios and specialized exoskeleton developers with regulatory clearance expertise. The competitive structure tiers across FDA-cleared platform holders, EU MDR-compliant hardware vendors, and METI-subsidized domestic suppliers in Japan. Dominant archetypes include integrated surgical-to-rehabilitation strategists, precision actuator technology specialists, and AI-powered adaptive system developers. Competitive moves concentrate on predicate pathway leveraging for faster FDA entry and performance-based service contract unbundling to capture hospital procurement shifts.
Among the named players, Ekso Bionics Holdings and Cyberdyne exemplify divergent regulatory anchoring strategies, with the former representing North American 510(k) pathway specialization and the latter occupying Japan's PMDA neurological device framework. Stryker Corporation sits within the medical device conglomerate archetype, leveraging integrated platform strategies that span acute surgical intervention through post-acute rehabilitation. These three companies illustrate how geographic regulatory prioritization and hardware-software integration depth determine positioning across institutional procurement channels.
| Leading Market Players |
|---|
| Ekso Bionics Holdings |
| Cyberdyne |
| Intuitive Surgical |
| Lifeward |
| Bionik Laboratories |
| Stryker Corporation |
| Hocoma |
| Zimmer Biomet Holdings |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German precision actuator facilities shapes both supply concentration and price floors for sub-Newton force-feedback systems, with EU MDR compliance costs embedding upward pressure across medical-grade hardware tiers while Japanese component sourcing creates geographic cost divergence.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement between exoskeleton manufacturers and German precision actuator suppliers. Three-tier pricing structure across FDA-cleared premium platforms, EU MDR-compliant standard systems, and economy-grade assistive devices reflects certification investment differentials. Pricing pressure stems from hospital procurement departments unbundling after-sales service contracts and demanding performance-based uptime guarantees. Rehabilitation centers show highest price sensitivity due to reimbursement coding uncertainty, while Japanese nursing homes under METI subsidies demonstrate lowest sensitivity.
Supply Chain Analysis
Germany and Japan anchor precision actuator manufacturing for sub-Newton force-feedback systems, with Stuttgart-Tübingen and Tokyo-Osaka corridors concentrating specialized biomechanical component production. Supply chains draw from rare earth magnet suppliers in China, precision machining capacity in Switzerland, and sensor arrays from South Korean semiconductor fabricators. Single-source vulnerability concentrates in German torque motor suppliers serving neurological rehabilitation platforms. Distribution runs through hospital GPO contracts in the US, statutory health insurance procurement frameworks in Germany, and METI-certified facility channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The therapeutic robots market exhibits cyclical recovery characteristics as hospital capital expenditure cycles normalize post-pandemic, with rehabilitation center infrastructure investment serving as the primary cyclical driver.
For Market Incumbents: Fortify predicate pathway portfolios through incremental FDA 510(k) submissions that leverage existing clearances for faster market entry. Deepen regional service network density to capture unbundled performance-based maintenance contracts from hospital procurement departments. ISO 13485 certification investments create defensive moats against emerging hardware vendors lacking medical-grade quality management systems.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways through substantial equivalence claims offer the most penetrable regulatory entry point for exoskeleton developers. Home care channels for post-acute motor function maintenance remain underpenetrated relative to institutional rehabilitation settings, presenting white-space opportunity for lower-cost platform architectures. Partnership strategies with established rehabilitation center chains enable rapid clinical validation and reimbursement coding establishment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-powered adaptive system developers with proven physiological monitoring integration and EMR interoperability capabilities. Long-term viability over the next decade hinges on predictive analytics differentiation and software recurring revenue streams. Watch for inflection signals in Medicare reimbursement coding decisions for robot-assisted therapy sessions, as payer coverage determinations gate adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Medical-grade quality management systems unlock EU MDR compliance and hospital procurement eligibility. |
| AI Companion Software Development | Predictive analytics integration attracts disproportionate R&D allocation from US hospital end users. |
| Home Care Channel Partnership | Residential motor function restoration offers volume expansion beyond saturated institutional rehabilitation markets. |
| Performance-Based Service Contract | Uptime guarantees align with hospital procurement shifts toward unbundled maintenance arrangements. |
| PMDA Neurological Pathway Navigation | Japan's assistive device framework creates regulatory moat for commercialized exoskeleton platforms. |
Study Parameters
The analysis maps robotic exoskeletons, companion robots, AI-powered platforms, and sensor-integrated systems, each validated through rehabilitation center administrators, biomedical engineers, hospital procurement managers, and regulatory affairs specialists. Primary interviews combined with secondary validation from FDA 510(k) databases, EU MDR notified body registries, METI facility certification records, and hospital GPO contract filings. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates across hardware configurations and care settings.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, clinical application, technology architecture, and end-user setting. CAGRs derived from regression analysis of historical procurement trajectories, reimbursement pathway evolution, and facility certification program expansion. Forecast inputs incorporate actuator supply constraints, regulatory timeline distributions, and payer coverage probability assessments.
Decision-makers should treat outputs as directional under stable reimbursement coding and supply continuity assumptions; material deviation in Medicare or German statutory health insurance coverage decisions would warrant model refresh. Recalibration cycles align with material shifts in regulatory clearance timelines, facility subsidy program revisions, and precision actuator supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market