
 Cold Rolling Oils/Lubricants Market | 2026-2036
Cold Rolling Oils/Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Rolling Oils/Lubricants Market Analysis
The EU Green Deal is consolidating demand for low-VOC cold rolling oils across European steel manufacturing. Quaker Houghton leverages its specialty lubricant portfolio to serve automotive OEM qualification programs. Fuchs Petrolub anchors German industrial demand through technical service networks tied to mill audits. Shell competes on synthetic base stock supply security for high-speed tandem mills.
Cold rolling oils/lubricants are formulated liquids applied between rolls and metal strip to reduce friction, control temperature, and prevent surface defects during thickness reduction. These formulations typically contain base oils, emulsifiers, extreme-pressure additives, and corrosion inhibitors at oil concentrations of 2-10% in water for emulsion systems. Synthetic oil formulations command premium positioning in aluminum processing where surface finish tolerances are tightest. Bio-based oil demand is accelerating fastest among European fabricators facing extended producer responsibility rules. Mineral oil retains volume dominance in legacy steel mills where capital constraints limit fluid system conversions.
EPA air quality standards and REACH substance restrictions are reshaping formulation chemistry across North American and European markets. China's MEE enforces wastewater discharge limits that push mills toward water-soluble and semi-synthetic systems. India's BIS lubricant standards are tightening for imported cold rolling products used in government-funded steel expansion. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in multi-regional supply chains.
Market Dynamics
REACH substance restrictions and China's MEE wastewater discharge limits are forcing simultaneous chemistry reformulation across European and East Asian steel corridors, compressing product development cycles for lubricant suppliers serving flat-rolled aluminum and automotive-grade steel.
Growth Catalysts
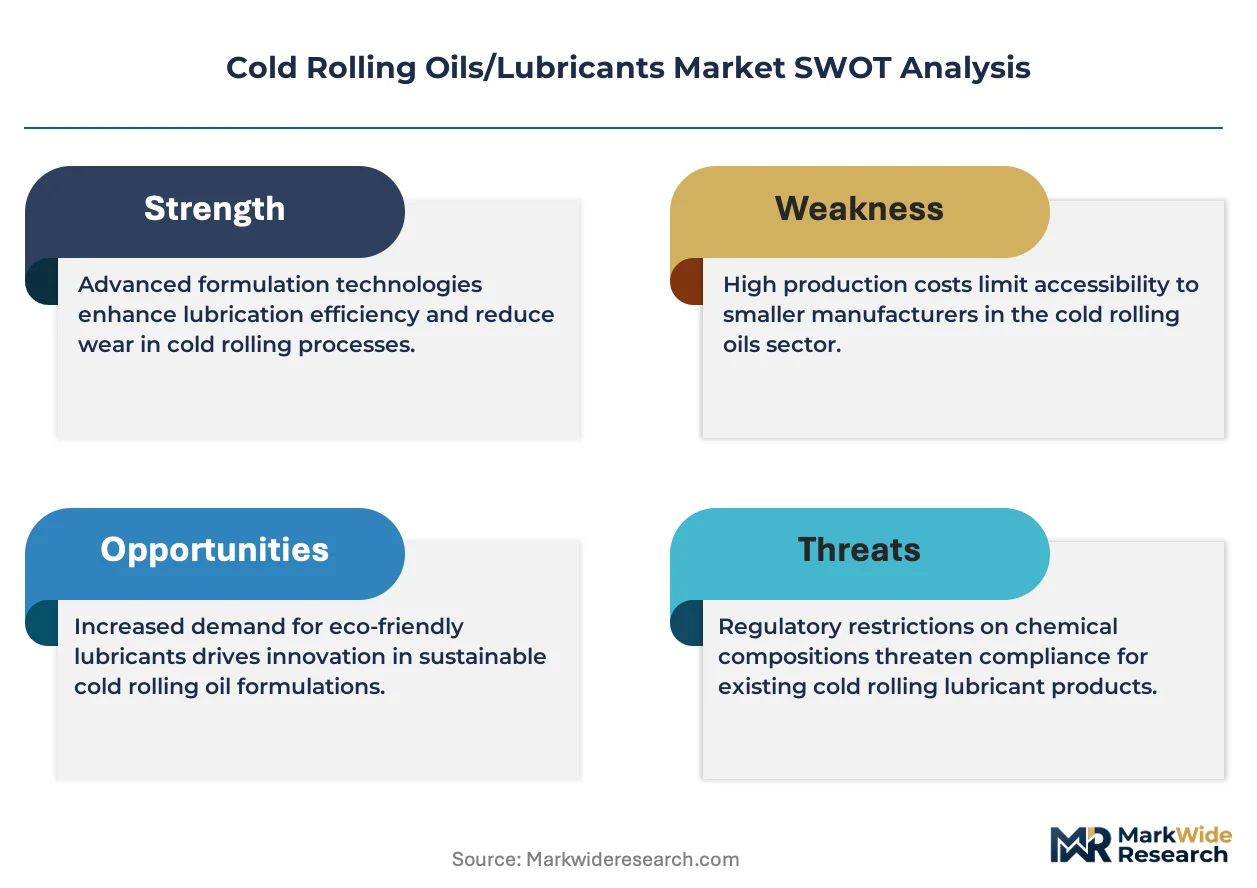
- EU Green Deal low-VOC mandates:European steel mills are accelerating bio-based fluid procurement to meet extended producer responsibility rules ahead of 2030 compliance deadlines.
- Aluminum surface finish tolerances:Synthetic oil formulations are capturing premium positioning in high-speed tandem mills where defect rates must stay below 0.3%.
- India's PLI scheme for specialty steel:Government-funded capacity expansion is importing cold rolling lubricants that meet tightened BIS standards for automotive-grade output.
Market Restraints
- Base stock supply concentration:Synthetic ester and polyalphaolefin feedstock production clusters in Germany and the US Gulf Coast, exposing buyers to regional disruption risk.
- Capital intensity of fluid system conversion:Legacy steel mills in Eastern Europe face seven-figure retrofit costs to switch from mineral oil to water-soluble emulsion systems.
- REACH authorization timelines:ECHA substance evaluation delays are freezing formulation approvals for extreme-pressure additives containing chlorinated paraffins.
Strategic Opportunities
- Underpenetrated Indian flat-rolled capacity:Greenfield steel projects in Odisha and Jharkhand lack established lubricant supply relationships, creating first-mover positioning for technical service providers.
- Water-soluble system convergence with MEE compliance:Semi-synthetic emulsion chemistry is aligning with China's dual carbon goals while reducing wastewater treatment burden.
- Automotive OEM qualification programs:Tier-1 suppliers are unbundling lubricant specification from mill equipment contracts, opening direct supplier-mill relationships.
Industry Challenges
- Formulation chemist scarcity:Tribology expertise combining metalworking fluid chemistry with aluminum rolling metallurgy concentrates at a handful of German and Japanese technical institutes.
- Multi-jurisdiction inventory stranding:Divergent EPA, REACH, and MEE substance lists force parallel product lines, complicating supply chain planning for multinational lubricant distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Rolling Oils/Lubricants Market |
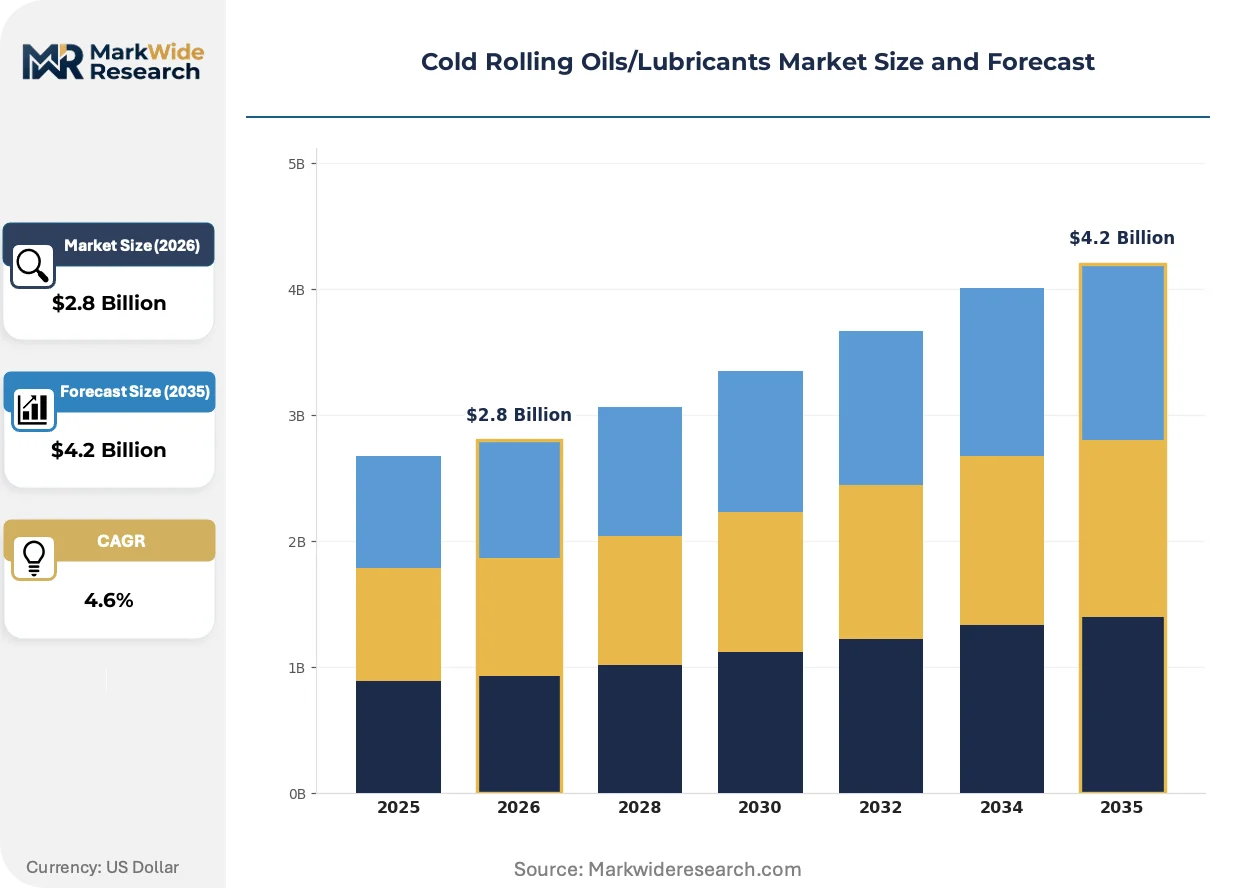
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Water-Soluble Oil, Bio-Based Oil Application: Steel Manufacturing, Aluminum Processing, Metalworking, Automotive Components Delivery Mode: Bulk Supply, Drummed Supply, Packaged Supply, Direct Supply End User: Manufacturers, OEMs, Fabricators, Maintenance Services |
| Companies Covered | Quaker Houghton, ExxonMobil, BP, Fuchs Petrolub, TotalEnergies, Croda International, Houghton International, Shell, ETNA Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Rolling Oils/Lubricants Market Emerging Trajectories
Synthetic base stock electrification, regulatory chemistry compression, and procurement unbundling are restructuring how cold rolling lubricants are formulated, approved, and supplied to steel and aluminum producers.
Electrified rolling mill designs are electrifying demand for thermally stable synthetic lubricants that withstand higher strip speeds without viscosity breakdown. Automotive OEMs in Germany and Japan are specifying these fluids for electric vehicle-grade steel production. The technology is electrifying supplier R&D allocation toward polyalphaolefin and ester chemistry platforms.
REACH Annex XIV authorization requirements are forcing substitution of chlorinated extreme-pressure additives with sulfur-phosphorus compounds across European steel manufacturing. ECHA substance evaluation timelines are compressing reformulation windows to eighteen months. Aluminum cold rolling lines in Italy and France are absorbing the highest compliance costs due to tighter surface defect tolerances.
Mill procurement departments are fragmenting lubricant specification authority away from captive equipment suppliers. Tier-1 automotive steel buyers in Japan are issuing direct fluid qualification standards to lubricant companies. This pattern is most visible in the Kansai and Chukyo industrial corridors where Toyota and Honda concentrate supplier development resources.
Cold Rolling Oils/Lubricants Market Segmentation
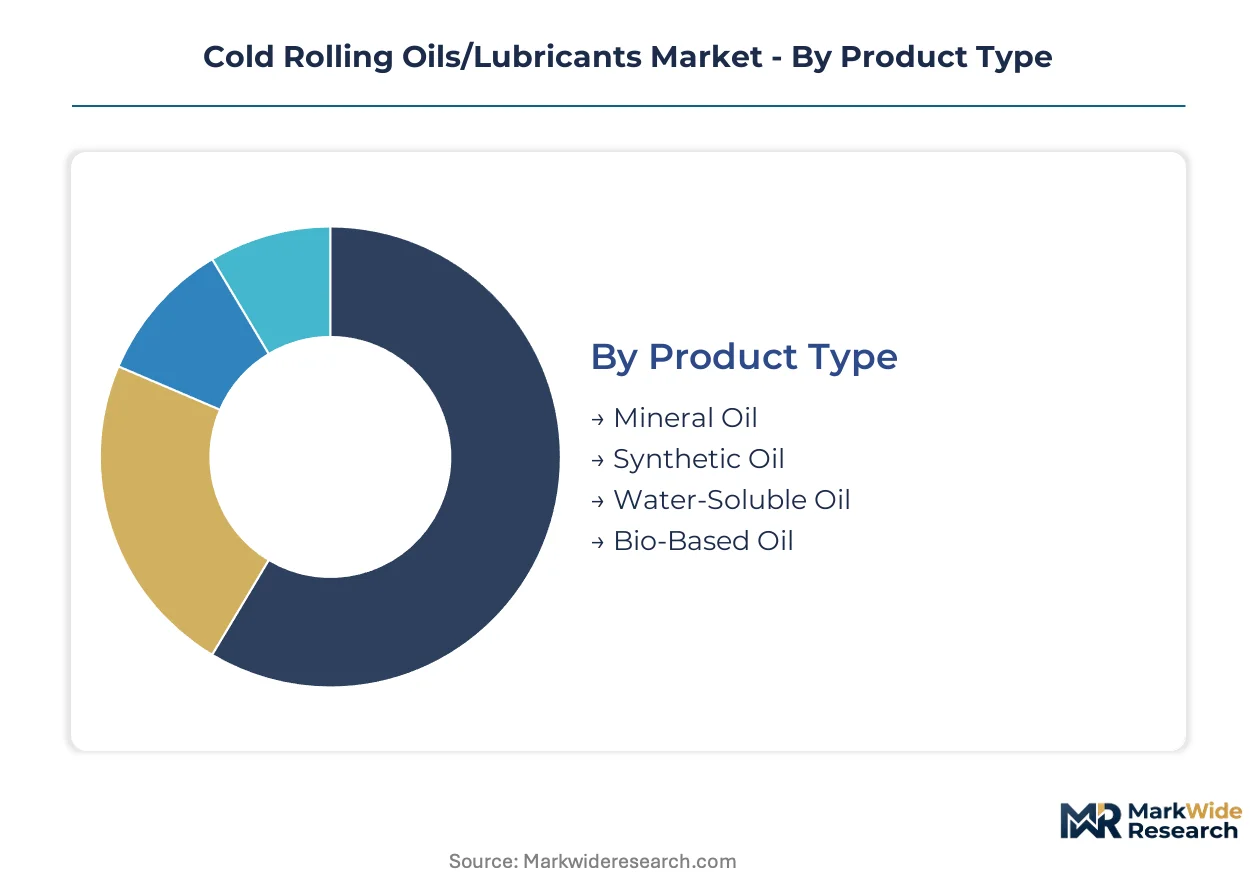
Cold rolling lubricant procurement diverges sharply across product chemistry, metal substrate, and supply chain configuration. Specification authority is fragmenting as mills and automotive buyers impose distinct qualification regimes on each segment axis.
Product Type:
Synthetic ester and polyalphaolefin platforms are displacing legacy mineral formulations in high-speed tandem applications.
- Mineral Oil:Paraffinic and naphthenic base stocks dominate legacy steel mills in Eastern Europe and India where capital constraints block fluid system conversions. BIS lubricant standards for government-funded Indian steel expansion still permit mineral oil deployment in greenfield projects with basic surface finish requirements.
- Synthetic Oil:Polyalphaolefin and ester formulations withstand thermal stress in aluminum tandem mills where strip speeds exceed 2,000 meters per minute. Demand concentrates in Germany and Japan where automotive OEMs specify synthetic fluids for electric vehicle-grade steel production.
- Water-Soluble Oil:Emulsion systems at 2-10% oil concentration align with China's MEE wastewater discharge limits. Semi-synthetic variants reduce treatment burden in East Asian flat-rolled corridors.
- Bio-Based Oil:Vegetable-derived esters from rapeseed and sunflower feedstocks satisfy REACH extended producer responsibility rules. European fabricators in Italy and France absorb premium pricing to meet EU Green Deal low-VOC mandates.
Mature deployment sits with mineral oil in legacy steel infrastructure. Newer deployment is concentrated in bio-based formulations across European automotive supply chains.
Application:
Surface finish tolerance specifications determine lubricant chemistry selection across metal substrate categories.
- Steel Manufacturing:Hot-rolled coil reduction to cold-rolled sheet consumes emulsion volumes in water-intensive tandem mills. German and Japanese automotive OEM procurement programs are unbundling lubricant specification from mill equipment contracts.
- Aluminum Processing:Foil and can-stock rolling demands synthetic formulations with defect rate ceilings below 0.3%. Premium positioning reflects tight surface tolerances in beverage packaging and aerospace-grade output.
- Metalworking:General fabrication and stamping operations use lower-specification emulsions with corrosion inhibitor packages. Maintenance services in India's Odisha and Jharkhand corridors lack established supply relationships.
- Automotive Components:Tier-1 suppliers in Japan's Kansai and Chukyo industrial corridors issue direct fluid qualification standards. Toyota and Honda concentrate supplier development resources on tribology performance validation.
Volume concentration tracks steel manufacturing. Margin expansion is steepest in aluminum processing.
Delivery Mode:
Supply chain configuration reflects mill scale, inventory carrying capacity, and technical service requirements.
- Bulk Supply:Tanker deliveries to integrated steelworks enable continuous emulsion system replenishment. German mill clusters along the Rhine corridor optimize logistics through pipeline-connected storage.
- Drummed Supply:200-liter containers serve mid-scale aluminum processors with batch mixing requirements. Distribution networks in Japan's Chukyo region maintain drum rotation programs for synthetic fluid freshness.
- Packaged Supply:Smaller fabricators and maintenance services purchase 20-liter containers for spot applications. India's fragmented metalworking sector relies on packaged formats due to working capital constraints.
- Direct Supply:Lubricant suppliers embed technical staff at high-volume mill sites for formulation tuning. Quaker Houghton and Fuchs Petrolub deploy direct service teams at German automotive-grade steel facilities.
Direct supply dominates high-value synthetic contracts. Packaged supply persists in price-sensitive maintenance segments.
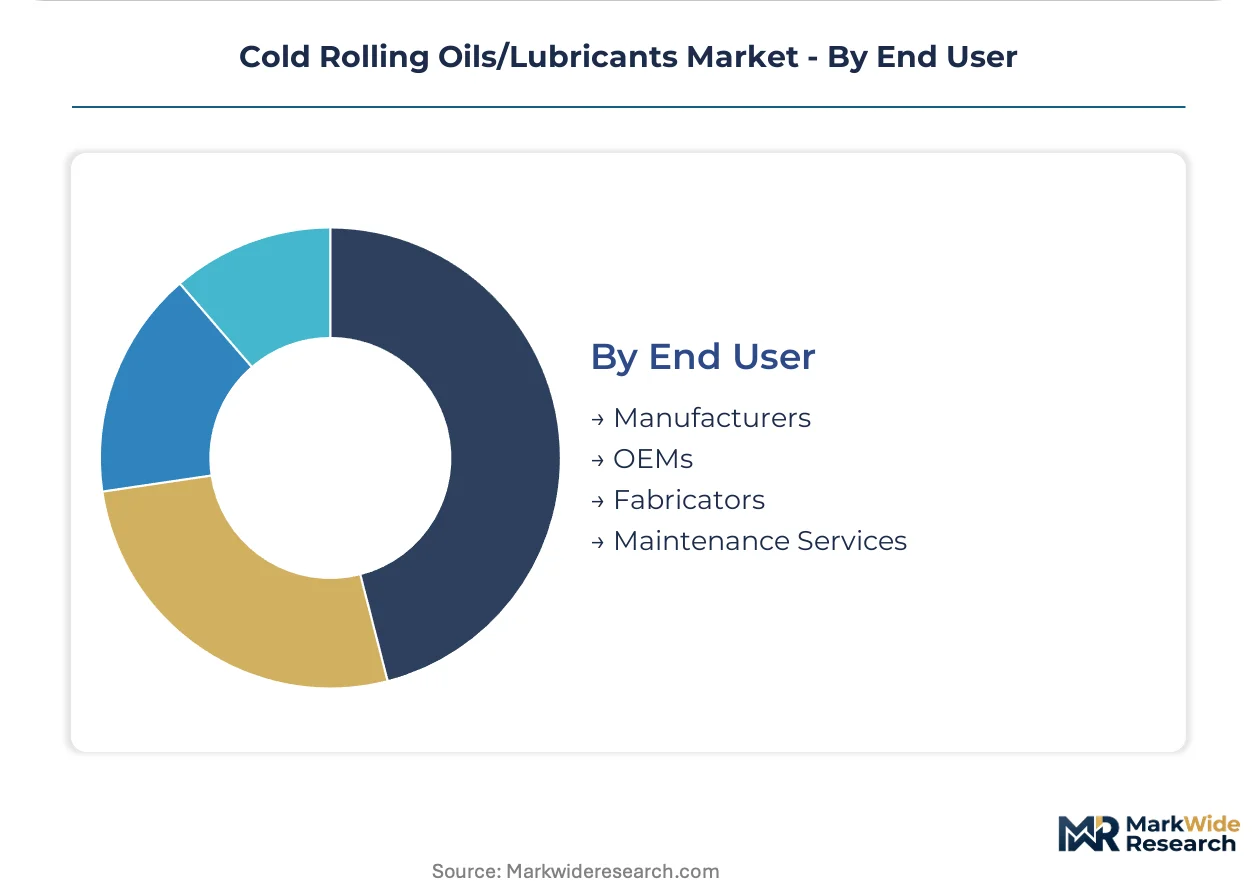
End User:
Procurement authority fragmentation is reshaping supplier-mill relationships across the value chain.
- Manufacturers:Integrated steel and aluminum producers specify lubricants through technical procurement departments with metallurgical expertise. China's state-owned mills coordinate MEE compliance through centralized purchasing.
- OEMs:Automotive original equipment manufacturers in Germany and Japan are issuing direct fluid qualification standards. Unbundling from captive equipment suppliers creates first-mover positioning for lubricant companies.
- Fabricators:Independent cold rolling and slitting operations prioritize cost minimization over performance optimization. REACH compliance costs in France and Italy pressure margin-sensitive fabricators toward bio-based alternatives.
- Maintenance Services:Third-party fluid management providers handle emulsion monitoring and additive replenishment. Technical service scarcity in India's emerging steel corridors limits maintenance service penetration.
Specification authority is shifting from manufacturers to OEMs. Fabricators face the steepest compliance cost absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European cold rolling lubricant procurement, with German automotive OEMs driving bio-based formulation demand through direct supplier qualification programs.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify synthetic fluids for electric vehicle-grade steel production. REACH Annex XIV authorization timelines compress reformulation windows to eighteen months for chlorinated additive substitution. Mill clusters along the Rhine corridor optimize logistics through pipeline-connected bulk storage systems.
China
State-owned steel mills in the Yangtze River Delta coordinate centralized purchasing for MEE wastewater compliance. Semi-synthetic emulsion chemistry aligns with dual carbon goals while reducing treatment burden. High-speed aluminum tandem lines in Jiangsu province require synthetic formulations at strip speeds exceeding 2,000 meters per minute.
Japan
Toyota and Honda concentrate supplier development resources in the Kansai and Chukyo industrial corridors. METI standards push mills toward tribology performance validation beyond basic fluid specifications. Tier-1 automotive steel buyers issue direct qualification standards, unbundling lubricant procurement from captive equipment contracts.
India
Greenfield steel projects in Odisha and Jharkhand lack established lubricant supply relationships, creating first-mover positioning opportunities. The PLI scheme for specialty steel imports cold rolling lubricants meeting tightened BIS standards. Working capital constraints force fragmented metalworking sectors toward packaged supply formats.
United States
EPA air quality standards reshape formulation chemistry across Gulf Coast synthetic base stock production clusters. Aluminum processors in the Midwest require thermally stable lubricants for electrified rolling mill designs. Automotive OEM qualification programs in Detroit mirror German and Japanese procurement unbundling patterns.
Cold Rolling Oils/Lubricants Market Vendor Landscape
The competitive structure tilts toward integrated specialty chemical conglomerates with captive tribology expertise. Three to five multinational lubricant suppliers anchor volume contracts through embedded technical service teams at high-volume mill sites. Strategic archetypes include synthetic base stock specialists, bio-based formulation innovators, and full-service fluid management providers. Dominant competitive moves encompass geographic expansion into underpenetrated Indian flat-rolled capacity and portfolio diversification toward water-soluble emulsion systems.
Within the integrated specialty chemical tier, Quaker Houghton and Fuchs Petrolub exemplify archetypes combining formulation chemistry with direct mill-site technical service. Shell occupies a position reflecting synthetic base stock supply security for high-speed tandem applications. These three entities represent the concentration of tribology expertise combining metalworking fluid chemistry with aluminum rolling metallurgy.
| Leading Market Players |
|---|
| Quaker Houghton |
| ExxonMobil |
| BP |
| Fuchs Petrolub |
| TotalEnergies |
| Croda International |
| Houghton International |
| Shell |
| ETNA Products |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement programs in Germany and Japan anchor value-based pricing through direct fluid qualification standards that tie contract terms to surface defect rates and mill uptime performance. REACH compliance costs and synthetic base stock scarcity concentrate pricing power among suppliers with captive tribology expertise.
Pricing Analysis
Throughput-linked value pricing dominates high-speed aluminum tandem mills where defect rate ceilings below 0.3% determine contract value. Price differentiation rests on certification grade for EU Green Deal compliance and volume scale for bulk emulsion deliveries. Cost compression in bio-based formulations is intensifying because rapeseed and sunflower feedstock availability tightens across European agricultural supply chains. Fabricators in Italy and France absorb premium pricing with limited negotiating leverage, while legacy steel mills in Eastern Europe retain standard mineral oil contracts with higher price sensitivity.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and Japan's Chukyo industrial region feed hub-and-spoke patterns serving high-volume mill clusters. Synthetic ester and polyalphaolefin production concentrates in Germany and the US Gulf Coast, drawing from specialty chemical feedstocks and chlorinated paraffin alternatives. Single-source vulnerability in extreme-pressure additive supply chains exposes formulators to ECHA authorization delays. Distribution runs through pipeline-connected bulk systems for integrated steelworks and drum rotation programs for mid-scale aluminum processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic base stock production capacity constraints prop pricing premiums, with formulation chemist scarcity limiting supply expansion faster than demand growth across East Asian flat-rolled corridors.
For Market Incumbents: Deploy embedded technical service teams at greenfield steel projects in Odisha and Jharkhand to preempt competitor positioning. Deepen backward integration into bio-based ester feedstocks before EU extended producer responsibility rules tighten further. Lock in long-term offtake agreements with Yangtze River Delta state-owned mills facing MEE wastewater compliance deadlines. For New Entrants and Emerging Players: Digital fluid monitoring platforms offer the lowest-friction entry path for maintenance services in India's fragmented metalworking sector. Target packaged supply formats for spot-application fabricators lacking working capital for bulk commitments. Pursue direct qualification with Tier-1 automotive steel buyers in Japan's Kansai corridor where procurement unbundling from captive equipment suppliers is accelerating. For Investors and Strategic Acquirers: The window for entry favors specialty chemical conglomerates with captive tribology expertise combining metalworking fluid chemistry with aluminum rolling metallurgy. Monitor ECHA substance evaluation timelines for chlorinated paraffin alternatives as the inflection indicator for formulation chemistry consolidation. Long-term viability hinges on water-soluble system capabilities aligning with China's dual carbon goals and India's PLI scheme compliance requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures rapeseed and sunflower supply chains ahead of EU Green Deal low-VOC mandates tightening across Italian and French fabricators. |
| Long-Term Supply Agreement | Locks in volume commitments with Yangtze River Delta state-owned mills coordinating centralized purchasing for MEE wastewater compliance. |
| Technical Service Embedding | Positions Quaker Houghton and Fuchs Petrolub teams at German automotive-grade steel facilities for formulation tuning and mill audit support. |
| Geographic Expansion | Captures first-mover positioning in Odisha and Jharkhand greenfield steel projects lacking established lubricant supply relationships. |
| Joint Venture | Combines synthetic base stock supply security from Shell with regional distribution networks serving Japan's Chukyo aluminum processing lines. |
Methodological Framework
Independent corroboration across plant managers at European steel mills, procurement leads at German automotive OEMs, technical R&D directors at specialty lubricant formulators, and distribution channel partners in East Asia underwrites the qualitative findings. Primary interviews with maintenance directors at high-speed tandem aluminum facilities were cross-referenced against customs and trade data, SEC filings from integrated chemical conglomerates, and European steel association production statistics. Bottom-up emulsion volume estimates and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical flat-rolled steel and aluminum production data frames the projection horizon. The analytical framework models chemistry type, metal substrate, delivery mode, and end-user procurement authority fragmentation throughout the forecast period. CAGRs were derived from rolling average growth trajectories applied to segment-level volume and value estimates. Industry-specific inputs include REACH authorization timeline assumptions and China's MEE enforcement intensity across provincial steel clusters.
Inputs from ECHA substance evaluation databases and METI standards documentation were available through the study window; gaps in real-time mill-level fluid consumption data introduce uncertainty bands around emulsion system conversion rate assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
EDM Oils/Fluids Market
Lubricants
Vietnam Lubricants Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Hydro Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market