
 Germany Automotive Lubricants Market | 2026-2036
Germany Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Lubricants Market Foresight
Aftermarket service revenue is narrowing toward high-margin synthetic formulations and extended-drain solutions. FUCHS Group anchors its position through captive supply of ester-based blends for German OEM specifications. LIQUI MOLY GmbH differentiates via additive chemistry leadership in the independent workshop channel. Shell plc leverages backward integration into Group III base oil production to control input costs.
Germany Automotive Lubricants are formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with synthetic grades typically achieving viscosity indices above 140 and thermal stability thresholds exceeding 200°C for turbocharged direct-injection engines. Their primary purpose is to extend component life and maintain fuel efficiency under variable load cycles. Engine oils command the largest volume pool, though bio-based formulations represent the fastest-growing technology tier as OEMs face Scope 3 emissions accounting. Passenger vehicles dominate application demand, while fleet operators in the commercial truck segment generate premium pricing through bulk procurement of long-drain synthetics.
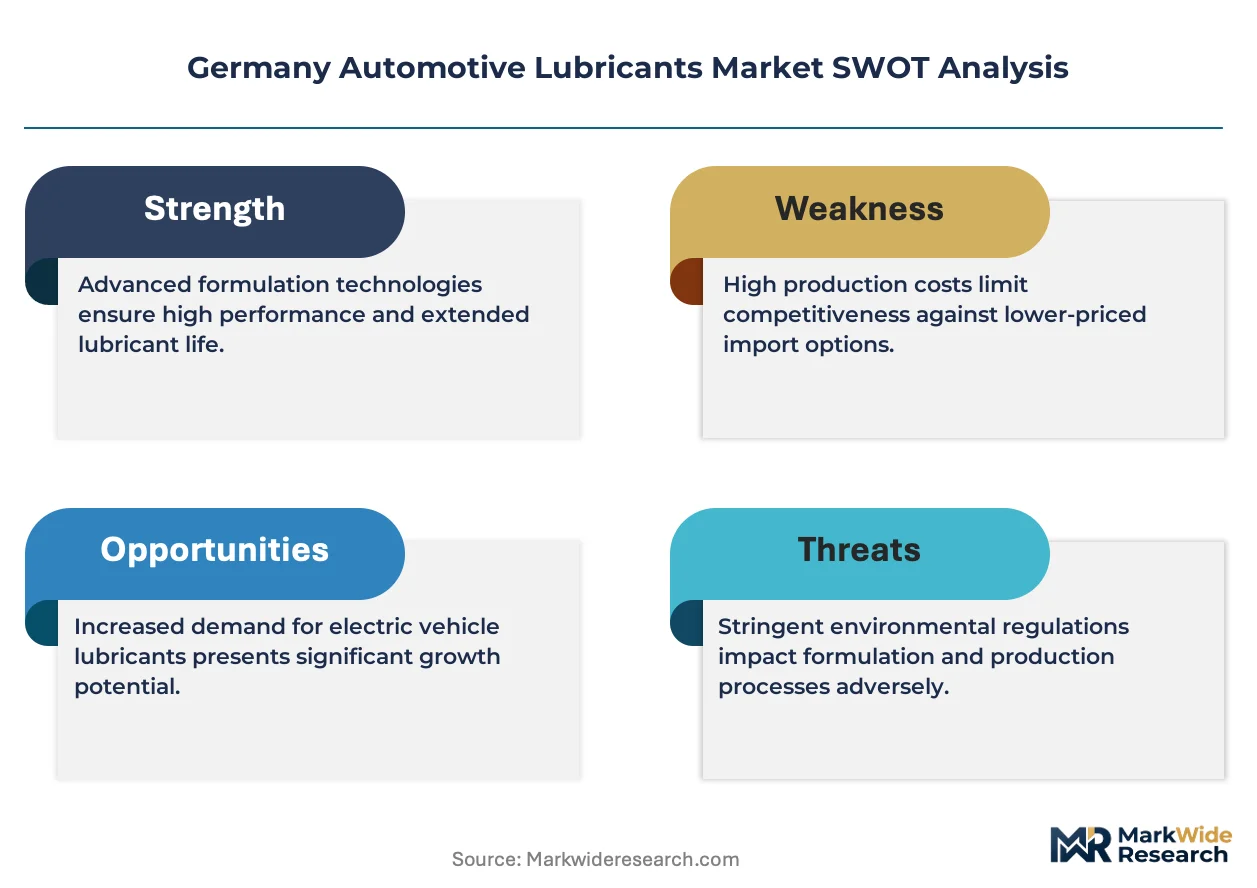
The EU Green Deal and REACH framework mandate biodegradability thresholds and restrict certain sulfur-phosphorus additive packages, compelling reformulation across the value chain. KBA enforces ACEA and OEM-specific oil sequences that determine warranty compliance and market access for lubricant suppliers. Stakeholders must monitor the interplay between OEM electrification timelines and residual internal combustion service demand to calibrate portfolio transition strategies.
Market Dynamics
EU Green Deal emission benchmarks are compressing drain intervals and accelerating synthetic lubricant penetration across German fleet operations, while KBA enforcement of ACEA sequences tightens formulation compliance requirements for warranty-linked service channels.
Growth Catalysts
- REACH biodegradability mandates:OEMs face Scope 3 emissions accounting pressure that elevates bio-based lubricant specifications in procurement tenders.
- Bavaria manufacturing density:Munich-Ingolstadt corridor clustering of OEM service networks creates concentrated demand pull for specification-compliant synthetics.
- Long-drain synthetic chemistry:Fleet operators in commercial logistics corridors adopt extended-interval formulations to minimize vehicle downtime.
Market Restraints
- Group III base oil supply concentration:Backward integration by major blenders limits independent access to high-viscosity-index feedstocks.
- REACH additive restrictions:Sulfur-phosphorus package limitations force costly reformulation of anti-wear chemistries.
- Battery electric drivetrain substitution:OEM electrification timelines threaten residual internal combustion engine service volumes.
Strategic Opportunities
- Independent workshop channel digitization:E-commerce platforms and direct-to-garage distribution bypass traditional wholesaler markups.
- Baden-Württemberg industrial belt:Stuttgart-region automotive suppliers represent underpenetrated mid-tier fleet accounts.
- EU Green Deal carbon border adjustments:Import lubricants face compliance cost disadvantages versus domestic bio-based production.
Industry Challenges
- ACEA sequence certification timelines:OEM-specific approval processes delay new formulation market entry by 18-24 months.
- Additive chemistry skill scarcity:Formulation chemists with ester-based blend expertise command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Lubricants Market |
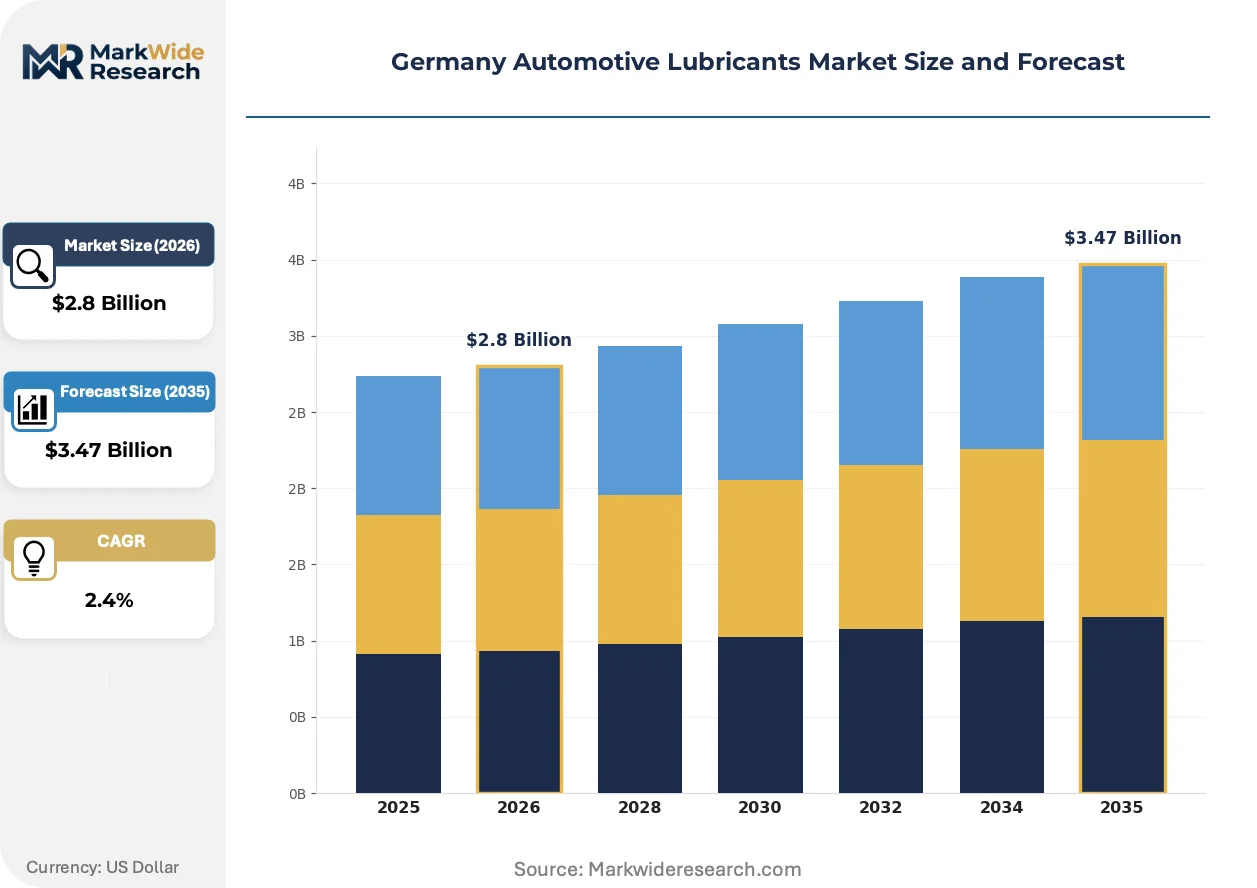
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Transmission Fluids, Greases, Brake Fluids, Coolants Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Agricultural Machinery, Construction Equipment Technology: Synthetic, Mineral, Semi-Synthetic, Bio-Based, Ester-Based End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Service Stations, Fleet Operators |
| Companies Covered | Shell plc, FUCHS Group, BP plc, ExxonMobil Corporation, TotalEnergies, LIQUI MOLY GmbH, Castrol, Henkel, Motul, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Lubricants Market Shifts & Advancements
Synthetic base oil technology is collapsing traditional mineral oil economics, while regulatory chemistry restrictions and fleet procurement centralization reshape competitive positioning across German distribution channels.
Polyalphaolefin (PAO) and ester-based synthetic blends deliver viscosity indices exceeding 140 and thermal stability above 200°C for turbocharged direct-injection engines. Fleet operators in long-haul logistics are mandating these formulations in bulk procurement contracts. The technology is collapsing price premiums that historically separated synthetic from mineral segments.
EU Green Deal emission benchmarks and REACH biodegradability thresholds restrict sulfur-phosphorus additive packages and mandate reformulation timelines. German blenders face compliance cost escalation for legacy chemistries. Passenger vehicle OEM service networks are accelerating bio-based lubricant qualification to meet Scope 3 reporting requirements.
Centralized fleet procurement departments are consolidating lubricant purchasing decisions away from decentralized garage-level ordering. Independent workshops face margin compression as large logistics operators negotiate direct supply agreements with major blenders. This pattern concentrates in North Rhine-Westphalia's Ruhr logistics corridor where dense fleet operations enable volume-based contracting.
Germany Automotive Lubricants Market Segmentation
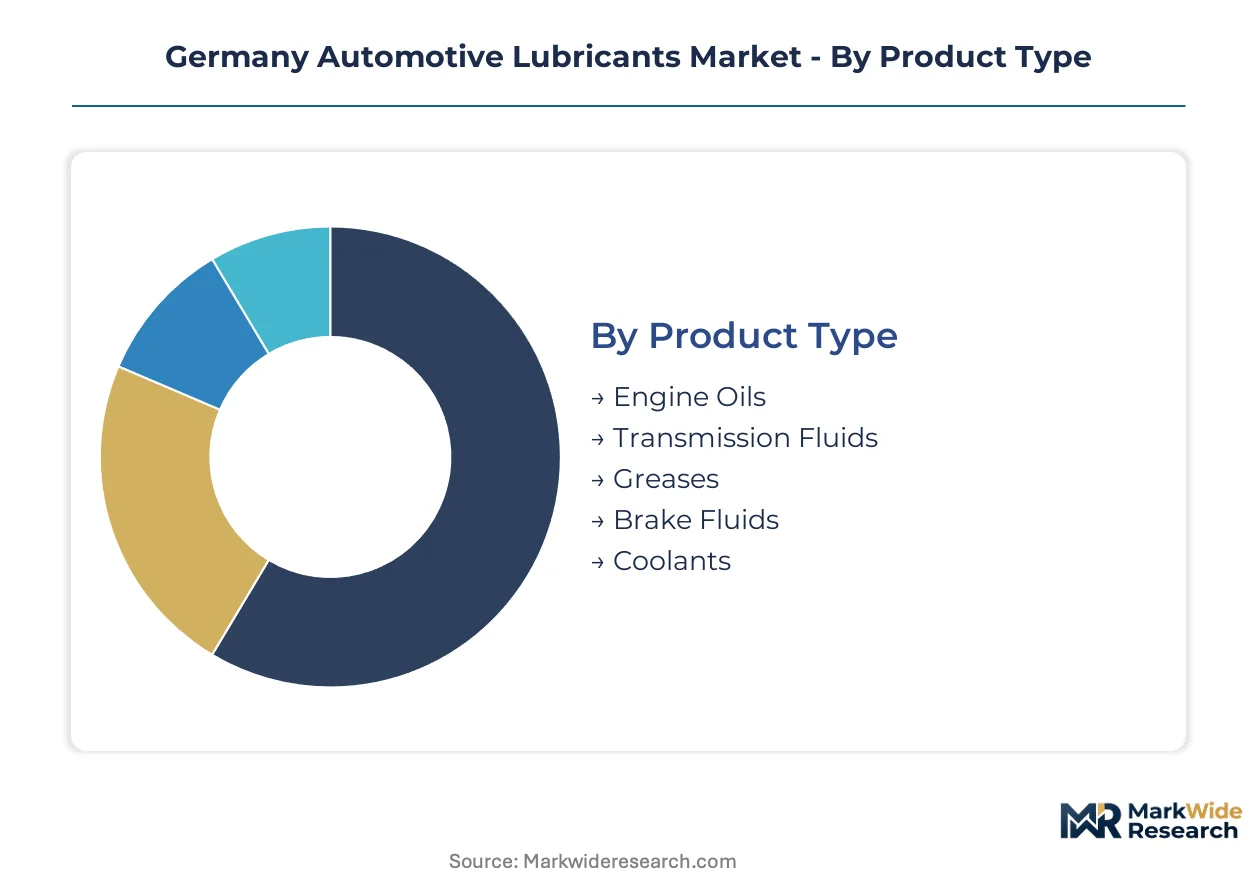
German lubricant procurement patterns diverge sharply across product categories and end-use channels. Specification compliance, drain-interval economics, and fleet centralization create distinct demand profiles that reward targeted portfolio architecture.
Product Type:
Mature formulations dominate volume throughput while emerging chemistries capture specification premiums in OEM channels.
- Engine Oils:PAO and Group III base stocks deliver viscosity indices above 140 for turbocharged direct-injection powertrains. Bavaria's OEM service networks concentrate demand for ACEA C5 and C6 sequences that satisfy KBA warranty requirements.
- Transmission Fluids:Dual-clutch and continuously variable specifications require precisely engineered friction modifiers. Stuttgart-region automotive suppliers generate concentrated pull for OEM-fill ATF contracts in passenger vehicle assembly.
- Greases:Lithium complex thickeners with high-drop-point characteristics serve chassis and wheel bearing applications across commercial logistics fleets.
- Brake Fluids:DOT 4 and DOT 5.1 glycol-ether formulations maintain hygroscopic performance thresholds for safety-critical hydraulic systems.
- Coolants:Ethylene glycol and organic acid technology blends protect aluminum engine blocks from cavitation erosion in extended-service intervals.
Engine oils handle the majority of throughput; bio-based coolants are climbing the fastest on share as Scope 3 accounting tightens.
Application:
Cost tier segmentation separates premium synthetic adopters from price-sensitive mineral oil users across vehicle categories.
- Passenger Vehicles:OEM service networks specify full synthetics for warranty compliance while independent workshops push semi-synthetic alternatives. Munich-Ingolstadt corridor density creates specification-compliant demand concentration.
- Commercial Trucks:Long-haul logistics operators mandate extended-drain synthetics to minimize downtime across North Rhine-Westphalia's Ruhr corridor. Fleet procurement centralization compresses margins for traditional distribution channels.
- Two-Wheelers:Scooter and motorcycle applications favor JASO MA2 certified formulations for wet clutch compatibility.
- Agricultural Machinery:Seasonal operating patterns and contamination exposure drive demand for robust anti-wear packages in universal tractor transmission oils.
- Construction Equipment:Severe-duty hydraulic and drivetrain applications require high-viscosity-index formulations with enhanced soot-handling capacity.
Commercial trucks generate the steepest pricing premiums; agricultural machinery represents the most price-elastic demand pool.
Technology:
Supply concentration in Group III base oil production shapes competitive access across technology tiers.
- Synthetic:PAO and hydrocracked Group III formulations achieve thermal stability above 200°C. Baden-Württemberg industrial belt fleet operators are mandating these chemistries in bulk procurement tenders.
- Mineral:Solvent-refined base stocks retain cost advantage in price-sensitive aftermarket channels despite narrowing performance gaps with semi-synthetics.
- Semi-Synthetic:Blended formulations balance upgrade economics for independent workshops serving aging vehicle parc.
- Bio-Based:Vegetable oil esters and synthetic esters satisfy REACH biodegradability mandates. EU Green Deal carbon border adjustments disadvantage imported alternatives against domestic production.
- Ester-Based:Diester and polyol ester chemistry delivers extreme-pressure performance for racing and high-performance applications.
Synthetics command the dominant revenue share; bio-based formulations are expanding most quickly as OEM qualification accelerates.
End User:
Customer type determines channel economics and formulation specification intensity across the value chain.
- OEMs:Factory-fill specifications require 18-24 month approval timelines through ACEA sequence certification and proprietary test protocols. KBA enforcement ties warranty compliance to approved lubricant sequences.
- Aftermarket Providers:Independent workshops face margin compression from fleet procurement centralization. E-commerce platforms and direct-to-garage distribution bypass traditional wholesaler markups.
- Vehicle Assemblers:Just-in-time supply contracts demand logistics integration with assembly plant operations.
- Service Stations:High-volume oil change operations prioritize inventory turnover and multi-vehicle specification coverage.
- Fleet Operators:Centralized procurement departments negotiate direct supply agreements with major blenders, collapsing traditional distribution margins.
Fleet operators are consolidating purchasing power fastest; aftermarket providers face the most severe margin pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German lubricant consumption patterns diverge sharply from neighboring markets, with specification intensity and fleet centralization driving higher synthetic penetration than in Southern or Eastern European counterparts.
Bavaria
Munich-Ingolstadt corridor clustering concentrates OEM service network demand for ACEA C5 and C6 specification-compliant synthetics. KBA enforcement ties warranty compliance to approved lubricant sequences, elevating formulation standards above national averages. Ingolstadt's Audi manufacturing complex and surrounding supplier parks generate captive factory-fill and aftermarket pull.
North Rhine-Westphalia
Ruhr logistics corridor fleet operators mandate extended-drain synthetic formulations to minimize commercial vehicle downtime. REACH biodegradability mandates from ECHA accelerate bio-based lubricant procurement in centralized fleet tenders. Cologne-Düsseldorf industrial density supports blending infrastructure and distribution hub positioning.
Baden-Württemberg
Stuttgart-region automotive suppliers represent underpenetrated mid-tier fleet accounts for synthetic transmission fluids and industrial lubricants. EU Green Deal carbon border adjustments disadvantage imported alternatives against domestic bio-based production. Porsche and Mercedes-Benz assembly operations in Zuffenhausen and Sindelfingen anchor specification-compliant demand.
Lower Saxony
Volkswagen Wolfsburg headquarters and surrounding component suppliers generate concentrated OEM-fill contract volumes. Hanover's commercial vehicle manufacturing cluster drives heavy-duty engine oil demand with severe-duty soot-handling requirements. Seasonal agricultural machinery operations in rural districts sustain price-elastic mineral oil consumption.
Hesse
Frankfurt-Rhine-Main logistics hub clustering supports fleet operator procurement centralization and direct blender agreements. Frankfurt Airport cargo operations and adjacent distribution centers generate commercial vehicle service demand. Independent workshop channels face margin compression from volume-based contracting.
Germany Automotive Lubricants Market Competitive Landscape
Capability concentration sits with integrated blenders controlling base oil supply; scale advantage sits with multinational oil majors with backward integration into Group III production. The vendor base stratifies across three tiers: captive OEM suppliers, independent specialists with additive chemistry leadership, and volume-driven mineral oil distributors. Strategic moves center on ester-based formulation certification timelines and direct-to-fleet distribution bypassing traditional wholesale channels.
Among Germany-based lubricant specialists, FUCHS Group anchors the integrated blender archetype through captive supply capabilities, while LIQUI MOLY GmbH occupies a position exemplifying additive chemistry differentiation in independent workshop channels. Shell plc represents the multinational major archetype with upstream control over base oil feedstocks. These three players illustrate how competitive positioning diverges between specification compliance depth and procurement scale efficiency.
| Leading Market Players |
|---|
| Shell plc |
| FUCHS Group |
| BP plc |
| ExxonMobil Corporation |
| TotalEnergies |
| LIQUI MOLY GmbH |
| Castrol |
| Henkel |
| Motul |
| Others |
Supply & Pricing Matrix
Group III base oil production concentration in the Netherlands and Belgium feeds directly into margin capture by integrated blenders commanding German OEM specification channels. REACH compliance costs for sulfur-phosphorus additive reformulation compress returns for independent formulators lacking backward integration into hydrocracked feedstocks.
Pricing Analysis
Long-term offtake contracts dominate procurement between major fleet operators and integrated blenders, while spot purchasing persists for independent workshops. Pricing stratifies across ACEA C6-certified premium synthetics, standard Group III formulations, and economy mineral grades. Cost compression in the independent channel is intensifying because centralized fleet procurement collapses traditional wholesaler markups. Commercial truck fleet operators exhibit lowest price sensitivity due to downtime cost calculus, whereas agricultural machinery owners remain most responsive to per-liter pricing.
Supply Chain Analysis
EU dual-use export controls on advanced hydrocracking catalysts limit technology transfer into non-integrated blending facilities. Base oil supply concentrates in the Netherlands, Belgium, and Germany itself, with PAO feedstocks drawing from specialized crackers in the US Gulf Coast. The value chain rests on Group III hydrocracked stocks, ester-based additive packages, and lithium complex thickener chemistries. Single-source vulnerability sits with hydrocracker output from Rotterdam-Antwerp hub. Distribution runs through captive OEM service networks, direct-to-fleet agreements, and independent workshop wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery electric drivetrain substitution threatens residual internal combustion service volumes, forcing incumbents to defend lubricant demand through extended-drain formulation innovation and fleet contract lock-in.
For Market Incumbents: Pre-empt electrification-driven volume erosion by accelerating ester-based long-drain certification timelines with German OEMs. Secure captive supply agreements for Group III base oil through backward integration or joint venture structures with Rotterdam-Antwerp hub operators. Channel control through direct-to-fleet digital platforms isolates margin pools from wholesale compression.
For New Entrants and Emerging Players: Baden-Württemberg's Stuttgart-region automotive supplier belt offers underpenetrated mid-tier fleet accounts for synthetic transmission fluid contracts. Bio-based lubricant qualification gaps among incumbent blenders create specification white-space for REACH-compliant vegetable oil ester formulations. A direct-to-garage e-commerce go-to-market bypasses entrenched wholesaler relationships in the independent workshop channel.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed additive chemistry specialists possessing ACEA sequence certification capabilities but lacking base oil integration. Long-term viability hinges on portfolio transition timing between residual combustion service and industrial lubricant diversification. The inflection signal to watch is OEM electrification timeline acceleration compressing factory-fill contract renewal rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Ester-Based Formulation Certification | ACEA C6 sequence approval with BMW and Mercedes-Benz secures warranty-linked service channels. |
| Backward Integration into Group III | Hydrocracker joint ventures in Rotterdam-Antwerp hub lock in feedstock cost control against spot volatility. |
| Direct-to-Fleet Digital Platform | E-commerce procurement portals bypass traditional wholesaler markups in North Rhine-Westphalia logistics corridors. |
| Bio-Based Lubricant Scale-Up | Domestic vegetable oil ester production satisfies REACH biodegradability mandates ahead of carbon border adjustments. |
| Independent Workshop Channel Partnership | Technical training programs with LIQUI MOLY GmbH anchor additive chemistry differentiation in aftermarket service. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of KBA enforcement records, ACEA oil sequence databases, and ECHA REACH registration dossiers. Primary interviews engaged lubricant formulation chemists, OEM procurement directors at Audi and Mercedes-Benz, fleet maintenance managers across North Rhine-Westphalia logistics operators, and independent workshop owners in Bavaria. Secondary sources incorporated customs trade data on base oil imports, SEC filings of integrated oil majors, and production statistics from the German Mineral Oil Industry Association. Bottom-up volume modeling triangulated against top-down market sizing from macroeconomic automotive production indicators.
Forecast inputs span vehicle parc composition, OEM electrification commitment timelines, and REACH regulatory phase-in schedules across the projection horizon. Segmentation dimensions modeled include base oil technology tier, ACEA specification sequence, end-use application, and regional production cluster density. CAGRs derive from regression analysis against historical lubricant consumption intensity per vehicle kilometer and scenario-weighted electrification penetration curves. Industry-specific inputs incorporate KBA registration data for turbocharged direct-injection engine share and fleet operator procurement centralization indices.
Practitioners should monitor EU Green Deal emission benchmark tightening and battery electric vehicle sales penetration for early signals of forecast revision. Forecasts reflect assumptions on residual internal combustion engine service interval extension rates and bio-based lubricant OEM qualification velocity. Material shifts in German OEM electrification timelines or REACH additive restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
North America Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market