
 Mexico Automotive Engine Oils Market | 2026-2036
Mexico Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Engine Oils Market Foresight
Qualified lubricant blending technicians is collapsing across Mexico's Gulf Coast refining corridor, forcing Shell and Chevron to accelerate in-house certification programs at their Veracruz and Tampico facilities. ExxonMobil leverages its captive base oil supply from Baytown to sustain margin stability against import-dependent competitors. Roshfrans anchors its position through deep distribution in Mexico City's independent aftermarket, where it controls shelf placement across 2,000-plus automotive shops.
Mexico automotive engine oils are formulated lubricants comprising base oils plus detergent, dispersant, anti-wear, and viscosity-index improver additive packages, engineered to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines operating across temperature extremes from Sonora deserts to Toluca highlands. Synthetic formulations lead value generation due to OEM fill specifications from Nissan, Volkswagen, and BMW plants in Puebla and San Luis Potosí, while 5W-30 viscosity grade dominates volume as the default recommendation for modern passenger vehicles with tighter tolerances. Service stations capture the largest transaction volume through fleet card programs, though online retail is gaining fastest among DIY consumers in Monterrey and Guadalajara metropolitan zones.
SEMARNAT enforces NOM-086 on lubricant labeling and waste oil collection, compelling blenders to reformulate for biodegradability and fund reverse-logistics networks. PROFECO monitors consumer-facing claims through its verification laboratory in Mexico City, while ASEA regulates energy sector procurement standards that spill over into fleet lubricant specifications. Stakeholders must track how impending alignment between Mexican NOMs and API SP/ILSAC GF-6 standards will force reformulation investments and reshape competitive access for non-integrated importers.
Market Dynamics
Fleet operators across Mexico's commercial trucking corridors are accelerating synthetic lubricant adoption to extend drain intervals and compress maintenance downtime, fundamentally restructuring procurement volumes and margin pools across the value chain.
Growth Catalysts
- PROSEC program incentives:Tariff relief on imported base oils and additives reduces formulation costs for blenders serving OEM assembly plants in Puebla and San Luis Potosí.
- Synthetic formulation mandates:Nissan, Volkswagen, and BMW manufacturing specifications require full-synthetic fills for warranty compliance, pulling demand away from mineral alternatives.
- Fleet card consolidation:Commercial transport operators centralize lubricant purchasing through service station networks, aggregating transaction volume and securing preferential pricing tiers.
Market Restraints
- Base oil import dependency:Mexico lacks domestic Group II/III base oil production, exposing blenders to freight cost volatility from US Gulf Coast supply points.
- NOM-086-SEMARNAT-2011 compliance costs:Mandatory biodegradability reformulation and waste oil reverse-logistics funding compress margins for non-integrated importers.
- Qualified technician scarcity:Gulf Coast refining corridor faces collapsing availability of certified lubricant blending technicians, forcing accelerated in-house training investments.
Strategic Opportunities
- Bajío manufacturing corridor expansion:Guanajuato and Querétaro automotive clusters anchor bulk procurement volumes for suppliers with localized blending capacity.
- Online retail channel emergence:DIY consumers in Monterrey and Guadalajara metropolitan zones are migrating from traditional automotive shops to e-commerce platforms for convenience and price transparency.
- API SP/ILSAC GF-6 alignment:Impending NOM harmonization with North American performance standards creates first-mover advantage for blenders with existing certification infrastructure.
Industry Challenges
- Additive package sourcing complexity:Formulators must balance detergent, dispersant, anti-wear, and viscosity-index improver specifications across divergent OEM requirements without inventory duplication.
- Multi-temperature formulation engineering:Products must perform across Sonora desert heat and Toluca highland cold without separate SKUs, complicating R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Engine Oils Market |
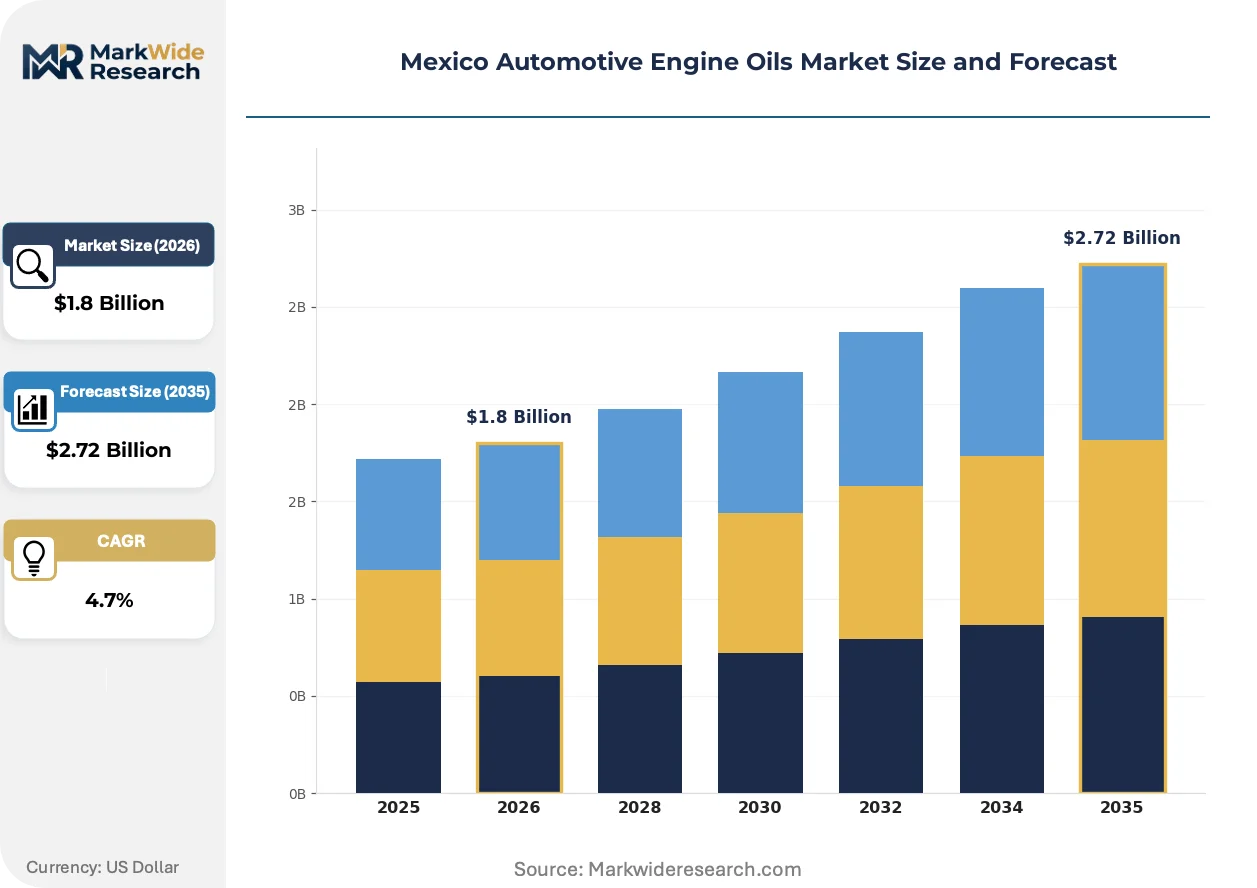
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, High-Mileage, Diesel Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 End User: Passenger Vehicles, Commercial Trucks, SUVs, Motorcycles Distribution Channel: Online Retail, Automotive Shops, Supermarkets, Service Stations |
| Companies Covered | Shell, ExxonMobil, Chevron, BP (Castrol), TotalEnergies, Valvoline, Bardahl, Roshfrans, Fuchs Petrolub SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Engine Oils Market Shifts & Advancements
Formulation chemistry and distribution architecture are undergoing parallel transformation as OEM specifications tighten and buyer access patterns fragment across physical and digital channels.
Low-viscosity synthetic blends engineered around 5W-30 specifications are displacing conventional 10W-40 and 15W-40 grades in passenger vehicle service bays. Modern engine architectures from Volkswagen and BMW assembly plants in Puebla demand tighter tolerances and reduced cold-start friction. The shift is compressing demand for higher-viscosity mineral stocks and redirecting blender capacity toward Group III base oil procurement.
SEMARNAT enforcement of NOM-086-SEMARNAT-2011 on lubricant labeling and waste oil collection is compelling reformulation investments across the importer and blender base. The regulation mandates biodegradability thresholds and funded reverse-logistics networks for used oil recovery. Smaller non-integrated blenders without captive collection infrastructure face disproportionate compliance cost burdens relative to integrated majors with existing waste management systems.
Fleet procurement patterns are fragmenting from single-source annual contracts toward multi-vendor spot purchasing through digital platforms. Large commercial transport operators in the Bajío corridor now benchmark lubricant pricing across service station networks and direct distributor channels simultaneously. This behavior is most pronounced among refrigerated freight operators running tight margin structures, where fluid cost per kilometer has become a tracked operational metric.
Mexico Automotive Engine Oils Market Segmentation
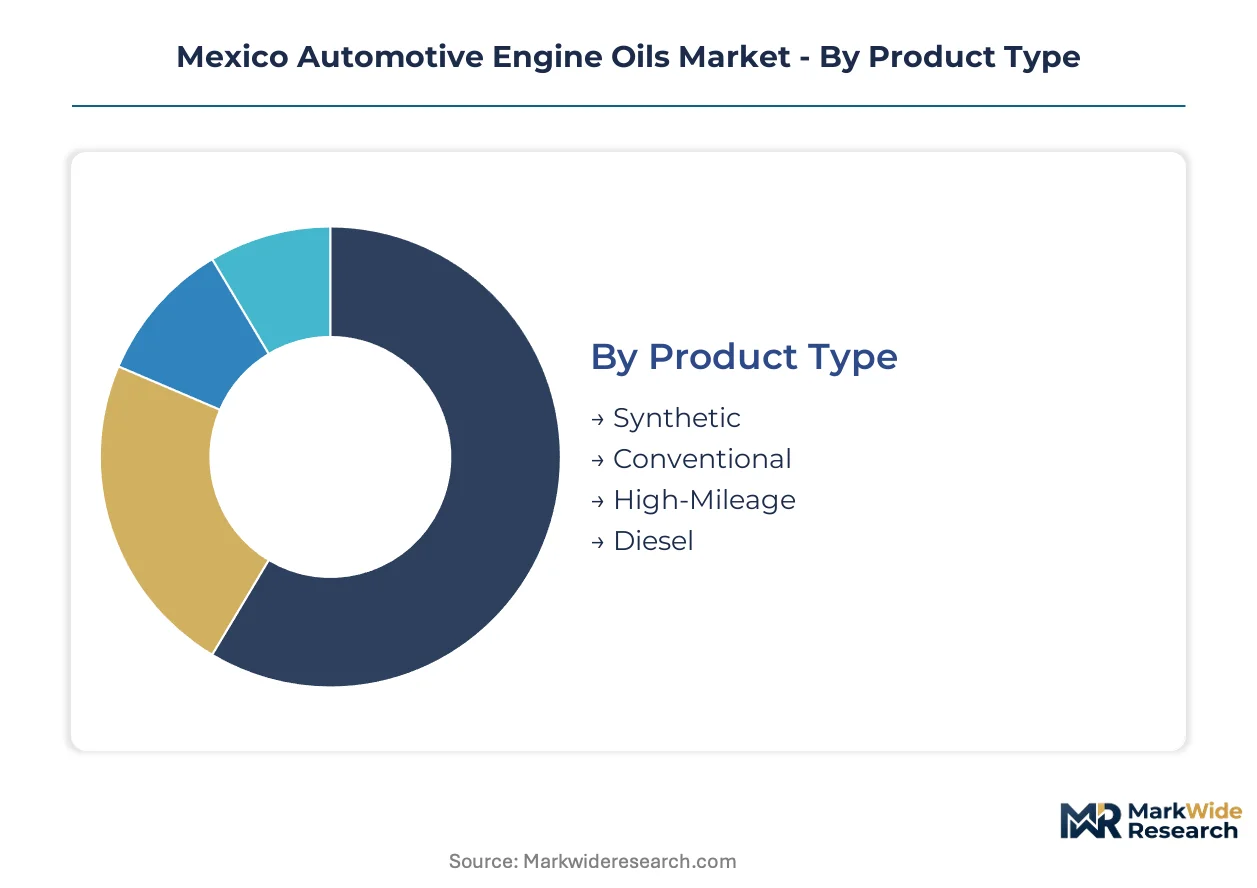
Segmentation in Mexico's automotive engine oils market reveals how formulation chemistry, procurement scale, and channel access fragment competitive positioning across distinct customer workflows. Each dimension carries unique margin structures and compliance burdens that reshape supplier resource allocation.
Product Type:
Synthetic formulations flow through OEM fill programs and fleet direct accounts, while conventional and high-mileage products concentrate in independent aftermarket channels where price sensitivity dominates.
- Synthetic:Full-synthetic formulations using Group III base oils meet Nissan, Volkswagen, and BMW assembly plant specifications for warranty compliance. Demand clusters in Puebla and San Luis Potosí manufacturing zones where OEM technical service bulletins mandate drain intervals exceeding 15,000 kilometers.
- Conventional:Mineral-based stocks serve older vehicle parc in Mexico City's independent service sector where cost-per-change remains the primary purchase criterion. Volumes concentrate in high-turnover automotive shops across Iztapalapa and Gustavo A. Madero districts.
- High-Mileage:Seal conditioners and enhanced detergents target vehicles exceeding 120,000 kilometers, prevalent in secondary markets where vehicle retention cycles stretch past twelve years.
- Diesel:Heavy-duty formulations with elevated total base number combat soot loading in commercial freight corridors spanning Querétaro to Nuevo Laredo.
Synthetic dominates value generation. Conventional anchors volume throughput in price-sensitive channels.
Viscosity Grade:
Grade selection tracks engine architecture evolution, with lower viscosity specifications correlating to newer vehicle cohorts and tighter manufacturing tolerances.
- 5W-30:The default service recommendation for modern passenger vehicles across Bajío assembly plant service networks. Volkswagen and BMW technical bulletins specify this grade for turbocharged direct-injection architectures, concentrating demand in Guanajuato and Querétaro dealer channels.
- 0W-20:Ultra-low viscosity formulations reduce cold-start friction in hybrid and downsized gasoline engines, gaining share fastest in Monterrey metropolitan zone where newer vehicle penetration exceeds national averages.
- 10W-40:Higher viscosity mineral blends serve aging fleet vehicles and commercial light trucks operating in Sonora desert heat without thermal breakdown.
- 15W-50:Racing and severe-service applications in high-performance segments, limited to specialty distributors and motorsport supply chains.
5W-30 commands the largest installed base. 0W-20 is climbing the fastest as OEM fill specifications tighten.
End User:
User categories separate procurement scale, with commercial operators centralizing through fleet programs and individual owners fragmenting across retail channels.
- Commercial Trucks:Fleet operators running refrigerated and dry freight across Mexico's Pacific and Gulf corridors aggregate lubricant purchasing through service station card programs, negotiating volume tiers based on kilometer commitments.
- Passenger Vehicles:Individual owners in Guadalajara and Monterrey metropolitan zones drive DIY segment growth through online price comparison, migrating from traditional automotive shops to e-commerce platforms.
- SUVs:Higher displacement engines and towing duty cycles pull demand toward synthetic high-viscosity grades in suburban Monterrey and Tijuana markets.
- Motorcycles:Small-displacement two-wheeler parc in Mexico City and Puebla concentrates 10W-40 conventional demand through independent mechanics serving delivery and commuter segments.
Commercial Trucks centralize procurement scale. Passenger Vehicles is where channel fragmentation accelerates.
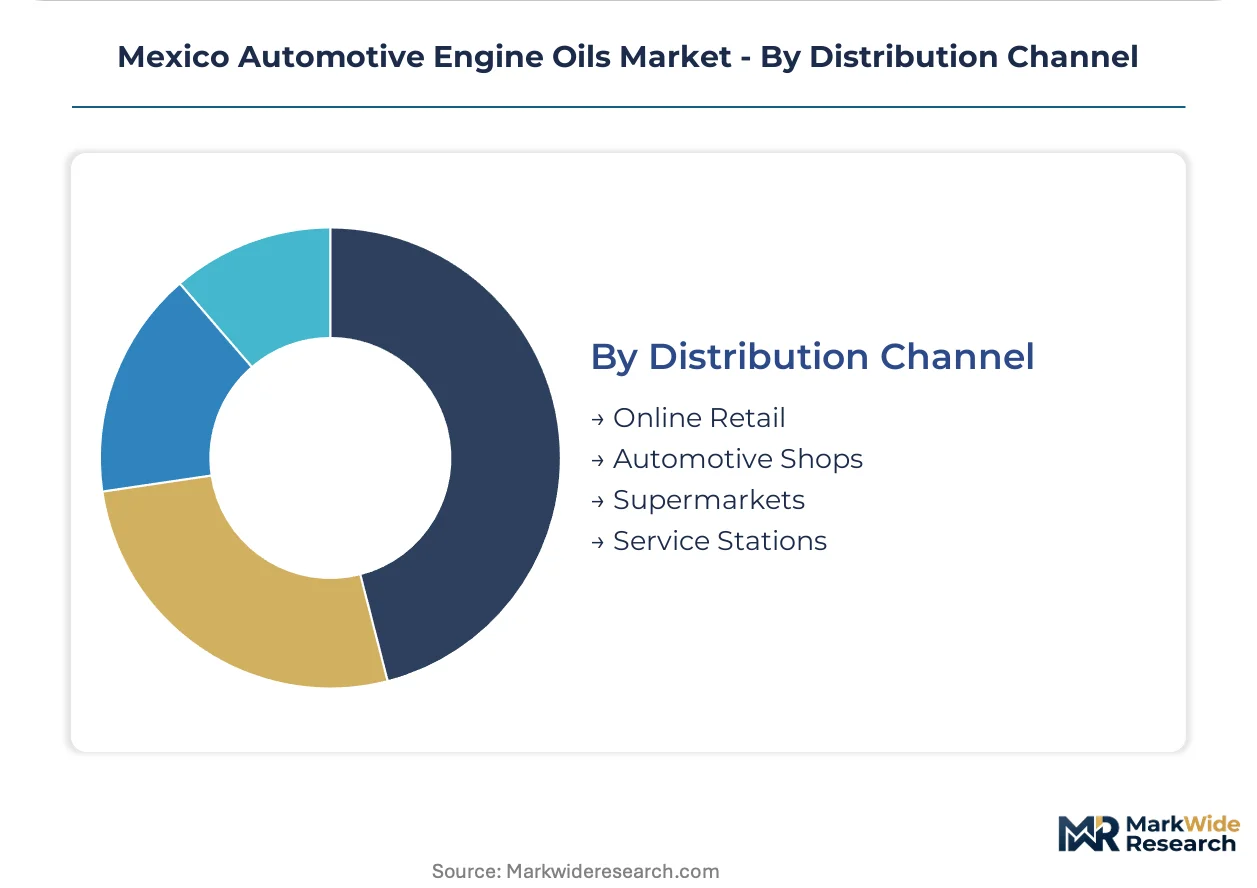
Distribution Channel:
Channel selection determines margin capture, with direct fleet accounts yielding lowest per-liter revenue and highest retention, while online retail sacrifices service attachment for price transparency.
- Service Stations:Pemex and private fuel networks capture fleet card volume through integrated lubricant-fuel purchasing, anchoring bulk transaction flow across federal highway corridors.
- Automotive Shops:Independent mechanics in Mexico City's 2,000-plus service points control installation labor attachment, defending conventional product share through relationship-based repeat business.
- Online Retail:Amazon Mexico and Mercado Libre gain DIY consumer share in Monterrey and Guadalajara through price comparison tools and subscription delivery programs.
- Supermarkets:Walmart and Soriana hypermarkets serve emergency top-off purchases and rural markets lacking dedicated automotive distribution.
Service Stations dominate fleet volume. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Bajío automotive corridor where OEM assembly plants anchor bulk procurement, while Gulf Coast blending facilities absorb freight cost volatility from US base oil imports.
Bajío Region
Guanajuato and Querétaro manufacturing clusters drive synthetic lubricant demand through Nissan, Volkswagen, and BMW assembly operations. PROSEC tariff relief on imported base oils reduces formulation costs for blenders serving these OEM technical specifications. Tier-1 suppliers in Silao and Apaseo el Grande anchor bulk procurement volumes for warranty-compliant fill programs.
Mexico City Metro
Independent aftermarket channels concentrate in Iztapalapa and Gustavo A. Madero districts where conventional products dominate cost-sensitive service bays. PROFECO verification laboratory monitors consumer-facing claims through standardized testing protocols. Roshfrans controls shelf placement across 2,000-plus automotive shops through deep distribution relationships.
Nuevo León
Monterrey metropolitan zone leads DIY segment migration to e-commerce platforms through price comparison tools and subscription delivery programs. Fleet operators running refrigerated freight negotiate volume tiers through service station card programs. Newer vehicle penetration exceeds national averages, accelerating 0W-20 ultra-low viscosity adoption.
Veracruz-Tampico Corridor
Gulf Coast refining facilities face collapsing availability of certified lubricant blending technicians. Shell and Chevron accelerate in-house certification programs to sustain operational continuity. Base oil import dependency from US Gulf Coast supply points exposes blenders to freight cost volatility and currency fluctuation risks.
Jalisco
Guadalajara metropolitan zone mirrors Monterrey's online retail channel emergence among DIY consumers seeking convenience and price transparency. Independent mechanics defend conventional product share through relationship-based repeat business. Secondary vehicle markets with retention cycles exceeding twelve years sustain high-mileage formulation demand.
Mexico Automotive Engine Oils Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexico's automotive engine oils market. Vertically integrated majors with captive base oil supply sustain margin stability against import-dependent blenders facing freight cost volatility. The competitive structure separates into three strategic archetypes: integrated global majors with upstream refining control, regional formulators with deep distribution networks, and specialty importers serving niche OEM specifications. Dominant competitive moves include backward integration into base oil supply chains and geographic expansion through localized blending capacity in the Bajío corridor.
Among integrated global majors, Shell and ExxonMobil exemplify archetypes with upstream control over supply chains. Shell anchors Gulf Coast operational presence through accelerated technician certification programs at Veracruz facilities. ExxonMobil leverages Baytown captive base oil supply to sustain margin stability. Roshfrans occupies a distinct position as a regional formulator with deep aftermarket distribution, controlling shelf placement across Mexico City's independent service network.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil |
| Chevron |
| BP (Castrol) |
| TotalEnergies |
| Valvoline |
| Bardahl |
| Roshfrans |
| Fuchs Petrolub SE |
| Others |
Supply & Pricing Matrix
Group III base oil substitution for Group I mineral stocks redraws procurement geography toward US Gulf Coast supply points while compressing formulation economics for import-dependent blenders against integrated competitors with captive supply. This input transition simultaneously elevates freight cost exposure and concentrates pricing power among majors with backward integration into base oil production.
Pricing Analysis
The customization-premium spread between OEM-configured synthetic formulations and standard aftermarket mineral products spans three performance tiers anchored by certification grade and volume commitment. Price differentiation tracks API SP/ILSAC GF-6 compliance status and PROSEC tariff relief eligibility, with fleet card programs extracting steepest discounts through kilometer-based volume guarantees. Cost compression in conventional mineral tiers intensifies as independent service shops consolidate purchasing through distributor cooperatives. DIY consumers in Monterrey and Guadalajara exhibit highest price transparency sensitivity, while OEM fill programs demonstrate lowest elasticity due to warranty compliance requirements.
Supply Chain Analysis
Inbound logistics costs from US Gulf Coast ports to Veracruz and Tampico blending facilities fluctuate with container availability and Houston Ship Channel congestion, exposing non-integrated importers to working capital pressure. Mexico's lubricant supply chain draws from US base oil production, Asian additive package manufacturing, and domestic blending capacity concentrated in the Gulf Coast corridor. Single-source vulnerability pervades Group II/III base oil procurement, as no domestic production exists to offset import dependency. Distribution runs through service station networks for fleet volume, automotive shops for installation-attached sales, and e-commerce platforms for DIY convenience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation through card program centralization has shifted procurement leverage toward volume-aggregated buyers, fragmenting supplier pricing power across transaction tiers.
For Market Incumbents: Fortify Bajío corridor positioning through localized blending capacity expansion in Guanajuato and Querétaro to compress delivery costs for OEM assembly plants. Deepen API SP/ILSAC GF-6 certification infrastructure ahead of NOM harmonization to raise compliance barriers against non-integrated importers. Secure captive base oil supply agreements or backward integration into Group III production to insulate margins from freight volatility threatening import-dependent competitors. For New Entrants and Emerging Players: Digital platform service layers where incumbent distributors under-serve DIY price comparison behavior present the most penetrable entry path. Target Guadalajara and Monterrey metropolitan zones with subscription delivery programs and transparent pricing tools that bypass traditional automotive shop relationships. Anchor initial positioning through high-mileage formulations for secondary vehicle markets in Jalisco, where twelve-year retention cycles sustain underserved demand. For Investors and Strategic Acquirers: The market sits at a regulatory-alignment phase that favors blenders with existing certification infrastructure and established reverse-logistics networks. Long-term viability across the projection horizon hinges on compliance cost absorption capacity rather than pure scale. Acquisition targets should display integrated waste oil collection systems and PROSEC program utilization. Watch NOM-086 enforcement intensity as the inflection signal for margin compression among non-compliant importers.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Blending Capacity Expansion | Reduces freight exposure from US Gulf Coast supply points for Bajío OEM clusters. |
| API SP/ILSAC GF-6 Certification Investment | Positions blenders for impending NOM harmonization ahead of compliance deadlines. |
| Waste Oil Reverse-Logistics Network Buildout | Satisfies SEMARNAT NOM-086 mandates while raising barriers for non-integrated competitors. |
| Fleet Card Program Partnership | Captures centralized procurement volume from refrigerated freight operators in Nuevo León. |
| E-Commerce Platform Integration | Targets DIY migration in Monterrey and Guadalajara through price transparency tools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lubricant blending technicians, OEM procurement managers, fleet operations directors, and aftermarket distributors; and secondary validation through customs trade records, SEMARNAT regulatory filings, PROSEC tariff documentation, and vehicle production databases. Bottom-up triangulation across channel volume estimates and top-down reconciliation against formulation consumption patterns anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning synthetic versus conventional formulation chemistry, viscosity grade specifications, end-user procurement scale, and distribution channel access patterns. CAGRs were derived from trend extrapolation of OEM fill specifications, fleet drain interval extension rates, and channel migration velocities. Forecast inputs incorporated PROSEC program utilization rates and NOM-086 compliance cost trajectories.
Underlying assumptions cover stable US-Mexico trade lane capacity, SEMARNAT enforcement continuity, and OEM assembly plant operational schedules, with deviation risk concentrated in base oil price volatility and currency fluctuation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Metalworking Fluids Market
Lubricants
Anti-Static Oil Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Thailand Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
High Performance Lubricants Market
Lubricants
Kenya Lubricants Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market