
 Soy Flour Market | 2026-2036
Soy Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Flour Market Analysis
Agronomic expertise in soybean breeding and processing is reorganizing competitive dynamics across the value chain. Cargill leverages its origination networks across the U.S. Midwest to secure premium soybean supplies for flour milling. Archer Daniels Midland Company sustains crushing margins through co-product optimization at its Decatur, Illinois complex. CHS Inc. anchors farmer cooperative procurement, giving it disciplined cost control over input flows.
Soy flour consists of finely ground soybean meal or whole roasted soybeans, typically containing 40-50% protein by weight and produced through extrusion or conventional milling processes; it functions primarily as a protein fortifier, emulsifier, and moisture binder in formulated foods. De-fatted soy flour leads volume due to its extended shelf stability and standardized protein content for industrial baking applications. Meat alternatives represent the fastest-growing application segment as formulators seek clean-label binders with complete amino acid profiles. Whole soy flour occupies a premium niche in specialty retail channels where minimally processed positioning commands price separation.
FDA protein quality labeling rules and USDA organic certification standards shape product development pathways and channel eligibility for soy flour suppliers. The EPA's biofuel mandates indirectly tighten soybean oil competition, redirecting crush economics toward flour and meal outputs. Stakeholders must monitor how evolving FDA guidance on plant-based protein health claims reshapes formulation R&D priorities and customer qualification requirements.
Market Dynamics
Protein fortification mandates in institutional food procurement are compressing formulation cycles for soy flour suppliers. USDA school nutrition standards and FDA protein quality labeling rules now require documented amino acid completeness, forcing millers to upgrade analytical capabilities and certificate management systems ahead of contract renewals.
Growth Catalysts
- USDA Organic Certification:Federal procurement preference for certified ingredients is opening institutional channels previously closed to conventional soy flour. School districts and hospital systems now specify organic protein fortifiers in bid documents.
- Extrusion Texturization:Twin-screw extrusion advances enable meat alternative producers to achieve fibrous mouthfeel without methylcellulose binders. Soy flour with modified particle size distribution commands formulation priority.
- Brazil:Crushing capacity expansion in Mato Grosso and Paraná is securing origin-sourced flour supply for export markets. Port infrastructure investments at Santos reduce transit variability to European and Asian buyers.
Market Restraints
- Soybean Price Volatility:Weather-driven yield uncertainty in Argentina and U.S. Midwest production zones transmits directly to flour input costs. Crush margin compression limits processor flexibility on long-term contracting.
- Single-Origin Concentration:Brazilian port dominance creates chokepoint exposure for global supply security. Drought or labor disruption at Santos generates cascading delivery failures.
- Protein Digestibility Limitation:Trypsin inhibitor content in raw flour requires heat treatment that degrades lysine availability. Formulators must balance functional performance against amino acid score requirements.
Strategic Opportunities
- Southeast Asia:Underdeveloped meat alternative manufacturing in Indonesia and Vietnam offers first-mover positioning for fortifier suppliers. Local bakery and noodle sectors seek cost-efficient protein enrichment.
- Precision Fermentation Convergence:Blending soy flour with fermentation-derived proteins enables hybrid products that meet clean-label expectations while managing unit economics. Co-development partnerships with biotech platforms are emerging.
- E-Commerce Direct-to-Manufacturer:Bulk ingredient platforms bypass traditional distributor markups for mid-sized food manufacturers. Digital procurement reduces working capital requirements for regional processors.
Industry Challenges
- Food Safety Certification Timeline:BRCGS and FSSC 22000 audit scheduling delays extend customer qualification periods by four to six months. Smaller millers lack dedicated compliance staff to parallel-track multiple certifications.
- Legacy ERP Integration:Lot traceability requirements for FDA FSMA compliance strain paper-based inventory systems. Capital expenditure for serialized tracking infrastructure competes with capacity expansion budgets.
- Specialized Milling Expertise Scarcity:Protein content consistency demands operators trained in near-infrared calibration and tempering protocols. Retirement waves in Midwest milling regions constrain technical talent pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Flour Market |
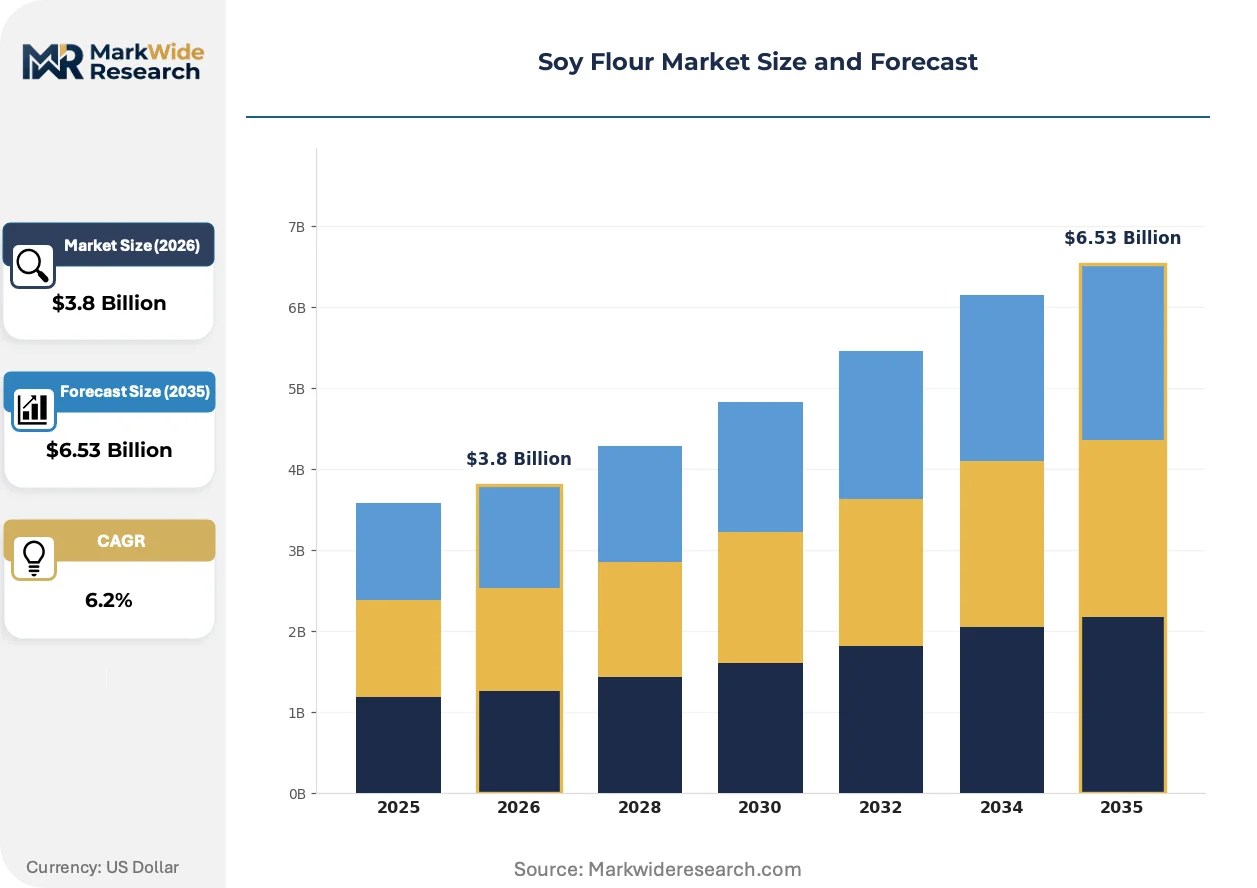
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Soy Flour, De-Fatted Soy Flour, Whole Soy Flour, Instant Soy Flour Application: Baking, Dairy Alternatives, Meat Alternatives, Infant Nutrition End User: Food Manufacturers, Dietary Supplement Makers, Retail Consumers, Restaurants Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Cargill, Archer Daniels Midland Company, CHS Inc., Wilmar International, Bunge Limited, DuPont, The Scoular Company, Foodchem International Corporation, Bob’s Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Flour Market Emerging Trajectories
Clean-label binder substitution is accelerating formulation redevelopment across processed food categories. Manufacturers are retiring modified starches and synthetic emulsifiers in favor of plant-derived alternatives with recognized ingredient names.
Extruded soy protein concentrate is decomposing the methylcellulose monopoly in meat alternative binding applications. Plant-based burger and sausage formulators at mid-sized co-manufacturers are adopting enzyme-modified soy flour to achieve sliceable texture without E-number ingredients. The technology is decomposing premium pricing for specialty hydrocolloids by delivering equivalent water-binding at commodity input costs.
EU Green Deal Farm-to-Fork targets are tightening pesticide residue thresholds for imported protein ingredients. Maximum residue limits for glyphosate and neonicotinoids now exclude conventional Brazilian soy from certain European organic processing channels. Northern European buyers are demanding third-party verified deforestation-free documentation alongside certificate of analysis packages.
Food service distributors are unbundling ingredient sourcing from prepared product procurement. Regional restaurant chains now contract directly with soy flour millers for custom protein specification, bypassing broadline distributor private-label programs. The disintermediation is most visible in U.S. fast-casual segments where culinary teams formulate proprietary plant-based menu items requiring traceable single-origin fortification.
Soy Flour Market Segmentation
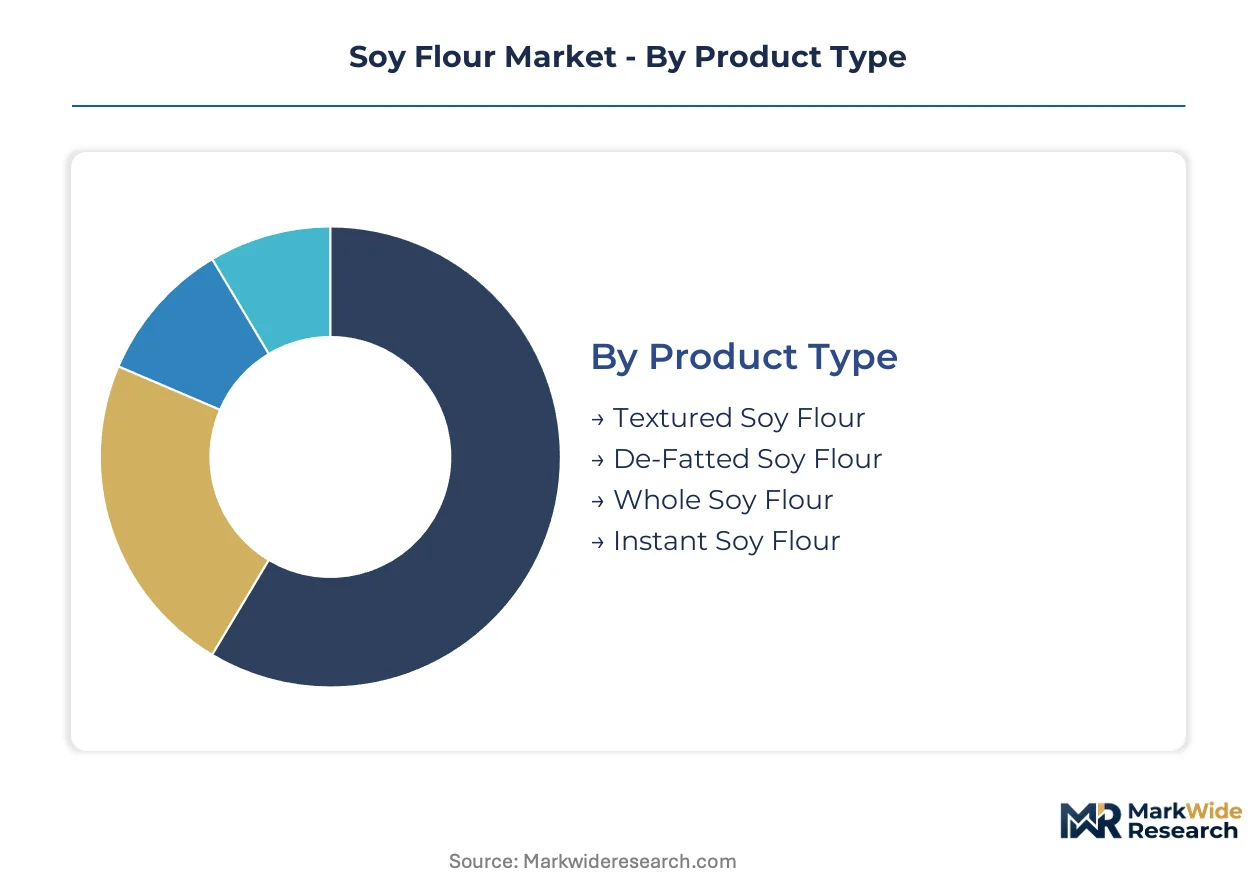
Soy flour segmentation reveals how protein fortification requirements reshape procurement patterns across institutional and retail channels. Product specifications diverge sharply between industrial buyers seeking standardized amino acid profiles and specialty channels prioritizing minimally processed positioning.
Product Type:
Channel mix varies dramatically by flour processing intensity, with de-fatted variants dominating institutional procurement while whole flour concentrates in premium retail.
- De-Fatted Soy Flour:Oil-extracted meal ground to 40-50% protein concentration delivers extended shelf stability for industrial baking and meat alternative manufacturing. USDA school nutrition contracts and FDA protein quality mandates concentrate demand among North American institutional foodservice distributors.
- Whole Soy Flour:Minimally processed roasted soybean preserves full lipid content and fiber matrix for clean-label positioning. Specialty retail channels in Germany and France command price separation for organic-certified whole flour with deforestation-free documentation.
- Textured Soy Flour:Extruded variants create fibrous structures for meat analog applications.
- Instant Soy Flour:Pre-gelatinized formulations dissolve rapidly for beverage fortification.
By volume, de-fatted soy flour leads. By growth pace, whole soy flour is expanding most quickly.
Application:
Cost tier stratification separates commodity baking applications from premium meat alternative formulations requiring customized particle engineering.
- Meat Alternatives:Twin-screw extrusion enables fibrous texture without methylcellulose binders. Clean-label formulators at mid-sized co-manufacturers specify enzyme-modified soy flour to achieve sliceable consistency.
- Baking:Protein fortification in pan breads and tortillas leverages de-fatted flour for moisture retention and crumb structure. Brazilian millers supply standardized protein specifications to Latin American industrial bakeries.
- Dairy Alternatives:Emulsification properties stabilize plant-based yogurt and cheese analogs.
- Infant Nutrition:Hypoallergenic positioning requires extensive trypsin inhibitor reduction protocols.
Meat alternatives command premium formulation spending. Baking applications anchor baseline volume throughput.
End User:
Customer type determines specification rigor, with food manufacturers demanding certificate-of-analysis packages unavailable to retail consumers.
- Food Manufacturers:Industrial buyers integrate soy flour into formulated products requiring documented amino acid completeness for FDA compliance. BRCGS and FSSC 22000 certifications filter supplier qualification.
- Dietary Supplement Makers:Protein powder blenders source instant soy flour for beverage applications with specific dispersibility requirements.
- Retail Consumers:Home bakers purchase whole soy flour through specialty channels for gluten-free recipes.
- Restaurants:Fast-casual chains contract directly with millers for proprietary plant-based menu development.
Food manufacturers generate highest contract values. Restaurants are gaining procurement sophistication fastest.
Distribution Channel:
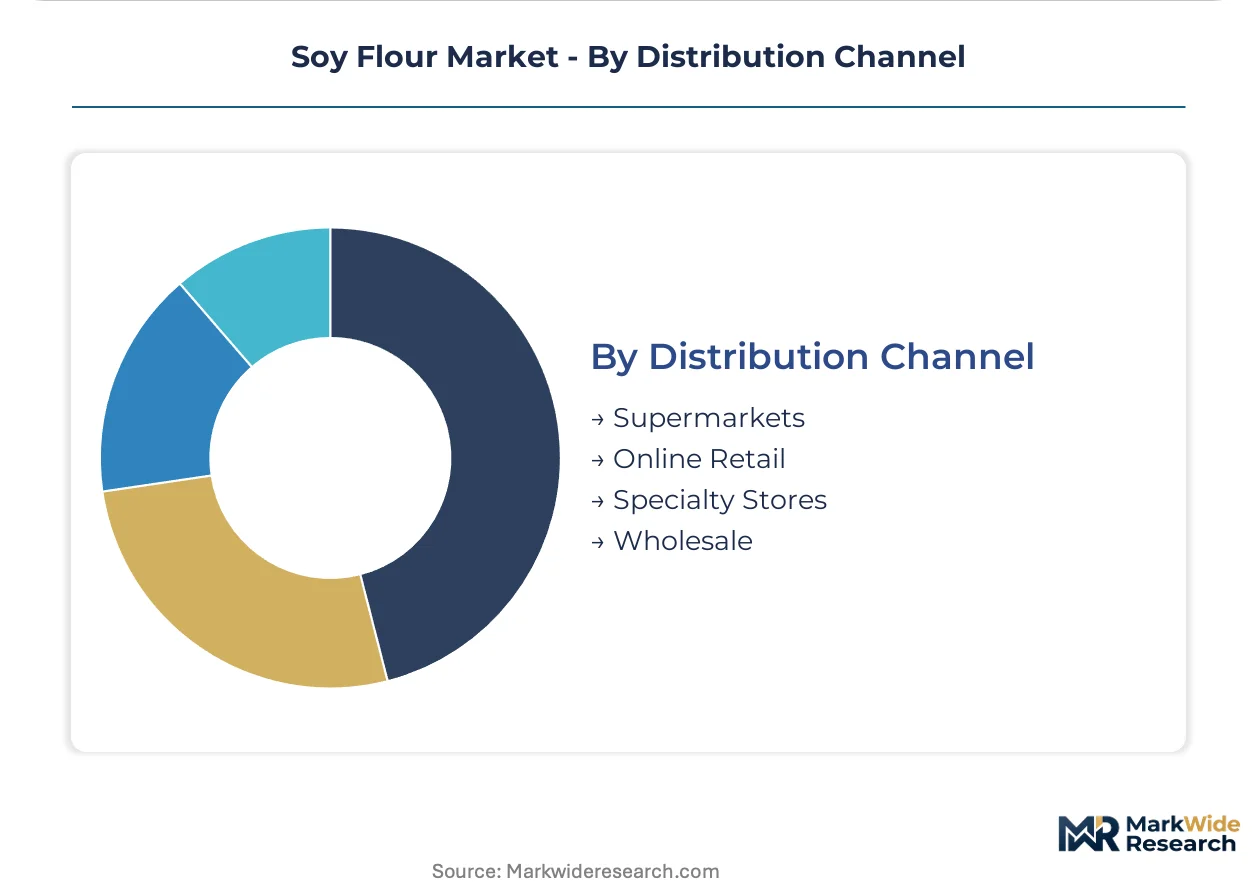
Supply concentration determines channel economics, with wholesale bypassing distributor markups for volume buyers while specialty stores capture organic premiums.
- Wholesale:Bulk ingredient platforms serve mid-sized meat alternative producers with direct miller relationships. Digital procurement reduces working capital requirements through just-in-time delivery scheduling.
- Specialty Stores:Organic and non-GMO certification requirements concentrate whole soy flour sales in dedicated health food channels across Netherlands and Switzerland.
- Supermarkets:Mass retail carries conventional de-fatted flour for home baking segments.
- Online Retail:E-commerce platforms aggregate small-batch specialty suppliers for geographic reach.
Wholesale channels dominate tonnage movement. Online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Brazil and Argentina prioritize export-oriented crushing for de-fatted flour production, while Germany and France emphasize organic whole flour for clean-label retail channels. The United States anchors institutional procurement through school nutrition and meat alternative manufacturing.
United States
Institutional foodservice and fast-casual restaurant chains drive de-fatted soy flour demand for protein fortification. FDA protein quality labeling rules and USDA school nutrition standards mandate documented amino acid completeness, forcing millers to upgrade certificate management systems. The Midwest corridor—centered on Decatur, Illinois—hosts concentrated crushing and milling infrastructure serving North American industrial bakeries.
Brazil
Export-oriented crushing capacity expansion in Mato Grosso and Paraná secures origin-sourced flour supply for European and Asian buyers. Port infrastructure investments at Santos reduce transit variability, though single-origin concentration creates chokepoint exposure. EU Green Deal Farm-to-Fork pesticide residue thresholds now exclude certain conventional Brazilian soy from organic processing channels.
Germany
Specialty retail channels in Germany command price separation for organic-certified whole soy flour with deforestation-free documentation. EFSA and EU organic certification standards shape product eligibility, while REACH compliance requirements filter supplier qualification. Northern European buyers cluster procurement through Hamburg and Rotterdam gateway ports for traceable single-origin fortification.
China
Domestic meat alternative manufacturing and bakery sectors absorb standardized de-fatted flour for cost-efficient protein enrichment. SAMR food safety regulations and GB standards for plant protein ingredients tighten import documentation requirements. Yangtze River Delta processing hubs near Shanghai concentrate extrusion texturization capacity for regional meat analog producers.
India
Underdeveloped meat alternative manufacturing offers first-mover positioning for fortifier suppliers targeting local bakery and noodle sectors. FSSAI protein content labeling mandates and BIS quality standards reshape procurement specifications for industrial buyers. Maharashtra and Gujarat host emerging oilseed processing clusters seeking backward integration into flour milling for domestic food manufacturers.
Soy Flour Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in soy flour supply. The upper tier comprises agricultural conglomerates with captive crushing assets and origination networks spanning multiple continents. Below them, regional millers and specialty ingredient suppliers compete on certification depth and custom formulation services. Two strategic archetypes dominate: scale-driven crush-and-mill operators optimizing co-product economics, and clean-label specialists commanding organic and non-GMO premiums. Competitive moves concentrate on vertical integration into origination assets and geographic expansion through port-adjacent milling investments.
Within the integrated agricultural conglomerate tier, Cargill, Archer Daniels Midland Company, and Bunge Limited exemplify scale-driven positioning. Cargill leverages Midwest origination networks for premium soybean supply security. Archer Daniels Midland Company anchors crushing margin optimization through co-product management at its Illinois complex. Bunge Limited occupies a position within South American export infrastructure, securing Brazilian port access for global flour distribution. These entities represent the consolidation logic driving procurement concentration among institutional food manufacturers seeking multi-origin supply assurance.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| CHS Inc. |
| Wilmar International |
| Bunge Limited |
| DuPont |
| The Scoular Company |
| Foodchem International Corporation |
| Bob's Red Mill Natural Foods |
| Others |
Supply Flow & Price Mechanics
Enzyme-modified soy flour displacing methylcellulose binders in meat alternative formulations simultaneously redirects procurement geography toward Brazilian crushing clusters and compresses premium pricing tiers for specialty hydrocolloids.
Pricing Analysis
Contract-based long-term offtake agreements dominate institutional procurement, with spot markets serving smaller regional processors. Price differentiation separates organic-certified whole flour from conventional de-fatted grades, with certification tier and volume scale as primary drivers. Pricing pressure stems from crush margin compression at Argentine processors facing weather-driven yield uncertainty. Mid-sized co-manufacturers exhibit highest price sensitivity, while fast-casual restaurant chains prioritize traceability over unit cost.
Supply Chain Analysis
Container availability fluctuations on the Santos-Rotterdam trade lane elevate inbound logistics costs for European buyers sourcing Brazilian-origin flour. Geographic supply concentrates in Brazil, Argentina, and the United States Midwest. Raw material flows draw from soybean origination networks, crushing capacity, and port handling infrastructure. Single-origin concentration at Santos creates chokepoint exposure. Distribution runs through wholesale bulk ingredient platforms and foodservice broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label substitution dynamics and USDA organic certification mandates are accelerating procurement restructuring, creating high-growth disruption for suppliers capable of certificate-of-analysis precision.
For Market Incumbents: Consolidate origination control through backward integration into Mato Grosso crushing assets. Expand near-infrared calibration capacity to meet FDA amino acid documentation requirements. Precision fermentation partnerships represent the critical threat to commodity flour positioning. For New Entrants and Emerging Players: Custom formulation services for enzyme-modified particle engineering present the most penetrable white-space opportunity. Target Southeast Asian bakery and noodle sectors seeking cost-efficient protein enrichment. Deploy e-commerce direct-to-manufacturer platforms to bypass distributor markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional millers lacking FSSC 22000 certification infrastructure. Long-term viability favors suppliers with multi-origin supply assurance and deforestation-free documentation capabilities. Monitor EU Green Deal pesticide residue threshold tightening as inflection indicator for organic channel eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination Assets | Captive soybean supply from Mato Grosso crushing clusters secures margin control against Argentine weather volatility. |
| Organic Certification Investment | Federal procurement preference under USDA standards opens institutional channels previously closed to conventional suppliers. |
| Precision Fermentation Partnership | Hybrid protein blending with biotech platforms enables clean-label positioning while managing unit economics. |
| Near-Infrared Calibration Expansion | Protein content consistency meets FDA amino acid completeness mandates for school nutrition contracts. |
| E-Commerce Platform Launch | Digital procurement reduces working capital requirements for mid-sized meat alternative manufacturers. |
Methodological Framework
A standing panel of crushing operations managers, food manufacturer procurement leads, and regulatory affairs specialists provided ongoing calibration. Primary interviews with ingredient formulators, distributor category buyers, and certification auditors combined with secondary validation from USDA procurement databases, FDA guidance documents, and Brazilian trade flow records. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product processing intensity, application cost tier, end-user specification rigor, and distribution channel concentration. CAGRs derived from historical volume trajectories and elasticity-adjusted demand drivers incorporated extrusion texturization adoption curves and organic certification penetration rates.
Underlying assumptions cover crush margin stability, port infrastructure reliability, and regulatory threshold continuity, with deviation risk concentrated in Argentine production zones and EU pesticide residue policy. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Meat Tenderizer Powder Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Cheese Powder Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Textured Wheat Protein Market
Ingredients
Cognitive Ingredients Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Pet Food Premix Market
Ingredients
Sesame Oil Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Almond Ingredients Market
Ingredients
Corn Oil Market
Ingredients
Fish Gelatin Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Global Starch Derivatives Market
Ingredients
Hydrolyzed Vegetable Protein Market