
 Vegan Oatmeal Market | 2026-2036
Vegan Oatmeal Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Oatmeal Market Analytics
EU Green Deal compliance is hardening the cost-of-entry calculus for oat processors seeking shelf space in European retail. General Mills leverages its North American milling infrastructure to sustain bulk supply contracts with foodservice distributors. Bob's Red Mill Natural Foods differentiates through organic certification density and specialty grain expertise. Nature's Path Foods anchors its position via climate-neutral sourcing commitments and independent retail channel control.
Vegan oatmeal comprises dehulled oat groats processed through steaming, flaking, or cutting to yield beta-glucan-rich porridge products with soluble fiber content typically ranging from four to six grams per serving, designed for cholesterol management and sustained glycemic response in consumer diets. Instant oatmeal dominates volume through single-serve convenience positioning in commuter and office consumption occasions, while steel-cut oats command premium shelf pricing in specialty retail due to longer cook times and artisanal perception. Overnight oats represent the fastest-expanding format as refrigerated ready-to-eat breakfast adoption displaces hot preparation routines in urban households.
FDA nutrition labeling requirements and USDA organic standards govern product claims and ingredient transparency in the United States, while EFSA health claim authorization shapes beta-glucan cardiovascular marketing permissions across European markets. These frameworks elevate reformulation costs for new entrants but simultaneously protect established brands with existing certification infrastructure. Stakeholders must monitor evolving clean-label thresholds and carbon accounting disclosure mandates as procurement criteria tighten across institutional foodservice contracts.
Market Dynamics
The EU Green Deal's sustainable agriculture mandates are hardening procurement criteria for oat processors, forcing reformulation investments and carbon accounting disclosure across institutional foodservice contracts while concentrating demand in certified organic supply channels.
Growth Catalysts
- Hospitality Sector Expansion:Hotels and corporate cafeterias are expanding vegan breakfast menus as plant-based dining becomes standard in contract catering. ESG procurement policies now require climate-neutral grain sourcing.
- EFSA Beta-Glucan Claims:Authorized cardiovascular health claims enable premium positioning for soluble fiber content in European retail. Reformulated products command shelf space through substantiated cholesterol management messaging.
- Overnight Oats Format:Refrigerated ready-to-eat breakfast adoption in urban households displaces hot preparation routines. Convenience positioning captures commuter and office consumption occasions previously served by instant formats.
Market Restraints
- Organic Oat Input Volatility:Certified organic oat groat prices fluctuate with weather-dependent harvests in Nordic growing regions. Yield uncertainty compresses processor margins during contract fulfillment.
- German Demand Concentration:Climate-neutral grain preference in Germany absorbs disproportionate supply volume. Over-reliance on this single market creates pricing pressure during local harvest shortfalls.
- Steel-Cut Technical Limitation:Extended cook times restrict adoption in foodservice environments requiring rapid throughput. Artisanal perception fails to offset operational inefficiency in high-volume settings.
Strategic Opportunities
- USDA Organic Certification Gap:North American retail channels lack density of certified organic vegan oatmeal relative to European penetration. FDA nutrition labeling infrastructure supports claims-based differentiation for entrants.
- Carbon Accounting Integration:EU Green Deal procurement criteria create first-mover advantage for processors with verified lifecycle emissions data. Institutional contracts increasingly mandate Scope 3 grain sourcing disclosure.
- Refrigerated Distribution Innovation:Cold-chain expansion in urban grocery enables overnight oats placement outside traditional hot-cereal aisles. Direct-to-door subscription models bypass conventional retail slotting constraints.
Industry Challenges
- Clean-Label Reformulation Timeline:EFSA and FDA dual compliance extends product development cycles for transatlantic brands. Ingredient transparency thresholds tighten faster than certification infrastructure expands.
- Specialized Milling Capex:Dehulling and flaking equipment for gluten-free oat processing requires capital deployment at smaller scale than conventional grain infrastructure. Financing availability constrains mid-tier processor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Oatmeal Market |
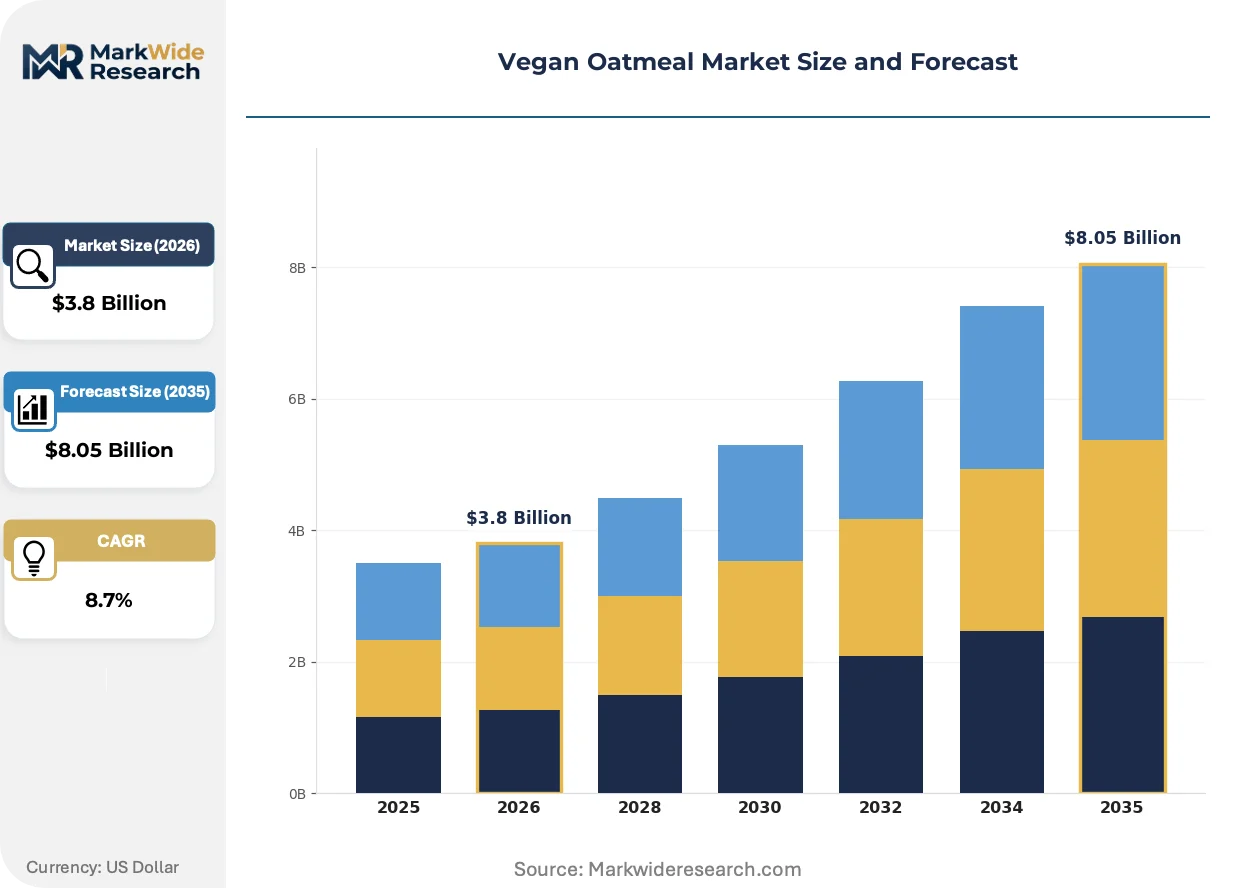
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oatmeal, Steel-Cut Oats, Rolled Oats, Overnight Oats Flavor Profile: Chocolate, Apple Cinnamon, Maple, Berry Medley Packaging Type: Bags, Cups, Sachets, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | General Mills, Bob's Red Mill Natural Foods, The Quaker Oats Company, Kellogg Company, Nestlé, Nature's Path Foods, Post Holdings, Grain Millers, B&G Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Oatmeal Market Evolving Landscape
Product format innovation and regulatory disclosure requirements are restructuring competitive advantage around supply chain traceability rather than manufacturing scale alone.
Precision oat processing technology is modularizing production lines for rapid format switching between instant, steel-cut, and overnight oat specifications. Regional co-manufacturers adopt these systems to serve multiple brand clients without dedicated equipment. This flexibility is modularizing capital deployment, enabling smaller processors to compete on variety rather than volume.
CSRD corporate sustainability reporting mandates in Europe require granular Scope 3 emissions disclosure for agricultural inputs. Oat processors must implement farm-level carbon tracking to retain institutional contract eligibility. Foodservice distributors in Germany and France are responding by consolidating procurement around suppliers with verified climate-neutral certification.
Urban households are displacing hot breakfast preparation with refrigerated overnight oats consumed during commutes. Grocery retailers are reallocating shelf space from ambient cereal aisles to refrigerated grab-and-go sections. This channel rotation is most visible in metropolitan areas of Germany and the United States where cold-chain infrastructure supports expanded fresh breakfast placement.
Vegan Oatmeal Market Segmentation
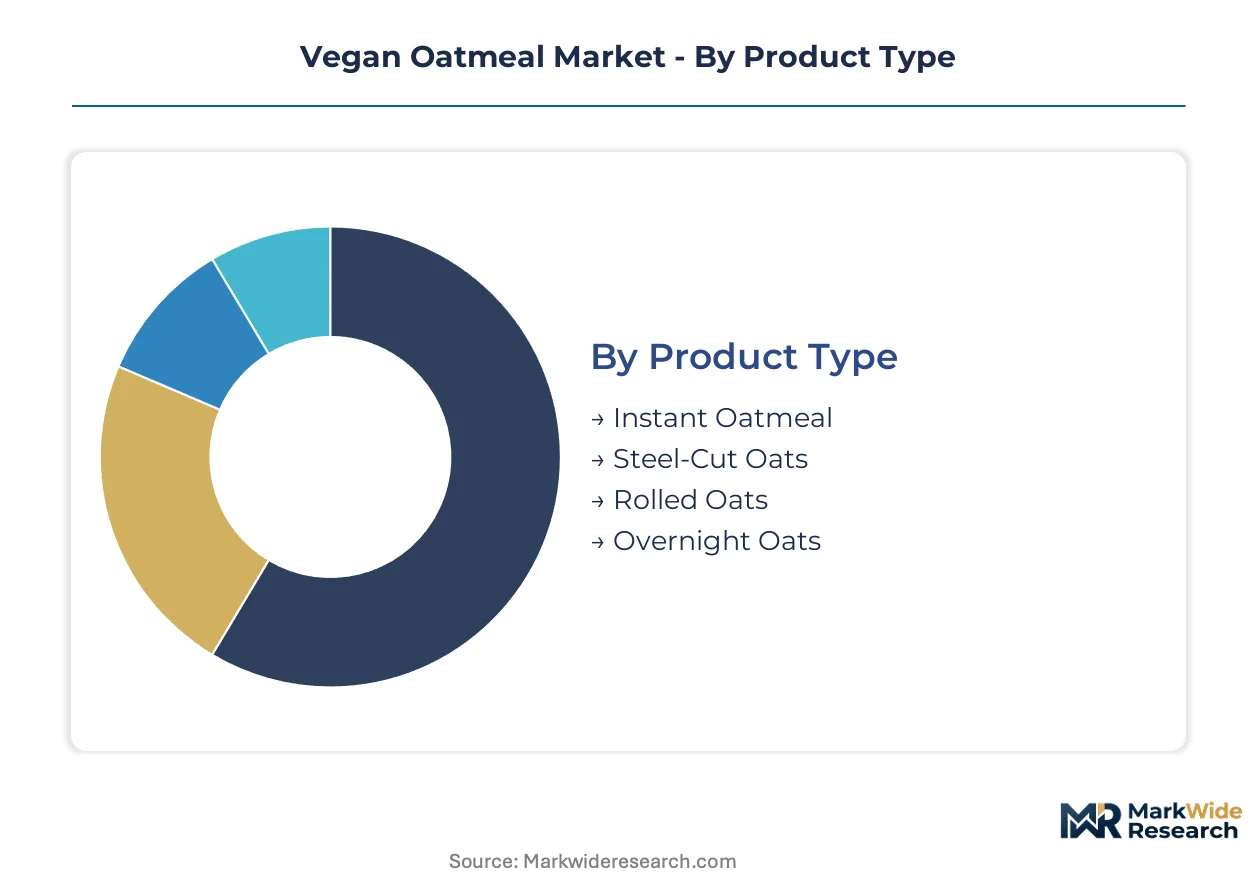
Format differentiation in vegan oatmeal determines procurement patterns across institutional foodservice and retail channels. Processing method, flavor positioning, and packaging economics each create distinct margin structures and shelf placement strategies.
Product Type:
Buyer differentiation hinges on preparation time tolerance and nutritional density priorities.
- Instant Oatmeal:Steam-processed and pre-cooked flakes rehydrate with hot water in under two minutes. Commuter demand in the United States and Germany absorbs the majority of single-serve cup volume. Convenience positioning captures office breakfast occasions but faces margin compression from private-label competition.
- Overnight Oats:Raw rolled oats soaked in plant-based milk yield refrigerated ready-to-eat porridge with preserved beta-glucan integrity. Urban households in Berlin and New York displace hot cereal routines with grab-and-go formats. Cold-chain expansion enables placement outside traditional cereal aisles.
- Steel-Cut Oats:Groats cut into pinhead pieces require 20-30 minute cook times. Artisanal perception commands premium pricing in specialty retail.
- Rolled Oats:Steamed and flattened groats balance cook time with texture. Bulk sales dominate baking and foodservice ingredient procurement.
Volume sits with Instant Oatmeal; growth tilts toward Overnight Oats.
Flavor Profile:
Regional taste preferences and seasonal rotation cycles determine formulation investment priorities.
- Apple Cinnamon:Classic breakfast flavor profile with year-round stability in North American retail. EFSA-approved health claims pair naturally with cholesterol management messaging.
- Berry Medley:Antioxidant positioning targets wellness-focused consumers in German organic channels. Limited harvest windows for freeze-dried strawberries constrain supply planning.
- Chocolate:Cocoa powder formulations attract younger demographics and dessert-positioned consumption occasions.
- Maple:Natural sweetener appeal aligns with clean-label procurement criteria in Canadian and US markets.
Apple Cinnamon anchors baseline volume; Berry Medley is climbing the fastest on wellness positioning.
Packaging Type:
Unit economics and waste reduction mandates reshape container selection across channel tiers.
- Sachets:Single-serve paper or film pouches minimize portion waste in hospitality minibars and airline catering. Lightweight format reduces freight costs for e-commerce fulfillment.
- Cups:Pre-portioned containers with peelable lids dominate convenience store and vending placement. Recyclable cup materials face EU Green Deal packaging compliance scrutiny.
- Bags:Multi-serve resealable pouches serve family households and bulk buyers in club retail.
- Bulk Containers:Foodservice totes and dispensers supply cafeterias and bakery ingredient operations.
Sachets dominate travel and hospitality procurement; cups face sustainability-driven substitution pressure.
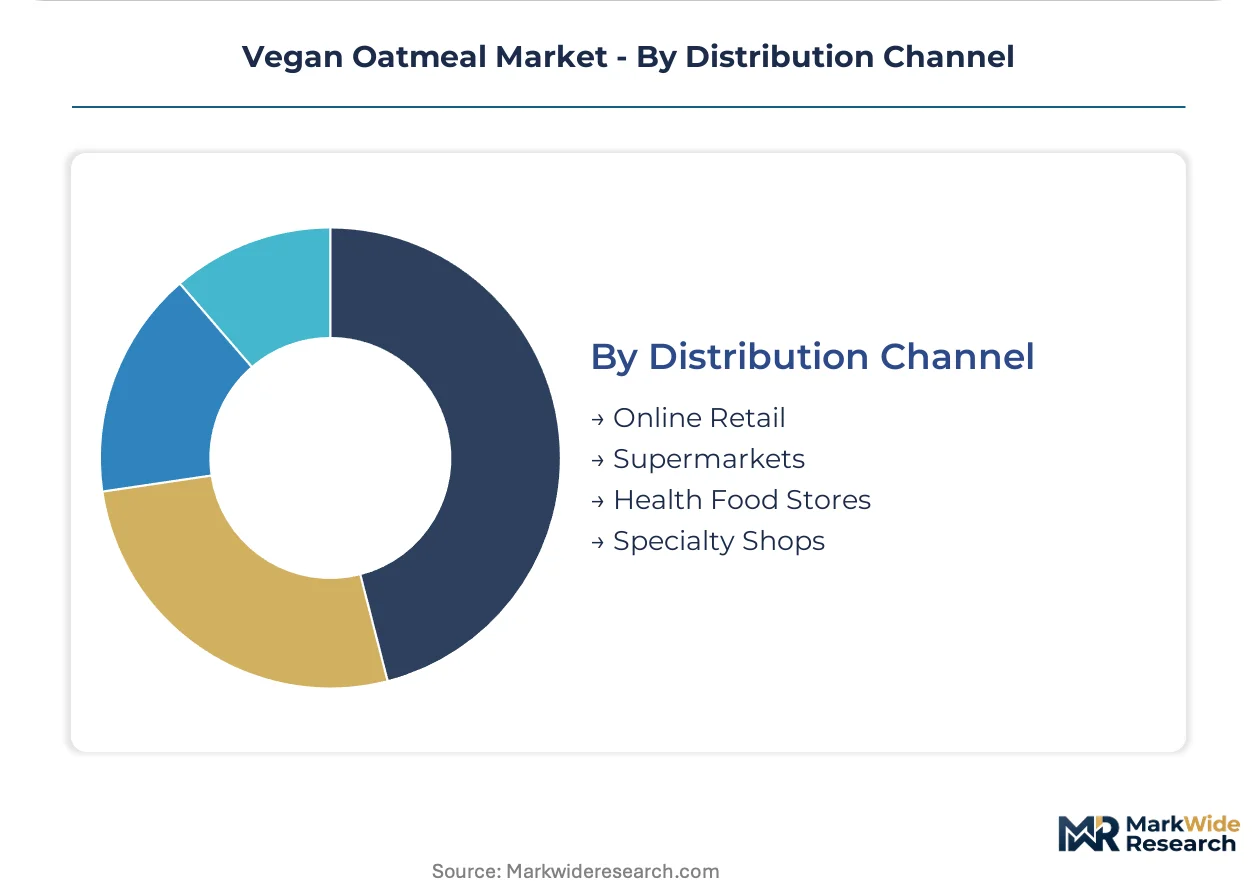
Distribution Channel:
Channel selection reflects shopper mission type and certification verification requirements.
- Supermarkets:Mass-market placement requires slotting fee negotiation and promotional calendar participation. Climate-neutral certification increasingly gates entry in German retail banners.
- Health Food Stores:Independent retailers prioritize organic certification density and specialty grain expertise. Staff recommendation drives trial for premium-positioned formats.
- Online Retail:Subscription models bypass conventional shelf space constraints. Direct-to-door overnight oats capitalize on urban cold-chain infrastructure.
- Specialty Shops:Gourmet and ethnic grocers curate artisanal steel-cut and heritage oat varieties.
Supermarkets hold the revenue base; online retail is gaining share fastest on subscription stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's sustainable agriculture tax incentives are concentrating oat processing investment in Nordic certified-organic zones and North American Prairie infrastructure corridors.
United States
Urban cold-chain expansion in New York and Los Angeles accelerates overnight oats adoption among commuter households. FDA nutrition labeling requirements govern beta-glucan cardiovascular claims while USDA organic standards shape procurement criteria. The Pacific Northwest cluster around Portland anchors specialty grain milling capacity for foodservice distribution.
Germany
Climate-neutral grain preference absorbs disproportionate supply volume from Nordic organic oat harvests. EFSA health claim authorization enables cholesterol management messaging in retail packaging. The Berlin-Brandenburg metro corridor concentrates refrigerated ready-to-eat breakfast innovation and subscription fulfillment infrastructure.
Canada
Prairie provinces sustain bulk oat groat supply contracts through heritage milling infrastructure. Health Canada and PMRA standards intersect with provincial organic certification bodies. The Saskatchewan-Manitoba grain belt supplies raw material to North American instant oatmeal processors.
United Kingdom
Independent health food retail channels prioritize organic certification density and specialty grain expertise. FSA labeling requirements align with evolving clean-label thresholds across contract catering. London's urban cold-chain network enables overnight oats placement in grab-and-go refrigerated sections.
France
CSRD corporate sustainability reporting mandates drive farm-level carbon tracking for institutional foodservice eligibility. ANSM and CNIL frameworks intersect with EU Green Deal procurement criteria. The Île-de-France region concentrates hospitality sector vegan breakfast menu expansion and ESG procurement policy implementation.
Vegan Oatmeal Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across format tiers and certification segments. The market structure tilts toward scale-driven consolidation in instant oatmeal while specialty channels sustain independent organic millers. Three archetypes dominate: diversified food conglomerates with North American milling infrastructure, certified-organic pure-plays with climate-neutral sourcing commitments, and regional co-manufacturers with modular precision processing lines. Competitive moves center on carbon accounting integration for EU institutional contracts and cold-chain partnerships for refrigerated format expansion.
Within the diversified conglomerate tier, General Mills and Kellogg Company occupy positions anchored by bulk supply infrastructure and foodservice distribution scale. Among certified-organic specialists, Bob's Red Mill Natural Foods and Nature's Path Foods exemplify the archetype built on organic certification density and independent retail channel control. These named entities represent the strategic poles—scale-driven commodity supply versus sustainability-certified premium positioning—that structure competitive dynamics across procurement channels.
| Leading Market Players |
|---|
| General Mills |
| Bob's Red Mill Natural Foods |
| The Quaker Oats Company |
| Kellogg Company |
| Nestlé |
| Nature's Path Foods |
| Post Holdings |
| Grain Millers |
| B&G Foods |
| Others |
Value Network & Pricing Analysis
Modular precision oat processing technology is compressing capital barriers for mid-tier processors while simultaneously fragmenting supply concentration across Nordic organic zones and North American Prairie corridors. This equipment transition enables regional co-manufacturers to compete on format variety rather than volume scale, reshaping both cost economics and procurement power distribution.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with certified organic oat groats commanding substantial markups over conventional grades due to EFSA health claim authorization requirements. Price differentiation rests on organic certification density and climate-neutral verification status, with German institutional buyers exhibiting lowest price sensitivity due to ESG procurement mandates. Cost compression in instant oatmeal runs through private-label competition, while steel-cut formats sustain artisanal premiums despite operational inefficiency.
Supply Chain Analysis
Workforce availability constraints in Saskatchewan-Manitoba and Nordic growing regions are tightening seasonal processing capacity during harvest windows. Supply concentrates in Canada, Germany, and the United States, with raw material dependencies on certified organic oat groats, plant-based milk inputs, and recyclable packaging substrates. Single-source vulnerability in Nordic organic harvests creates contract fulfillment risk during weather-dependent yield shortfalls. Distribution runs through foodservice distributors, supermarket chains, and direct-to-door subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Scope 3 disclosure mandates have erected a cost-of-compliance barrier that protects incumbent processors with verified carbon accounting infrastructure while excluding undercapitalized entrants from institutional contract eligibility.
For Market Incumbents: To counter private-label margin erosion in instant oatmeal, deepen backward integration into certified organic oat groat sourcing through Nordic supply agreements. Prioritize climate-neutral certification density as the priority lever for retaining German hospitality sector contracts under tightening ESG procurement criteria.
For New Entrants and Emerging Players: Precision oat processing technology enables rapid format switching between overnight oats and steel-cut specifications without dedicated equipment investment. Target USDA Organic certification gaps in North American retail channels, deploying direct-to-door subscription models that bypass conventional supermarket slotting fee structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in certified-organic pure-plays with climate-neutral sourcing commitments and independent retail channel control. Long-term viability favors processors with farm-level carbon tracking infrastructure aligned with CSRD disclosure mandates. Watch for EFSA health claim authorization expansions as inflection indicators for premium positioning sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Neutral Certification Investment | EU Green Deal procurement criteria gate institutional foodservice contracts around verified lifecycle emissions data. |
| Cold-Chain Distribution Expansion | Urban grocery retailers in Berlin and New York reallocate shelf space toward refrigerated grab-and-go overnight oats placement. |
| Backward Integration into Organic Sourcing | Nordic certified-organic oat groat supply agreements compress input volatility exposure during contract fulfillment. |
| Precision Processing Technology Deployment | Modular production lines enable regional co-manufacturers to serve multiple brand clients without dedicated equipment. |
| Direct-to-Consumer Subscription Launch | Bypass conventional retail slotting constraints through urban cold-chain infrastructure for overnight oats fulfillment. |
Research Methodology
Multi-period observation of certified organic oat groat pricing, EFSA health claim authorization timelines, and hospitality sector ESG procurement policy adoption anchored the trend analysis, supplemented by interviews with oat mill procurement directors, foodservice distributor category managers, retail buyer executives, and sustainability compliance officers. Secondary validation drew from EU Green Deal regulatory filings, CSRD corporate sustainability reports, USDA organic certification databases, and Nordic harvest yield statistics. Bottom-up volume modeling and top-down value estimation were triangulated against channel shipment data.
Input-output matrices structured demand forecasting across product format, flavor profile, packaging type, and distribution channel dimensions throughout the projection horizon. CAGRs were derived from segment-level growth rate synthesis calibrated to regulatory milestone impacts. Forecast inputs incorporated EU Green Deal implementation pace, cold-chain infrastructure expansion rates, and organic oat acreage conversion trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events in Nordic growing regions or accelerated CSRD disclosure mandate expansion. Forecasts reflect documented assumptions regarding EFSA health claim authorization stability and German institutional procurement policy continuity. Material deviation in organic certification infrastructure buildout or EU sustainable agriculture tax incentive scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Fermented Plant-Based Food Market