
 South Africa MNO - MVNO Market | 2026-2036
South Africa MNO - MVNO Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa MNO - MVNO Market Analytics
Modular service bundling is shifting how South African buyers construct connectivity plans. Vodacom leverages its infrastructure depth to anchor premium postpaid portfolios. FNB Connect differentiates through financial-service integration that locks in retail banking clients. Rain specializes in data-only propositions that compete aggressively on price per gigabyte.
The South Africa MNO-MVNO ecosystem comprises mobile network operators owning licensed spectrum and radio infrastructure alongside mobile virtual network operators leasing wholesale capacity to resell branded services under ICASA regulatory oversight. The primary commercial purpose is delivering voice, data, and messaging services across GSM, LTE, 4G, and 5G radio interfaces to end users without requiring spectrum ownership. Postpaid and hybrid service categories capture the deepest margin pools as enterprise clients prioritize predictable billing and dedicated support tiers. Prepaid remains the highest-volume segment among individual users in peri-urban and informal settlement markets where credit access is constrained. 5G technology deployment is accelerating fastest in metropolitan distribution channels where online platforms and retail outlets converge for device-and-plan bundling.
ICASA governs spectrum allocation and wholesale pricing transparency, while the Competition Commission scrutinizes MNO dominance in national roaming negotiations. These frameworks shape MVNO market access by mandating cost-reflective wholesale rates and interconnection standards. The Consumer Protection Act reinforces disclosure requirements for prepaid tariff structures. Stakeholders must monitor spectrum auction outcomes and wholesale cost benchmarks to calibrate retail pricing power against infrastructure-dependent rivals.
Market Dynamics
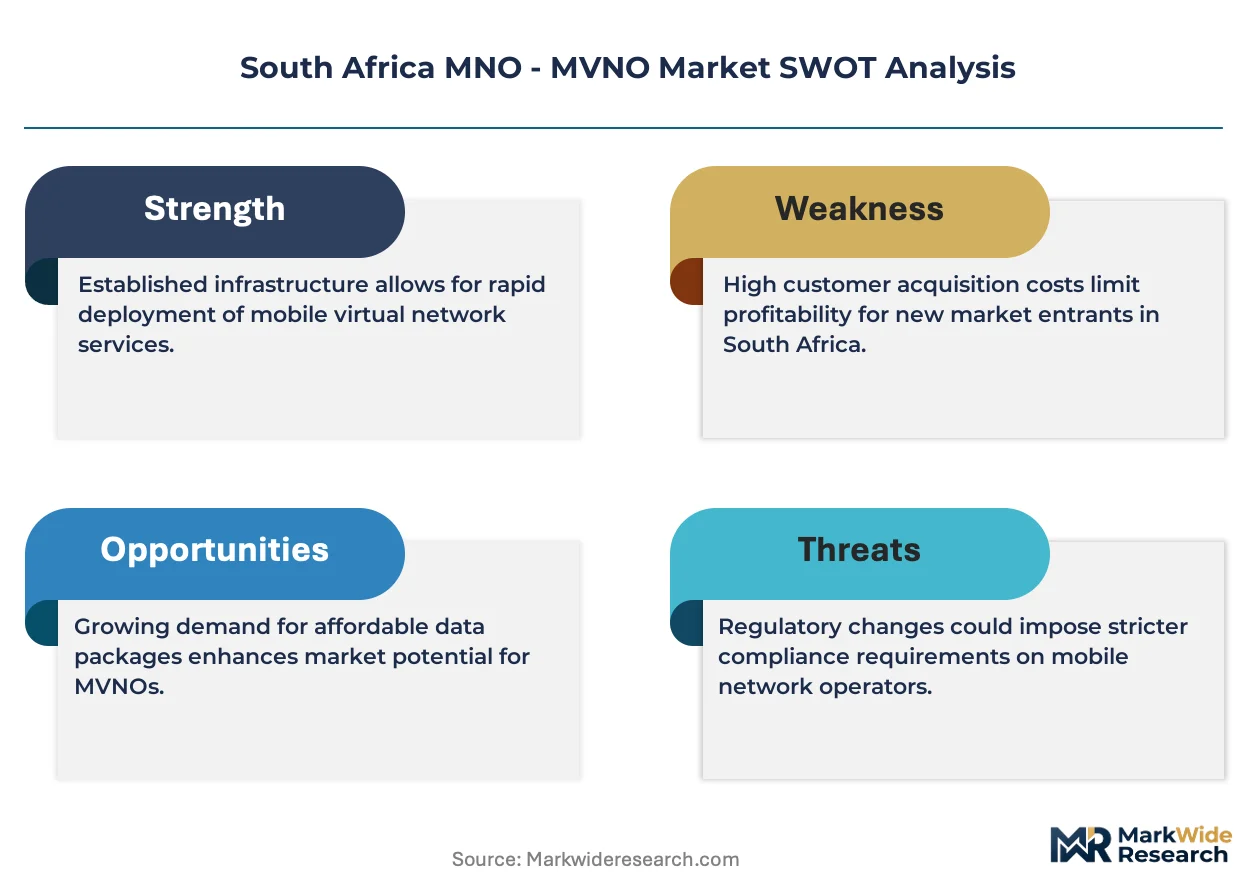
ICASA's wholesale pricing transparency mandates are compressing MNO margins while forcing infrastructure owners to open network access at regulated rates, fundamentally restructuring how virtual operators enter the South African mobile services market.
Growth Catalysts
- ICASA Spectrum Licensing Reforms:New frameworks mandate cost-reflective wholesale rates, lowering barriers for MVNOs to lease capacity from established infrastructure owners without spectrum ownership requirements.
- Hybrid Connectivity Adoption:Small enterprises across Gauteng's corporate corridors are bundling fixed-line and mobile services, creating demand for flexible postpaid arrangements that MNOs and MVNOs can jointly serve.
- 5G Radio Interface Deployment:Accelerated rollout in metropolitan distribution channels enables higher-margin data services and supports device-and-plan bundling strategies for premium customer segments.
Market Restraints
- Wholesale Rate Volatility:MNOs retain pricing power in national roaming negotiations, creating input cost uncertainty for MVNOs dependent on leased network capacity.
- Infrastructure Concentration:Licensed spectrum and radio assets concentrate among three dominant MNOs, limiting MVNO negotiating leverage and service differentiation options.
- Credit Access Constraints:Peri-urban and informal settlement populations face limited banking penetration, restricting postpaid adoption and compressing average revenue per user in prepaid-heavy segments.
Strategic Opportunities
- Western Cape Enterprise Corridors:Cape Town's technology and financial services clusters show underpenetrated demand for dedicated enterprise MVNO solutions with service-level guarantees.
- Financial-Service Convergence:Banking-integrated mobile offerings that bundle airtime, data, and payment services create sticky customer relationships beyond pure connectivity.
- eSIM Technology Adoption:Remote provisioning capabilities eliminate physical distribution dependencies, enabling digital-first MVNO launches with reduced operational overhead.
Industry Challenges
- Interconnection Standard Complexity:MVNOs must navigate ICASA-mandated technical specifications for seamless handoff between host networks, requiring specialized engineering capabilities.
- Customer Acquisition Cost Intensity:Saturated urban markets demand heavy marketing expenditure to dislodge subscribers from established MNO relationships, straining MVNO capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa MNO - MVNO Market |
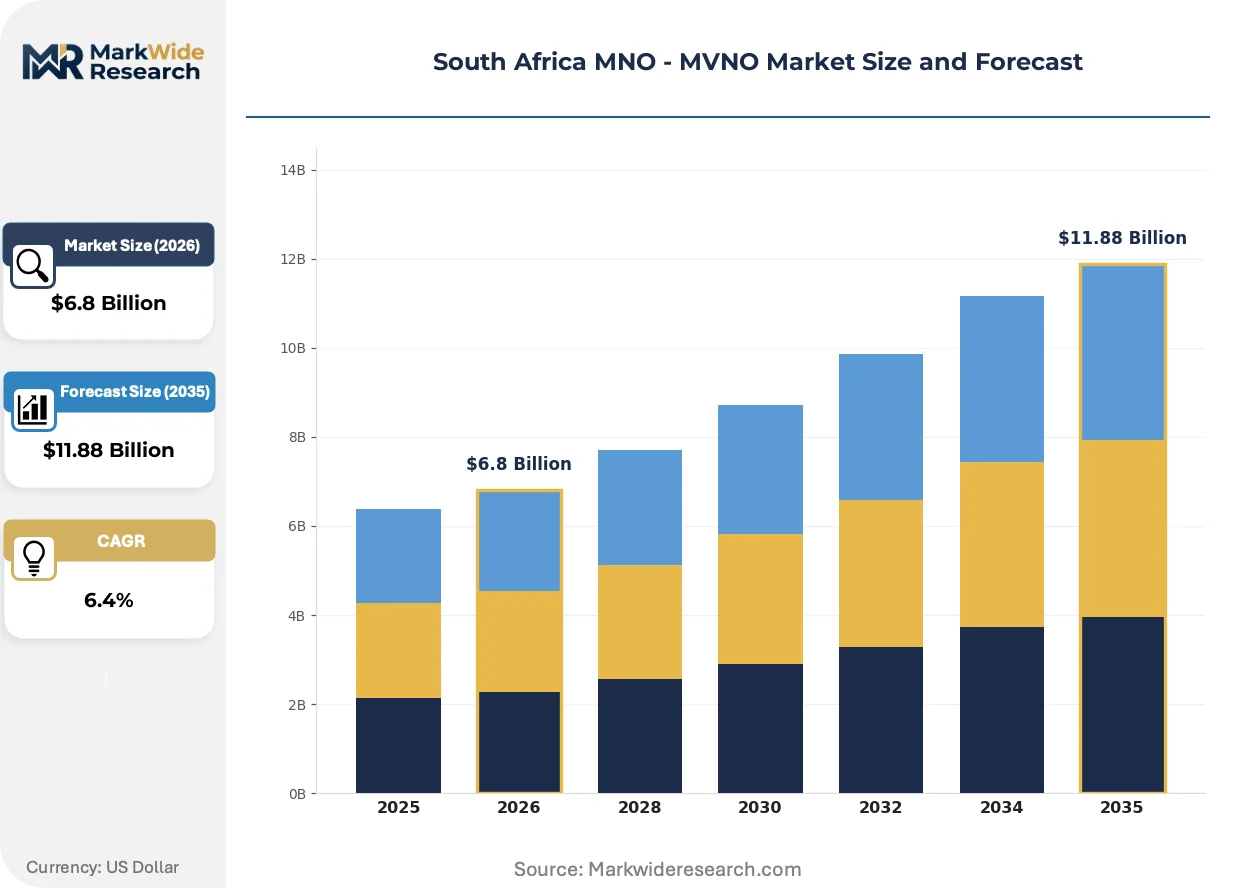
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Postpaid, Prepaid, Hybrid, Roaming Customer Type: Individual Users, Small Enterprises, Large Corporations, Government Technology: 4G, 5G, LTE, GSM Distribution Channel: Retail Outlets, Online Platforms, Telemarketing, Resellers |
| Companies Covered | Telkom, Melon, Vodacom, Standard Bank Connect, FNB Connect, MTN South Africa, Rain, PnP Mobile, Cell C, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa MNO - MVNO Market Evolving Landscape
Digital distribution platforms and embedded connectivity models are displacing traditional retail-led subscriber acquisition across South Africa's mobile services landscape, compressing activation timelines and reshaping customer lifetime value calculations.
Standalone data-only propositions are rewriting competitive positioning in the South African market. Rain pioneered this architecture, stripping voice and messaging to compete purely on price per gigabyte. Price-sensitive consumers and secondary-device owners are migrating to these plans at accelerating velocity. The model is compressing voice-centric ARPU structures and forcing hybrid bundling responses from full-service operators.
ICASA's Consumer Protection Act disclosure requirements are tightening tariff transparency standards. Prepaid pricing structures must now present total cost clarity upfront, eliminating hidden out-of-bundle charges. Individual users in informal settlement markets benefit from simplified comparison shopping, while operators face compliance overhead in restructuring legacy pricing systems.
Enterprise procurement patterns favor subscription-based connectivity with predictable billing cycles. Corporate IT departments in Johannesburg and Pretoria are consolidating vendor relationships, demanding dedicated support tiers and volume-commitment discounts. This behavior concentrates purchasing power among fewer buyers, pressuring MVNOs to demonstrate service reliability metrics that match MNO infrastructure guarantees.
South Africa MNO - MVNO Market Segmentation
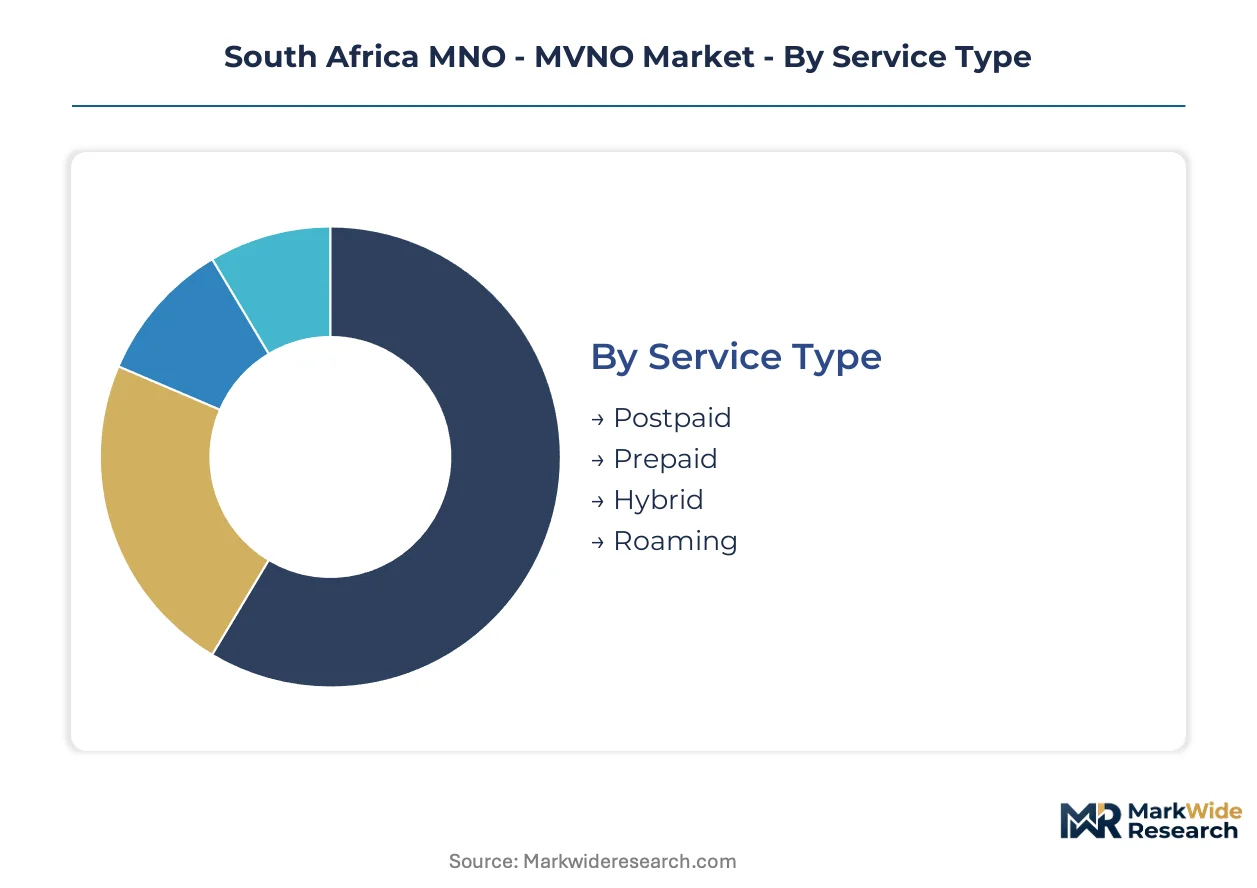
Segmentation in South Africa's MNO-MVNO market reveals how service architecture, customer economics, and technology deployment create distinct margin pools. Each dimension shapes wholesale negotiations, retail pricing power, and customer acquisition strategies differently across Gauteng's corporate corridors and peri-urban settlements.
Service Type:
Standalone service propositions operate independently of bundled financial products, while embedded offerings integrate with banking or enterprise software stacks.
- Postpaid:Monthly billing arrangements with contractual commitments and credit checks. Large corporations in Johannesburg and Pretoria prioritize predictable expenditure and dedicated support tiers, driving enterprise procurement consolidation.
- Prepaid:Pay-as-you-go models requiring no credit history or bank account. Demand concentrates in informal settlement markets where ICASA's Consumer Protection Act disclosure requirements simplify tariff comparison for price-sensitive users.
- Hybrid:Bundled fixed-line and mobile connectivity with unified billing. Small enterprises across Gauteng's corporate corridors adopt these packages to streamline vendor management and secure volume discounts.
- Roaming:Cross-network service continuity for subscribers traveling beyond host MNO coverage. National roaming negotiations under Competition Commission scrutiny create input cost volatility for MVNOs dependent on leased capacity.
Volume placements concentrate in Prepaid; the faster expansion belongs to Hybrid.
Customer Type:
Cost tier differentiation separates high-touch enterprise accounts from low-margin mass-market segments with diverging service expectations.
- Individual Users:Personal subscribers purchasing single-line voice and data services. Peri-urban populations with constrained credit access drive prepaid dominance, compressing average revenue per user.
- Small Enterprises:Businesses with 10-100 employees requiring multi-line connectivity with basic support. These buyers are gaining share fastest as ICASA's wholesale pricing reforms enable MVNOs to compete for flexible postpaid arrangements.
- Large Corporations:Enterprise clients demanding service-level agreements, dedicated account management, and volume-commitment pricing. IT departments in Cape Town's technology clusters underpenetrate MVNO solutions relative to MNO infrastructure guarantees.
- Government:Public sector procurement through centralized tender processes with compliance and security requirements. State contracts favor established operators with proven reliability metrics and national coverage footprints.
Revenue concentration sits with Large Corporations; Small Enterprises are climbing the fastest.
Technology:
Application maturity separates legacy radio interfaces from next-generation deployments with diverging capital intensity and margin profiles.
- 4G:LTE-Advanced networks delivering 50-100 Mbps peak speeds with mature device ecosystems. Metropolitan distribution channels still route majority volume through this interface as 5G handset penetration lags.
- 5G:Next-generation radio with sub-6GHz and mmWave variants enabling enterprise IoT and fixed-wireless substitution. Rollout accelerates fastest in Johannesburg and Pretoria where device-and-plan bundling strategies target premium customer segments.
- LTE:Earlier 4G generation operating on 1800MHz and 2600MHz bands with established coverage. Rural and secondary urban markets retain significant LTE dependency where spectrum refarming proceeds gradually.
- GSM:2G voice-centric infrastructure for basic handsets and machine-to-machine applications. Legacy support obligations constrain spectrum reallocation despite declining subscriber counts.
Current subscriptions cluster on 4G; 5G deployment is gaining share fastest.
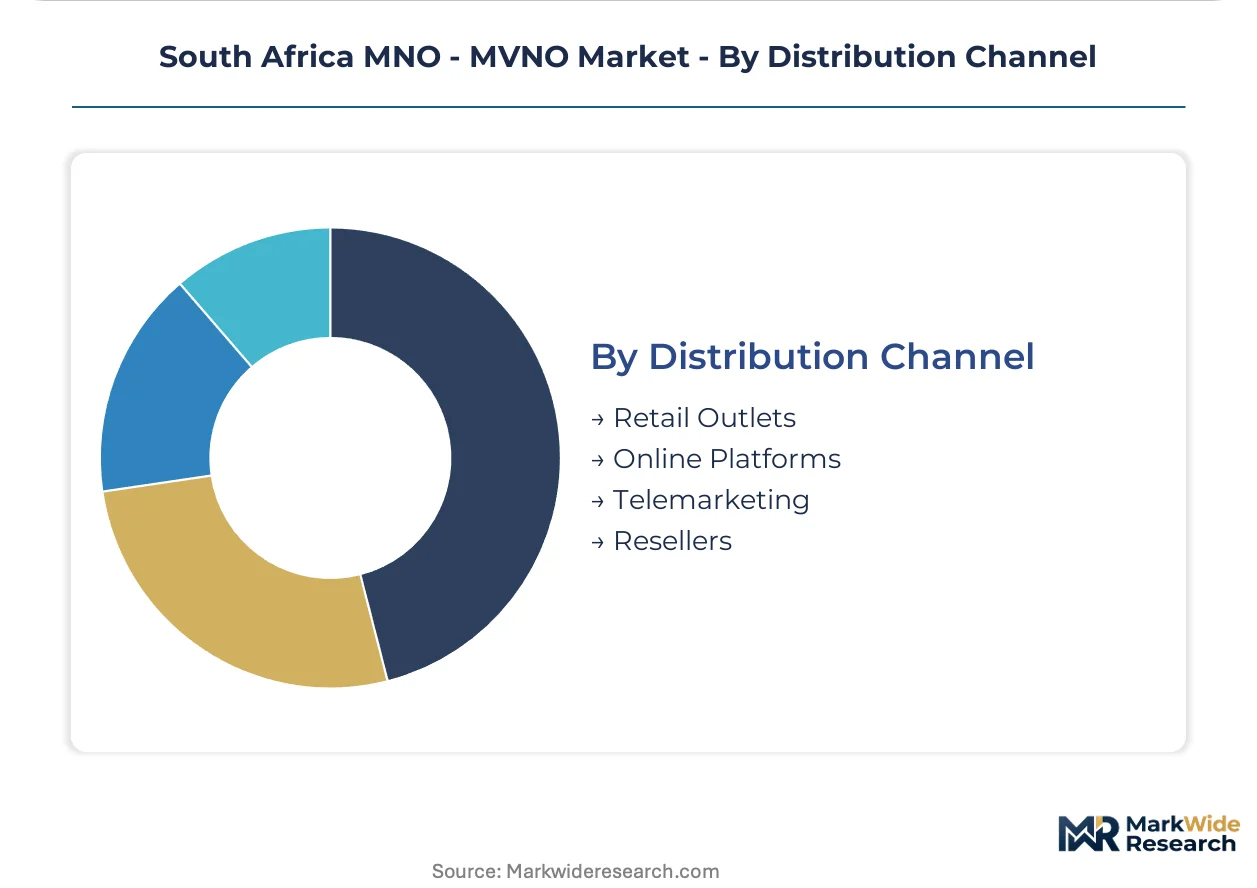
Distribution Channel:
Customer acquisition economics favor digital-first models over physical retail with diverging activation timelines and lifetime value calculations.
- Retail Outlets:Branded stores and electronics retailers offering in-person plan selection and SIM activation. Township and peri-urban markets retain retail dependency where smartphone penetration and digital literacy lag.
- Online Platforms:Direct-to-consumer websites and mobile applications enabling self-service provisioning. eSIM technology adoption eliminates physical distribution dependencies, supporting digital-first MVNO launches with reduced operational overhead.
- Telemarketing:Outbound sales campaigns targeting existing customer databases with upgrade and migration offers. Regulatory constraints under the Consumer Protection Act limit cold-calling flexibility.
- Resellers:Independent agents and informal traders distributing prepaid vouchers and starter packs. This channel penetrates deepest in informal settlement markets beyond formal retail footprints.
Transaction volume flows through Retail Outlets; Online Platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's mobile services production concentrates in Johannesburg and Pretoria infrastructure corridors, while consumption spreads across Gauteng's dense corporate zones, Western Cape technology clusters, and KwaZulu-Natal industrial belts. This geographic split shapes wholesale network economics and MVNO entry strategies differently across sub-national markets.
Gauteng Province
Johannesburg and Pretoria corporate corridors generate concentrated demand for hybrid connectivity packages among small enterprises. ICASA's wholesale pricing transparency mandates enable MVNOs to lease capacity from host MNOs at regulated rates. Sandton and Rosebank financial districts show accelerating adoption of banking-integrated mobile services that bundle airtime with payment platforms.
Western Cape
Cape Town's technology and financial services clusters present underpenetrated opportunities for dedicated enterprise MVNO solutions. The Consumer Protection Act's disclosure requirements simplify tariff comparison for individual users in peri-urban settlement markets. Stellenbosch and Paarl wine-industry corridors are adopting IoT-enabled vineyard monitoring that drives specialized data-service demand.
KwaZulu-Natal
Durban's port logistics and manufacturing base creates demand for machine-to-machine connectivity across supply chain operations. ICASA spectrum licensing reforms have lowered barriers for regional MVNOs to serve industrial clients without infrastructure ownership. Richards Bay mineral processing corridors are consolidating vendor relationships around subscription-based connectivity with predictable billing cycles.
Eastern Cape
Port Elizabeth automotive manufacturing clusters and Gqeberha port operations require reliable cross-network roaming for logistics fleet management. Credit access constraints in informal settlement markets sustain prepaid dominance, compressing average revenue per user. East London industrial zones are negotiating volume-commitment discounts with operators demonstrating service reliability metrics.
North West Province
Rustenburg platinum mining operations and surrounding extraction corridors generate specialized demand for remote-site connectivity solutions. The Competition Commission's scrutiny of MNO dominance in national roaming negotiations creates input cost uncertainty for MVNOs serving dispersed mining communities. Mahikeng and surrounding agricultural belts show emerging adoption of digital distribution platforms for prepaid voucher purchases.
South Africa MNO - MVNO Market Competitive Landscape
The competitive structure tilts toward infrastructure-anchored consolidation among licensed MNOs, with MVNOs occupying dependent wholesale positions. Three dominant players control licensed spectrum and radio assets, creating tiered access for virtual operators leasing capacity. Strategic archetypes include full-service MNOs with infrastructure depth, banking-integrated MVNOs leveraging financial service ecosystems, and data-only specialists competing on price per gigabyte. Dominant competitive moves center on spectrum auction positioning and wholesale rate negotiations under ICASA oversight.
Within the infrastructure-anchored tier, Vodacom and MTN South Africa represent full-service MNO archetypes with spectrum ownership and national coverage obligations. Telkom occupies a hybrid position with fixed-line heritage and mobile infrastructure assets. Among MVNO specialists, FNB Connect exemplifies financial-service convergence, Rain anchors the data-only proposition segment, and Cell C represents a challenger MNO transitioning toward wholesale-dependent models. These named entities illustrate how competitive positioning stratifies across infrastructure ownership, service bundling, and customer segment focus without requiring specific operational claims about each company's current strategic initiatives.
| Leading Market Players |
|---|
| Telkom |
| Melon |
| Vodacom |
| Standard Bank Connect |
| FNB Connect |
| MTN South Africa |
| Rain |
| PnP Mobile |
| Cell C |
| Others |
Value Network & Pricing Analysis
Network engineering talent concentration in Gauteng's Johannesburg-Pretoria corridor drives labor-cost spreads between premium enterprise MVNOs and prepaid-focused virtual operators. ICASA's wholesale pricing transparency mandates compress MNO margins while forcing infrastructure owners to open network access at regulated rates, fundamentally restructuring how virtual operators construct tiered service offerings.
Pricing Analysis
Margin tightening in prepaid segments reflects ICASA's Consumer Protection Act disclosure requirements eliminating hidden out-of-bundle charges. Three-tier pricing structure across premium postpaid, standard hybrid, and economy prepaid levels stratifies by credit access and support intensity. Price differentiation traces to wholesale rate volatility in national roaming negotiations and infrastructure-dependent service reliability guarantees. Individual users in peri-urban informal settlements exhibit highest price sensitivity, while large corporations in Sandton financial district prioritize predictable billing over per-gigabyte rates.
Supply Chain Analysis
Spectrum licensing rests on ICASA's regulatory framework, equipment supply feeds from Chinese and European network infrastructure vendors, and wholesale capacity draws from three dominant MNOs controlling licensed radio assets. Raw material dependencies center on base station hardware, fiber backhaul components, and subscriber identity modules. Single-source vulnerability concentrates in host MNO national roaming agreements where wholesale rate renegotiations create input cost uncertainty. Distribution runs through retail outlets in township markets, online platforms with eSIM provisioning, and informal reseller channels penetrating informal settlements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectrum scarcity props pricing power for infrastructure owners while ICASA's wholesale mandates create dependent access economics for virtual operators, sustaining margin compression in leased-capacity business models.
For Market Incumbents: Acquire unlicensed spectrum holdings and small-cell deployment rights to deepen coverage differentiation against wholesale-dependent MVNOs. Vodacom and MTN South Africa should consolidate enterprise relationships through dedicated account management tiers before banking-integrated competitors like FNB Connect lock in Sandton financial district clients. Backward integration into fiber backhaul infrastructure reduces roaming cost exposure.
For New Entrants and Emerging Players: Direct-to-consumer digital channels enable eSIM-first launches with zero physical retail footprint, collapsing subscriber acquisition timelines against incumbent MNOs. Western Cape enterprise corridors present underpenetrated white space for dedicated MVNO solutions with service-level guarantees. Rain's data-only architecture demonstrates viable positioning for price-per-gigabyte competition without voice infrastructure investment.
For Investors and Strategic Acquirers: Re-rating potential sits with banking-integrated MVNOs given financial-service convergence creating sticky customer relationships beyond pure connectivity. Long-term viability favors operators with alternative revenue streams reducing wholesale cost pass-through dependency. Watch ICASA spectrum auction outcomes as inflection indicators for infrastructure valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Wholesale Rate Renegotiation | MVNOs securing cost-reflective terms under ICASA mandates improve margin sustainability against MNO pricing power. |
| eSIM Platform Launch | Digital-first provisioning eliminates physical distribution costs and accelerates subscriber activation timelines. |
| Banking Integration Partnership | FNB Connect demonstrates how financial-service bundling creates switching costs beyond connectivity pricing. |
| Enterprise SLA Development | Dedicated support tiers match MNO reliability guarantees for Johannesburg corporate procurement consolidation. |
| Spectrum Positioning | Auction participation determines long-term infrastructure economics and wholesale access leverage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Africa MNO-MVNO market assessment. Primary interviews with ICASA policy officers, MNO wholesale strategy leads, MVNO operations directors, and enterprise IT procurement managers in Johannesburg and Cape Town combined with bottom-up subscriber and revenue modeling. Secondary sources included ICASA annual reports, Competition Commission merger filings, operator financial disclosures, and spectrum auction documentation. Top-down macroeconomic validation cross-checked against mobile penetration statistics and enterprise connectivity expenditure surveys.
Segmentation-level granularity modeled service type, customer archetype, radio interface technology, and distribution channel across the projection horizon. Postpaid, prepaid, hybrid, and roaming categories combined with individual, small enterprise, large corporate, and government buyer segments. 4G, 5G, LTE, and GSM technology deployment curves informed capacity planning assumptions. CAGRs derived from subscriber growth trajectories, ARPU compression patterns, and wholesale cost evolution scenarios. Forecast inputs incorporated ICASA regulatory timeline probabilities and MNO infrastructure rollout commitments.
The model holds under stable wholesale pricing transparency enforcement; deviation in spectrum auction delays or roaming rate renegotiation failures would shift MVNO entry economics. Forecasts reflect assumptions about banking partnership stickiness and enterprise procurement consolidation velocity. Regulatory enforcement intensity, MNO infrastructure investment cycles, and digital distribution adoption curves constitute the primary revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Cloud Telephony Service Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Chile Telecom Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
5G Equipment Market
Telecommunications
Denmark ICT Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Thailand Telecom Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
IoT MVNO (Services) Market