
 Finland Telecom Market | 2026-2036
Finland Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Telecom Market Insights
Network infrastructure leasing revenue is fragmenting as cloud providers build proprietary fiber routes and enterprises adopt direct cloud connectivity. Nokia anchors its position through deep R&D intensity in Open RAN and optical transport systems. Elisa Oyj differentiates via vertical integration into submarine cable assets linking Finland to Central Europe. Telia Finland Oyj competes through nationwide 5G standalone coverage and fixed wireless access bundles.
Finland telecom encompasses wireline, wireless, and data communication services transmitting voice, video, and data across copper, fiber, and radio frequency infrastructure operating at frequencies from 700 MHz to 28 GHz and beyond. The sector serves residential consumers, enterprise operations, and public administration through subscription-based recurring revenue models. Fiber optic deployment leads capital allocation among technology segments as operators replace legacy DSL with XGS-PON and future 25G PON architectures. Mobile service revenue sustains the largest revenue pool though 5G enterprise applications represent the fastest expansion vector. Business customer segments command premium pricing relative to residential due to service-level agreements and managed security requirements.
Finnish Transport and Communications Agency Traficom governs spectrum licensing, net neutrality enforcement, and universal service obligations under national communications legislation. European Electronic Communications Code implementation through Finland's revised Laki sähköisen viestinnän palveluista shapes wholesale access pricing and infrastructure sharing mandates. National Cyber Security Centre Finland coordinates operator resilience standards and incident reporting protocols. Stakeholders must weigh Traficom's pending 6 GHz band allocation decisions against parallel investments in millimeter-wave small cell densification for industrial automation corridors.
Market Dynamics
Finland's telecom sector is reconfiguring around 5G standalone infrastructure as Traficom's spectrum policy forces operators to abandon non-standalone architectures and migrate core networks to cloud-native deployments by regulatory deadline.
Growth Catalysts
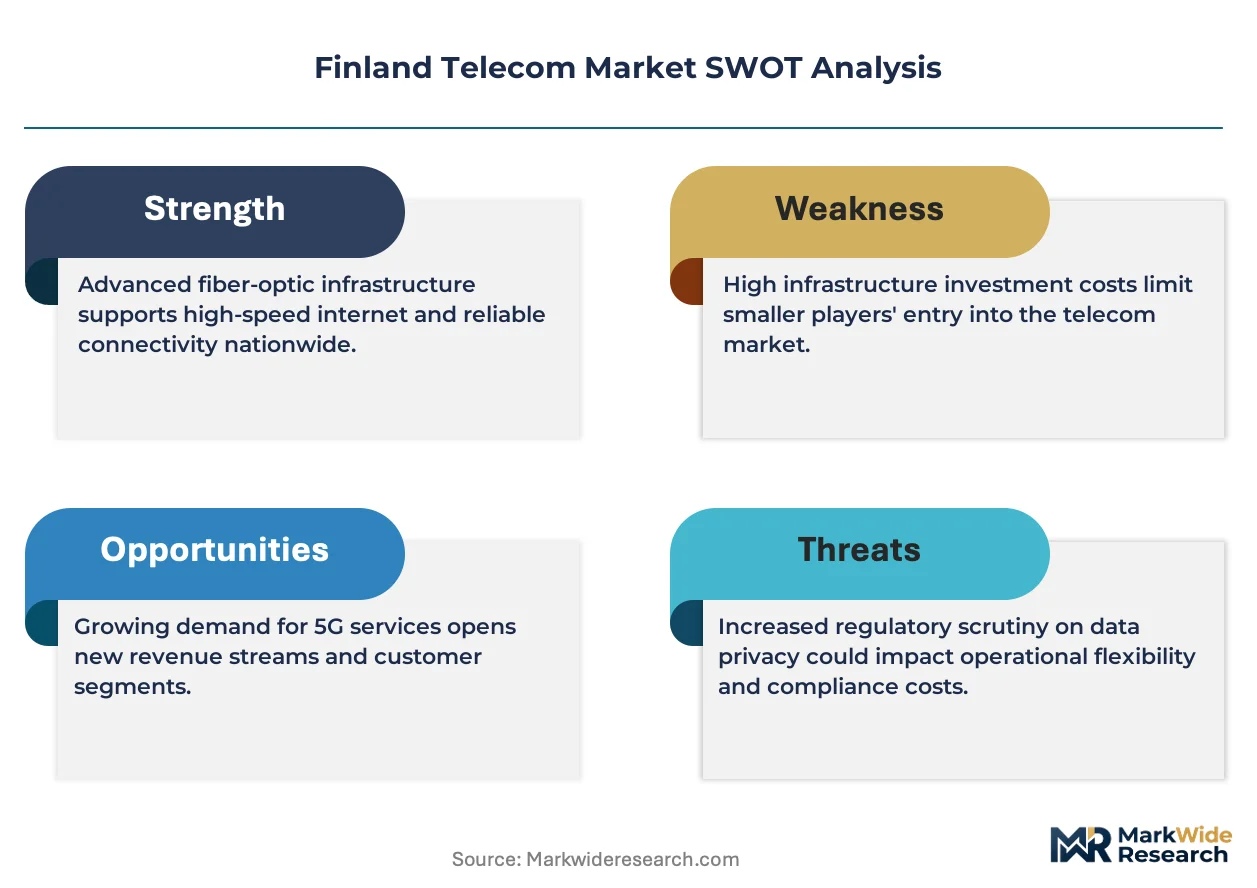
- Traficom's 5G spectrum framework:Mandatory 26 GHz and 3.5 GHz allocations for industrial automation corridors are accelerating private network deployments among manufacturing clusters in Tampere and Oulu.
- Data center concentration:Hyperscale facility investments in Helsinki metropolitan area are driving dark fiber demand and interconnection services from wholesale operators.
- Open RAN standardization:Nokia's R&D commitment to O-RAN-compliant interfaces is reducing vendor lock-in and lowering total cost of ownership for mobile network infrastructure.
Market Restraints
- Fiber deployment cost escalation:Permitting delays in densely forested regions and rock excavation requirements in granite substrate terrain are extending rural rollout timelines beyond economic viability thresholds.
- Submarine cable concentration:Finland's international connectivity depends on a limited set of Baltic Sea cable systems, creating single-point-of-failure exposure for enterprise cloud access.
- Copper legacy obligation:Universal service mandates under Laki sähköisen viestinnän palveluista require maintaining PSTN infrastructure despite accelerating fiber substitution, stranding operational expenditure.
Strategic Opportunities
- Eastern Finland penetration gap:North Karelia and Kainuu regions exhibit sub-50% fiber coverage versus 85% in southern provinces, presenting greenfield buildout potential for alternative network operators.
- 6 GHz Wi-Fi convergence:Traficom's pending 6 GHz authorization for unlicensed use enables enterprise private 5G and Wi-Fi 6E hybrid architectures for industrial IoT deployments.
- Carbon-neutral network claims:EU Green Deal alignment allows operators to monetize renewable-powered infrastructure through sustainability-linked enterprise contracts.
Industry Challenges
- Cloud-native engineering scarcity:Kubernetes and container orchestration expertise for 5G core virtualization remains concentrated among Helsinki-area talent pools, constraining nationwide deployment velocity.
- Multi-vendor integration complexity:Disaggregated RAN architectures from multiple suppliers are creating interoperability testing burdens and delaying commercial service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Telecom Market |
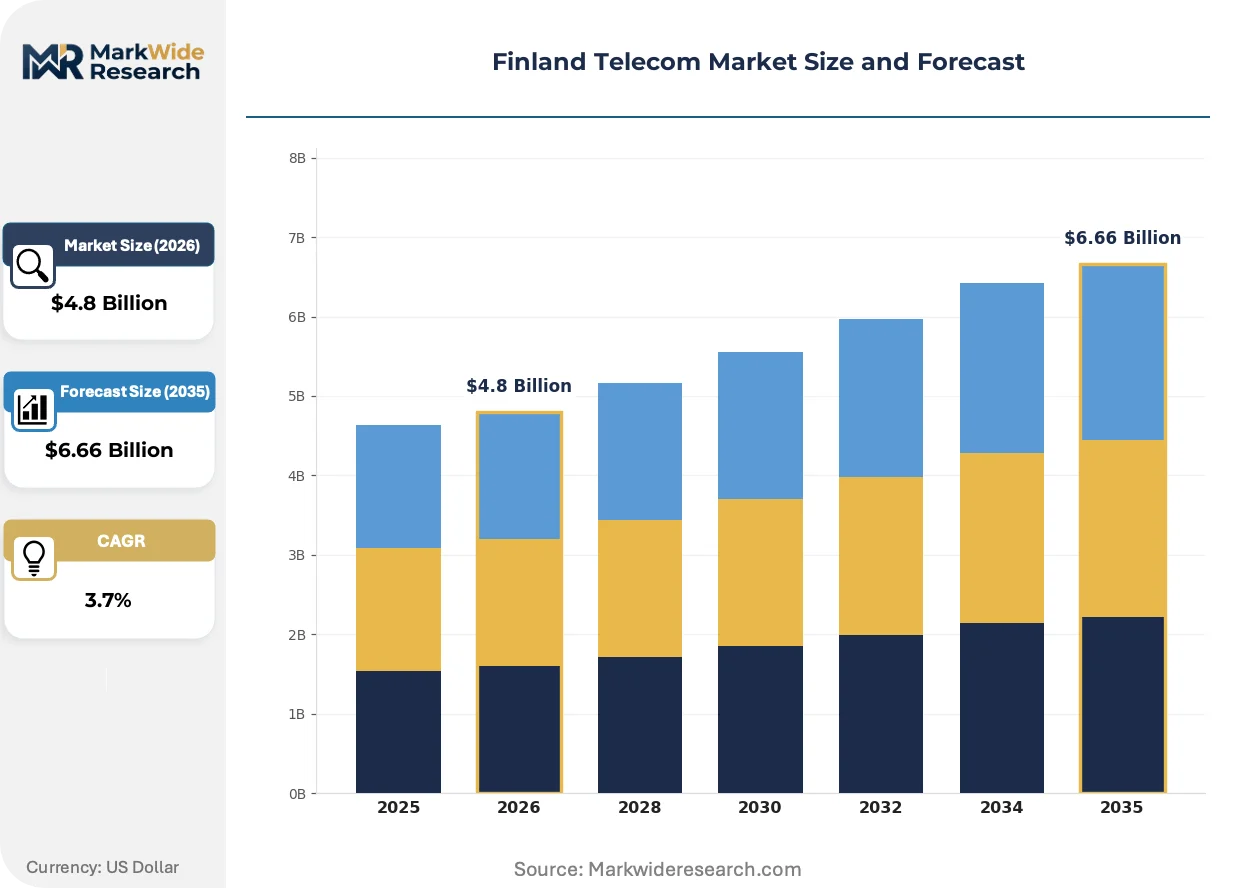
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Broadband, VoIP Technology: 4G LTE, 5G, Fiber Optic, DSL Customer Type: Residential, Business, Government, Enterprise Pricing Model: Subscription, Pay-As-You-Go, Bundled Services, Prepaid |
| Companies Covered | DNA Plc, Digita, Nokia, Teliasonera, Sonera, Elisa Oyj, Ficolo, Ålcom, Telia Finland Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Telecom Market Trends and Innovations
Finnish telecom infrastructure is converging toward software-defined architectures that separate control plane intelligence from physical transport layers, enabling programmable network services.
Network functions virtualization is virtualizing radio access and core network elements previously bound to proprietary hardware. Mobile operators including Elisa Oyj and Telia Finland Oyj are migrating 60% of network functions to containerized deployments by operational commitment. This shift is virtualizing capital intensity by substituting commercial off-the-shelf servers for purpose-built telecom equipment, compressing equipment vendor margins while expanding systems integrator roles.
Finland's implementation of the European Electronic Communications Code through revised Laki sähköisen viestinnän palveluista mandates infrastructure sharing and wholesale access pricing transparency. The legislation compels dominant operators to publish reference offers for dark fiber and bitstream access. Rural municipalities and alternative network builders are leveraging these provisions to accelerate last-mile competition in underserved postal code regions.
Enterprise procurement patterns are compressing contract durations from traditional five-year managed service agreements toward two-year subscription renewals with usage-based pricing tiers. Manufacturing and logistics verticals in the Helsinki-Turku corridor are unbundling connectivity from security and cloud access, selecting best-of-breed suppliers rather than single-source telecom relationships. This fragmentation is most pronounced among mid-market enterprises with 200-500 employees, where IT directors retain direct vendor negotiation authority.
Finland Telecom Market Segmentation
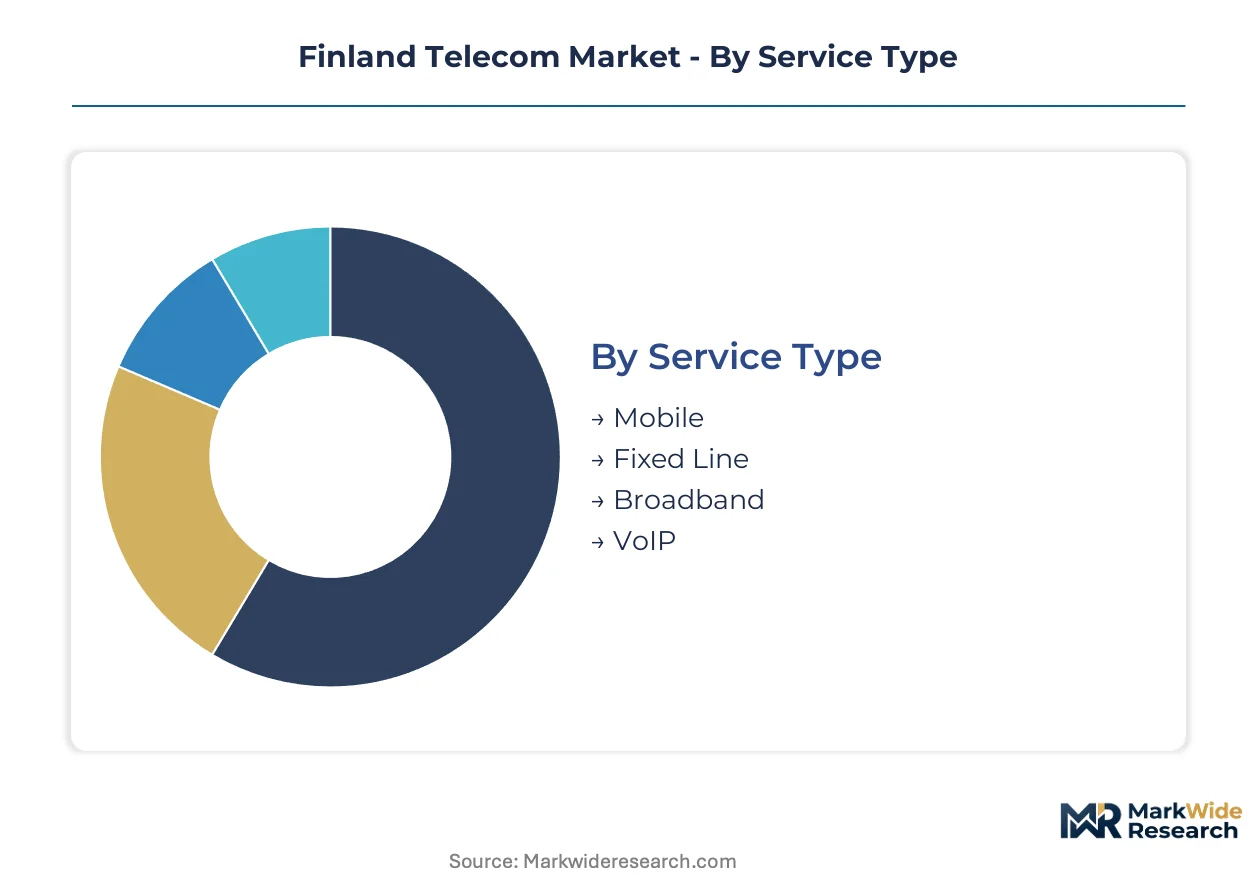
Finnish telecom operators structure pricing and network investments around distinct service tiers, technology generations, and customer accountability levels. Segmentation clarity reveals where capital allocation concentrates and where regulatory obligations distort commercial returns.
Service Type:
Cost tier differentiation separates subscription-based recurring revenue from transactional usage models across consumer and enterprise accounts.
- Mobile:Cellular voice and data services operating across 700 MHz to 28 GHz spectrum bands. Helsinki metropolitan area and Tampere corridor concentrate 5G enterprise demand driven by manufacturing automation requirements.
- Fixed Line:Traditional PSTN copper infrastructure delivering voice services under universal service mandates. Rural municipalities in North Karelia and Kainuu still depend on legacy infrastructure where fiber economics fail.
- Broadband:High-speed internet access via fiber, cable, or fixed wireless technologies. Residential demand clusters in southern provinces where XGS-PON deployment exceeds 85% coverage.
- VoIP:Packet-switched voice services replacing circuit-switched telephony in enterprise environments. Corporate headquarters in Espoo and Vantaa drive migration toward cloud-native unified communications.
Mobile holds installed capacity. Broadband is rotating up the share rankings.
Technology:
Network maturity stratifies capital intensity from legacy depreciation to greenfield deployment cycles.
- 5G:Fifth-generation mobile networks with standalone core architectures and network slicing capabilities. Traficom's spectrum mandates for 26 GHz and 3.5 GHz bands are accelerating industrial private network deployments in Oulu manufacturing clusters.
- Fiber Optic:Optical transport infrastructure spanning XGS-PON and emerging 25G PON standards. Granite substrate terrain in eastern Finland constrains trenching economics despite southern province density advantages.
- 4G LTE:Fourth-generation mobile technology carrying residual traffic during 5G migration. Rural coverage obligations maintain LTE as fallback where standalone 5G capex exceeds revenue thresholds.
- DSL:Digital subscriber line copper-based broadband facing accelerated substitution. Legacy universal service requirements strand operational expenditure on declining subscriber bases.
Fiber Optic commands deployment priority. 5G is climbing the fastest trajectory among mobile technologies.
Customer Type:
Accountability tier determines service level agreement complexity and pricing premium capture.
- Enterprise:Large organizations with 500+ employees requiring managed security and dedicated connectivity. Financial services and logistics verticals in the Helsinki-Turku corridor unbundle connectivity from cloud access.
- Business:Mid-market operations with 200-500 employees and direct IT procurement authority. Manufacturing facilities select best-of-breed suppliers rather than single-source telecom relationships.
- Government:Public administration entities with resilience and data sovereignty requirements. National Cyber Security Centre Finland coordinates incident reporting protocols across state networks.
- Residential:Household consumers purchasing standardized subscription bundles. Price sensitivity concentrates in urban apartments where multiple operators compete.
Enterprise holds contract value concentration. Business is rotating up the share rankings.
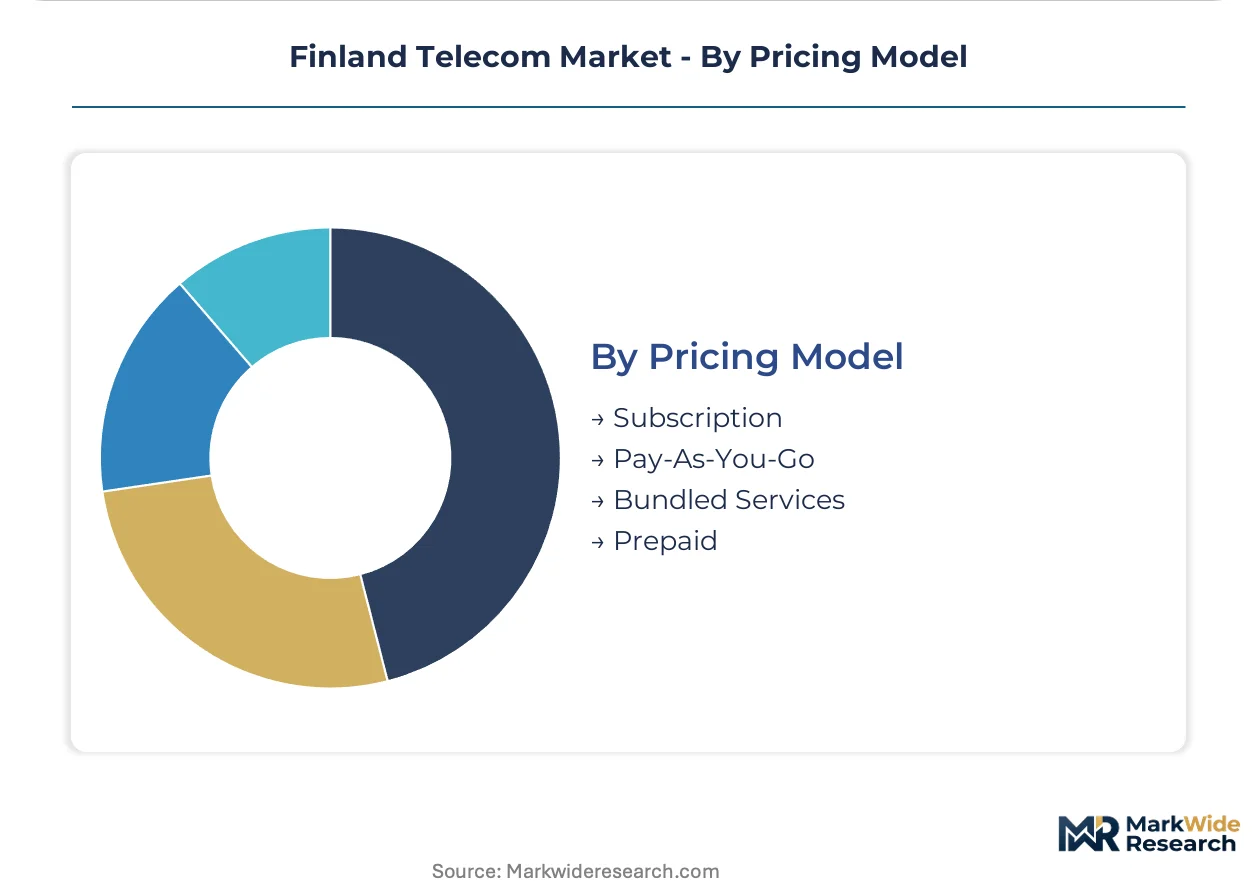
Pricing Model:
Revenue predictability separates committed subscription streams from variable consumption patterns.
- Subscription:Recurring monthly fees for fixed service tiers with committed bandwidth. Enterprise procurement is compressing contract durations from five-year agreements toward two-year renewals.
- Bundled Services:Combined mobile, fixed, and content offerings with cross-subsidized pricing. Telia Finland Oyj competes through nationwide 5G standalone coverage packaged with fixed wireless access.
- Prepaid:Advance payment for mobile voice and data without credit commitment. Student populations and temporary residents in university cities sustain this segment.
- Pay-As-You-Go:Usage-based metering without minimum commitment. IoT sensor deployments and machine-to-machine applications favor this model for variable connectivity needs.
Subscription holds revenue base stability. Bundled Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in southern provinces exhibit low price elasticity for fiber connectivity, while residential subscribers in eastern regions drive aggressive tariff competition among operators.
Helsinki Metropolitan Area
Hyperscale data center investments from international cloud providers anchor dark fiber demand across Espoo and Vantaa. Traficom's 5G spectrum mandates accelerate standalone core deployments. The Helsinki-Turku corridor concentrates enterprise unbundling trends where manufacturing verticals select best-of-breed suppliers.
Tampere Corridor
Industrial automation corridors generate private 5G network deployments among manufacturing clusters. National Cyber Security Centre Finland coordinates resilience standards for critical infrastructure operators. Oulu manufacturing clusters drive 26 GHz and 3.5 GHz spectrum utilization for machine-to-machine applications.
Southern Provinces
XGS-PON deployment exceeds 85% coverage, compressing DSL substitution timelines. Revised Laki sähköisen viestinnän palveluista mandates wholesale access pricing transparency for dominant operators. Urban apartments in densely populated zones sustain multiple operator competition and subscription bundle innovation.
Eastern Finland
North Karelia and Kainuu regions exhibit sub-50% fiber coverage, extending rural rollout timelines beyond economic viability thresholds. Universal service obligations under national communications legislation require maintaining PSTN infrastructure despite accelerating fiber substitution. Alternative network operators target greenfield buildout potential in underpenetrated postal code regions.
Åland Islands
Submarine cable connectivity dependence creates single-point-of-failure exposure for enterprise cloud access. Ålcom represents regional operator specialization in island-specific connectivity requirements. Maritime logistics and tourism verticals drive specialized fixed wireless access demand across the archipelago.
Finland Telecom Market Competitive Landscape
Capability concentration sits with infrastructure vendors; scale advantage sits with integrated service providers. The market structures around three tiers: equipment suppliers anchoring R&D intensity, national operators commanding subscriber bases, and alternative network builders targeting rural whitespace. Dominant competitive moves include spectrum portfolio optimization and submarine cable asset control.
Within the integrated operator tier, Elisa Oyj and Telia Finland Oyj represent national-scale service providers with infrastructure ownership positions. Nokia exemplifies the equipment vendor archetype through O-RAN standardization commitments. DNA Plc occupies a challenger position within the mobile and fixed-line convergence segment.
| Leading Market Players |
|---|
| DNA Plc |
| Digita |
| Nokia |
| Teliasonera |
| Sonera |
| Elisa Oyj |
| Ficolo |
| Ålcom |
| Telia Finland Oyj |
| Others |
Pricing and Supply Chain Analysis
Single-source submarine cable dependency for international bandwidth determines both enterprise pricing tier spreads and supply chain resilience investments across Finnish telecom infrastructure. Traficom's spectrum licensing timelines and Nokia's O-RAN equipment sourcing create dual chokepoints that compress margin structures while forcing geographic diversification in network hardware procurement.
Pricing Analysis
Managed service and security add-ons drive lifetime value capture beyond baseline connectivity subscriptions. Three-tier pricing structure across premium SLA-backed enterprise, standard business, and economy residential levels stratifies across fiber penetration density and latency guarantees. Pricing pressure stems from hyperscale cloud providers building proprietary dark fiber routes that bypass traditional wholesale tariffs. Residential subscribers in Helsinki metropolitan area exhibit highest price sensitivity due to multi-operator competition, while manufacturing clusters in Tampere corridor accept premium rates for private 5G slicing.
Supply Chain Analysis
EU dual-use technology export controls and US CHIPS Act restrictions limit advanced optical transport equipment flows into Nordic network builds. Hardware sourcing concentrates in China, Germany, and USA for radio units, core network servers, and submarine cable components respectively. Semiconductor content in 5G baseband units and routing silicon creates raw material exposure to Taiwan and South Korea fabrication capacity. Single-source vulnerability concentrates in submarine cable landing station equipment where Nokia holds dominant position. Distribution runs through systems integrator partnerships rather than direct operator procurement for cloud-native core deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finnish telecom operates as a regulatory-moat market where Traficom's spectrum scarcity and universal service mandates create entrenched barriers against price-based disruption. Switching costs for enterprise customers with embedded private 5G and fiber SLAs reinforce incumbent positioning.
For Market Incumbents: Harden submarine cable asset control through capacity reservations on Baltic Sea routes to neutralize cloud provider bypass threats. Consolidate Open RAN interoperability testing partnerships to accelerate multi-vendor deployment timelines and reduce Kubernetes talent scarcity constraints in Helsinki-area engineering pools. For New Entrants and Emerging Players: Eastern Finland's North Karelia and Kainuu fiber whitespace represents the most penetrable entry point given sub-50% coverage and stranded PSTN universal service obligations burdening incumbents. Municipal wholesale access mandates under revised Laki sähköisen viestinnän palveluista enable dark fiber leasing as anchor tenant strategy before retail subscriber acquisition. For Investors and Strategic Acquirers: Traficom's pending 6 GHz band authorization reshapes the acquisition landscape toward private network specialists with industrial IoT deployment capabilities. Five-to-ten year viability favors operators with captive submarine cable positions and renewable-powered data center adjacencies. Signal to monitor: hyperscale facility announcements in Helsinki metropolitan area as demand inflection proxy.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Capacity Expansion | Secures international bandwidth redundancy against Baltic Sea cable system single-point-of-failure exposure. |
| Open RAN Interoperability Certification | Reduces Nokia vendor lock-in and accelerates multi-supplier RAN deployment timelines for Elisa Oyj and Telia. |
| Eastern Finland Fiber Buildout | Captures greenfield subscriber growth in North Karelia and Kainuu where incumbent economics fail. |
| 6 GHz Private Network Authorization | Enables enterprise Wi-Fi 6E and 5G hybrid architectures for Tampere manufacturing automation corridors. |
| Renewable Energy Infrastructure Integration | Monetizes EU Green Deal alignment through sustainability-linked enterprise contract premiums. |
Research Methodology
Desk research of Traficom spectrum allocation records, European Electronic Communications Code implementation documents, and operator capex disclosures preceded structured interviews with network engineering directors, wholesale fiber procurement managers, and municipal broadband coordinators. Secondary validation drew from National Cyber Security Centre Finland resilience reports, hyperscale data center development databases, and submarine cable landing station filings. Bottom-up subscriber and traffic volume estimates triangulated against top-down market value reconstructions.
Assumptions held fixed include Traficom's regulatory timeline adherence, Nokia's O-RAN R&D commitment continuity, and EU Green Deal carbon neutrality targets for network infrastructure. The analytical framework modeled service type, technology generation, customer accountability tier, and geographic fiber penetration density across the analysis window. CAGRs derived from segment-level revenue trajectory synthesis incorporating enterprise cloud migration velocity and residential bundle substitution patterns. Forecast inputs included hyperscale facility pipeline data and industrial automation corridor 5G adoption curves.
Practitioners should monitor Traficom spectrum auction timing, hyperscale cloud provider fiber self-build announcements, and Open RAN interoperability certification milestones for early signals. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and equipment vendor supply continuity. Material shifts in EU export control scope or Baltic Sea cable system availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
SIP Trunking Services Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
GPON Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
DWDM System Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
DECT System Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
5G Radio Access Network Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Sri Lanka Telecom Tower Market