
 Standalone 5G Network Market | 2026-2036
Standalone 5G Network Market Size, Share, and Industry Trends Forecast 2026-2036
Standalone 5G Network Market Analytics
Capital-intensity divergence between cloud-native software stacks and legacy hardware-dependent architectures is bifurcating competitive dynamics in the Standalone 5G Network Market. Telefonaktiebolaget LM Ericsson leverages its cloud RAN portfolio to reduce operator total cost of ownership while sustaining R&D intensity in automated network slicing. Nokia Corporation anchors its position through end-to-end private wireless solutions that compete directly against IT-centric vendors in enterprise verticals.
Standalone 5G denotes a cellular architecture built upon a 5G New Radio interface paired with a cloud-native 5G Core, operating independently of 4G LTE control-plane dependencies and enabling network slicing with sub-10 millisecond latency guarantees for mission-critical applications. Sub-6 GHz deployments currently dominate commercial rollouts due to favorable propagation characteristics and existing spectrum availability, while mmWave infrastructure concentrates in dense urban hotspots and industrial campuses where beamforming compensates for limited range. Among deployment models, private networks attract disproportionate investment from manufacturing and logistics sectors seeking deterministic connectivity without public network contention.
The FCC governs spectrum allocation and equipment authorization in the United States, while ETSI and 3GPP shape interoperability standards that determine vendor market access across European and Asian jurisdictions. The FCC's recent mid-band auction reforms and the EU's Radio Equipment Directive collectively accelerate infrastructure deployment timelines by harmonizing certification pathways. Stakeholders must monitor spectrum refarming decisions and open RAN interoperability mandates as these policy levers will determine vendor consolidation patterns and enterprise procurement flexibility.
Market Dynamics
Cloud-native 5G Core architectures are compressing deployment timelines and fragmenting vendor hierarchies as operators abandon legacy hardware dependencies for containerized software stacks.
Growth Catalysts
- Industrial Automation:Manufacturing facilities in Germany leverage BNetzA campus network licenses to replace wired deterministic control with wireless private 5G, eliminating cable maintenance and reconfiguration costs.
- FCC Mid-Band Auctions:The United States spectrum framework unlocks 3.45 GHz and 2.5 GHz licenses that lower capital barriers for regional carriers and private network operators entering enterprise verticals.
- Network Slicing:Cloud-native core implementations enable sub-10 millisecond latency guarantees for mission-critical applications in autonomous logistics and remote surgery.
Market Restraints
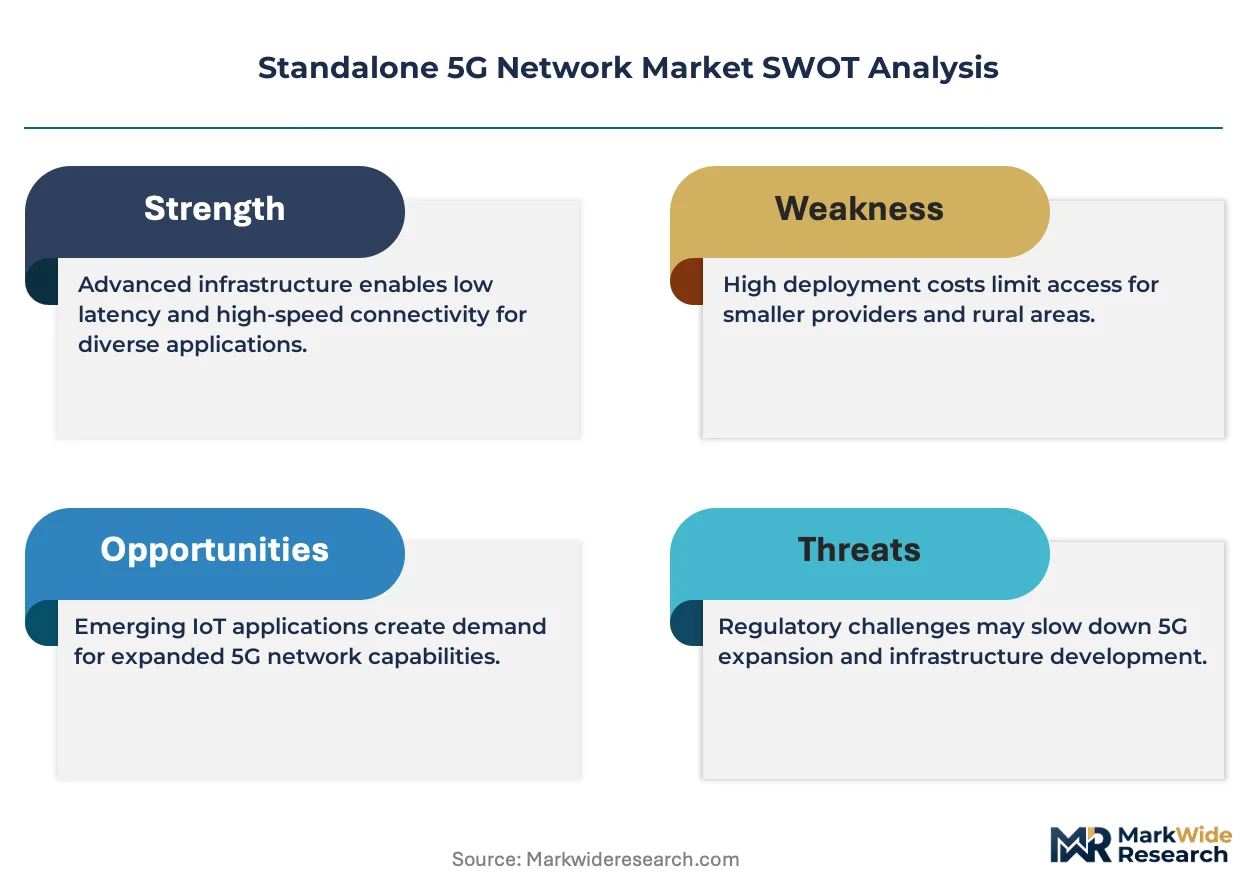
- Semiconductor Supply Concentration:Advanced baseband processor fabrication concentrates among Taiwan-based foundries, exposing infrastructure timelines to geopolitical disruption and capacity constraints.
- Radio Unit Cost Structure:Massive MIMO antenna arrays and beamforming chipsets constitute 40-50% of radio access network capex, compressing margins for price-sensitive deployments.
- ITU-R Spectrum Harmonization Delays:Divergent national band plans for mmWave and mid-band allocations force vendors to maintain multiple hardware variants, inflating R&D overhead.
Strategic Opportunities
- Open RAN Interoperability Mandates:The European Union's push for vendor-neutral interfaces creates procurement flexibility for operators seeking to disaggregate radio and baseband suppliers.
- Smart Agriculture:Brazil's agribusiness sector presents underpenetrated demand for private 5G networks enabling precision irrigation and autonomous harvesting across vast plantation geographies.
- Edge Computing Convergence:Integration of multi-access edge computing with standalone 5G cores allows hyperscalers to offer distributed cloud services with guaranteed latency for industrial IoT.
Industry Challenges
- Container Orchestration Expertise Gap:Mobile network operators face acute shortages of Kubernetes and cloud-native infrastructure engineers capable of managing distributed 5G Core deployments.
- Legacy Integration Complexity:Enterprises with existing Wi-Fi 6 and LTE-M installations encounter protocol friction and handoff management issues when overlaying standalone 5G for critical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standalone 5G Network Market |
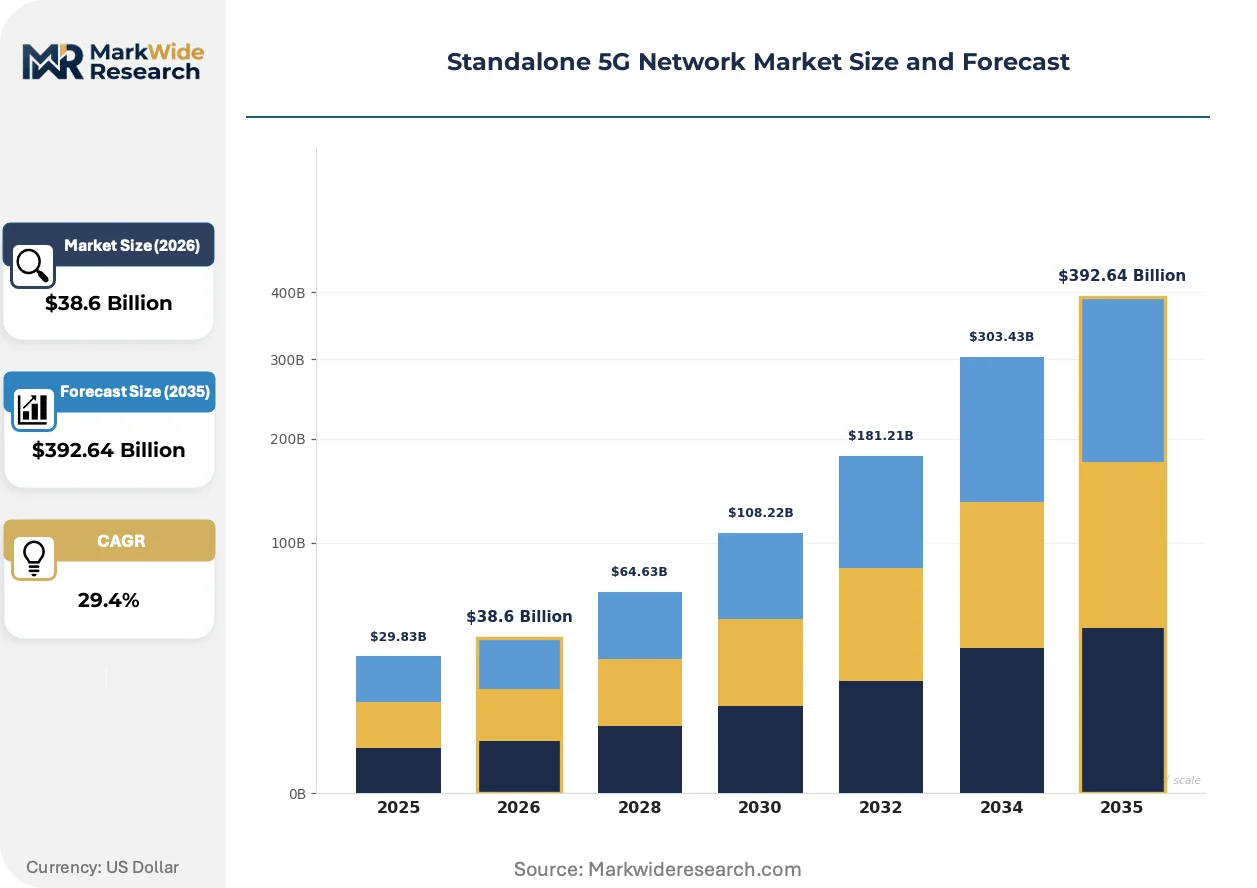
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $392.64 Billion |
| CAGR (2026 – 2036) | 29.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: MmWave, Sub-6 GHz, Massive MIMO, Beamforming Application: Smart Cities, Autonomous Vehicles, Industrial Automation, Telemedicine End User: Telecom Operators, Enterprises, Government, Healthcare Deployment Model: Private Network, Public Network, Hybrid Network, Site-based Infrastructure |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Nokia Corporation, Huawei Technologies Co., Ltd., Samsung Electronics Co., Ltd., ZTE Corporation, AT&T Inc., Verizon Communications, Inc., Cisco Systems, Inc., Vodafone Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standalone 5G Network Market Evolving Landscape
Deterministic wireless protocols are eroding the dominance of wired industrial Ethernet as factories prioritize flexibility over fixed infrastructure investments.
Intelligent radio units with embedded AI accelerators are supplanting conventional remote radio heads in industrial deployments. German automotive manufacturers adopt these units for real-time quality inspection and robotic coordination. The shift compresses hardware procurement cycles from multi-year vendor lock-in toward modular, software-upgradable platforms.
The EU AI Act imposes transparency requirements on automated network optimization algorithms deployed within 5G cores. Infrastructure vendors must now document training data provenance and decision logic for slicing resource allocation. European operators are responding by establishing AI governance committees and renegotiating supplier liability terms.
Enterprise procurement teams now demand outcome-based connectivity contracts with uptime and latency service-level agreements rather than capital-intensive network ownership. Manufacturing buyers in Japan and South Korea lead this transition, pressuring vendors to offer network-as-a-service models with guaranteed performance metrics. Equipment suppliers respond by forming captive financing arms and operational partnerships with systems integrators.
Standalone 5G Network Market Segmentation
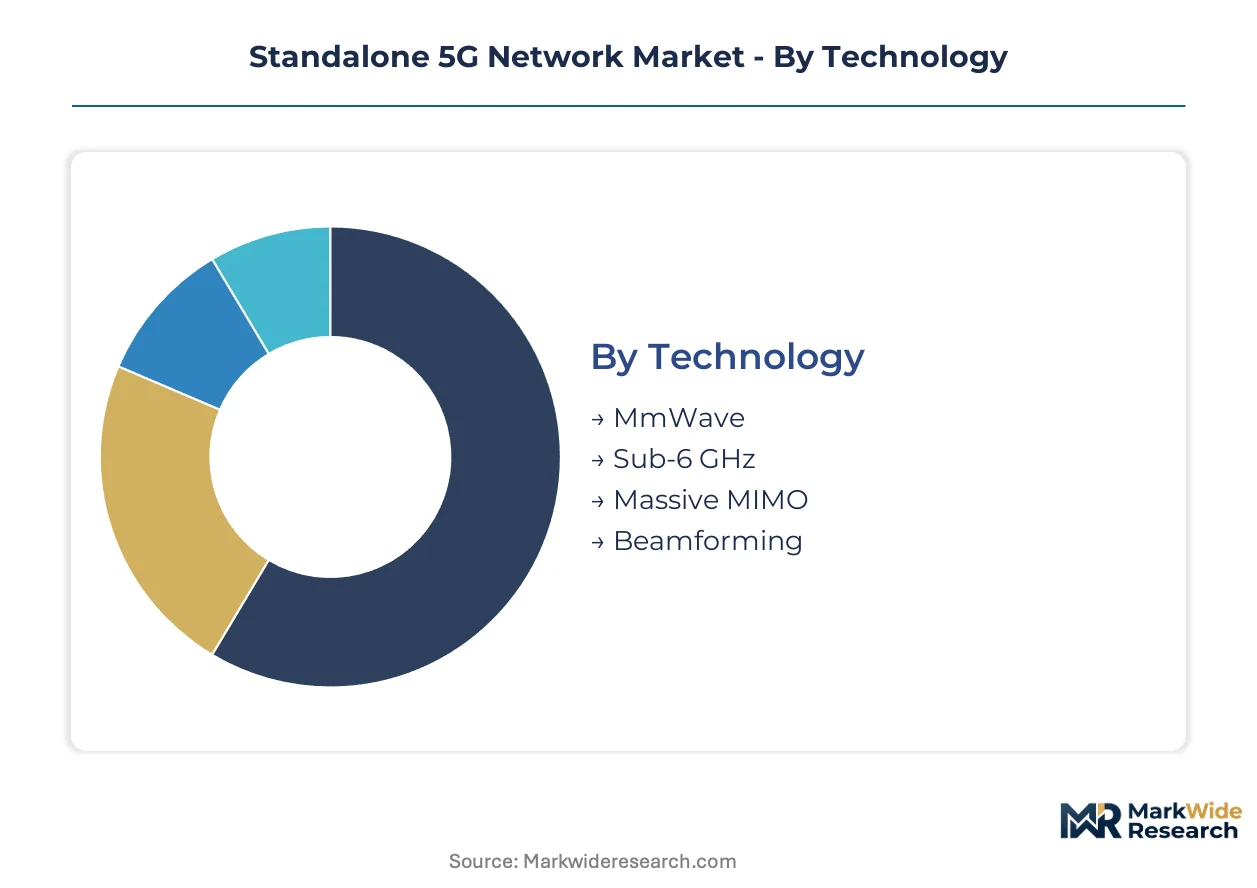
Standalone 5G architectures fragment across multiple technical and commercial dimensions, with regulatory frameworks determining which deployment models achieve scale in specific jurisdictions. Understanding these segment boundaries clarifies where infrastructure investments concentrate and how vendor strategies must adapt to heterogeneous demand patterns.
Technology:
FCC spectrum allocations and ETSI harmonization decisions create divergent technology adoption curves across national markets, with mid-band availability directly shaping Sub-6 GHz deployment velocity.
- MmWave:Millimeter-wave systems operate above 24 GHz with narrow beamwidths enabling multi-gigabit throughput in dense environments. German automotive manufacturers deploy MmWave for real-time robotic coordination in Stuttgart and Munich assembly plants, though limited range constrains outdoor coverage economics.
- Sub-6 GHz:Mid-band spectrum between 1 GHz and 6 GHz delivers balanced propagation and capacity for wide-area coverage. United States regional carriers leverage FCC 3.45 GHz licenses to build cost-efficient rural networks, avoiding the capital intensity of dense small-cell grids.
- Massive MIMO:64T64R antenna arrays multiply spectral efficiency through spatial multiplexing. Japanese operators deploy these systems in Tokyo and Osaka for enhanced mobile broadband.
- Beamforming:Dynamic beam steering algorithms concentrate radiated energy toward user equipment. South Korean infrastructure incorporates beamforming for stadium and transportation hub coverage.
Established volume favors Sub-6 GHz; emerging adoption favors MmWave in industrial campus configurations.
Application:
End-use requirements for latency tolerance and reliability grade determine which applications justify standalone core investments versus non-standalone alternatives.
- Industrial Automation:Deterministic wireless control replaces wired Ethernet for programmable logic controller communication. German factories under BNetzA campus licenses achieve sub-10 millisecond latency for robotic synchronization, eliminating cable maintenance costs.
- Autonomous Vehicles:Vehicle-to-everything communication demands ultra-reliable low-latency links for collision avoidance and platooning. Michigan and Arizona test corridors deploy standalone 5G for autonomous truck coordination.
- Smart Cities:Integrated sensor networks for traffic management and environmental monitoring consume moderate bandwidth with relaxed latency requirements. Barcelona and Singapore deploy these for urban optimization.
- Telemedicine:Remote surgical consultation and diagnostic imaging transmission require guaranteed bandwidth without mission-critical control-loop specifications. Mayo Clinic and Cleveland Clinic pilot these for rural specialist access.
Industrial Automation captures the steepest expansion trajectory as manufacturing verticals displace legacy connectivity.
End User:
Procurement authority and technical sophistication create distinct customer segments with diverging contract structures and performance expectations.
- Telecom Operators:Licensed spectrum holders building consumer and enterprise service portfolios. Verizon and Deutsche Telekom drive volume through nationwide coverage mandates.
- Enterprises:Manufacturing, logistics, and extraction companies acquiring private spectrum or leasing network slices. BASF and BMW operate captive 5G networks under German local licensing.
- Government:Defense and public safety agencies requiring sovereign infrastructure with security certification. Pentagon facilities mandate standalone cores for classified communications.
- Healthcare:Hospital systems and research institutions prioritizing guaranteed connectivity for clinical workflows. Cleveland Clinic deploys private 5G for surgical robot telemetry.
Telecom Operators dominate current infrastructure procurement; Enterprises represent the fastest-climbing customer category as private network licensing expands.
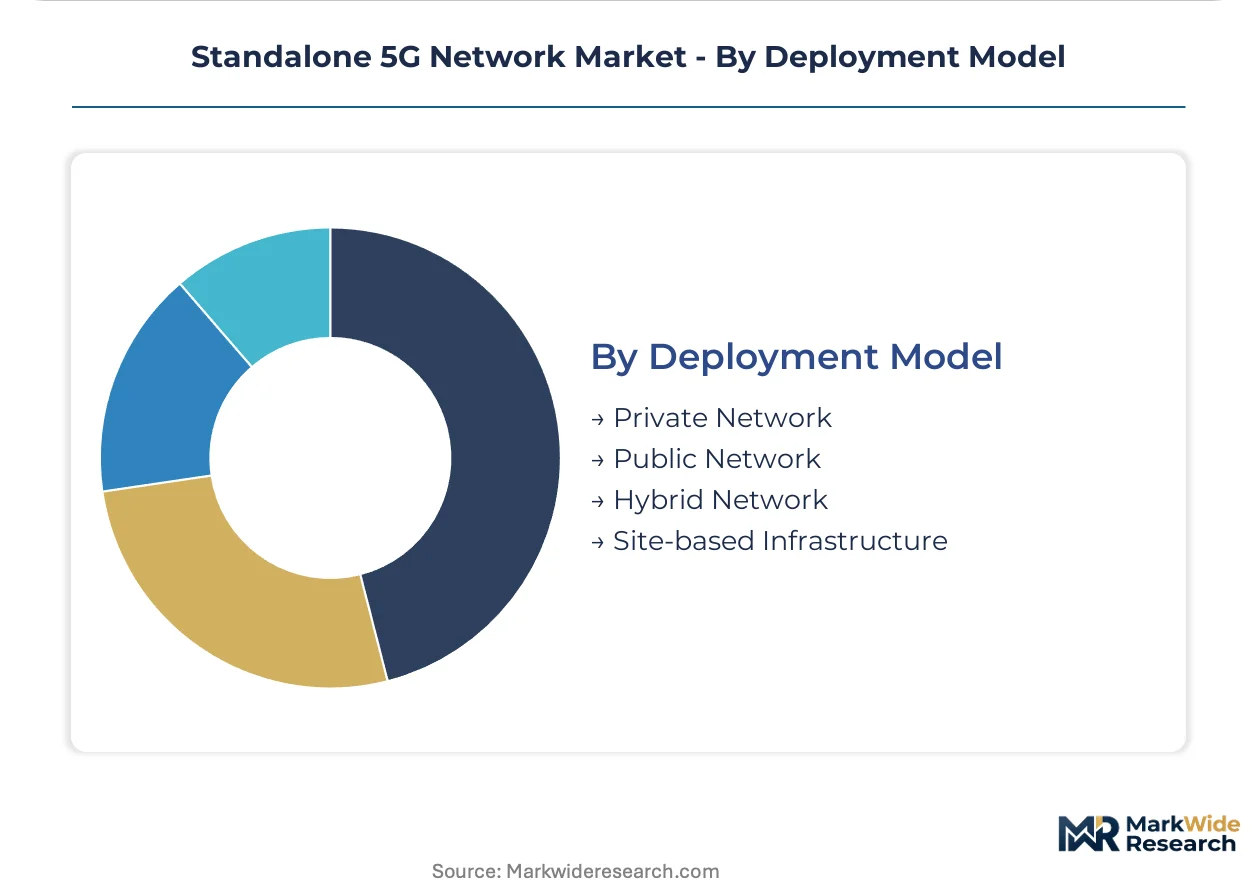
Deployment Model:
Capital structure and operational responsibility allocation determine which deployment models align with specific risk tolerances and technical capabilities.
- Private Network:Captive infrastructure with dedicated spectrum and isolated core functions. Nucor Steel and John Deere operate these for deterministic industrial control.
- Public Network:Shared infrastructure serving multiple tenants under standard service level agreements. T-Mobile and Vodafone build these for mass-market coverage.
- Hybrid Network:Segregated slices atop shared physical infrastructure combining cost efficiency with isolation guarantees. Siemens deploys these for factory-floor separation from administrative traffic.
- Site-based Infrastructure:Temporary or modular deployments for events, construction, or emergency response. Olympic venues and disaster recovery operations utilize these.
Private Network deployments gain share fastest in manufacturing verticals; Public Network retains volume leadership in consumer broadband.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where BNetzA campus licenses command premium deployment economics, while United States operators exploit FCC mid-band auctions to compress entry costs for regional carriers.
United States
Regional carriers and private network operators drive demand through FCC 3.45 GHz and 2.5 GHz license acquisitions. The FCC's mid-band auction framework lowers capital barriers for enterprise vertical entry. Michigan and Arizona test corridors deploy standalone 5G for autonomous vehicle coordination.
Germany
Automotive and chemical manufacturers replace wired deterministic control with wireless private 5G under BNetzA campus network licenses. The BNetzA regulatory regime supports factory-local deployments through dedicated spectrum allocation. Stuttgart and Munich assembly plants deploy MmWave for real-time robotic coordination.
China
Industrial IoT and smart manufacturing applications accelerate core network investments. The MIIT governs spectrum allocation and equipment certification for domestic infrastructure deployment. Yangtze River Delta manufacturing clusters integrate standalone 5G for automated quality inspection systems.
Japan
Mobile operators deploy Massive MIMO systems for enhanced mobile broadband in dense urban corridors. METI coordinates industrial digitalization initiatives that prioritize wireless factory automation. Tokyo and Osaka infrastructure incorporates beamforming for stadium and transportation hub coverage.
South Korea
Enterprise procurement teams demand outcome-based connectivity contracts with guaranteed latency service-level agreements. The national regulator shapes spectrum policy for industrial IoT expansion. Manufacturing buyers in Seoul Capital Area lead the transition toward network-as-a-service models.
Standalone 5G Network Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where cloud-native software stacks challenge legacy hardware-dependent architectures. The vendor base concentrates among integrated infrastructure providers and disaggregated component specialists. Two strategic archetypes dominate: end-to-end platform vendors competing for operator core contracts, and enterprise-focused private network specialists targeting vertical automation. Competitive moves center on cloud RAN portfolio expansion and automated network slicing capability development.
Within the integrated infrastructure tier, Telefonaktiebolaget LM Ericsson and Nokia Corporation exemplify contrasting strategic positioning. Ericsson leverages its cloud RAN portfolio to reduce operator total cost of ownership, while Nokia anchors its position through end-to-end private wireless solutions that compete directly against IT-centric vendors in enterprise verticals. Samsung Electronics Co., Ltd. occupies a position bridging consumer device integration with infrastructure supply.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Huawei Technologies Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| AT&T Inc. |
| Verizon Communications, Inc. |
| Cisco Systems, Inc. |
| Vodafone Group Plc |
| Others |
Value Network & Pricing Analysis
Capacity-reservation agreements with Taiwan-based foundries lock in baseband processor allocation while fixing radio unit costs for infrastructure vendors navigating semiconductor volatility. These contracts bind pricing visibility to supply security across the 5G equipment value chain.
Pricing Analysis
The customization-premium spread between standard radio units and configured-to-order private network cores reaches three-to-one multiples. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the standard tier intensifies because Chinese vendors are flooding mid-band massive MIMO markets. Enterprise buyers in Germany exhibit lowest price sensitivity due to BNetzA license scarcity, while United States regional carriers face acute margin pressure.
Supply Chain Analysis
Strategic-stockpile preferences dominate baseband processor procurement as vendors buffer against Taiwan Semiconductor Manufacturing Company capacity constraints. Advanced semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. Radio unit assembly draws from gallium nitride substrates, high-frequency laminates, and precision antenna substrates. Single-source vulnerability in 7-nanometer baseband chip production threatens infrastructure deployment timelines. Distribution runs through direct OEM relationships with telecom operators and systems integrators for enterprise verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Standalone 5G sits in early-cycle expansion as industrial automation accelerates displacement of wired Ethernet in manufacturing facilities. Private network licensing regimes in Germany and the United States create structural tailwinds for infrastructure demand.
For Market Incumbents: Secure cloud-native core certification pathways before Open RAN interoperability mandates fragment procurement. Deepen backward integration into antenna array manufacturing to defend margins against radio unit cost inflation. Prioritize Kubernetes talent acquisition to close the container orchestration expertise gap threatening deployment timelines. For New Entrants and Emerging Players: Differentiate on outcome-based network-as-a-service models with guaranteed latency SLAs rather than capital-intensive hardware sales. Target Brazilian agribusiness as the most penetrable vertical, where precision irrigation and autonomous harvesting demand remains underdeveloped. Pursue go-to-market partnerships with systems integrators possessing existing manufacturing relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among private network operators offering managed slicing services to enterprise verticals. Long-term viability favors vendors with software-upgradable radio platforms over hardware-locked architectures. Watch Open RAN interoperability mandate implementation timelines as the critical inflection signal for vendor consolidation patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Certification | ETSI and 3GPP compliance unlocks European operator procurement and enterprise vertical access. |
| Open RAN Interoperability Investment | EU vendor-neutral interface mandates create procurement flexibility and disaggregation opportunities. |
| Private Network Systems Integration | Captive operational partnerships with manufacturing clients secure recurring managed service revenue. |
| Edge Computing Convergence | Multi-access edge computing integration enables hyperscaler distributed cloud service offerings. |
| AI Governance Framework Development | EU AI Act compliance for automated network optimization algorithms mitigates supplier liability exposure. |
Research Methodology
Cross-validation between infrastructure vendor disclosures and regulatory filing databases anchors the qualitative findings. Primary interviews with network planning executives at mobile operators, private spectrum procurement leads at manufacturing enterprises, and cloud RAN engineering directors inform demand segmentation. Secondary sources include FCC auction records, ETSI standardization documents, BNetzA license registries, and 3GPP technical specifications. Bottom-up deployment tallies triangulate against top-down infrastructure spending estimates.
Sensitivity analysis around spectrum auction timing and industrial automation penetration rates tests forecast robustness. The analytical framework segments by technology, application, end user, and deployment model across the projection horizon. CAGRs derive from logistic diffusion curves fitted to historical cellular generation transitions. Key inputs include baseband processor foundry capacity expansion schedules and national private network licensing velocity.
Material uncertainties — geopolitical disruption to Taiwan-based semiconductor fabrication and divergent national mmWave band plans — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory harmonization progress and enterprise procurement team technical sophistication. Revision becomes warranted when Open RAN interoperability mandate enforcement crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
IP Centrex Platforms Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Utility Communications Market
Telecommunications
Voice Communication Control System Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
5G in Defense Market
Telecommunications
Spain ICT Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Managed M2M Services Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Brazil Telecom Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Cambodia Telecom Tower Market