
 Autonomous BVLOS Drones Market | 2026-2036
Autonomous BVLOS Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous BVLOS Drones Market Outlook
Certified-flight-grade autonomy is redrawing competitive boundaries in unmanned aerial systems. Skydio leverages advanced computer vision stacks to dominate close-quarters industrial inspection missions. General Atomics Aeronautical Systems, Inc. anchors defense and border surveillance portfolios with extended-endurance fixed-wing platforms. Zipline International Inc. specializes in precision delivery logistics across distributed healthcare networks in challenging terrain.
Autonomous BVLOS drones operate without continuous human visual contact, utilizing redundant GPS navigation, onboard AI algorithms, and detect-and-avoid collision systems to execute pre-programmed missions beyond operator sight range, primarily for commercial payload delivery, infrastructure monitoring, and aerial surveillance where human piloting proves impractical or cost-prohibitive. Fixed-wing architectures sustain longest endurance for corridor inspection and mapping missions, while hybrid configurations capture expanding margin pools as operators demand vertical takeoff flexibility combined with efficient cruise performance. Delivery services and surveillance use cases attract disproportionate technology investment as logistics providers and government agencies validate operational reliability at scale.
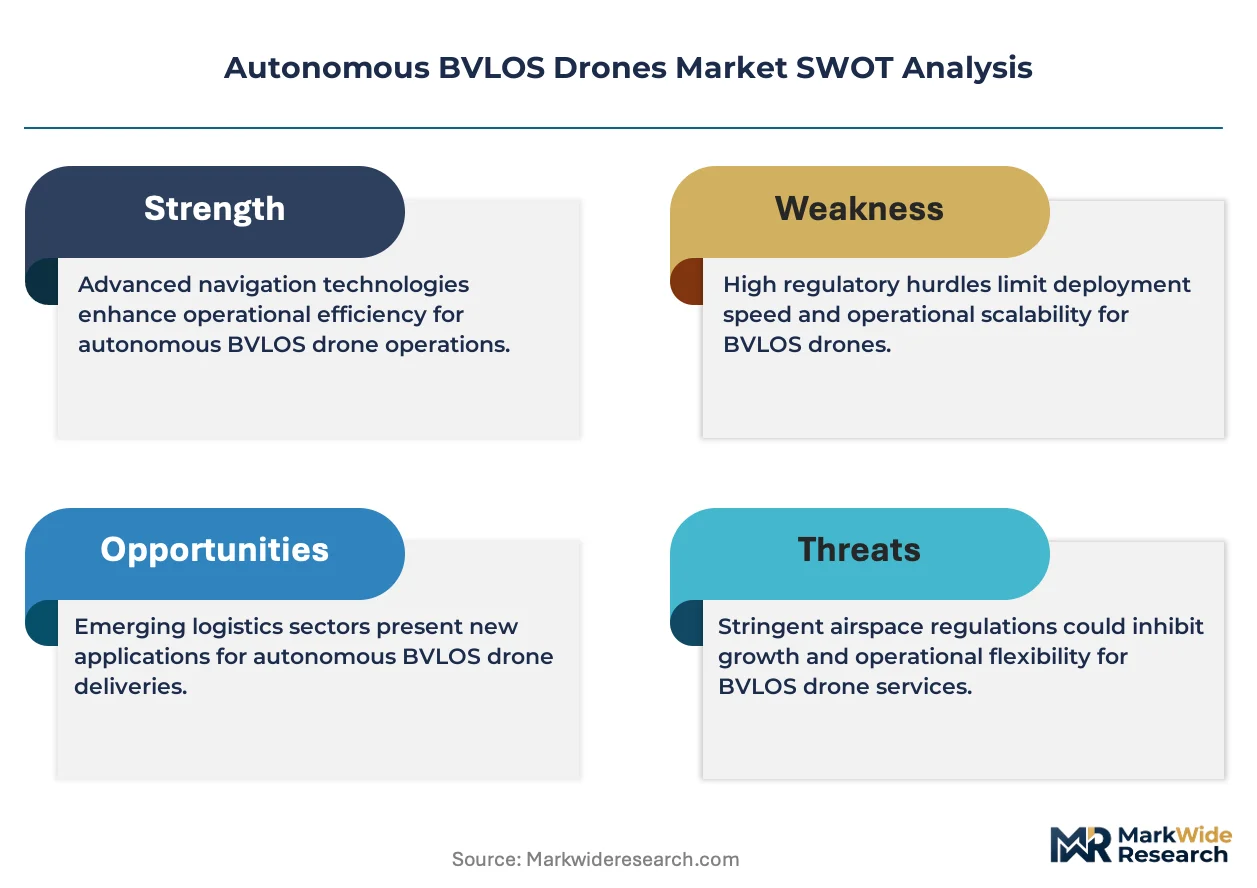
The FAA's Part 107 waiver system and emerging Remote ID mandates shape product certification pathways and fleet deployment timelines for operators seeking US airspace access, while EASA's specific category framework and EU drone regulation harmonize cross-border BVLOS standards across European member states. Stakeholders must monitor evolving airspace integration policies and operator certification requirements as regulatory clarity determines which technology platforms achieve commercial scalability first.
Market Dynamics
Certified-flight-grade autonomy stacks are redrawing competitive boundaries as FAA Part 107 waivers and EASA specific-category certifications progressively unlock commercial airspace access, forcing hardware manufacturers to prioritize detect-and-avoid systems over raw flight endurance specifications.
Growth Catalysts
- Remote ID mandates:The FAA's Remote ID requirements accelerate fleet modernization cycles as operators replace legacy unregistered aircraft with compliant platforms to maintain US airspace access.
- Energy corridor inspections:Transmission line operators across Texas, California, and the Mountain West states deploy fixed-wing BVLOS systems to monitor thousands of miles of infrastructure with minimal ground crew.
- Computer vision convergence:Onboard AI-powered obstacle detection enables safe navigation in GPS-denied environments, expanding operational envelopes into urban canyons and dense forest canopy.
Market Restraints
- Lithium-polymer battery cost volatility:Raw material price swings for cobalt and nickel directly compress gross margins on electric propulsion systems, particularly affecting multirotor platforms with high cell counts.
- Sensor supply concentration:Production of military-grade IMUs and precision GPS modules clusters among a handful of US and European defense contractors, creating single-source vulnerability for certified autonomy stacks.
- Airspace coordination fragmentation:Inconsistent waiver processing timelines across FAA regional offices delay commercial deployment schedules and inflate pre-revenue operating costs.
Strategic Opportunities
- Brazilian agribusiness expansion:Large-scale soy and sugarcane cooperatives in Mato Grosso and São Paulo states present untapped demand for crop monitoring and precision spraying across million-hectare estates.
- EU drone regulation harmonization:EASA's standardized specific-category framework enables cross-border fleet operations, reducing certification duplication costs for operators serving multiple member states.
- 5G network slicing integration:Low-latency command-and-control links via dedicated network slices allow beyond-radio-line-of-sight operations without satellite dependency, opening maritime and offshore energy applications.
Industry Challenges
- Autonomy software certification backlog:FAA and EASA qualified personnel shortages extend type certification timelines for new detect-and-avoid algorithms, delaying product launches by 18-24 months.
- Legacy radar integration:Air traffic management systems at regional airports require expensive hardware upgrades to distinguish cooperative drones from non-cooperative targets, creating deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous BVLOS Drones Market |
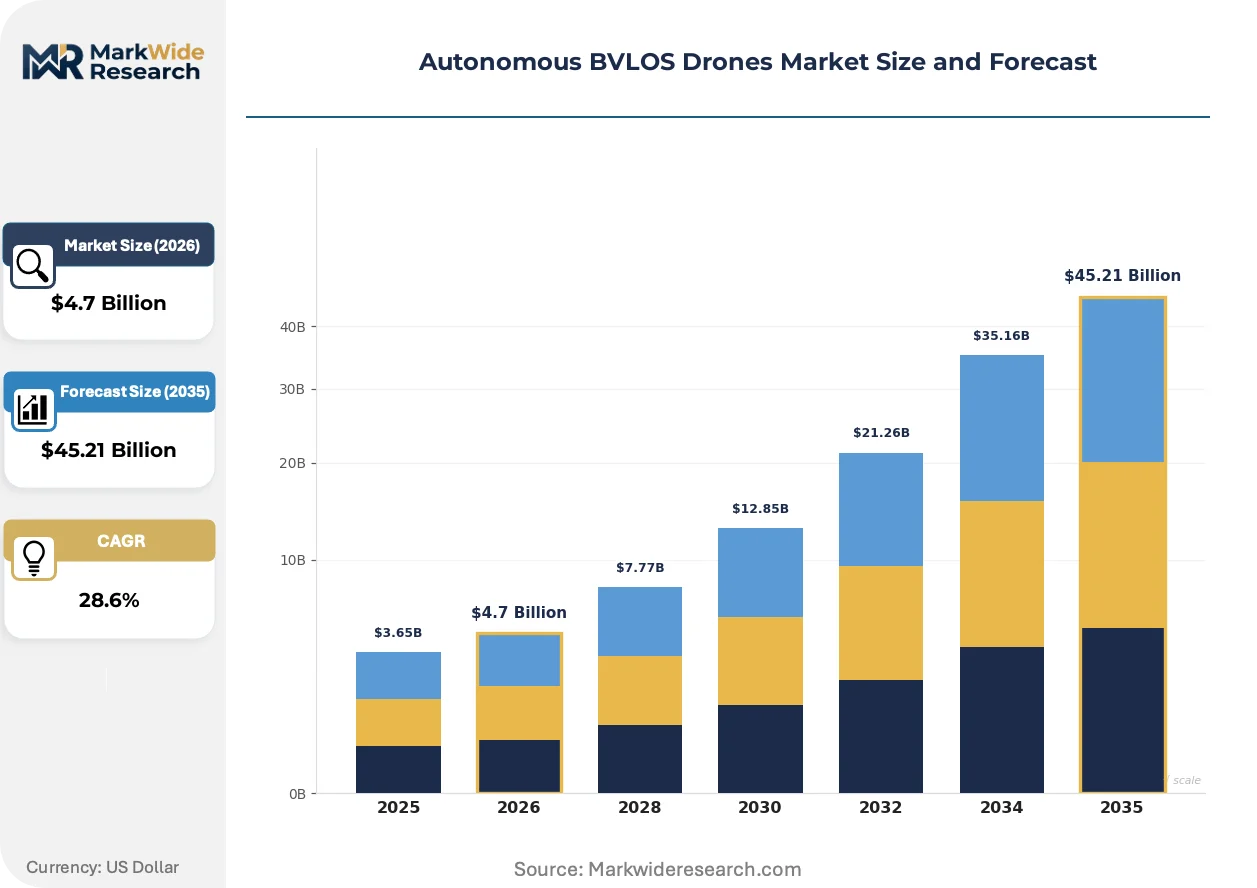
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Tow-Plane Use Case: Agriculture, Infrastructure Inspection, Delivery Services, Surveillance End User: Agricultural Corporations, Logistics Providers, Energy Companies, Government Agencies Technology: GPS Navigation, Computer Vision, AI Algorithms, Collision Avoidance |
| Companies Covered | Skydio, Zipline International Inc., Wing, DJI, AeroVironment, Inc., General Atomics Aeronautical Systems, Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous BVLOS Drones Market Strategic Shifts
Autonomy architectures are diverging as mission-specific compute requirements splinter the historical one-stack-fits-all model, with edge AI inference engines, satellite-agnostic navigation, and modular payload interfaces each pursuing independent optimization paths.
Edge-based neural inference is fragmenting autonomy hardware roadmaps. Lightweight vision processing units now execute real-time obstacle classification without ground station dependency, enabling true solo operations in communication-denied environments. Agricultural operators in Australia's wheat belt and Canada's prairie provinces prioritize these self-contained systems for remote property coverage where cellular connectivity fails.
EASA's U-space regulatory framework mandates cooperative drone behavior in controlled airspace, compelling manufacturers to integrate C2 link redundancy and geofencing compliance at the firmware level. This shifts competitive emphasis from raw flight performance to certification-ready software stacks. Logistics providers planning European cross-border routes must validate their platforms against harmonized standards before 2026 implementation deadlines.
Leasing structures displace outright purchase for fleet operators managing seasonal demand volatility. Rural healthcare networks in Rwanda and Ghana now access Zipline-style delivery capability through pay-per-delivery arrangements rather than capital-intensive aircraft ownership. This reconfigures vendor revenue models toward recurring service fees and incentivizes reliability improvements over specification maximization.
Autonomous BVLOS Drones Market Segmentation
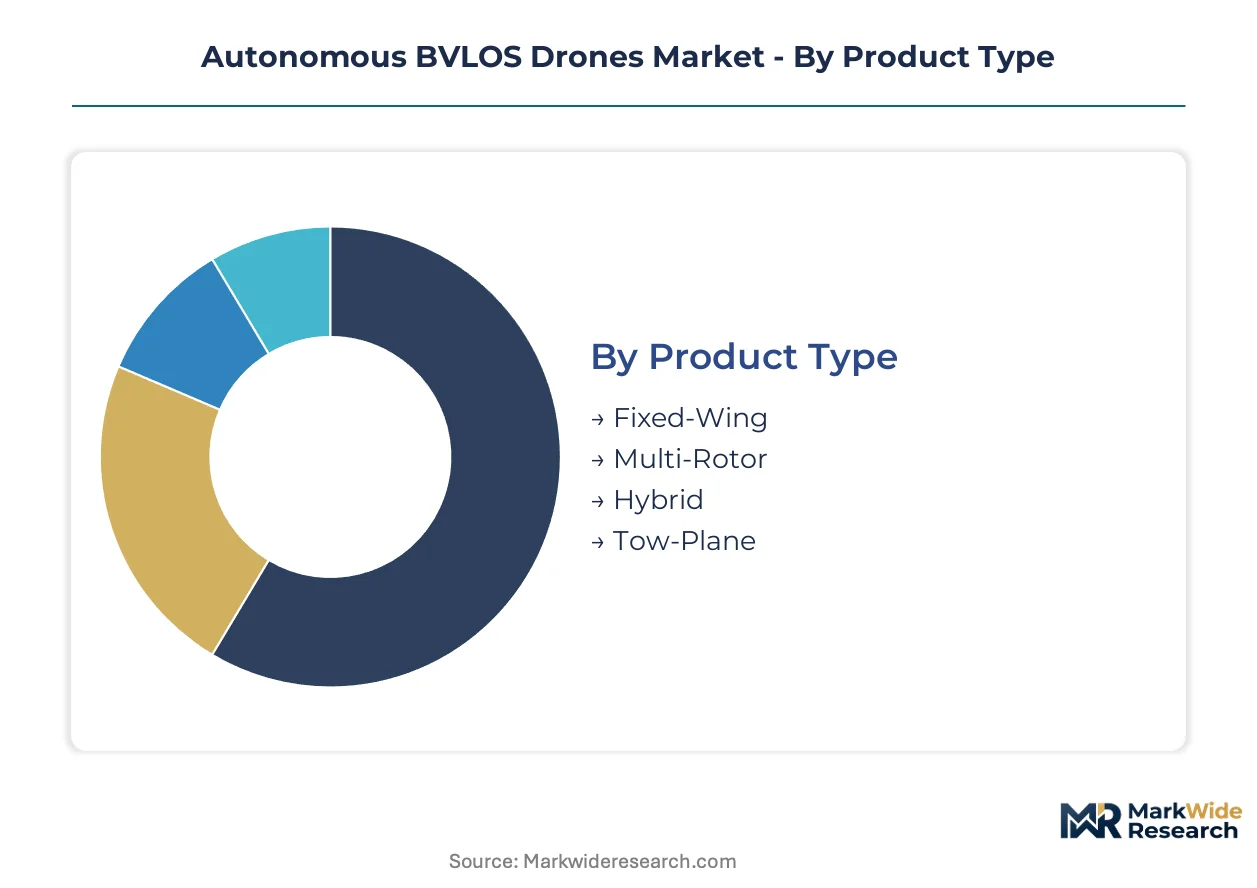
Autonomous BVLOS drones fragment across four distinct taxonomies that determine procurement priorities and certification pathways. Product architecture dictates endurance profiles and airspace access requirements. Use case specialization shapes sensor payloads and autonomy stack specifications. Technology integration separates certified-flight-grade platforms from experimental systems.
Product Type:
Fixed-wing platforms dominate cross-border corridor missions in the United States and Australia, while hybrid configurations gain traction among European operators seeking vertical takeoff flexibility without sacrificing range.
- Fixed-Wing:Extended-endurance architectures sustain 8-14 hour flight durations on efficient cruise profiles. Transmission line operators across Texas and California deploy these systems for thousand-mile infrastructure corridors where ground crew minimization drives procurement decisions.
- Hybrid:Vertical takeoff capability combined with fixed-wing cruise efficiency captures expanding margin pools as EASA U-space regulations demand precision landing in constrained sites. Logistics providers planning European cross-border healthcare delivery prioritize these configurations for hospital rooftop operations.
- Multi-Rotor:Agility-focused platforms with high cell-count electric propulsion dominate close-quarters industrial inspection where maneuverability outweighs endurance specifications.
- Tow-Plane:Glider-launch configurations serve specialized atmospheric research and high-altitude sensor deployment missions requiring minimal onboard power draw.
Fixed-wing holds the largest share; momentum sits with hybrid as operators demand operational flexibility without dual fleet investments.
Use Case:
Cost tier stratification separates capital-intensive surveillance programs from pay-per-delivery logistics models that reduce customer capital commitment.
- Delivery Services:Precision payload systems execute pre-programmed drop sequences across distributed healthcare networks. Rwanda and Ghana's rural health networks validate pay-per-delivery structures that displace aircraft ownership costs.
- Infrastructure Inspection:Corrosion-detection sensor suites with thermal imaging penetrate utility procurement budgets across North American energy corridors. Texas and California transmission operators standardize these missions for wildfire risk mitigation.
- Agriculture:Crop monitoring and precision spraying configurations target large-scale farming cooperatives in Brazil's Mato Grosso state where million-hectare estates justify fleet procurement.
- Surveillance:Persistent observation platforms with encrypted data links anchor government agency budgets for border and maritime domain awareness.
Infrastructure inspection commands the deepest procurement budgets; delivery services are climbing the fastest as healthcare logistics operators validate reliability at scale.
End User:
Customer type determines certification urgency, with government agencies accepting extended procurement timelines that commercial logistics providers cannot tolerate.
- Energy Companies:Transmission and pipeline operators across the United States Mountain West states mandate FAA Part 107 waivers for beyond-visual-line-of-sight corridor monitoring. Their procurement volumes concentrate in fixed-wing platforms with minimal ground crew requirements.
- Logistics Providers:Healthcare and e-commerce delivery specialists prioritize EASA specific-category certification for European cross-border route validation. Their technology roadmaps emphasize detect-and-avoid software stacks over raw flight endurance.
- Agricultural Corporations:Brazilian soy and sugarcane cooperatives drive seasonal demand volatility that favors leasing structures over capital-intensive fleet ownership.
- Government Agencies:Border surveillance and maritime patrol programs accept 18-24 month autonomy software certification timelines that commercial operators reject.
Energy companies hold the largest share; momentum sits with logistics providers as pay-per-delivery models reduce customer capital barriers.
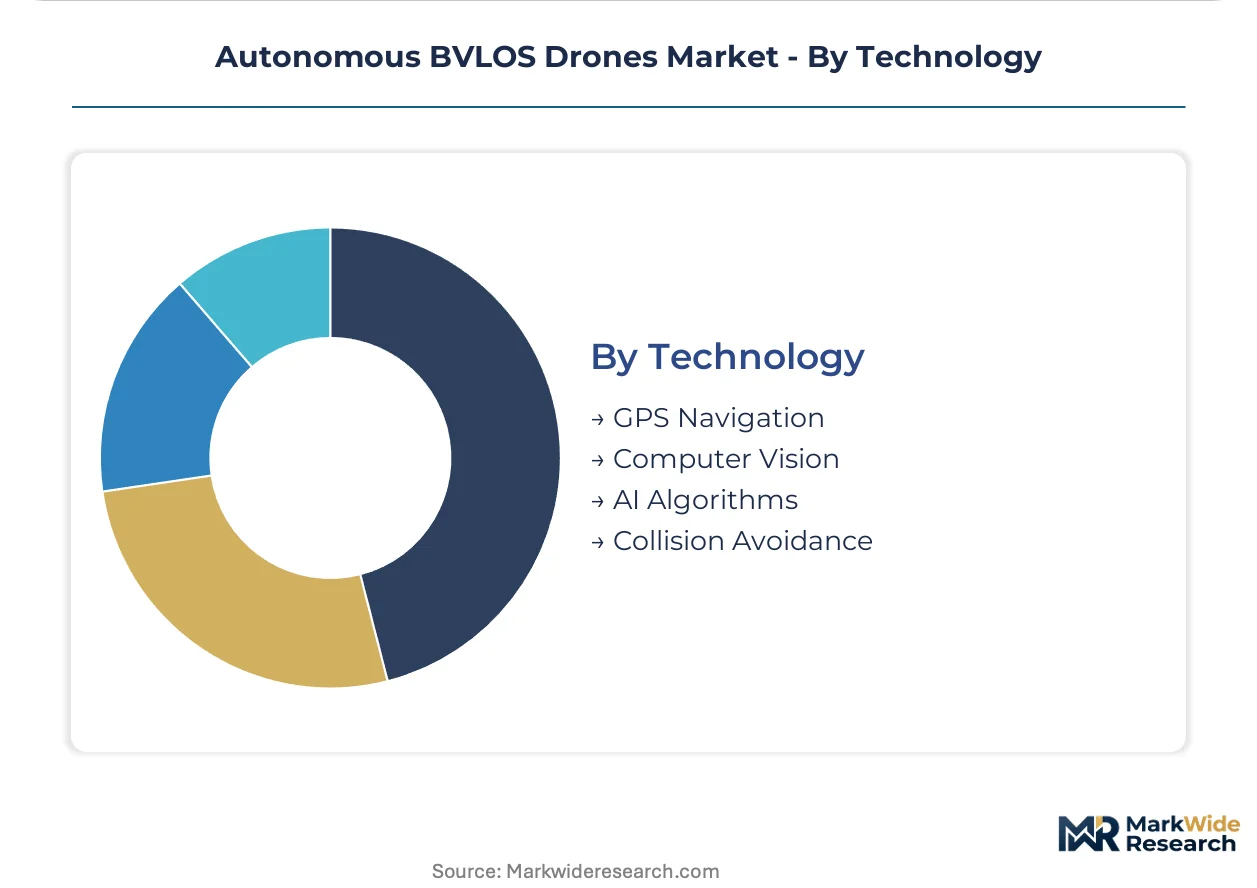
Technology:
Supply concentration for military-grade components creates single-source vulnerability that shapes vendor differentiation strategies.
- Computer Vision:Onboard neural inference engines execute real-time obstacle classification without ground station dependency. Australian wheat belt operators prioritize these self-contained systems for remote property coverage where cellular connectivity fails.
- Collision Avoidance:Detect-and-avoid systems integrating radar, lidar, and optical sensors constitute the critical path for FAA type certification. Qualified personnel shortages at the FAA extend algorithm validation timelines beyond product launch targets.
- GPS Navigation:Redundant multi-constellation receivers with anti-jam capabilities anchor certified-flight-grade autonomy stacks for defense and border surveillance applications.
- AI Algorithms:Mission planning and adaptive route optimization software differentiate service-layer revenue models from hardware-centric vendor strategies.
Collision avoidance holds the largest share; momentum sits with computer vision as edge inference enables GPS-denied navigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified-flight-grade autonomy stacks concentrate supply among US and European vendors, while demand disperses across energy corridors, agricultural belts, and healthcare networks spanning multiple continents. Regulatory fragmentation creates divergent deployment timelines, with FAA Part 107 waivers unlocking US commercial airspace faster than EASA's harmonized framework enables European cross-border operations.
United States
Rural logistics networks and energy corridor inspections drive concentrated deployment of long-endurance autonomous systems across Texas, California, and the Mountain West states. FAA Part 107 waivers and emerging Remote ID mandates shape product certification pathways and fleet deployment timelines for operators seeking airspace access. Transmission line operators in Texas deploy fixed-wing BVLOS systems to monitor thousands of miles of infrastructure with minimal ground crew.
Brazil
Large-scale soy and sugarcane cooperatives in Mato Grosso and São Paulo states present expanding demand for crop monitoring and precision spraying across million-hectare estates. The country's national aviation regulator progressively certifies beyond-visual-line-of-sight flight corridors for commercial agricultural operations. Agricultural operators in Mato Grosso prioritize autonomous fleet procurement for seasonal demand volatility that favors leasing structures.
Germany
Industrial inspection and logistics use cases concentrate demand in manufacturing clusters along the Rhine-Ruhr corridor and southern automotive belts. EASA's specific-category framework and EU drone regulation harmonize cross-border BVLOS standards across European member states. Logistics providers in Bavaria validate detect-and-avoid software stacks for hospital rooftop operations under emerging U-space regulatory deadlines.
Australia
Wheat belt agricultural operators and mining corridor inspectors deploy self-contained systems for remote property coverage where cellular connectivity fails. The country's civil aviation safety authority certifies autonomous operations across vast unpopulated territories with reduced air traffic coordination requirements. Agricultural operators in Western Australia's wheat belt prioritize edge-based neural inference engines for GPS-denied navigation in communication-denied environments.
Rwanda
Rural healthcare networks validate pay-per-delivery models that displace aircraft ownership costs through Zipline-style delivery capability. The country's national aviation authority established early regulatory frameworks for medical drone corridors that now serve as reference models for neighboring states. Healthcare logistics operators in Kigali's surrounding districts demonstrate reliability at scale through recurring service fee arrangements rather than capital-intensive procurement.
Autonomous BVLOS Drones Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with computer vision specialists commanding premium positioning in close-quarters industrial inspection while scale manufacturers capture volume in agricultural and consumer segments. The vendor base stratifies across three tiers: defense-prime contractors anchoring government surveillance portfolios, venture-backed autonomy stack developers pursuing FAA type certification, and diversified electronics conglomerates leveraging manufacturing scale. Dominant competitive moves include strategic partnerships between software developers and airframe manufacturers, plus geographic expansion through regulatory sandbox participation in emerging markets.
Within the defense-prime tier, General Atomics Aeronautical Systems, Inc. and Lockheed Martin Corporation exemplify extended-endurance platform specialists anchoring border surveillance and maritime domain awareness programs. Skydio and Zipline International Inc. occupy positions in the venture-backed autonomy tier, with the former representing advanced computer vision stacks for industrial inspection and the latter exemplifying precision delivery logistics validated across distributed healthcare networks in challenging terrain.
| Leading Market Players |
|---|
| Skydio |
| Zipline International Inc. |
| Wing |
| DJI |
| AeroVironment, Inc. |
| General Atomics Aeronautical Systems, Inc. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
Ninety-day sensor module lead times concentrate procurement leverage among defense-tier suppliers and force tiered pricing stratification across certified-flight-grade and experimental autonomy stacks. This inventory compression elevates working capital requirements for FAA certification-bound manufacturers while squeezing margins on uncertified platforms competing solely on specification.
Pricing Analysis
FAA Part 107 waiver tiers dictate the pricing structure across premium certified-flight-grade, standard commercial-grade, and economy experimental-grade platforms. Price differentiation centers on EASA specific-category certification status and detect-and-avoid algorithm validation depth. Cost compression in the economy tier intensifies because cobalt and nickel price volatility feeds directly into lithium-polymer battery pack costs. Logistics providers planning European cross-border routes demonstrate lowest price sensitivity due to pay-per-delivery model adoption, while agricultural cooperatives in Brazil exhibit highest sensitivity given seasonal demand volatility.
Supply Chain Analysis
Strategic stockpiling of military-grade IMUs and precision GPS modules dominates procurement behavior given single-source vulnerability among US and European defense contractors. Component manufacturing concentrates in the United States, Germany, and Taiwan for flight-critical sensors and compute modules. Raw material dependencies span cobalt and nickel for battery cells, rare earth elements for motor magnets, and specialized silicon for edge AI inference chips. Tariff exposure on Chinese-sourced electronics creates supply chain risk for multirotor platforms with high component counts. Distribution runs through direct OEM relationships with energy corridor operators and pay-per-delivery service contracts with healthcare logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified-flight-grade autonomy represents a high-growth disruption as FAA and EASA regulatory frameworks progressively unlock commercial airspace access at scale. Remote ID mandates and U-space implementation deadlines create technology inflection points that separate scalable platforms from legacy systems.
For Market Incumbents: Secure detect-and-avoid algorithm certification pipelines against FAA qualified personnel shortages that extend validation timelines. Anchor defense-prime relationships through extended-endurance platform roadmaps while building EASA specific-category validation capacity for European cross-border logistics contracts. Vertical integration into flight-grade sensor manufacturing mitigates single-source IMU vulnerability from concentrated defense contractor supply. For New Entrants and Emerging Players: Anchor in Brazilian agribusiness leasing structures where seasonal demand volatility displaces capital-intensive fleet ownership. Target Mato Grosso soy cooperatives and São Paulo sugarcane estates with precision spraying configurations validated under emerging national aviation regulator frameworks. Go-to-market through equipment-as-a-service arrangements reduces customer capital barriers and accelerates fleet penetration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with captive drone manufacturing divisions lacking certification-focused software stacks. Long-term viability centers on autonomy stack differentiation rather than airframe commoditization. Watch FAA type certification timeline compression as the inflection signal indicating regulatory capacity expansion and accelerated product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Detect-and-Avoid Certification Investment | FAA Part 107 waiver eligibility unlocks US energy corridor inspection contracts with minimal ground crew requirements. |
| EASA Specific-Category Validation | EU drone regulation harmonization enables cross-border healthcare delivery routes across German, French, and Dutch airspace. |
| 5G Network Slicing Partnership | Low-latency C2 links open maritime and offshore energy applications without satellite dependency costs. |
| Edge AI Inference Hardware Roadmap | Self-contained navigation penetrates Australian wheat belt and Canadian prairie provinces with failed cellular coverage. |
| Pay-per-Delivery Service Model | Recurring revenue structures displace capital barriers for Rwanda and Ghana rural health network procurement. |
Study Parameters
Desk research of FAA waiver databases, EASA certification registries, and national aviation authority filings preceded structured interviews with autonomy software engineers, fleet operations managers at energy corridor operators, EASA certification consultants, and healthcare logistics procurement leads. Primary fieldwork with Texas transmission line operators and Bavarian hospital rooftop validation programs combined with secondary analysis of SEC filings from defense-prime contractors and venture capital disclosures from autonomy stack developers. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across product architecture and use case dimensions.
Variance decomposition across product type, use case specialization, end user category, and technology integration anchors the analytical framework throughout the projection horizon. Segmentation modeling captures fixed-wing endurance profiles, hybrid VTOL flexibility premiums, multirotor maneuverability tradeoffs, and tow-plane specialization margins. CAGRs derive from installed base growth rates, fleet replacement cycles driven by Remote ID mandates, and penetration assumptions for pay-per-delivery models in healthcare logistics. Industry-specific forecast inputs include FAA regional office waiver processing capacity and EASA U-space implementation deadlines.
Decision-makers should treat outputs as directional under assumptions of progressive regulatory clarity and stable cobalt-nickel pricing; material deviation would warrant model refresh. Forecasts embed assumptions regarding FAA qualified personnel expansion and EASA cross-border harmonization velocity. Revision becomes warranted when autonomy software certification backlogs exceed thresholds that delay product launches beyond operator procurement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Europe Aerospace Robotics Market