
 Middle-East and Africa AUV & ROV Market | 2026-2036
Middle-East and Africa AUV & ROV Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa AUV & ROV Market Insights
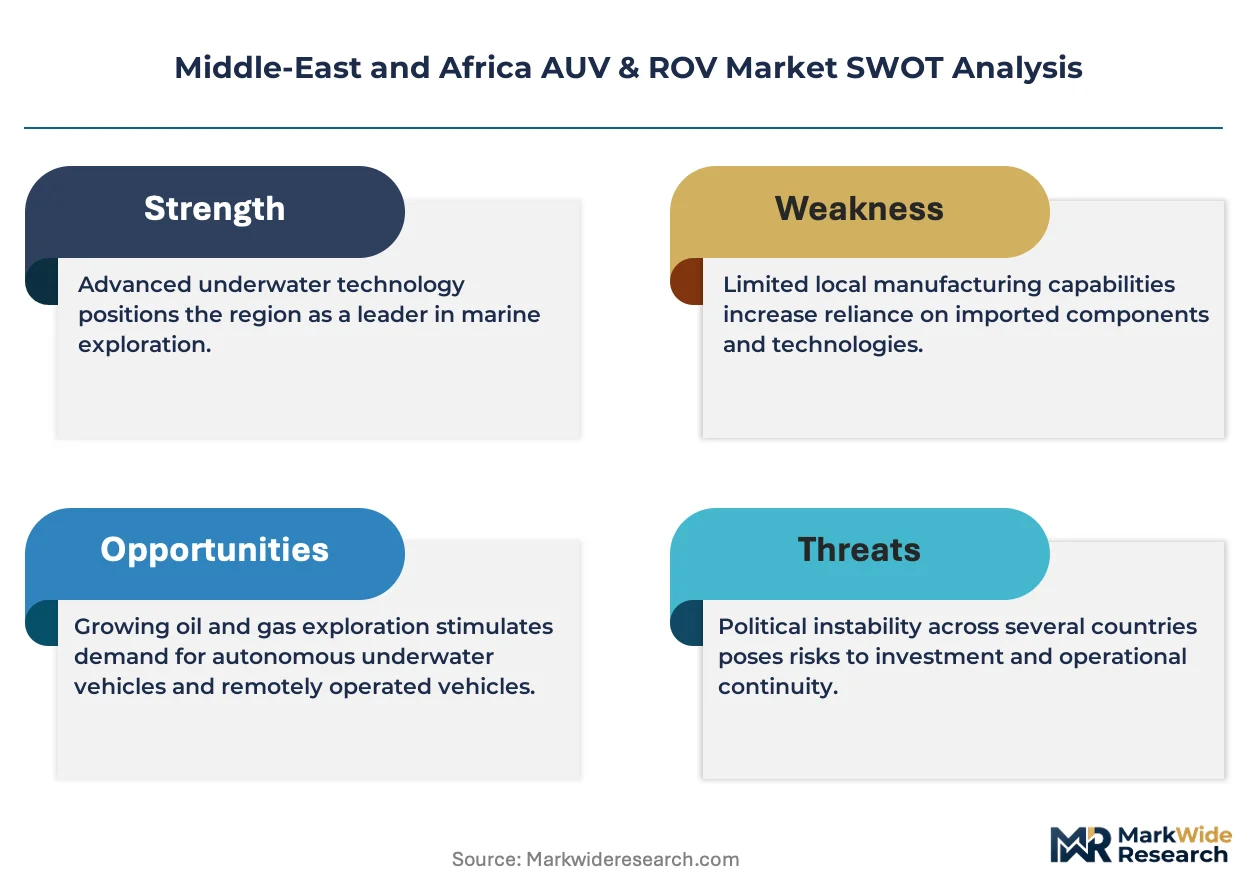
DNV-ST-F203 certification for subsea vehicle operations is reorganizing competitive access across the Middle-East and Africa AUV & ROV market. Fugro NV leverages its integrated survey and positioning capabilities to anchor long-term contracts in West African offshore blocks. Kongsberg Gruppen ASA sustains technology leadership through proprietary autonomous navigation systems calibrated for deep-water African basins. Saipem SpA competes on fabrication scale, operating dedicated ROV support vessels from bases in Angola and Nigeria.
Autonomous underwater vehicles and remotely operated vehicles are self-propelled or tethered subsea craft rated for depths from 300 meters to over 6,000 meters, equipped with sonar, manipulator arms, and sensor payloads for seabed intervention. Their primary purpose is to execute inspection, construction support, and data collection tasks in environments beyond diver reach. ROV systems dominate current offshore energy expenditure in the region, while autonomous systems represent the fastest-growing technology category as Nigerian and Angolan operators trial untethered platforms for pipeline survey. Inspection services command the largest service-type revenue pool, though data acquisition margins are expanding with higher-resolution seabed mapping requirements from marine research end users.
CE marking under the EU Marine Equipment Directive shapes product eligibility for vessels operating in Mediterranean-adjacent North African waters, while Nigeria's Department of Petroleum Resources enforces subsea safety standards that mandate ROV redundancy for deep-water drilling permits. South Africa's National Regulator for Compulsory Specifications administers pressure-vessel certifications affecting vehicle hull integrity. Stakeholders must monitor how autonomous system liability frameworks evolve across multiple national maritime jurisdictions before committing capital to next-generation platform deployments.
Market Dynamics
DNV-ST-F203 certification requirements are restructuring competitive access across the Middle-East and Africa AUV & ROV market, forcing vessel operators to upgrade inspection protocols and recalibrate procurement criteria for subsea service contracts.
Growth Catalysts
- Deep-water drilling permits:Nigeria's Department of Petroleum Resources mandates ROV redundancy for deep-water drilling permits, compelling offshore operators to expand tethered vehicle fleets.
- Marine research expansion:South Africa's marine research institutions are driving demand for deep-water survey vehicles with higher-resolution seabed mapping requirements.
- Subsea inspection programs:Offshore oil and gas operators in the Gulf of Guinea are expanding subsea inspection programs, creating sustained demand for intervention-class ROV systems.
Market Restraints
- Pressure-vessel certification delays:South Africa's National Regulator for Compulsory Specifications administers pressure-vessel certifications that extend vehicle hull integrity approval timelines.
- Autonomous liability frameworks:Multiple national maritime jurisdictions lack harmonized autonomous system liability frameworks, freezing capital commitment to next-generation platform deployments.
- CE marking exclusion:CE marking under the EU Marine Equipment Directive shapes product eligibility only for Mediterranean-adjacent North African waters, fragmenting equipment standards across the broader region.
Strategic Opportunities
- Angolan untethered trials:Angolan operators are trialing autonomous platforms for pipeline survey, creating first-mover advantage for AUV manufacturers with deep-water navigation calibration.
- West African offshore blocks:Integrated survey and positioning capabilities anchor long-term contract potential in West African offshore blocks where exploration activity is intensifying.
- Data acquisition margins:Higher-resolution seabed mapping requirements from marine research end users are expanding data acquisition margins beyond traditional inspection services.
Industry Challenges
- Autonomous navigation calibration:Proprietary autonomous navigation systems require basin-specific calibration for deep-water African conditions, demanding specialized engineering talent scarce in regional markets.
- Multi-jurisdictional compliance:Stakeholders must monitor liability framework evolution across multiple national maritime jurisdictions before deploying capital to next-generation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa AUV & ROV Market |
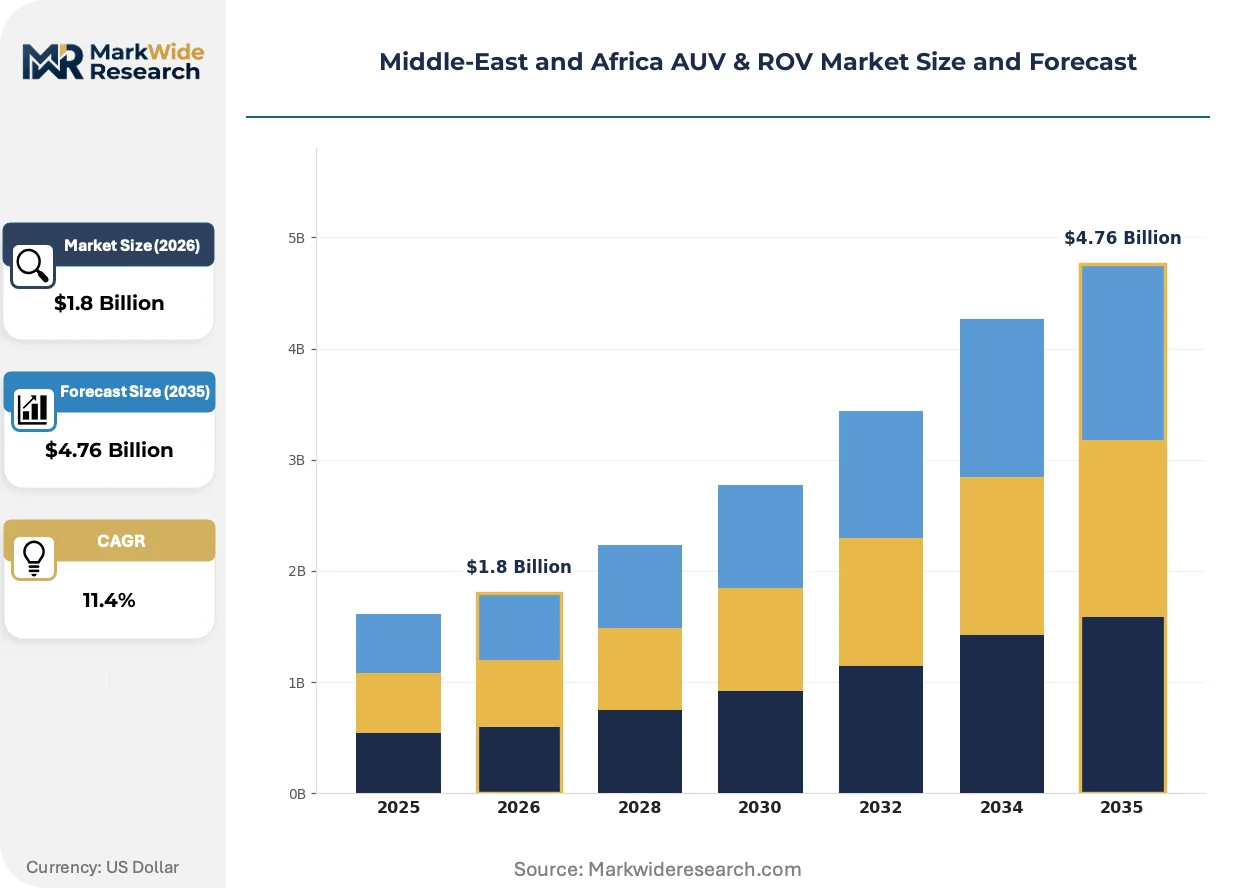
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUV, ROV, Hybrid Systems, Observation Vehicles End User: Oil & Gas, Marine Research, Defense, Environmental Monitoring Service Type: Inspection, Survey, Maintenance, Data Acquisition Technology: Electric, Hydraulic, Autonomous Systems, Communication Equipment |
| Companies Covered | DOF Subsea AS, Fugro NV, Subsea 7 SA, Saipem SpA, Oceaneering International Inc, Teledyne Technologies Incorporated, Kongsberg Gruppen ASA, ATLAS ELEKTRONIK GmbH, TechnipFMC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa AUV & ROV Market Trends and Innovations
Autonomous underwater platforms are actively reshaping competitive positioning in the Middle-East and Africa AUV & ROV market, compressing the traditional dominance of tethered systems while forcing suppliers to recalibrate service models around untethered data collection architectures.
Untethered autonomous navigation systems calibrated for deep-water African basins are fragmenting the traditional ROV-dominated service landscape. Nigerian and Angolan offshore operators are piloting these platforms for pipeline survey applications at accelerating pace. The technology is fragmenting long-term maintenance contracts previously captured by tethered vehicle operators with dedicated support vessels.
Nigeria's Department of Petroleum Resources enforces subsea safety standards that mandate ROV redundancy for deep-water drilling permits, tightening operational compliance burdens. This regulatory pressure is compressing procurement timelines and elevating certification costs for market entrants. Deep-water drilling permit applicants in Nigerian offshore blocks are responding by consolidating supplier relationships with DNV-ST-F203 certified service providers.
Service unbundling is disrupting traditional bundled inspection-maintenance contracts in West African offshore energy procurement. Nigerian offshore energy sector buyers are separating data acquisition from physical intervention, creating discrete vendor selection criteria. This pattern is most visible in the Gulf of Guinea where national oil companies are restructuring tender specifications to enable autonomous platform competition.
Middle-East and Africa AUV & ROV Market Segmentation
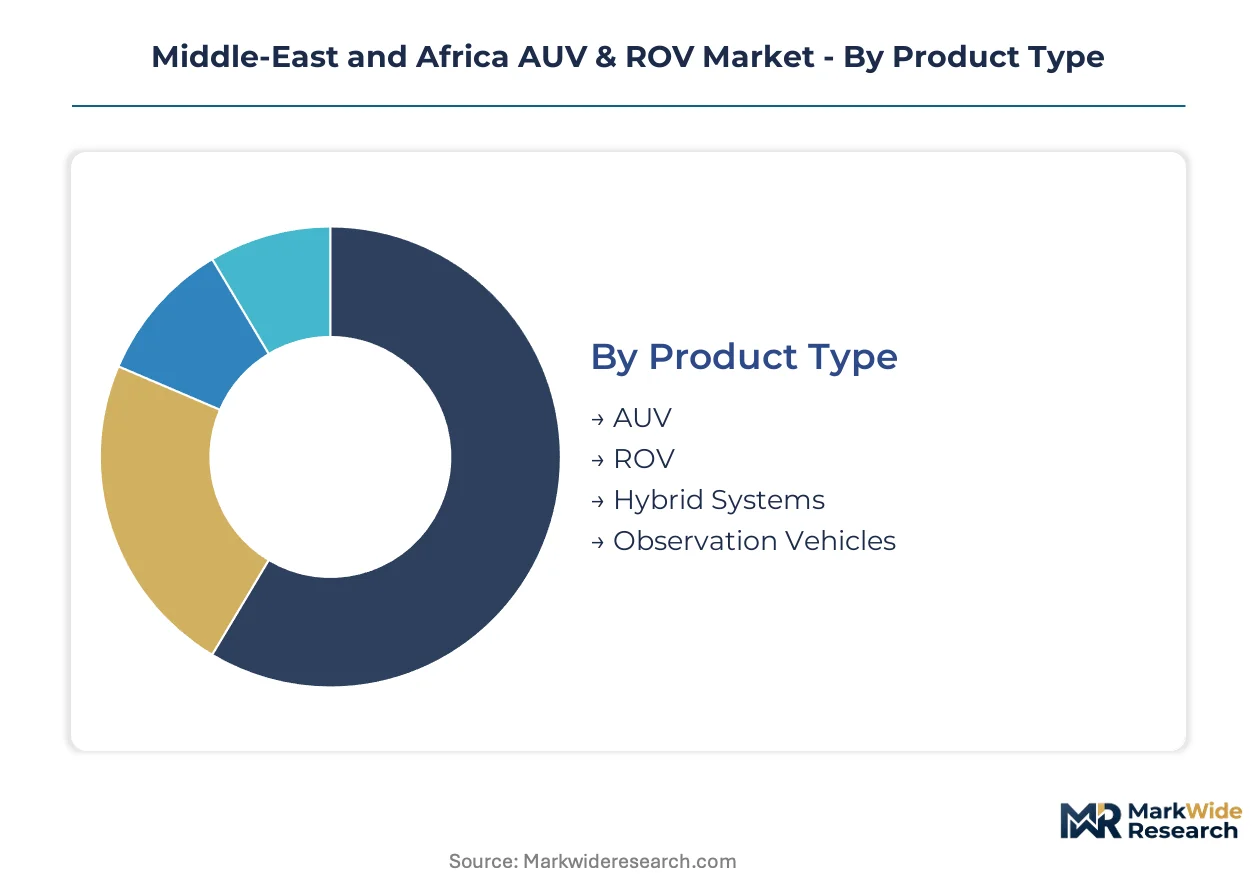
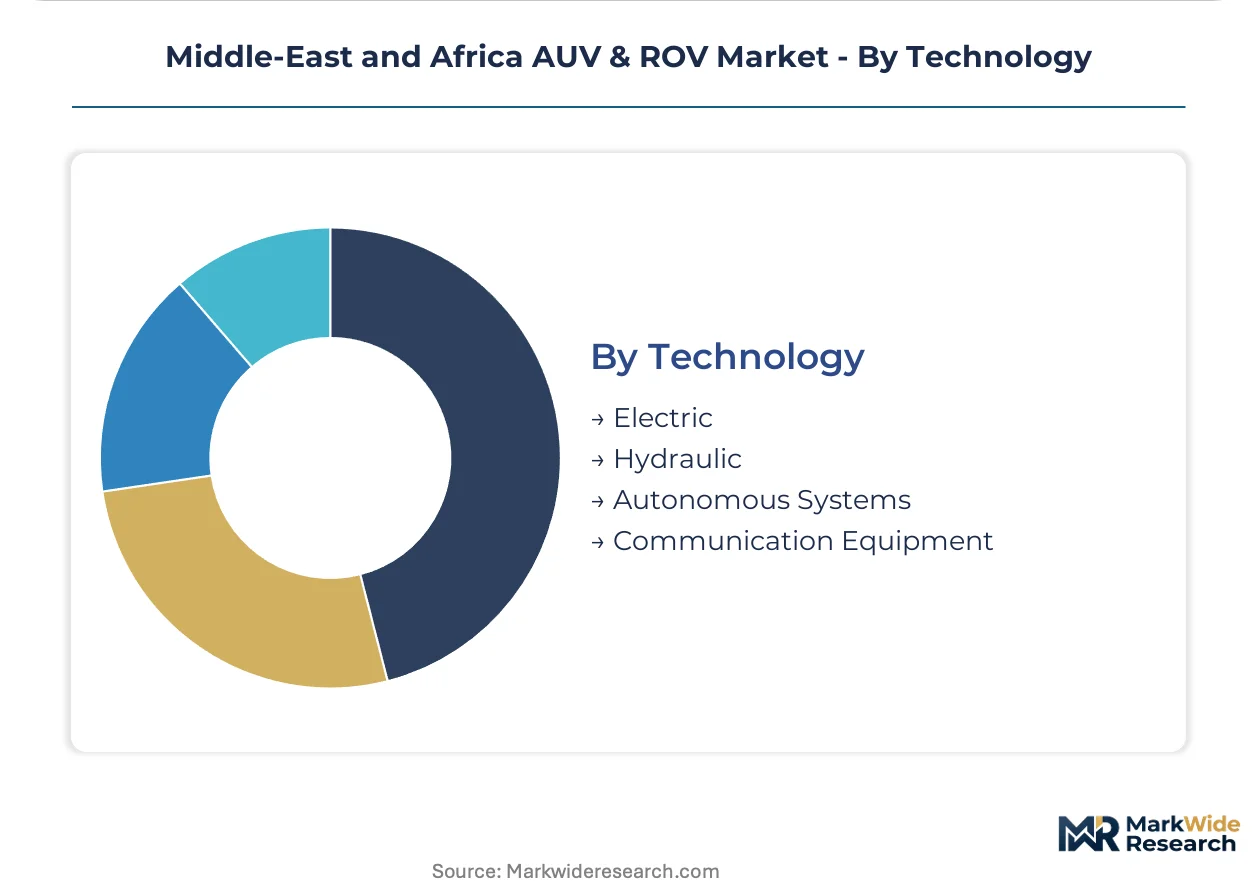
Segmentation in the Middle-East and Africa AUV & ROV market reveals how regulatory pressure and operational depth requirements reshape procurement patterns across offshore energy and marine science applications.
Product Type:
DNV-ST-F203 certification tiers create distinct market access barriers that favor tethered systems with established compliance records over autonomous platforms still navigating liability frameworks.
- ROV:Tethered vehicles rated for 3,000-6,000 meter operations dominate Nigerian and Angolan offshore maintenance contracts. Nigeria's Department of Petroleum Resources mandates ROV redundancy for deep-water drilling permits, cementing procurement priority for intervention-class tethered fleets.
- AUV:Self-propelled untethered platforms carry sensor payloads for pipeline survey without surface vessel constraint. Angolan operators are piloting these systems for autonomous seabed mapping, though multi-jurisdictional liability gaps freeze capital commitment at scale.
- Hybrid Systems:Configurations combining tethered reliability with untethered endurance address transitional operational requirements in Gulf of Guinea inspection programs.
- Observation Vehicles:Lighter platforms rated for shallow-water marine research support South Africa's higher-resolution seabed mapping initiatives.
Established volume favors ROV; emerging adoption favors AUV.
End User:
Cost tier differentiation separates capital-intensive offshore energy procurement from grant-funded marine research acquisition cycles.
- Oil & Gas:Offshore operators in Nigeria and Angola concentrate procurement for subsea inspection and construction support, with bundled service contracts historically capturing long-term vendor relationships.
- Marine Research:South Africa's institutions drive demand for deep-water survey vehicles with resolution specifications exceeding commercial energy sector requirements.
- Defense:Regional naval programs acquire observation-class platforms for harbor security and seabed infrastructure monitoring.
- Environmental Monitoring:Gulf of Guinea environmental compliance programs generate discrete procurement for baseline seabed assessment.
Energy sector procurement dominates contract value; marine research segments are climbing the fastest.
Service Type:
Application maturity separates physical intervention capabilities from data-centric service margins.
- Inspection:Visual and sensor-based assessment of subsea infrastructure commands the largest revenue pool across Nigerian and Angolan offshore blocks.
- Survey:Seabed mapping and pipeline route characterization concentrates demand in West African exploration licensing rounds.
- Maintenance:Intervention-class ROV operations for valve operation and equipment replacement require dedicated support vessel coordination.
- Data Acquisition:Higher-resolution seabed mapping requirements from South African research end users are expanding margins beyond traditional inspection services.
Physical intervention services anchor current revenue; data acquisition capabilities are gaining share fastest.
Technology:
Supply concentration in electric propulsion systems contrasts with fragmented autonomous navigation calibration requirements.
- Electric:Battery-powered propulsion dominates observation and light-work-class vehicles for marine research and shallow inspection applications.
- Hydraulic:High-power systems for heavy intervention tasks retain priority in deep-water drilling support where torque requirements exceed electric alternatives.
- Autonomous Systems:Proprietary navigation architectures require basin-specific calibration for deep-water African conditions, demanding engineering talent scarce in regional markets.
- Communication Equipment:Acoustic and optical data links enable real-time telemetry for tethered operations and delayed data retrieval for autonomous missions.
Proven hydraulic systems defend intervention market position; autonomous navigation architectures show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore energy operators concentrate procurement across West African basins while marine research institutions anchor demand in Southern Africa. National oil companies and international majors drive contract value through bundled subsea service agreements. Regulatory divergence between petroleum authorities and maritime safety agencies fragments equipment certification requirements.
Nigeria
Deep-water drilling permit holders anchor regional ROV fleet expansion through mandatory redundancy requirements. The Department of Petroleum Resources enforces subsea safety standards that elevate certification costs for market entrants. Lagos and Port Harcourt host the primary vendor coordination centers where DNV-ST-F203 compliance verification occurs before offshore deployment.
Angola
Autonomous platform trials for pipeline survey are accelerating capital commitment to untethered navigation systems. The national petroleum regulator aligns with international maritime conventions for subsea vehicle operations. Luanda serves as the operational hub where fabrication yards coordinate ROV support vessel mobilization to Block 15 and Block 17 developments.
South Africa
Marine research institutions drive demand for deep-water survey vehicles with resolution specifications exceeding commercial energy sector requirements. The National Regulator for Compulsory Specifications administers pressure-vessel certifications affecting vehicle hull integrity approval timelines. Cape Town and Durban concentrate oceanographic fleet operations where seabed mapping programs require higher-resolution sensor payloads.
Saudi Arabia
Offshore field development in the Arabian Gulf sustains intervention-class ROV procurement for platform maintenance and inspection. The national petroleum authority mandates equipment standards aligned with international classification society rules. Dhahran and Jubail Industrial City host the primary coordination centers where ARAMCO contractors consolidate subsea service contracts.
United Arab Emirates
Artificial island construction and subsea infrastructure expansion sustain demand for observation and light-work-class vehicles. The national maritime authority enforces vessel equipment standards for operations in Gulf waters. Dubai and Abu Dhabi serve as regional logistics hubs where international service providers coordinate fleet movements across Middle Eastern offshore blocks.
Middle-East and Africa AUV & ROV Market Competitive Landscape
Player mix skews toward integrated energy service contractors with dedicated vessel fleets and proprietary technology developers with autonomous navigation capabilities. Market structure concentrates around three strategic archetypes: full-service subsea contractors owning ROV support vessels, technology specialists licensing autonomous navigation systems, and regional fabrication yards assembling intervention-class platforms. Competitive dynamics center on certification acquisition speed and long-term contract anchoring through integrated survey and positioning capabilities.
Among European-integrated service contractors, Fugro NV, Saipem SpA, and Kongsberg Gruppen ASA exemplify distinct competitive positions. Fugro represents the survey-specialist archetype with integrated positioning capabilities. Saipem occupies the fabrication-scale tier with dedicated vessel operations. Kongsberg exemplifies technology leadership through proprietary autonomous systems. These three anchors illustrate how geographic origin and corporate structure shape strategic positioning without predetermining market share outcomes.
| Leading Market Players |
|---|
| DOF Subsea AS |
| Fugro NV |
| Subsea 7 SA |
| Saipem SpA |
| Oceaneering International Inc |
| Teledyne Technologies Incorporated |
| Kongsberg Gruppen ASA |
| ATLAS ELEKTRONIK GmbH |
| TechnipFMC |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month lead times for DNV-ST-F203 certified pressure vessels concentrate procurement leverage with Norwegian and Singaporean fabrication yards, compressing margin capture for African-based assemblers while elevating day-rate premiums for compliant intervention-class systems.
Pricing Analysis
Cost-plus contracts indexed to Brent crude movements dominate West African offshore procurement, with Nigerian national oil companies layering DNV-ST-F203 certification premiums atop base vessel day-rates. Price differentiation separates intervention-class ROVs with dual-redundant hydraulic systems from observation platforms with electric propulsion. Margins are tightening in shallow-water inspection tiers as regional fabrication yards in Angola and Nigeria expand light-work-class assembly capacity. Marine research institutions in South Africa exhibit lowest price sensitivity, prioritizing sensor resolution specifications over capital expenditure constraints.
Supply Chain Analysis
Port congestion at Durban and Lagos elevates inbound logistics costs for pressure-hull steel and subsea-rated optical cables sourced from German and Japanese specialty mills. Component supply concentrates in Norway for autonomous navigation systems, the United States for high-torque hydraulic power units, and China for battery-electric propulsion modules. Single-source vulnerability sits with deep-water acoustic positioning transponders produced by a concentrated tier of North Sea suppliers. Distribution runs through ARAMCO contractor consolidation centers in Dhahran and international service provider hubs in Luanda.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous navigation calibration for deep-water African basins constitutes a high-growth disruption as Angolan operators accelerate untethered pipeline survey trials beyond Nigerian regulatory ROV mandates.
For Market Incumbents: Shield long-term maintenance contract portfolios by embedding DNV-ST-F203 certification investment into bundled service offerings before autonomous platforms fragment intervention-class revenue pools. Backward integration into pressure-vessel fabrication through partnerships with South African yards reduces exposure to Norwegian supplier lead-time volatility. For New Entrants and Emerging Players: DNV-ST-F203 fast-track accreditation for hybrid tethered-autonomous systems unlocks procurement eligibility in Nigerian deep-water drilling permit applications. White-space concentration sits with marine research data acquisition in South Africa, where resolution specifications exceed commercial energy sector requirements. Channel entry through Cape Town oceanographic fleet operators bypasses incumbent energy service contractor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Nigerian and Angolan petroleum authorities are hardening subsea safety standards faster than autonomous liability frameworks mature. Acquisition targets should display integrated survey-positioning capabilities with existing West African vessel operations. The signal to watch is Angolan national petroleum regulator adoption of autonomous navigation performance standards, which would unlock capital commitment at scale.| Strategic Initiative | Industry Significance |
|---|---|
| DNV-ST-F203 Certification Investment | Unlocks Nigerian deep-water drilling permit procurement eligibility for intervention-class fleets. |
| Autonomous Navigation Calibration | Establishes proprietary basin-specific performance data for Angolan pipeline survey applications. |
| Backward Integration into Pressure-Vessel Fabrication | Reduces fourteen-to-eighteen-month lead time exposure through South African yard partnerships. |
| Marine Research Data Acquisition Partnership | Captures higher-margin resolution specifications from Cape Town oceanographic institutions. |
| Hybrid System Development | Bridges tethered reliability requirements with untethered endurance for Gulf of Guinea inspection programs. |
Research Methodology
Desk research of subsea classification society filings, offshore drilling permit registries, and marine research vessel procurement records preceded structured interviews with ROV operations managers at Nigerian and Angolan offshore contractors, DNV certification auditors, and South African oceanographic fleet directors. Secondary validation drew from Department of Petroleum Resources safety bulletins, National Regulator for Compulsory Specifications pressure-vessel certification databases, and ARAMCO contractor qualification lists. Bottom-up vessel fleet enumeration triangulated against top-down offshore energy expenditure estimates.
Variance decomposition across product type, end user, service tier, and technology architecture shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included tethered versus autonomous platform categories, oil and gas versus marine research versus defense end-use applications, and electric versus hydraulic versus autonomous navigation propulsion systems. CAGRs derived from weighted average of historical deployment trajectories and regulatory-mandated fleet expansion requirements, with specific inputs for Nigerian ROV redundancy permit rules and Angolan autonomous trial acceleration.
Decision-makers should treat outputs as directional under base assumptions of sustained Brent crude price support for West African offshore development and stable DNV-ST-F203 certification timelines; material deviation in autonomous liability framework harmonization would warrant model refresh. Forecasts reflect these assumptions without guarantee of regulatory or technological path stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Aerostat System Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Asia-Pacific Unmanned Systems Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Drone Tethered Stations Market