
 Aerostat System Market | 2026-2036
Aerostat System Market Size, Share, and Industry Trends Forecast 2026-2036
Aerostat System Market Analysis
FAA airspace certification for tethered platforms above 500 feet is hardening the cost-of-entry calculus for new aerostat manufacturers seeking commercial contracts. Northrop Grumman Corporation leverages its integrated defense electronics portfolio to bundle radar payloads with aerostat envelopes for military end users. Lockheed Martin Corporation anchors its position through persistent investment in high-altitude, long-endurance tethered systems for government surveillance programs. TCOM L.P. specializes in the design and fielding of large-scale aerostats, sustaining decades of operational deployments across multiple climate zones.
An aerostat system comprises a lighter-than-air platform—typically filled with helium and constrained by a ground-tethered mooring system—equipped with electro-optical, infrared, or radar payloads for sustained aerial operations lasting days to weeks. These systems operate at altitudes from 500 feet to 15,000 feet, delivering persistent surveillance, communications relay, and environmental monitoring without the fuel consumption or crew requirements of fixed-wing or rotary aircraft. The military application segment dominates current procurement volumes, driven by border security and battlefield intelligence requirements, while the disaster management application segment is expanding as emergency services adopt aerostats for cellular network restoration and search coordination after infrastructure collapse. The communication technology segment is maturing rapidly, with remote sensing technology capturing growing interest for scientific research missions requiring atmospheric data collection.
The US FAA and Department of Defense jointly shape aerostat deployment through airspace integration rules and operational safety mandates, while India's DGFT and Ministry of Defence regulate import and indigenous production under strategic procurement guidelines. EASA in Europe enforces design certification standards that constrain cross-border military interoperability for non-CE-marked platforms. Stakeholders must monitor evolving airspace sovereignty frameworks as nations tighten control over low-altitude aerial domains where aerostats traditionally operate.
Market Dynamics
The aerostat market faces a structural tension between FAA airspace restrictions above 500 feet and military demand for higher-altitude persistent surveillance platforms. This regulatory ceiling is compressing commercial deployment options while accelerating specialized military procurement pathways.
Growth Catalysts
- India's Border Surveillance Modernization:The Ministry of Defence is expanding tethered aerostat procurement for persistent intelligence missions along contested frontiers. DGFT strategic procurement guidelines favor indigenous production partnerships.
- Helium Recovery Systems:Closed-loop gas management technology is reducing operational costs for long-duration deployments. Military operators in desert climates are prioritizing platforms with integrated reclamation capabilities.
- Coastal Perimeter Mandates:Saudi Arabia and the UAE are deploying networked aerostat arrays for maritime domain awareness. National security frameworks in both countries are funding multi-platform installations.
Market Restraints
- Helium Supply Concentration:Global helium extraction concentrates in Qatar, Russia, and the United States. Geopolitical disruptions to this triad create input cost volatility for envelope manufacturers.
- FAA Certification Barriers:Commercial tethered operations above 500 feet require extended airworthiness demonstrations. This regulatory friction blocks new entrants from accessing utility and telecommunications contracts.
- Satellite Substitution Threat:Low-Earth orbit constellations are displacing aerostats for certain communications relay applications. Starlink and comparable networks offer comparable coverage without mooring infrastructure.
Strategic Opportunities
- Disaster Cellular Restoration:Emergency management agencies are adopting rapid-deployment aerostats for network infrastructure replacement. FEMA and comparable organizations represent underpenetrated demand channels.
- Atmospheric Research Convergence:Integration of LiDAR with hyperspectral sensors is creating new scientific payload configurations. Research institutions are funding high-altitude data collection programs.
- EU Green Deal Alignment:Zero-emission aerial platforms qualify for sustainability-linked procurement preferences. EASA certification pathways for environmentally classified systems are accelerating.
Industry Challenges
- Aerodynamics Engineering Talent Scarcity:Lighter-than-air platform design requires specialized fluid dynamics expertise. Defense contractors are competing with commercial aviation for limited personnel pools.
- Payload Integration Complexity:Electro-optical and radar systems from disparate vendors demand extensive electromagnetic compatibility testing. Certification timelines extend by months for multi-sensor configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerostat System Market |
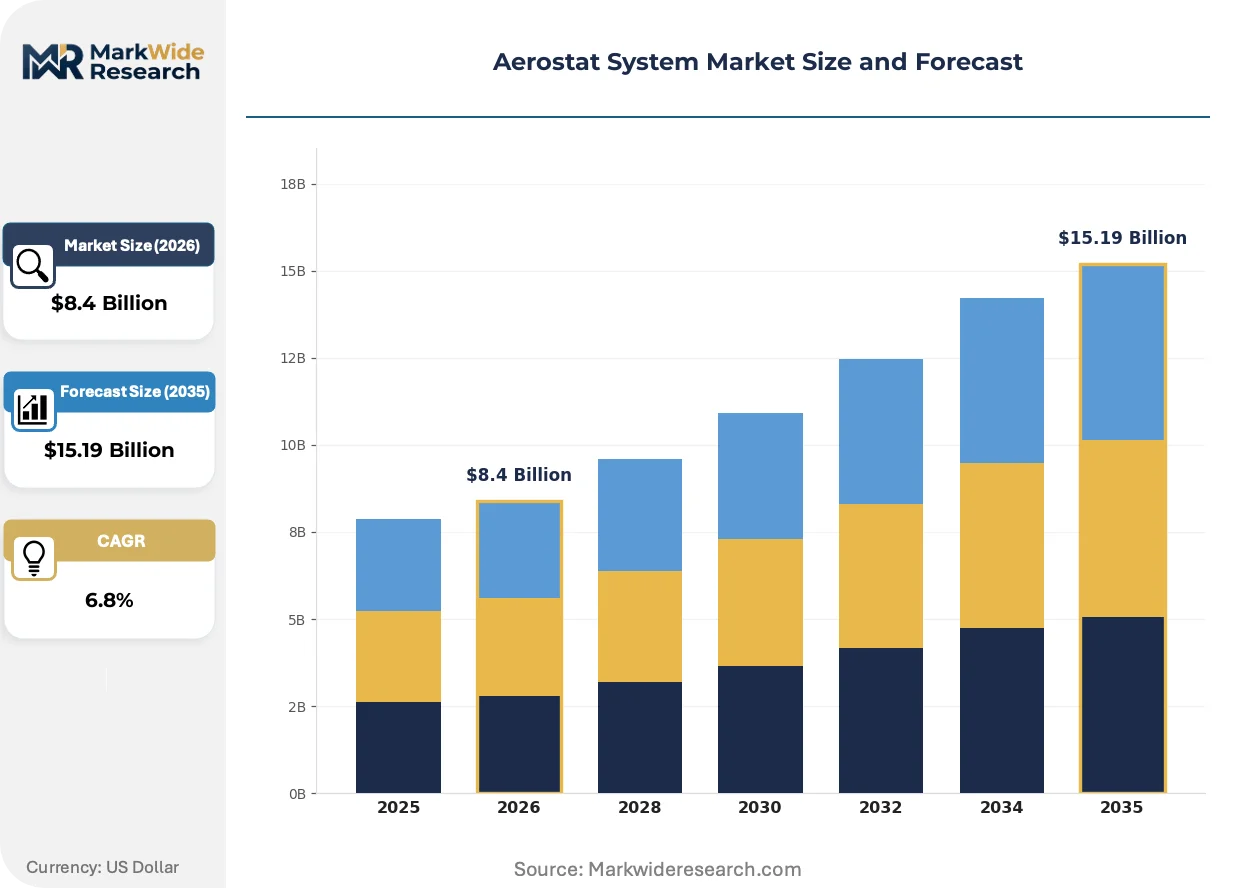
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Mobile, Tethered, Free-flying Technology: Observation, Communication, Remote Sensing, Surveillance Application: Military, Scientific Research, Disaster Management, Event Monitoring End User: Government, Defense Contractors, Research Institutions, Emergency Services |
| Companies Covered | Northrop Grumman Corporation, Raven Industries Inc., Lockheed Martin Corporation, QinetiQ, ILC Dover LP, Raytheon Technologies Corporation, Israel Aerospace Industries Ltd., Thales Group, TCOM L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerostat System Market Emerging Trajectories
Autonomous mooring systems and AI-enhanced stabilization are rewriting operational paradigms for tethered platforms. These advances are compressing crew requirements while extending mission endurance in adverse weather conditions.
Synthetic aperture radar miniaturization is rewriting payload economics for medium-altitude aerostats. Border security agencies in India and the Middle East are adopting these systems for through-cloud surveillance capability. The technology is compressing the cost gap between aerostat-mounted and airborne radar platforms.
The US FAA and Department of Defense are jointly revising airspace integration protocols for tethered systems in controlled corridors. This regulatory evolution is enabling beyond-visual-line-of-sight operations for military and select commercial applications. Defense contractors are accelerating certification investments to capture expanded operational envelopes.
Lifecycle service contracts are displacing equipment-only procurement in military segments. End-users in Saudi Arabia and the UAE are demanding integrated training, maintenance, and payload refresh guarantees. This shift is visible across Middle East defense procurement, where total-cost-of-ownership models now dominate evaluation criteria.
Aerostat System Market Segmentation
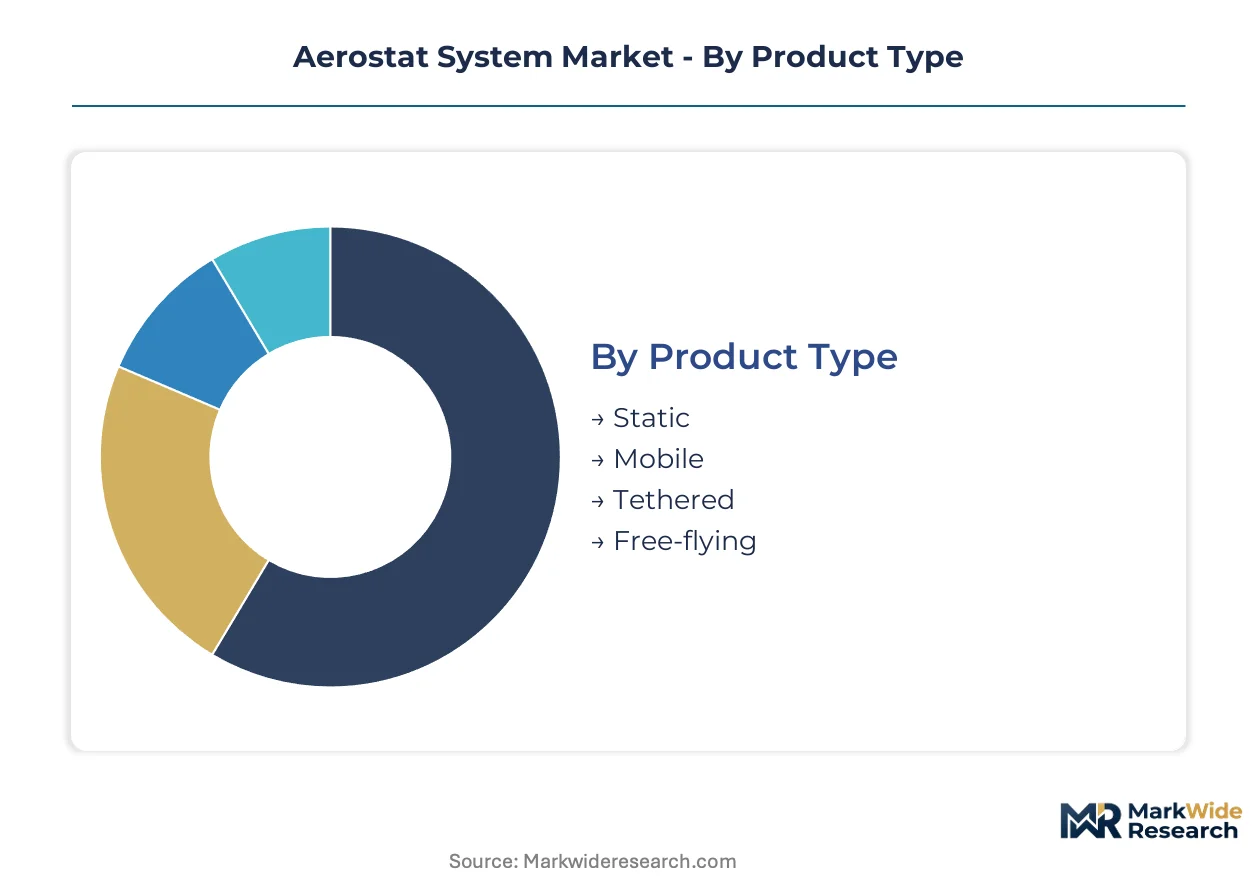
Aerostat procurement decisions pivot on altitude persistence requirements, payload integration complexity, and operational mobility constraints. Segment boundaries are blurring as military operators demand multi-mission platforms combining surveillance, communications relay, and environmental sensing in single deployments.
Product Type:
Defense procurement officers prioritize mission duration against relocation speed when selecting platform configurations.
- Tethered:Helium-filled envelopes constrained by ground-based mooring systems enable multi-week endurance at altitudes up to 15,000 feet. India's Ministry of Defence is expanding tethered procurement for persistent border intelligence along contested frontiers, with DGFT guidelines favoring indigenous production partnerships.
- Mobile:Rapidly deployable trailer-mounted systems with automated inflation and recovery sequences compress setup time to under 30 minutes. The US Department of Defense is accelerating mobile platform adoption under modernized aerial defense frameworks requiring expeditionary repositioning capability.
- Static:Permanent-site installations with fixed mooring infrastructure minimize per-mission operational costs for continuous coverage zones. Coastal perimeter mandates in Saudi Arabia and the UAE favor static arrays for maritime domain awareness.
- Free-flying:Unconstrained lighter-than-air platforms with autonomous navigation systems operate without ground tether limitations. Scientific research institutions deploy free-flying configurations for atmospheric data collection requiring transect mobility.
Volume sits with Tethered systems; growth tilts toward Mobile platforms.
Technology:
Payload selection determines power requirements, stabilization precision, and data throughput specifications for envelope sizing.
- Surveillance:Synthetic aperture radar and electro-optical/infrared sensor packages deliver through-cloud target detection for border security applications. Miniaturization is compressing the cost gap between aerostat-mounted and airborne radar platforms.
- Communication:Cellular and tactical radio relay payloads restore network infrastructure after natural disasters or battlefield damage. FEMA and comparable emergency management agencies represent underpenetrated demand channels for rapid-deployment communication aerostats.
- Observation:Day/night camera systems with stabilized gimbal mounts provide real-time visual monitoring for event security and perimeter defense. Stadium operators and critical infrastructure managers are adopting observation aerostats for crowd monitoring applications.
- Remote Sensing:LiDAR and hyperspectral sensor integration enables atmospheric composition analysis and terrain mapping. Research institutions are funding high-altitude data collection programs requiring precise altitude maintenance.
Defense contracts concentrate in Surveillance; expansion is steepest in Communication.
Application:
Mission profiles dictate payload weight budgets, weather tolerance thresholds, and crew certification requirements.
- Military:Intelligence, surveillance, and reconnaissance missions demand encrypted data links and electromagnetic hardening against countermeasures. Helium recovery systems with closed-loop gas management are reducing operational costs for desert climate deployments.
- Disaster Management:Cellular network restoration and search coordination after infrastructure collapse require rapid inflation and autonomous mooring capabilities. AI-enhanced stabilization is extending mission endurance in adverse weather conditions for emergency services operators.
- Scientific Research:Atmospheric data collection and environmental monitoring missions prioritize sensor precision over threat survivability. EASA certification pathways for environmentally classified systems are accelerating under EU Green Deal alignment.
- Event Monitoring:Temporary deployment for crowd control and traffic management at large public gatherings emphasizes quick setup and takedown cycles. Municipal security budgets are adopting short-duration aerostat rentals for major sporting and political events.
Military procurement dominates current volume; disaster management applications are climbing the fastest.
End User:
Contracting authority and funding mechanisms shape procurement evaluation criteria and vendor qualification requirements.
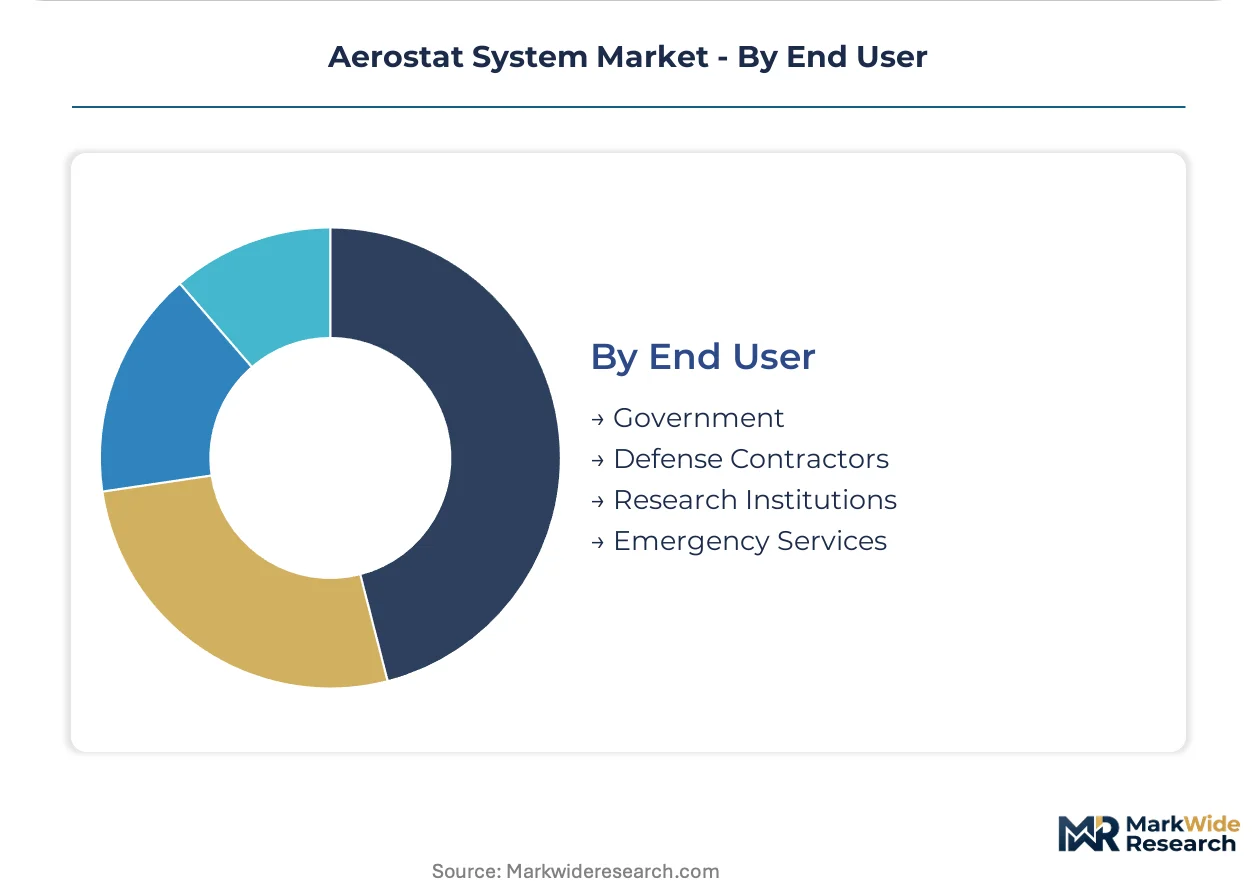
- Government:National security agencies and civilian departments with direct budget authority negotiate lifecycle service contracts displacing equipment-only procurement. Saudi Arabia and the UAE are demanding integrated training, maintenance, and payload refresh guarantees.
- Defense Contractors:Prime system integrators bundle aerostat platforms with radar and communications payloads for military end users. Northrop Grumman and Lockheed Martin leverage integrated defense electronics portfolios to capture bundled procurement awards.
- Research Institutions:Universities and national laboratories fund atmospheric science missions through competitive grant programs. Payload integration complexity extends certification timelines for multi-sensor scientific configurations.
- Emergency Services:Fire departments, police agencies, and medical response organizations adopt aerostats for incident command communications. FAA airspace certification barriers above 500 feet constrain commercial deployment options for municipal operators.
Defense Contractors and Government agencies split procurement volume; Emergency Services represent the most underpenetrated expansion channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense technology parks in the United States and aerospace clusters in Israel concentrate aerostat engineering talent and testing infrastructure. Special economic zones in India and the UAE accelerate manufacturing localization through tax abatements and import duty exemptions. National security procurement frameworks in Saudi Arabia and the UK channel government spending toward integrated surveillance platforms.
United States
The Department of Defense accelerates mobile aerostat procurement under modernized aerial defense frameworks requiring expeditionary repositioning capability. The FAA and DoD jointly revise airspace integration protocols for tethered systems in controlled corridors. Defense contractors in Maryland and California concentrate certification investments to capture expanded operational envelopes.
India
The Ministry of Defence expands tethered aerostat procurement for persistent intelligence missions along contested frontiers with Pakistan and China. DGFT strategic procurement guidelines favor indigenous production partnerships under the PLI scheme. Aerospace manufacturing clusters in Bangalore and Hyderabad host envelope fabrication and payload integration facilities.
Israel
Border security agencies deploy aerostat networks for Gaza and Lebanon perimeter monitoring with electromagnetic hardening against countermeasures. The national defense establishment regulates import and indigenous production under strategic procurement guidelines. Defense technology parks around Tel Aviv concentrate lighter-than-air platform engineering expertise.
Saudi Arabia
National security frameworks fund multi-platform aerostat installations for Red Sea and Persian Gulf maritime domain awareness. The General Authority for Military Industries mandates local content requirements for defense procurement awards. Industrial cities in the Eastern Province host static array mooring infrastructure and maintenance facilities.
United Kingdom
The Ministry of Defence procures tethered surveillance platforms for coastal and critical infrastructure protection under integrated security programs. EASA design certification standards constrain cross-border military interoperability for non-CE-marked platforms. Aerospace engineering clusters in Bristol and Farnborough concentrate payload integration and electromagnetic compatibility testing capabilities.
Aerostat System Market Vendor Landscape
United States producers anchor the premium systems tier; European and Israeli specialists hold differentiated positions in payload integration and regional defense markets. The vendor base concentrates around bundled platform-payload offerings and lifecycle service contracts displacing equipment-only procurement. Three archetypes dominate: integrated defense electronics conglomerates, lighter-than-air platform pure-plays, and national champions serving protected domestic markets. Competitive moves center on certification investments for expanded altitude envelopes and strategic partnerships with indigenous manufacturers in India and the Middle East.
Within the integrated defense electronics tier, Northrop Grumman Corporation and Lockheed Martin Corporation represent bundled procurement anchors combining radar payloads with aerostat envelopes for military end users. TCOM L.P. occupies a position as a lighter-than-air pure-play specialist sustaining decades of operational deployments across multiple climate zones. These three entities exemplify the strategic segmentation between diversified conglomerates leveraging cross-divisional synergies and focused specialists commanding envelope engineering depth.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Raven Industries Inc. |
| Lockheed Martin Corporation |
| QinetiQ |
| ILC Dover LP |
| Raytheon Technologies Corporation |
| Israel Aerospace Industries Ltd. |
| Thales Group |
| TCOM L.P. |
| Others |
Supply Flow & Price Mechanics
Captive helium sourcing through Qatar, Russia, and the United States anchors supply positions for envelope manufacturers while compressing margin flexibility for operators lacking long-term offtake contracts. This triad concentration forces procurement officers to accept price volatility or invest in reclamation infrastructure that reshapes total-cost-of-ownership calculations.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with rapid-deployment mobile platforms commanding substantial markups over standard tethered systems with 12-18 month delivery schedules. Three-tier pricing structure across expeditionary, standard, and legacy configurations reflects FAA certification tier and payload integration complexity. Cost compression in the commercial segment intensifies because satellite substitution threatens communications relay applications. Government defense contractors demonstrate lowest price sensitivity, while municipal emergency services operators face severe budget constraints.
Supply Chain Analysis
Refurbishment flows for mooring winches and sensor gimbals create secondary supply channels that extend platform lifecycles and dampen new equipment demand. Envelope fabrication draws from Qatar, the United States, and Russia for helium feedstock, with laminated fabric sourcing concentrated in aerospace clusters across Israel and the United Kingdom. Single-source vulnerability sits with specialized lighter-than-air engineering talent pools concentrated in Maryland, California, and Tel Aviv. Distribution runs through prime defense integrators bundling platforms with radar payloads for military end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
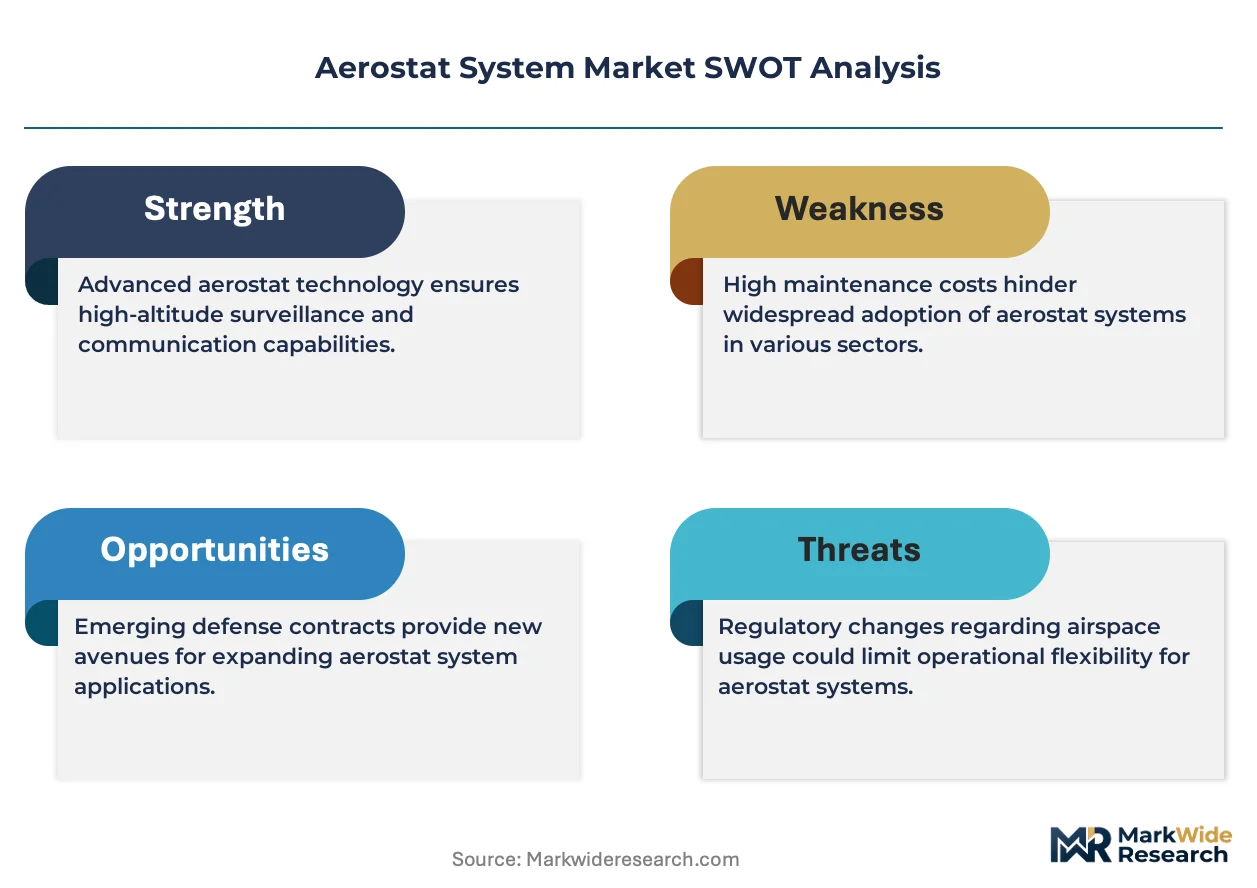
This market functions as a consolidation play where FAA certification barriers above 500 feet and helium supply concentration force capital-light entrants toward insolvency or acquisition.
For Market Incumbents: Deploy lifecycle service contracts to lock out competitors, converting equipment-only procurement into decade-long training and maintenance relationships. Northrop Grumman and Lockheed Martin already bundle radar payloads with aerostat envelopes, creating switching costs that emerging specialists cannot match. Satellite substitution threats from Starlink and comparable constellations demand payload diversification into atmospheric sensing and disaster communications restoration.
For New Entrants and Emerging Players: The premium-to-economy gap in mobile expeditionary platforms offers white-space entry for rapid-deployment specialists targeting FEMA and comparable emergency management agencies. Municipal disaster cellular restoration represents the most penetrable application segment, with AI-enhanced stabilization and autonomous mooring as the critical go-to-market differentiator. Partner with indigenous manufacturers in India under DGFT guidelines to access Ministry of Defence procurement channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor roll-ups seeking lighter-than-air platform capabilities for integrated surveillance offerings. Long-term viability favors specialists with helium reclamation technology and EASA environmental certification alignment under EU Green Deal frameworks. Monitor FAA airspace integration protocol revisions for tethered systems as the inflection signal for expanded commercial operational envelopes.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery System Integration | Closed-loop gas management reduces desert climate operational costs for Saudi and UAE military operators. |
| FAA Certification Investment | Extended airworthiness demonstrations unlock beyond-visual-line-of-sight operations for commercial telecommunications contracts. |
| Indigenous Manufacturing Partnership | DGFT-compliant production in Bangalore and Hyderabad secures Indian Ministry of Defence border surveillance awards. |
| Synthetic Aperture Radar Miniaturization | Through-cloud surveillance capability compresses cost gaps with airborne radar for India and Middle East border agencies. |
| Lifecycle Service Contract Conversion | Integrated training and maintenance guarantees displace equipment-only procurement in Saudi Arabia and UAE national security frameworks. |
Methodological Framework
Independent corroboration across defense procurement officers, aerostat platform engineers, and helium supply specialists underwrites the qualitative findings presented in this study. Primary interviews with Ministry of Defence acquisition leads in India, FAA certification consultants, and payload integration directors at aerospace clusters in Maryland and Tel Aviv combined with secondary validation from Department of Defense budget justifications, EASA design certification databases, and DGFT strategic procurement circulars. Bottom-up segment sizing and top-down macroeconomic anchoring triangulate volume and value estimates.
Comparable-period anchoring to historical defense procurement cycles and scientific research grant disbursement patterns structured the forecast window. Segmentation dimensions modeled include product type, payload technology, application mission profile, and end-user contracting authority across the projection horizon. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and technology substitution threats. Helium price volatility indices and FAA airspace integration timeline assumptions feed directly into scenario-weighted outputs.
Inputs from defense procurement databases and national laboratory grant records were available through the study window; gaps in commercial utility contract pricing introduce uncertainty bands around the telecommunications segment. Forecasts reflect documented assumptions about regulatory timeline acceleration and satellite constellation deployment rates. Practitioners should monitor FAA-DoD joint protocol revisions and Qatar helium export policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Lidar Drone Market