
 Military Robots Market | 2026-2036
Military Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Military Robots Market Analysis
The US Department of Defense's Replicator initiative is expanding the addressable market for attritable autonomous systems by streamlining procurement pathways and lowering certification barriers for non-traditional suppliers. Lockheed Martin Corporation leverages its Skunk Works division to sustain rapid prototyping cycles for tactical unmanned platforms. Elbit Systems Ltd. anchors Israeli defense exports through its Hermes UAV family and ground robotic systems. Rheinmetall AG competes in European mechanized warfare modernization with its Mission Master unmanned ground vehicle series.
Military robots encompass autonomous or remotely operated platforms engineered for combat support, reconnaissance, and force protection missions, typically integrating lithium-ion power systems, hardened communication links, and payload capacities ranging from five kilograms for tactical UAVs to multiple tons for ground logistics vehicles. The primary industrial purpose centers on substituting human operators in high-threat environments while extending situational awareness beyond visual line of sight. Unmanned Aerial Vehicles dominate current procurement volumes due to mature supply chains and proven ISR utility across multiple conflict theaters. Unmanned Ground Vehicles represent the fastest-expanding category as armies invest in last-mile logistics and counter-IED operations. Artificial Intelligence and Sensor Fusion technologies concentrate margin pools through software-defined capability upgrades that extend platform service lives without hardware replacement.
The US FAA and Department of Defense jointly regulate airspace integration and spectrum allocation for military unmanned systems, while the EU AI Act establishes risk-classification requirements for autonomous targeting algorithms that affect transatlantic technology transfer. China's MIIT and GB standards authorities enforce domestic content requirements that fragment supplier access for foreign component manufacturers. Stakeholders must monitor evolving lethal autonomous weapons governance at the UN Convention on Certain Conventional Weapons, as export control alignment on AI-enabled systems will determine which supplier nations retain market access in allied defense procurement networks.
Market Dynamics
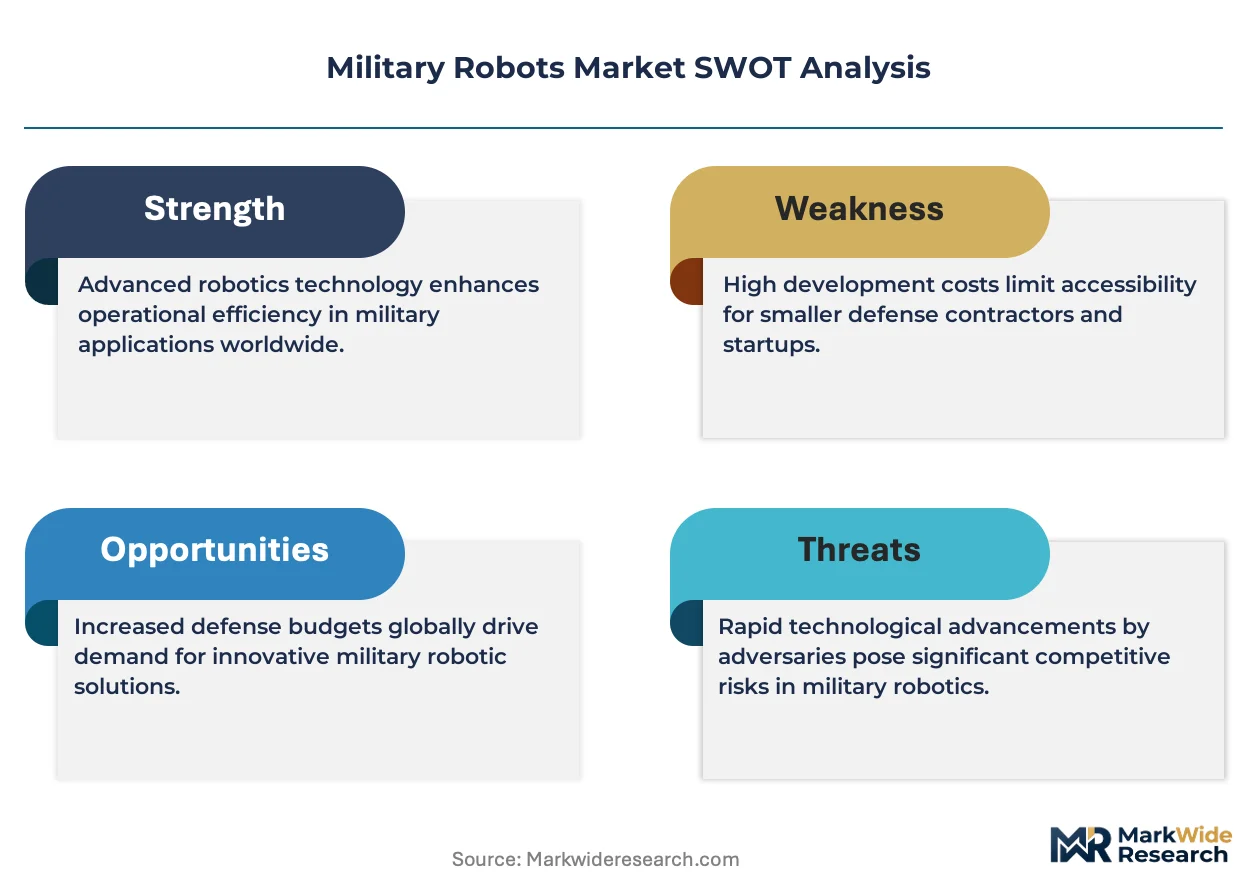
The US Department of Defense's Replicator initiative is compressing procurement cycles for attritable autonomous platforms and forcing defense primes to restructure supplier relationships around rapid iteration rather than decade-long development programs.
Growth Catalysts
- Replicator Initiative Procurement Reform:The Pentagon's mandate for thousands of low-cost autonomous systems by 2026 is opening acquisition pathways for non-traditional suppliers and accelerating fielding timelines.
- Counter-IED Operations:Ground forces in contested environments are deploying unmanned ground vehicles for route clearance and explosive ordnance disposal, reducing personnel exposure.
- AI-Enabled Sensor Fusion:Machine vision and multi-spectral payload integration are extending mission endurance without increasing operator headcount.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in China, creating vulnerability for Western defense supply chains under export control tensions.
- EU AI Act Compliance Burden:Risk-classification requirements for autonomous targeting algorithms are lengthening certification timelines for European suppliers seeking transatlantic contracts.
- Spectrum Allocation Friction:Military unmanned systems compete with commercial 5G and satellite operators for protected bandwidth, degrading communication link reliability in dense electromagnetic environments.
Strategic Opportunities
- Last-Mile Logistics Automation:Ground robotic systems for ammunition and medical resupply remain underdeployed relative to aerial platforms, creating white space for mechanized infantry units.
- Indo-Pacific Island Chains:Distributed operations across the Philippines, Japan, and Australia require attritable platforms that can operate beyond established logistics networks.
- Dual-Use Technology Transfer:Agricultural and mining autonomous navigation systems from commercial markets are compressing development costs for tactical ground vehicle programs.
Industry Challenges
- Autonomy Software Talent Scarcity:Defense contractors compete with commercial autonomous vehicle developers for machine learning engineers with security clearances.
- Legacy Platform Integration:New unmanned systems must interface with command-and-control networks designed for manned platforms, requiring expensive middleware development.
- Operational Test Timeline Compression:Rapid procurement mandates are colliding with established safety certification protocols, forcing trade-offs between fielding speed and reliability validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Robots Market |
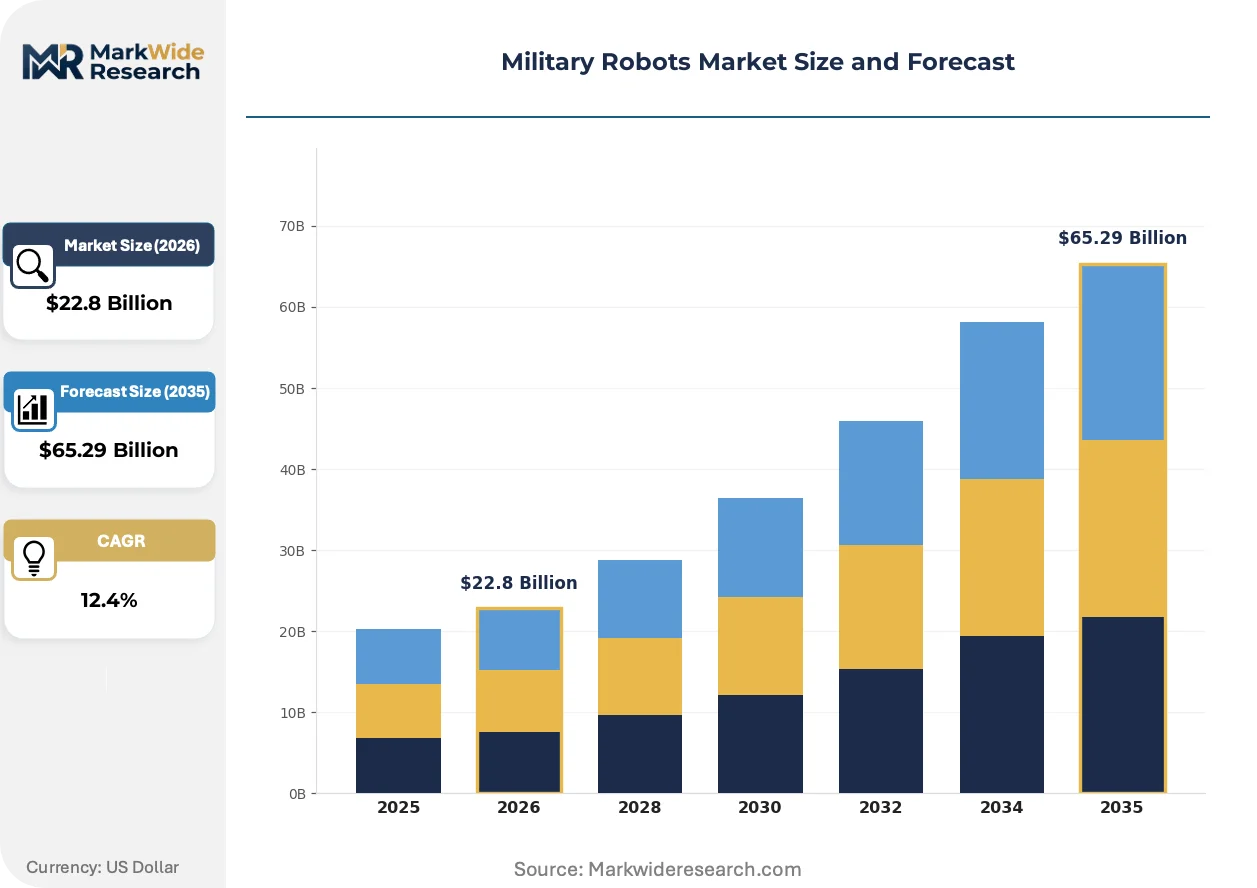
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $65.29 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Ground Vehicles, Unmanned Aerial Vehicles, Autonomous Underwater Vehicles, Robotic Exoskeletons End User: Defense Forces, Government Agencies, Private Security, Research Organizations Technology: Artificial Intelligence, Machine Learning, Navigation Systems, Sensor Fusion Application: Surveillance, Search and Rescue, Bomb Disposal, Logistics |
| Companies Covered | General Dynamics Corporation, Elbit Systems Ltd., Lockheed Martin Corporation, Rheinmetall AG, Raytheon, Northrop Grumman Corporation, Boeing, AeroVironment Inc, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Robots Market Emerging Trajectories
Defense procurement is pivoting from exquisite, high-unit-cost platforms toward swarming architectures and software-defined capabilities that allow hardware to evolve through over-the-air updates.
Swarm coordination algorithms are modularizing mission planning for unmanned aerial systems. Naval and ground forces are adopting distributed control architectures that allow single operators to manage multiple platforms simultaneously. This shift is compressing the cost-per-effect metric and enabling saturation tactics against integrated air defense networks.
The EU AI Act's risk-classification framework for autonomous weapons systems is forcing European suppliers to segregate development pipelines. Systems with human-in-the-loop targeting retain market access across NATO procurement networks, while fully autonomous engagement modes face export restrictions. German and French defense ministries are responding with dual-track certification programs.
Defense buyers are unbundling platform acquisition from sustainment contracts, treating autonomy software as a separately procured capability layer. The US Army's Robotic Combat Vehicle program exemplifies this pattern, with vehicle hulls sourced through traditional channels and perception stacks competed on 18-month refresh cycles. This bifurcation is most visible in reconnaissance and electronic warfare applications where algorithmic advantage decays rapidly.
Military Robots Market Segmentation
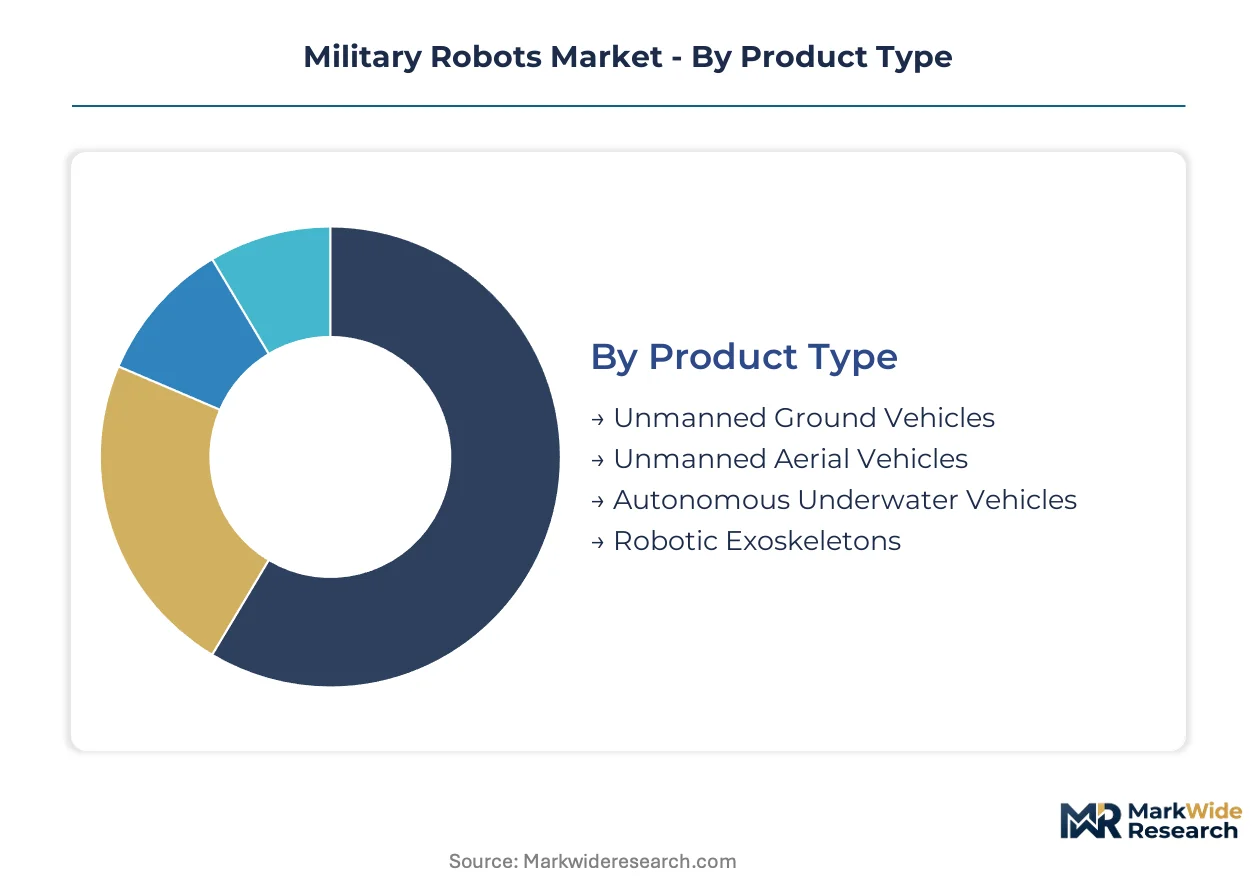
Military robot procurement varies sharply by mission profile and threat environment. Platform selection hinges on payload requirements, operator density constraints, and electromagnetic spectrum availability in contested theaters.
Product Type:
Standardization dominates high-volume attritable systems while customization persists in specialized ground platforms for explosive ordnance disposal and mine clearance.
- Unmanned Aerial Vehicles:Fixed-wing and rotary-wing configurations carry electro-optical, infrared, and signals intelligence payloads. Demand clusters in the United States for the Replicator initiative's thousands-unit procurement targets. Swarm-capable architectures are displacing single-platform ISR missions.
- Unmanned Ground Vehicles:Tracked and wheeled variants range from portable throwable robots to heavy logistics carriers. Israeli Defense Forces deploy these for route clearance in Gaza and Lebanon border operations. Counter-IED requirements drive procurement despite slower fielding timelines versus aerial systems.
- Autonomous Underwater Vehicles:Torpedo-shaped hulls with sonar arrays conduct seabed survey and mine countermeasures. Naval procurement concentrates in Australia and Japan for Indo-Pacific chokepoint monitoring.
- Robotic Exoskeletons:Powered frames reduce musculoskeletal load for ammunition handlers and logistics personnel. Development pipelines in France and Germany target heavy-lift applications for mechanized infantry.
Most installed capacity flows through Unmanned Aerial Vehicles. Expansion is steepest in Unmanned Ground Vehicles.
End User:
Volume concentrates in uniformed services with sovereign procurement authority while specialized capabilities fragment across civilian security and research channels.
- Defense Forces:Army, navy, and air force units account for the dominant procurement share with classified requirements driving platform customization. Budget cycles in the United States, China, and Israel determine annual contract awards.
- Government Agencies:Border patrol and coast guard organizations acquire modified military platforms for sovereign territory monitoring. European agencies prioritize dual-use certifications under EU AI Act constraints.
- Private Security:Corporate and critical infrastructure protection contracts specify reduced-capability variants with human-in-the-loop mandates. Demand remains constrained by liability frameworks and insurance costs.
- Research Organizations:Universities and defense laboratories source experimental platforms for algorithm development and human-machine teaming studies. Funding ties to national science foundations in Germany, the United Kingdom, and South Korea.
Defense Forces control the dominant share of fielded systems. Research Organizations are gaining share fastest through AI development partnerships.
Technology:
Hardware commoditization is shifting margin capture toward software layers that enable mission adaptation without platform replacement.
- Artificial Intelligence:Convolutional neural networks and reinforcement learning enable target recognition and path planning in GPS-denied environments. Deployment concentrates in the United States where the Department of Defense has relaxed acquisition pathways for algorithmic capabilities.
- Machine Learning:Supervised and unsupervised learning pipelines process multi-spectral sensor feeds for anomaly detection. Israeli platforms integrate these for urban terrain classification.
- Navigation Systems:Inertial measurement units, visual odometry, and celestial references provide positioning without satellite dependency. Chinese platforms emphasize indigenous Beidou integration for contested electromagnetic environments.
- Sensor Fusion:Multi-source data integration combines radar, electro-optical, and electronic warfare inputs into unified situational displays. NATO interoperability standards drive vendor consolidation around common data formats.
Navigation Systems anchor current procurement volumes. Artificial Intelligence commands the steepest investment trajectory.
Application:
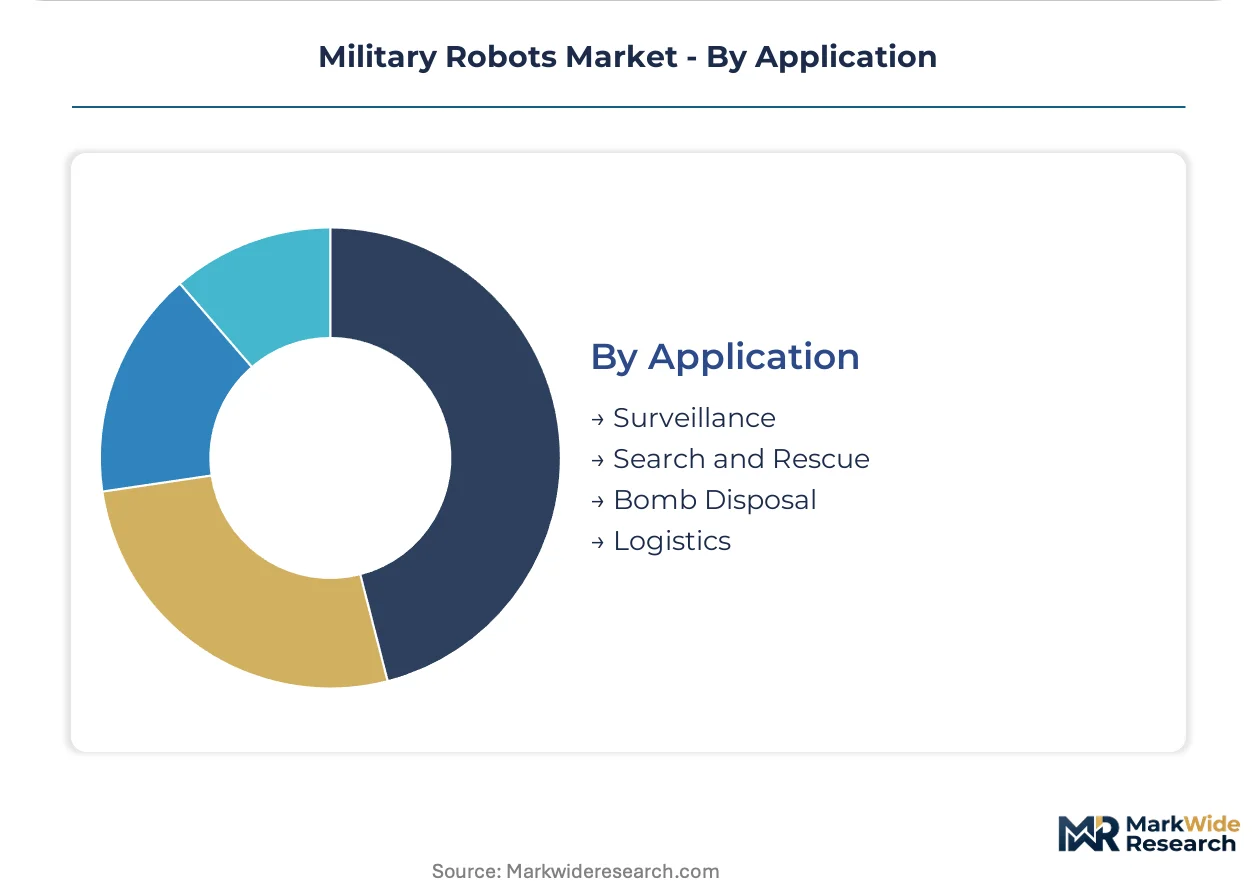
Mission type determines platform scale, autonomy level, and operator training requirements with logistics applications trailing surveillance in deployment maturity.
- Surveillance:Persistent wide-area motion imagery and signals intelligence collection dominate flight hours for aerial platforms. Indo-Pacific distributed operations in the Philippines and Japan drive demand for attritable systems with reduced signature.
- Search and Rescue:Thermal imaging and loudspeaker payloads support personnel recovery in disaster and combat scenarios. Alpine and maritime environments in Switzerland and Norway specify cold-weather endurance.
- Bomb Disposal:Manipulator arms and disruptor charges on ground platforms neutralize improvised explosive devices. Route clearance in Iraq and Afghanistan established operational doctrine now applied in Eastern Europe.
- Logistics:Ground resupply of ammunition, medical materiel, and rations reduces convoy exposure. The US Army's Robotic Combat Vehicle program and British Army trials represent early mechanized adoption.
Surveillance accounts for the largest deployed fleet. Logistics is climbing the fastest as ground forces address last-mile resupply gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense engineering talent clusters in the United States, Israel, and China anchor military robot development. These concentrations drive procurement patterns and shape supplier access across allied and contested markets.
United States
The Pentagon's Replicator initiative drives demand for attritable autonomous platforms at scale. The FAA and Department of Defense jointly regulate airspace integration and spectrum allocation for military unmanned systems. Defense contractors in the Washington DC-Virginia corridor and California's aerospace clusters compete for rapid prototyping contracts under compressed procurement timelines.
Israel
Border security operations and urban warfare doctrine sustain demand for unmanned ground vehicles and tactical UAVs. The Israeli Defense Forces' operational requirements shape export specifications for systems deployed in Gaza and Lebanon border zones. Elbit Systems and defense startups in the Tel Aviv metropolitan area concentrate development of electro-optical payloads and swarm coordination algorithms.
China
MIIT and GB standards authorities enforce domestic content requirements that fragment supplier access for foreign component manufacturers. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters host state-owned defense conglomerates developing indigenous navigation systems integrated with Beidou satellite infrastructure.
Germany
Mechanized warfare modernization programs drive procurement of unmanned ground vehicles for European NATO commitments. The EU AI Act's risk-classification requirements lengthen certification timelines for autonomous targeting algorithms. Rheinmetall and defense suppliers in North Rhine-Westphalia compete for Robotic Combat Vehicle program partnerships.
United Kingdom
Army trials for last-mile logistics automation create demand for ground resupply platforms. Ministry of Defence procurement aligns with NATO interoperability standards for sensor fusion and common data formats. BAE Systems and robotics developers in the Midlands and Southwest England focus on middleware integration with legacy command-and-control networks.
Military Robots Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base organizes around three strategic archetypes: primes managing system-of-systems integration, subsystem suppliers delivering autonomy software and sensor payloads, and emerging entrants exploiting streamlined acquisition pathways. Consolidation pressure intensifies as defense ministries unbundle platform acquisition from sustainment contracts. Competitive positioning hinges on security-cleared engineering capacity and demonstrated field reliability in contested electromagnetic environments.
Among US-based defense primes, Lockheed Martin Corporation and General Dynamics Corporation occupy positions in rapid prototyping cycles for tactical unmanned platforms. Elbit Systems Ltd. anchors Israeli defense exports through established relationships with Middle Eastern and European militaries. Rheinmetall AG exemplifies European mechanized warfare specialization through unmanned ground vehicle development for NATO modernization programs.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Elbit Systems Ltd. |
| Lockheed Martin Corporation |
| Rheinmetall AG |
| Raytheon |
| Northrop Grumman Corporation |
| Boeing |
| AeroVironment Inc |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Pentagon acquisition officers concentrated in the Washington DC-Virginia corridor negotiate platform-plus-software bundles that compress supplier margins on hardware while extracting premium pricing for autonomy software refresh cycles. The Replicator initiative's mandate for thousands of low-cost attritable units forces primes to absorb lithium-ion cell volatility through fixed-price contracts while algorithmic capability layers command recurring revenue streams.
Pricing Analysis
Platform-plus-software unbundling separates vehicle hull procurement from autonomy stack licensing across major defense programs. Three-tier pricing structure across mission-critical, standard-grade, and attritable-economy levels reflects certification burden and electromagnetic hardening requirements. Pricing pressure stems from the Replicator initiative's unit-cost ceilings for swarming aerial platforms. Government procurement officers exhibit highest price sensitivity on hardware hulls; special operations commands show lowest sensitivity for human-in-the-loop targeting systems.
Supply Chain Analysis
China's MIIT domestic-content mandates for Beidou navigation integration fragment supplier access for Western component manufacturers seeking People's Liberation Army contracts. Lithium-ion cell production concentrates in China, South Korea, and Japan; rare-earth magnet processing for electric drive systems rests on Chinese refining capacity. Single-source vulnerability runs through semiconductor foundry access for radiation-hardened chips. Distribution runs through defense primes managing tier-2 subsystem integration and direct government contracting offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined capability layers expand addressable margin pools as defense ministries shift procurement spend from hardware replacement toward algorithmic upgrade cycles. Autonomy talent scarcity and compressed fielding timelines create premium-capture opportunities for suppliers with security-cleared engineering benches.
For Market Incumbents: Anchor market position through captive production of lithium-ion battery management systems and in-house reinforcement learning pipelines for GPS-denied navigation. Lockheed Martin's Skunk Works rapid prototyping model and Elbit Systems' electro-optical payload vertical integration demonstrate defensible pathways against emerging autonomy-first entrants. Certification investment in EU AI Act human-in-the-loop compliance preserves NATO procurement access.
For New Entrants and Emerging Players: Swarm coordination algorithms offer technology-first wedge into the Replicator initiative's software procurement pathways. Last-mile logistics automation for mechanized infantry units represents the most penetrable white-space segment, with British Army trials and US Army Robotic Combat Vehicle program creating validated demand signals. Channel strategy should target direct relationships with program executive offices for rapid prototyping contracts rather than prime subcontractor positioning.
For Investors and Strategic Acquirers: Defense primes with autonomy software gaps are the most active acquirer in this space, with General Dynamics and Northrop Grumman demonstrating sustained appetite for machine vision and sensor fusion specialists. Five-to-ten-year viability hinges on security-cleared engineering capacity retention and demonstrated field reliability in contested electromagnetic environments. Watch for lethal autonomous weapons governance outcomes at the UN Convention on Certain Conventional Weapons as the critical inflection signal for export-controlled market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Software Acquisition | BAE Systems and Rheinmetall pursue machine vision specialists to close perception-stack gaps. |
| Domestic Battery Supply Agreement | US primes seek South Korean cell suppliers to reduce China-dependent lithium-ion exposure. |
| EU AI Act Compliance Certification | German and French ministries require human-in-the-loop validation for NATO export eligibility. |
| Swarm Coordination Platform Launch | AeroVironment and Elbit Systems compete for Replicator initiative thousand-unit procurement targets. |
| Indo-Pacific Logistics Partnership | Australian and Japanese naval programs drive autonomous underwater vehicle demand for chokepoint monitoring. |
Methodological Framework
Multiple input streams — program executive officer interviews, autonomy software engineer discussions, and defense procurement database analysis — were reconciled to construct market estimates. Primary fieldwork engaged rapid prototyping contract officers, electromagnetic spectrum managers, and subsystem integration leads at tier-1 and tier-2 suppliers. Secondary validation drew from Department of Defense budget justification materials, FAA airspace integration filings, and EU AI Act implementation guidance. Bottom-up platform deployment tallies and top-down defense ministry budget allocation analysis were cross-referenced for triangulation.
Historical procurement velocity was cross-referenced against expert panel assessments of Replicator initiative fielding timelines and Indo-Pacific distributed operations requirements. Segmentation modeling spanned platform type, mission application, autonomy level, and end-user service branch across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating procurement cycle compression, software refresh cadence, and lithium-ion supply constraint probabilities. Forecast inputs included Pentagon unmanned systems roadmap disclosures and Israeli Defense Forces operational deployment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lethal autonomous weapons governance resolutions and China-Taiwan semiconductor access disruptions. Assumptions regarding Replicator initiative funding continuity and EU AI Act certification timeline stability underpin the analytical framework. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Drone Tethered Stations Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Remote Weapon Systems Market