
 Global Particle Therapy Market | 2026-2036
Global Particle Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Particle Therapy Market Foresight
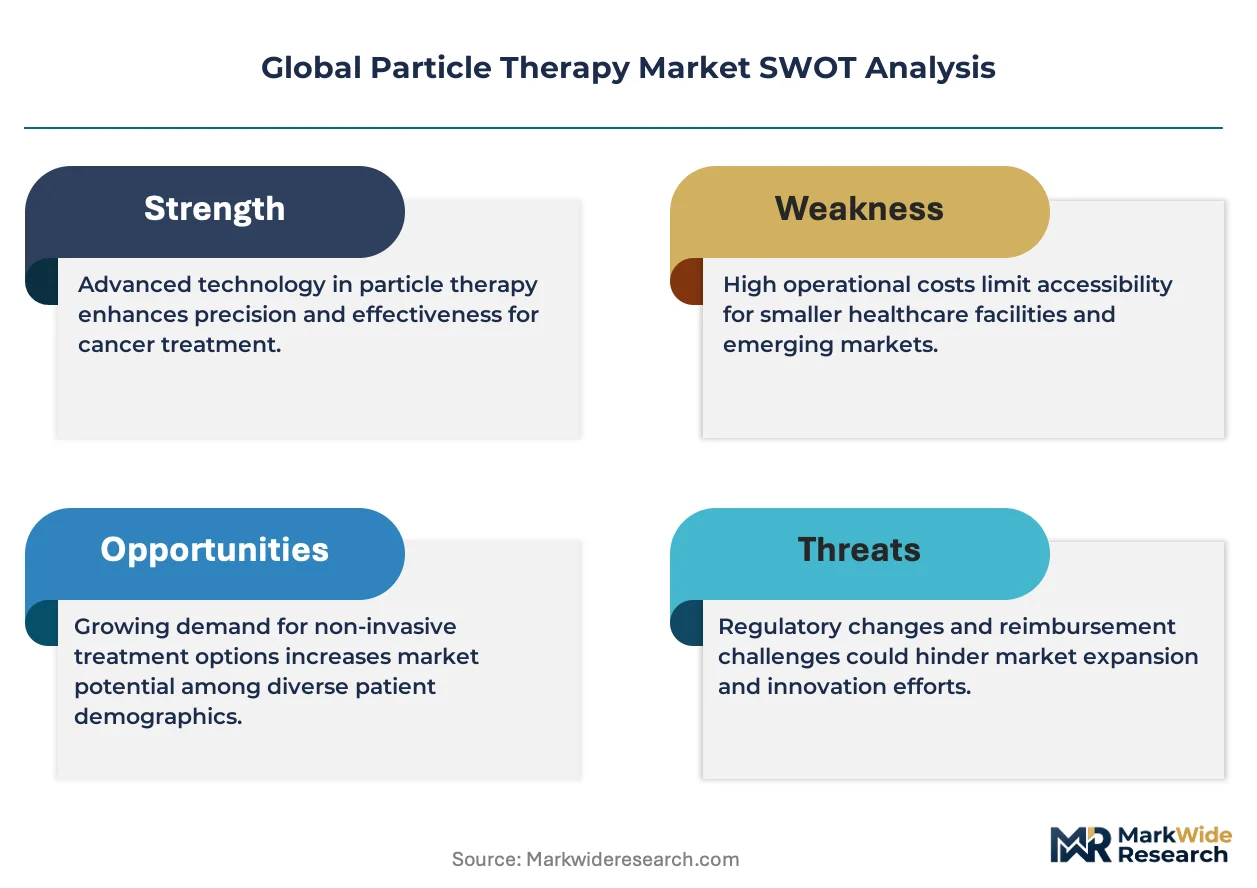
Modular single-room proton therapy configurations is broadening hospital procurement options beyond legacy multi-gantry facilities. IBA Worldwide leverages compact cyclotron designs to access mid-size oncology centers previously excluded from proton programs. Varian Medical Systems sustains R&D intensity across pencil-beam scanning software while Mevion Medical Systems anchors its position with superconducting synchrocyclotron platforms that reduce vault footprint.
Particle therapy directs accelerated protons, carbon ions, or neutrons to tumor sites with Bragg peak energy deposition that spares adjacent healthy tissue. Beam energy typically ranges from 70 to 250 MeV for protons, requiring isocentric gantries weighing 100-200 tons to rotate around supine patients. Pencil beam scanning dominates new installations for its dose-conformity advantage in complex tumor geometries. Proton therapy leads installed base volume while carbon ion therapy commands premium positioning in Asia-Pacific markets with dedicated heavy-ion research legacies. Academic medical centers represent the anchor end-user segment though specialized cancer clinics represent the fastest-growing facility category as ambulatory reimbursement models mature.
FDA 510(k) and PMA pathways govern US system approvals while EMA clinical evidence standards shape European reimbursement negotiations. Japan's PMDA and METI coordinate national health technology assessment for particle therapy inclusion in universal coverage. Stakeholders must monitor whether China's NMPA accelerates domestic superconducting cyclotron certification to alter import dependency patterns.
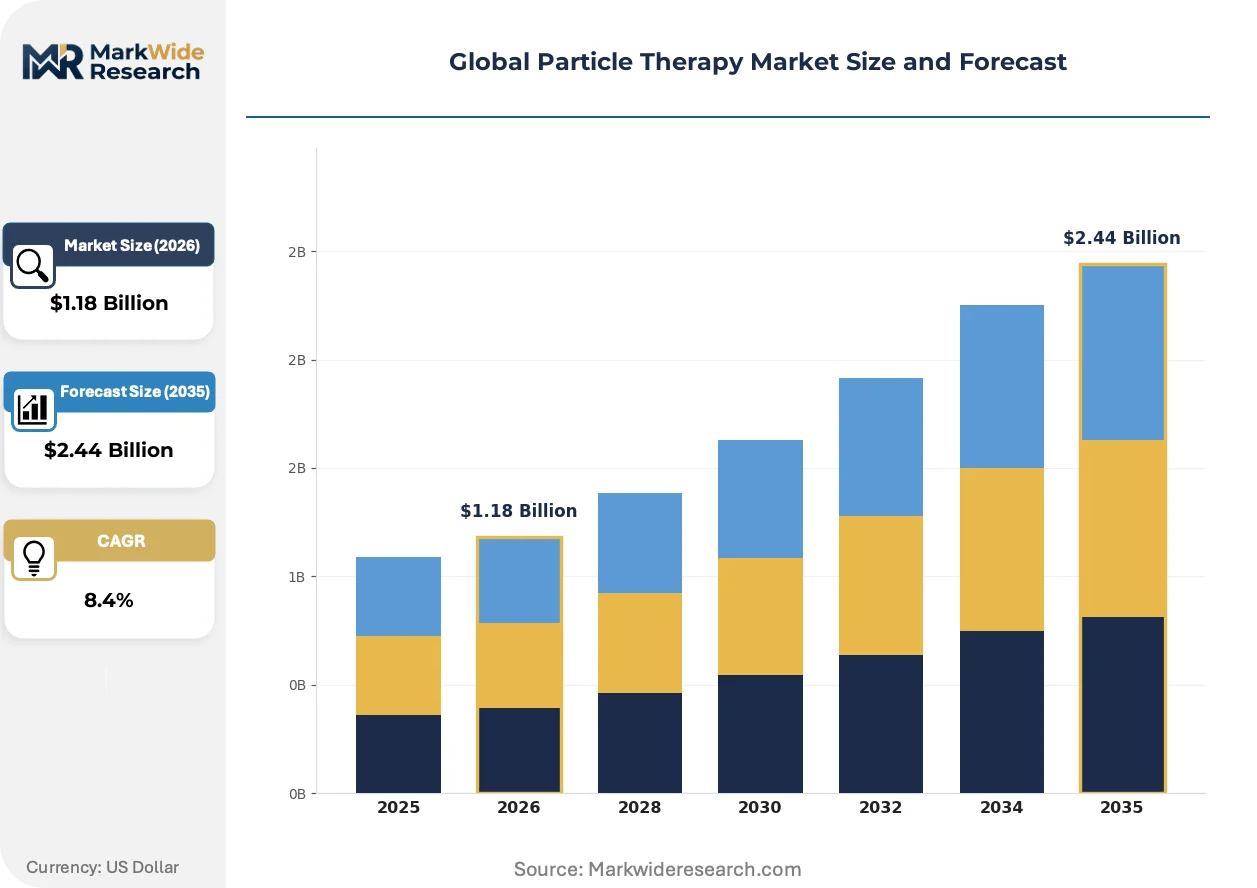
Market Dynamics
Compact single-room proton therapy systems are collapsing the minimum viable facility scale, enabling mid-size oncology centers in Germany, Japan, and the United States to enter particle therapy without the capital burden of multi-gantry campuses.
Growth Catalysts
- Japan's universal coverage inclusion:PMDA and METI coordination has embedded proton and carbon ion therapy into national health insurance, removing patient cost barriers and accelerating clinical volume.
- Pediatric oncology migration:Bragg peak tissue sparing is driving referral concentration to particle-capable centers treating childhood cancers, particularly medulloblastoma and sarcoma protocols.
- Pencil-beam scanning maturation:Dose-conformity software now enables intensity-modulated proton therapy for complex thoracic and abdominal tumors previously excluded from candidacy.
Market Restraints
- Superconducting magnet supply concentration:Niobium-titanium coil fabrication depends on a limited supplier base concentrated in Japan and Germany, creating lead-time vulnerability for cyclotron manufacturers.
- Vault construction cost escalation:Radiation shielding concrete and robotic gantry foundations require specialized contractors, with fixed-site preparation consuming 40-50% of total project budgets.
- Carbon ion therapy reimbursement gaps:Outside Japan and select German university hospitals, most national payers lack coding for heavy-ion modalities, restricting installed base expansion.
Strategic Opportunities
- India's emerging accreditation pathway:CDSCO and Atomic Energy Regulatory Board frameworks for medical cyclotron licensing are stabilizing, opening private hospital investment in Delhi and Mumbai corridors.
- Ambulatory surgery center integration:Same-day proton therapy protocols for ocular and superficial lesions could extend reach to outpatient networks with lower overhead structures than academic medical centers.
- Flash therapy convergence:Ultra-high dose-rate delivery systems combining proton beams with real-time imaging are creating preclinical partnerships between device manufacturers and radio-biology research consortia.
Industry Challenges
- Medical physicist training pipelines:Particle therapy planning and quality assurance require specialized certification beyond conventional radiotherapy residency, with fewer than 15 accredited training sites globally.
- Legacy cobalt-60 facility conversion:Existing gamma knife and linear accelerator suites face structural incompatibility with proton vault specifications, forcing greenfield construction rather than retrofit expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Particle Therapy Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Proton Therapy, Carbon Ion Therapy, Neutron Therapy, Boron Neutron Capture Therapy Beam Delivery Technology: Pencil Beam Scanning, Passive Scattering, Spot Scanning, Uniform Scanning Therapy Indication: Central Nervous System Tumors, Head & Neck Cancer, Lung Cancer, Pediatric Tumors End User Facility: Academic Medical Centers, Specialized Cancer Clinics, Research Institutes, Oncology Rehabilitation Centers |
| Companies Covered | Mevion Medical Systems, Siemens Healthineers, IBA Worldwide, Optivus Proton Therapy, Provision Healthcare, Varian Medical Systems, Sumitomo Heavy Industries, ProTom International, Hitachi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Particle Therapy Market Shifts & Advancements
Real-time adaptive planning and magnetic resonance guidance are compressing treatment margins and enabling hypofractionated protocols that challenge conventional fractionation economics.
Superconducting synchrocyclotron miniaturization is rewriting facility deployment economics. Mevion's 250 MeV platform eliminates the need for beam transport lines, reducing footprint to single-room configurations. Community hospital systems in the United States and regional cancer networks in Germany are adopting these systems at twice the pace of multi-gantry installations. The technology is compressing the addressable market from academic consortia to mid-capital oncology providers.
EMA's Medical Device Regulation (MDR) clinical evidence requirements are reshaping European procurement timelines. Class III device certification now demands prospective outcome data rather than predicate equivalence, extending system validation periods. German and Dutch university hospitals are front-loading clinical trial investment to secure reimbursement contracts, while Italian and Spanish centers delay procurement until post-market registries mature.
Hospital purchasing committees are unbundling equipment acquisition from long-term service contracts, treating proton therapy platforms as capital assets with competitive maintenance sourcing. German hospital groups now tender multi-vendor technical support separately from cyclotron purchase agreements. This pattern is most visible in North Rhine-Westphalia and Bavaria, where procurement centralization has compressed service margin structures for incumbent suppliers.
Global Particle Therapy Market Segmentation
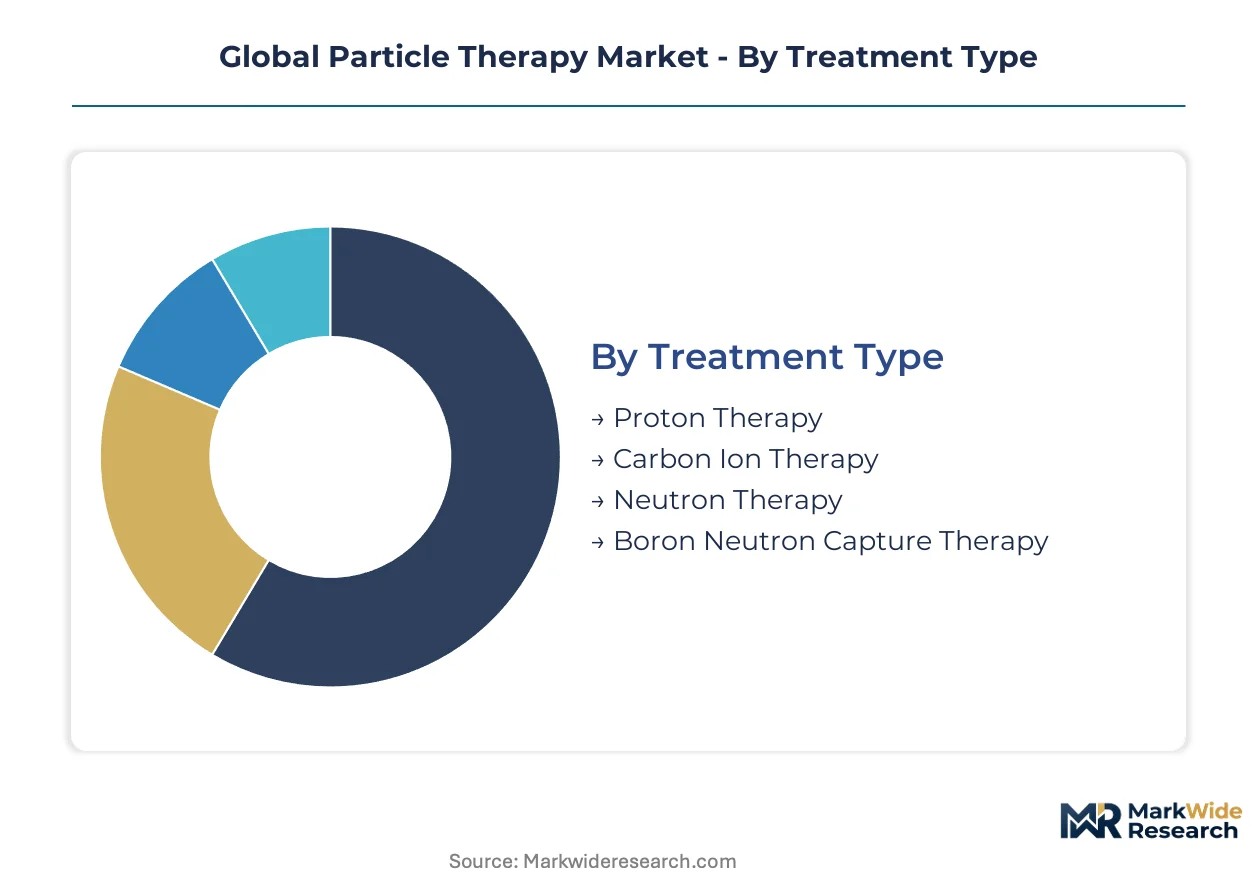
Particle therapy segmentation reveals how technical specifications, clinical protocols, and facility economics create distinct procurement pathways. Treatment modality selection directly constrains cyclotron energy requirements, vault shielding specifications, and reimbursement coding complexity.
Treatment Type:
Standalone proton systems dominate installed capacity, while carbon ion platforms embed into national research consortia with heavy-ion physics legacies.
- Proton Therapy:Accelerated hydrogen nuclei deliver Bragg peak deposition at 70-250 MeV, enabling precise dose conformality for solid tumors adjacent to critical organs. Demand concentrates in pediatric oncology centers across the United States, Germany, and Japan where tissue-sparing protocols command premium reimbursement.
- Carbon Ion Therapy:Heavy-ion beams provide enhanced relative biological effectiveness for hypoxic and radioresistant tumors, requiring synchrotron accelerators with substantially higher capital footprints. Installations cluster in Japanese university hospitals and select German facilities with established nuclear physics research infrastructure.
- Neutron Therapy:Fast neutron beams target salivary gland and prostate malignancies with high linear energy transfer characteristics.
- Boron Neutron Capture Therapy:Binary radiation modality combines thermal neutron irradiation with boron-10 pharmaceutical targeting for glioblastoma protocols.
Proton therapy leads volumes today; carbon ion therapy is gaining share fastest in Asia-Pacific markets with government-funded research commitments.
Beam Delivery Technology:
Cost tier stratification separates precision-scanning platforms from legacy scattering systems, with pencil-beam configurations commanding 40-60% equipment premiums.
- Pencil Beam Scanning:Magnetically deflected proton beams paint dose layer-by-layer with millimeter precision, enabling intensity-modulated proton therapy for irregular tumor geometries. New installations in the United States and Germany now specify pencil-beam as standard configuration, displacing passive scattering for complex thoracic and abdominal indications.
- Passive Scattering:Physical compensators and collimators shape broad proton beams, maintaining installed base relevance for uniform-field ocular and superficial treatments. Budget-constrained community hospitals in Germany's regional cancer networks retain passive systems for established prostate and breast protocols where anatomical complexity remains limited.
- Spot Scanning:Discrete spot positioning with adaptive energy modulation optimizes dose homogeneity for moving targets.
- Uniform Scanning:Continuous lateral beam sweep produces field uniformity without discrete spot overlap calculations.
Pencil beam scanning leads volumes today; spot scanning is expanding most quickly for lung and liver motion-management applications.
Therapy Indication:
Patient volume distribution follows pediatric referral patterns and hypofractionation eligibility, with CNS and pediatric tumors anchoring academic medical center economics.
- Central Nervous System Tumors:Skull base meningiomas and optic pathway gliomas require sub-millimeter precision to preserve cranial nerve function, making CNS protocols the reference indication for proton therapy commissioning. German university hospitals in Heidelberg and Essen report CNS cases comprising 35-45% of annual particle therapy volume.
- Pediatric Tumors:Medulloblastoma, ependymoma, and sarcoma protocols exploit Bragg peak sparing of developing bone marrow and soft tissues. St. Jude Children's Research Hospital and Boston's Massachusetts General Hospital anchor North American pediatric referral networks with dedicated proton programs.
- Head & Neck Cancer:Parotid and oropharyngeal malignancies benefit from salivary gland dose reduction.
- Lung Cancer:Motion-compensated proton delivery addresses thoracic tumor tracking challenges.
Central nervous system tumors lead volumes today; pediatric tumors are climbing the fastest as referral networks mature.
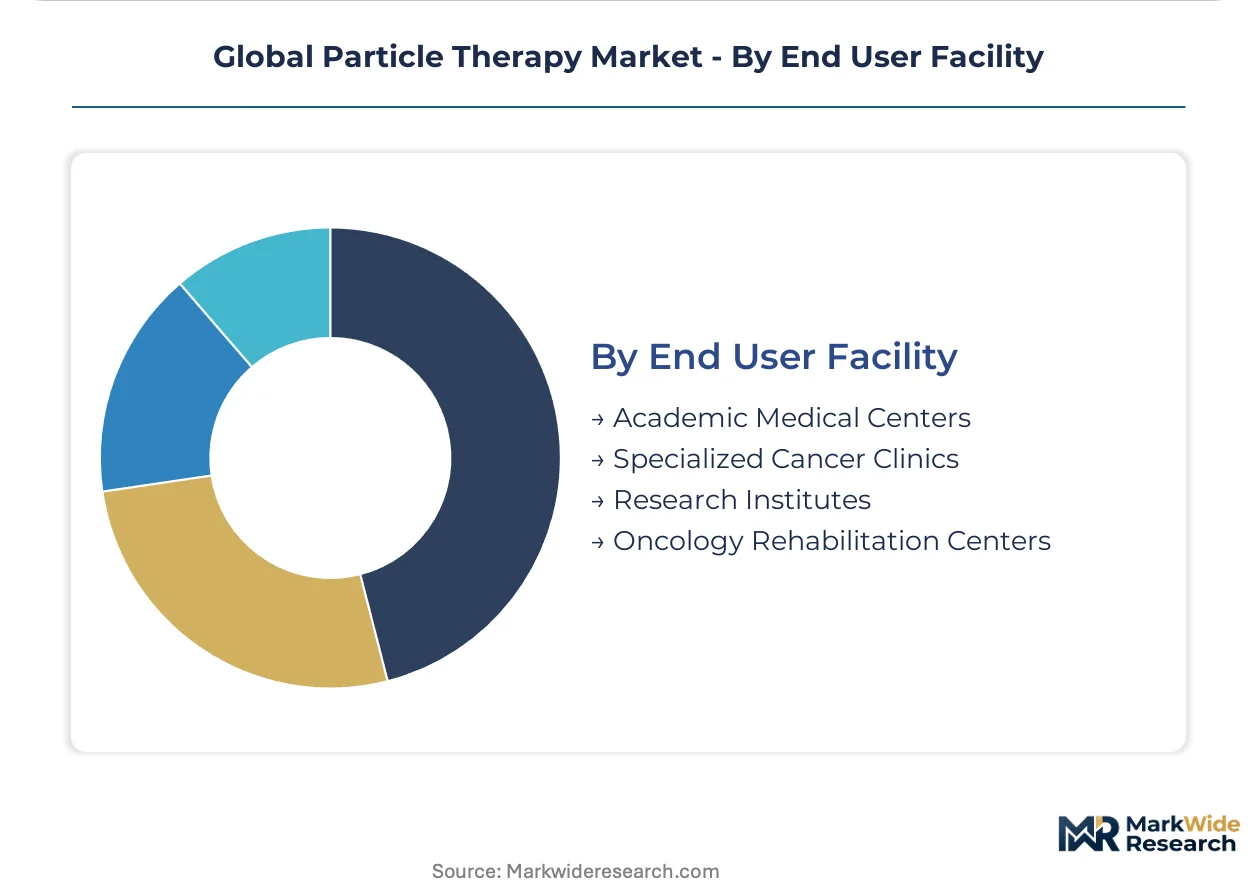
End User Facility:
Customer type determines procurement scale, with academic consortia demanding multi-gantry research platforms and specialized clinics accepting single-room configurations.
- Academic Medical Centers:Multi-disciplinary oncology institutes with residency programs require research-enabling beam lines, gantry redundancy, and integrated imaging suites. The University of Texas MD Anderson Cancer Center and Japan's National Cancer Center East anchor global proton research output with 3-4 gantry installations.
- Specialized Cancer Clinics:Focused oncology providers in Germany's North Rhine-Westphalia and Bavaria regions deploy compact single-room systems to capture regional patient flows without academic overhead structures. These facilities are expanding most quickly as ambulatory reimbursement models stabilize.
- Research Institutes:National laboratories and heavy-ion physics centers advance beam delivery physics and radiobiology protocols.
- Oncology Rehabilitation Centers:Post-treatment recovery facilities integrate particle therapy access into comprehensive cancer care pathways.
Academic medical centers lead volumes today; specialized cancer clinics represent the steepest expansion trajectory as single-room economics democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Particle therapy infrastructure originated at Harvard Cyclotron Laboratory and University of California radiation centers during the 1950s-1960s, establishing the United States as the foundational market before Japanese and German national programs scaled clinical adoption in subsequent decades.
United States
Pediatric oncology referral networks and private proton center investment drive system procurement. FDA 510(k) and PMA pathways govern cyclotron approvals, with recent single-room clearances shortening time-to-market. Massachusetts General Hospital and MD Anderson Cancer Center anchor multi-gantry research consortia in Boston and Houston metropolitan clusters.
Germany
Regional cancer networks and university hospital procurement centralization expand single-room system adoption. EMA MDR clinical evidence requirements reshape validation timelines, with Heidelberg and Essen facilities front-loading trial investment. North Rhine-Westphalia and Bavaria hospital groups now tender technical support separately from equipment purchase.
Japan
Government-funded heavy-ion research legacies and universal coverage inclusion accelerate carbon ion therapy volume. PMDA and METI coordinate national health technology assessment, embedding proton and carbon modalities into reimbursement. National Cancer Center East in Chiba prefecture anchors multi-gantry proton research output.
China
Domestic superconducting cyclotron development and private hospital investment in tier-one cities reshape import dependency patterns. NMPA certification timelines for medical accelerators influence procurement decisions. Shanghai and Beijing medical centers lead early adoption of compact proton configurations.
India
CDSCO and Atomic Energy Regulatory Board frameworks for medical cyclotron licensing stabilize, opening private hospital investment. Delhi and Mumbai corridors concentrate initial procurement interest. Tata Memorial Centre in Mumbai anchors national radiation oncology research capacity.
Global Particle Therapy Market Competitive Landscape
The competitive structure tilts toward integrated radiation therapy platform conglomerates with cyclotron manufacturing heritage. Three to four manufacturers control cyclotron supply, while specialized proton therapy system vendors compete on single-room deployment economics. Strategic archetypes include multi-modality imaging conglomerates, compact cyclotron specialists, and heavy-ion synchrotron builders. Competitive moves center on superconducting magnet miniaturization R&D and service contract unbundling.
Among United States-based proton therapy specialists, Mevion Medical Systems and Varian Medical Systems exemplify contrasting scale strategies, with the former anchoring superconducting synchrocyclotron miniaturization and the latter sustaining software-intensive pencil-beam scanning platforms. IBA Worldwide represents the Belgian integrated radiation therapy conglomerate archetype with cyclotron manufacturing depth. These three occupy positions spanning compact single-room deployment through multi-gantry academic installations.
| Leading Market Players |
|---|
| Mevion Medical Systems |
| Siemens Healthineers |
| IBA Worldwide |
| Optivus Proton Therapy |
| Provision Healthcare |
| Varian Medical Systems |
| Sumitomo Heavy Industries |
| ProTom International |
| Hitachi Ltd |
| Others |
Supply & Pricing Matrix
Medical physicist certification scarcity concentrated in Japan and Germany widens pricing-tier spreads between academic medical centers and community hospital installations, as specialized labor costs propagate through service contract premiums and training surcharge structures.
Pricing Analysis
Equipment-plus-service bundling with unbundled maintenance tendering now dominates procurement, separating cyclotron capital acquisition from multi-year technical support agreements. Price differentiation separates pencil-beam scanning configurations from passive scattering systems, with software-enabled precision commanding substantial premiums. Cost compression in single-room system tiers is intensifying because German hospital groups now competitively source maintenance separately from equipment purchase. Community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize research-enabling beam line redundancy over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with niobium-titanium superconducting coil fabrication concentrated in Japan and Germany, constraining cyclotron manufacturing throughput. Geographic supply concentration centers on Japanese heavy-ion research infrastructure, German precision engineering clusters, and United States compact system assembly. Raw material dependencies encompass high-purity niobium, radiation-grade concrete additives, and specialized robotic gantry bearings. Tariff exposure on Japanese-sourced superconducting magnets threatens lead-time reliability for European and North American installations. Distribution runs through direct manufacturer-hospital contracting with regional service subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Particle Therapy Market compounds steadily as pediatric oncology referral networks institutionalize tissue-sparing protocols into standard-of-care guidelines across major reimbursement markets.
For Market Incumbents: Hedge against service margin compression by deepening in-house production of superconducting magnet assemblies and securing long-term niobium supply agreements. Incumbent cyclotron manufacturers face emerging competition from domestic Chinese superconducting platform developers; vertical integration into coil fabrication restores pricing power eroded by unbundled procurement tendering. For New Entrants and Emerging Players: Compact synchrocyclotron miniaturization offers the most penetrable wedge for mid-capital community hospital systems previously excluded from proton programs. White-space targets include India's Delhi-Mumbai corridor where CDSCO licensing frameworks stabilize, and ambulatory surgery center integration for same-day ocular protocols. A software-first go-to-market emphasizing adaptive planning algorithms differentiates against legacy hardware-centric incumbents. For Investors and Strategic Acquirers: Radiation therapy platform conglomerates represent the most active acquirer category in this space, consolidating cyclotron manufacturing depth with pencil-beam scanning software capabilities. Long-term viability favors targets with FDA-cleared single-room configurations and established German or Japanese service infrastructure. Monitor China's NMPA domestic certification acceleration as an inflection indicator for import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Superconducting Magnet Miniaturization R&D | Mevion's 250 MeV platform eliminates beam transport lines, collapsing facility footprint requirements for community hospitals. |
| Service Contract Unbundling Response | German hospital groups in North Rhine-Westphalia now tender multi-vendor technical support separately from cyclotron purchase agreements. |
| Pencil-Beam Scanning Software Development | Varian sustains R&D intensity across dose-conformity algorithms for complex thoracic and abdominal tumor geometries. |
| Domestic Cyclotron Certification Pathway | China's NMPA acceleration of superconducting cyclotron certification would alter import dependency patterns for tier-one medical centers. |
| Flash Therapy Preclinical Partnership | Ultra-high dose-rate delivery systems create research consortia between device manufacturers and radio-biology institutions. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and emerging markets, with primary inputs from each region combined with secondary validation. The research incorporated interviews with proton therapy center medical directors, cyclotron manufacturing engineering leads, hospital purchasing committee administrators, and GPO contracts managers. Secondary sources encompass FDA 510(k) and PMA filing databases, EMA Medical Device Regulation guidance documents, Japan's PMDA reimbursement assessment publications, and hospital procurement database records. Bottom-up installation tracking and top-down reimbursement coverage analysis were triangulated against manufacturer shipment disclosures.
Rate-of-change decomposition structured the analytical framework across the projection horizon, modeling particle therapy adoption through treatment modality, beam delivery technology, therapy indication, and end-user facility type dimensions. CAGRs were derived from facility installation pipelines, reimbursement inclusion trajectories, and pediatric oncology protocol migration patterns. Industry-specific forecast inputs included superconducting magnet supply lead times and vault construction cost indices for radiation shielding materials.
The model holds under stable reimbursement inclusion and superconducting magnet supply continuity; deviation in tariff regimes or domestic certification acceleration in China would shift installation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Veterinary Oncology Market
Oncology
Internal Radiation Therapy Market
Oncology
Radiotherapy Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Testicular Cancer Treatment Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Sterile Oncology Injectable Market
Oncology
Cancer Supportive Care Products Market
Oncology
Metastases Spinal Tumor Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Esophageal Cancer Market
Oncology
Pancreatic Cancer Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Metastatic Cancer Drug Market