
 Europe Tumor Ablation Market | 2026-2036
Europe Tumor Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tumor Ablation Market Insights
Hospital procurement consortia across Europe is reconfiguring how tumor ablation systems reach end users, with centralized tendering now governing device selection in France and Italy. Medtronic Plc leverages its broad interventional portfolio to sustain multi-year supply agreements with large university hospital networks. Boston Scientific Corporation anchors its position through specialized cryoablation platforms for renal and prostate applications. Johnson & Johnson MedTech competes by integrating ablation catheters with its existing laparoscopic instrument ecosystems.
Tumor ablation encompasses percutaneous and intraoperative techniques that destroy neoplastic tissue through thermal energy delivery, typically achieving target temperatures of 50–100°C for coagulative necrosis or −40°C for cryogenic cell death, with primary purpose being curative or palliative treatment of solid organ malignancies in patients who are poor surgical candidates. Radiofrequency ablation dominates installed base volumes across European hospitals due to mature reimbursement codes and broad interventional radiology training, while microwave ablation represents the fastest-expanding technology segment as its larger ablation zones and shorter procedure times attract adoption in lung and liver applications. Cryoablation occupies a specialized margin pool in kidney and prostate cases where tissue preservation and procedural visibility carry premium clinical value.
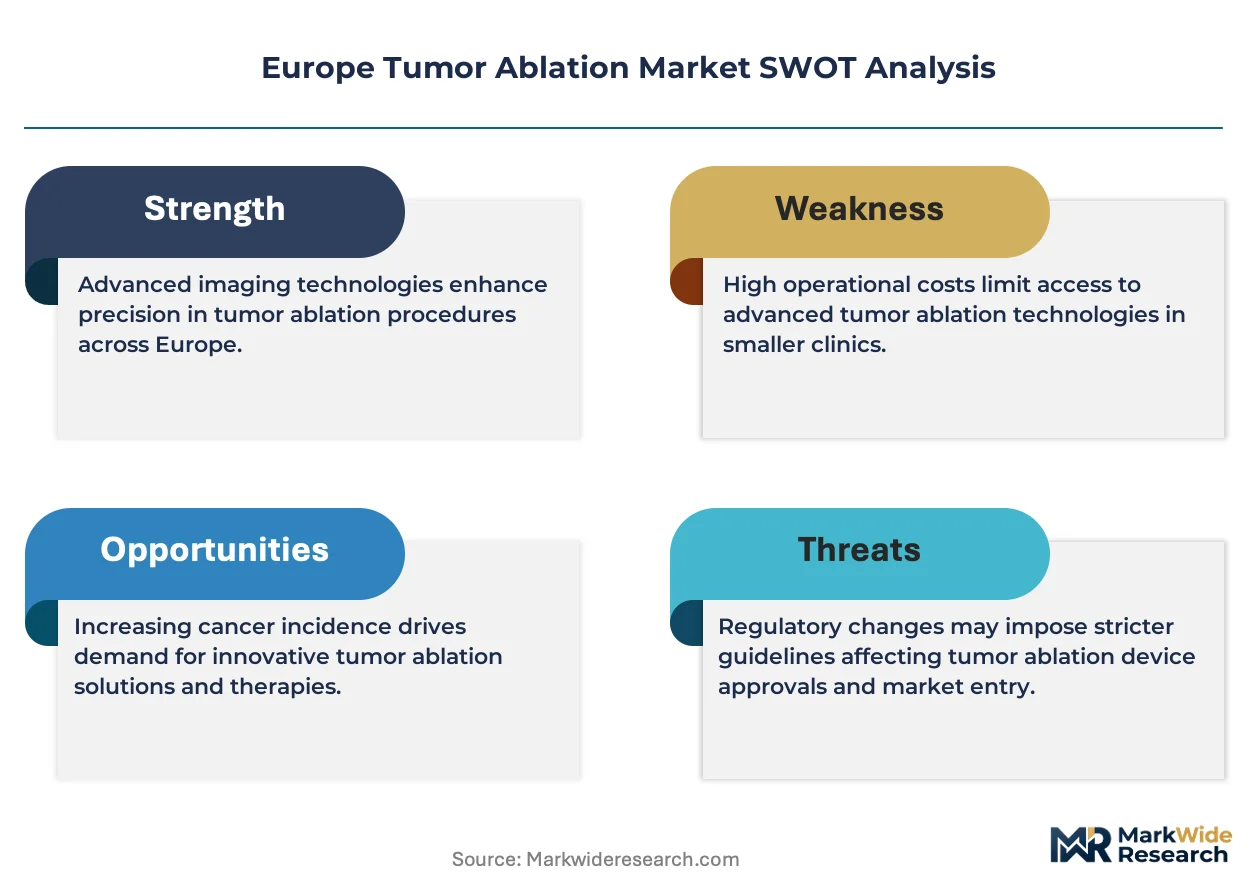
The EU Medical Device Regulation (MDR) and notified bodies in Germany, France, and the Netherlands are extending clinical evaluation requirements for class III ablation devices, compelling manufacturers to generate post-market surveillance data that reshapes product lifecycle economics. EMA guidance on combination products and the F-Gas Regulation governing cryoablation refrigerants add compliance layers that filter market access for smaller device firms. Stakeholders must monitor how national health technology assessment bodies in Germany and France calibrate reimbursement for emerging microwave and irreversible electroporation modalities against established radiofrequency benchmarks.
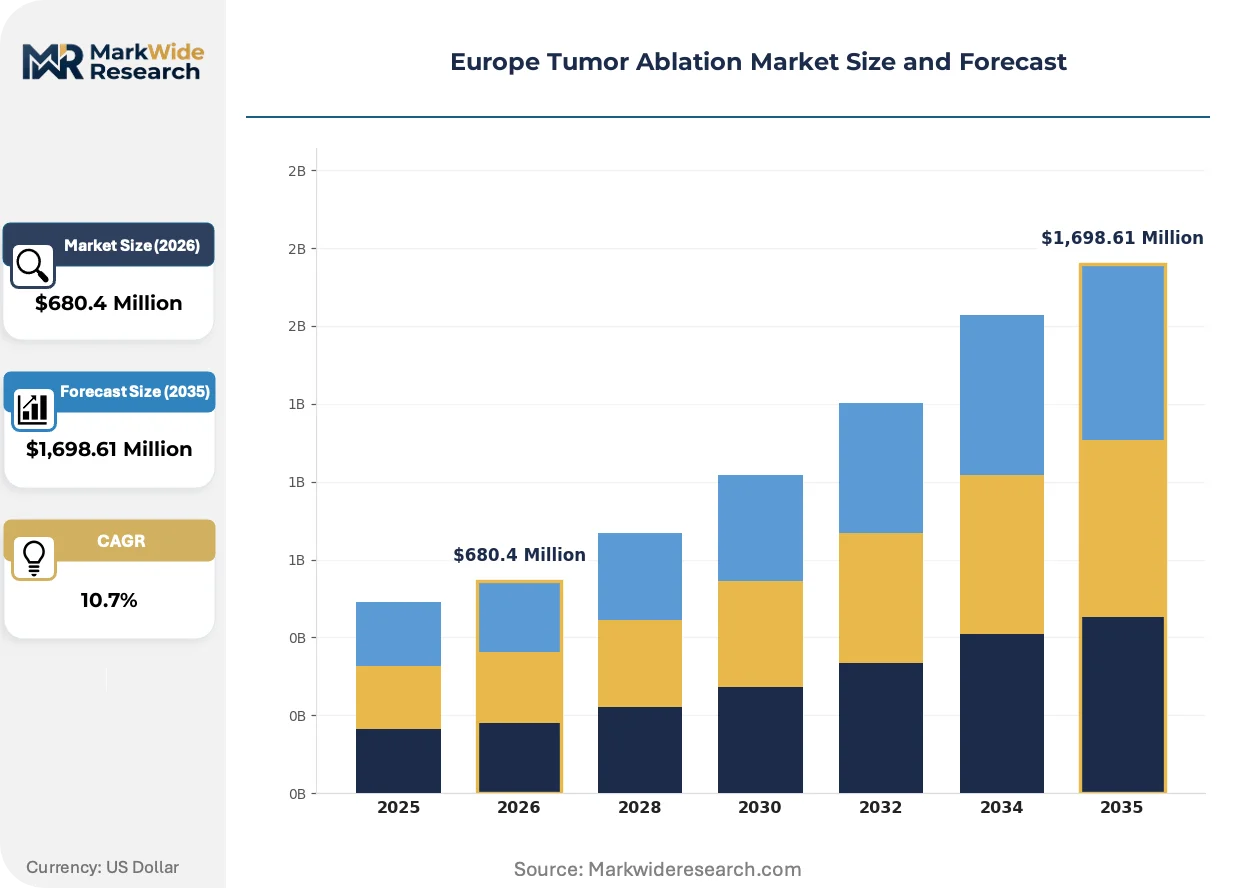
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product lifecycles by forcing manufacturers into larger pivotal trials and continuous post-market surveillance, fundamentally altering how thermal ablation devices reach European interventional radiology centers.
Growth Catalysts
- MDR clinical evidence mandates:Stricter notified body scrutiny in Germany, France, and the Netherlands is filtering out marginal competitors and consolidating procurement around established thermal ablation platforms with robust trial data.
- Microwave ablation adoption:Interventional radiology centers in Germany are replacing radiofrequency systems for liver and lung cases, drawn by larger ablation zones and reduced procedure times.
- Interventional oncology training expansion:University hospital networks across Italy and Spain are building dedicated ablation programs, creating installed base demand for multi-modality systems.
Market Restraints
- F-Gas Regulation compliance costs:The EU F-Gas Regulation governing cryoablation refrigerants is adding material cost layers and supply uncertainty for argon-based systems.
- Reimbursement stagnation in France:National health technology assessment bodies have frozen percutaneous ablation tariff updates, compressing hospital margin pools for new device acquisition.
- Radiofrequency installed base lock-in:Mature reimbursement codes and standardized training curricula across European hospitals slow microwave and irreversible electroporation conversion cycles.
Strategic Opportunities
- Poland and Eastern European hospital consolidation:Regional procurement centralization in Warsaw and Prague is creating single-tender opportunities for multi-system contracts.
- Irreversible electroporation for pancreatic lesions:Non-thermal cell death mechanisms open curative treatment for tumors adjacent to critical structures, a segment radiofrequency cannot safely address.
- Outcome-based procurement pilots:Dutch hospital consortia are testing device leasing tied to complication rates and recurrence-free survival metrics.
Industry Challenges
- Interventional radiologist training bottlenecks:Fellowship programs in Italy and Spain produce insufficient operators to match expanding ablation capacity, stretching procedure throughput.
- MDR technical documentation burden:Class III device recertification timelines now stretch 18-24 months, freezing product iteration cycles and freezing smaller manufacturers from portfolio refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tumor Ablation Market |
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,698.61 Million |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Microwave Ablation, Cryoablation, Laser Ablation End User: Hospitals, Oncology Clinics, Research Laboratories, Specialty Centers Technology: Image-Guided, Non-Image Guided, Thermal Techniques, Mechanized Systems Application: Liver Cancer, Lung Cancer, Kidney Tumors, Bone Metastases |
| Companies Covered | Medtronic Plc, Boston Scientific Corporation, AngioDynamics, Johnson & Johnson MedTech, Stryker Corporation, EDAP TMS, Mermaid Medical, HealthTronics, Galil Medical Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tumor Ablation Market Trends and Innovations
Real-time imaging fusion and energy delivery control systems are transforming how European interventional radiologists plan and execute tumor ablation, compressing the gap between diagnostic imaging and therapeutic intervention.
Microwave ablation technology is digitizing procedure workflow through integrated impedance monitoring and automated power modulation. German university hospitals are deploying these systems for lung metastasis cases at accelerating rates. The technology is digitizing how ablation margins are confirmed intraoperatively, reducing dependency on post-procedure contrast imaging.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules for cryoablation platforms. Manufacturers face reformulation investments or supply chain restructuring for argon-based systems. Renal and prostate application segments are absorbing compliance costs through premium pricing, while lung and liver cryoablation volumes contract.
Centralized tendering through hospital procurement consortia is consolidating vendor relationships across France and Italy. Large university hospital networks now negotiate multi-year supply agreements spanning ablation generators, disposable electrodes, and service contracts. This concentration is most visible in Paris and Milan, where three-consortium structures govern 60 percent of device selection decisions.
Europe Tumor Ablation Market Segmentation
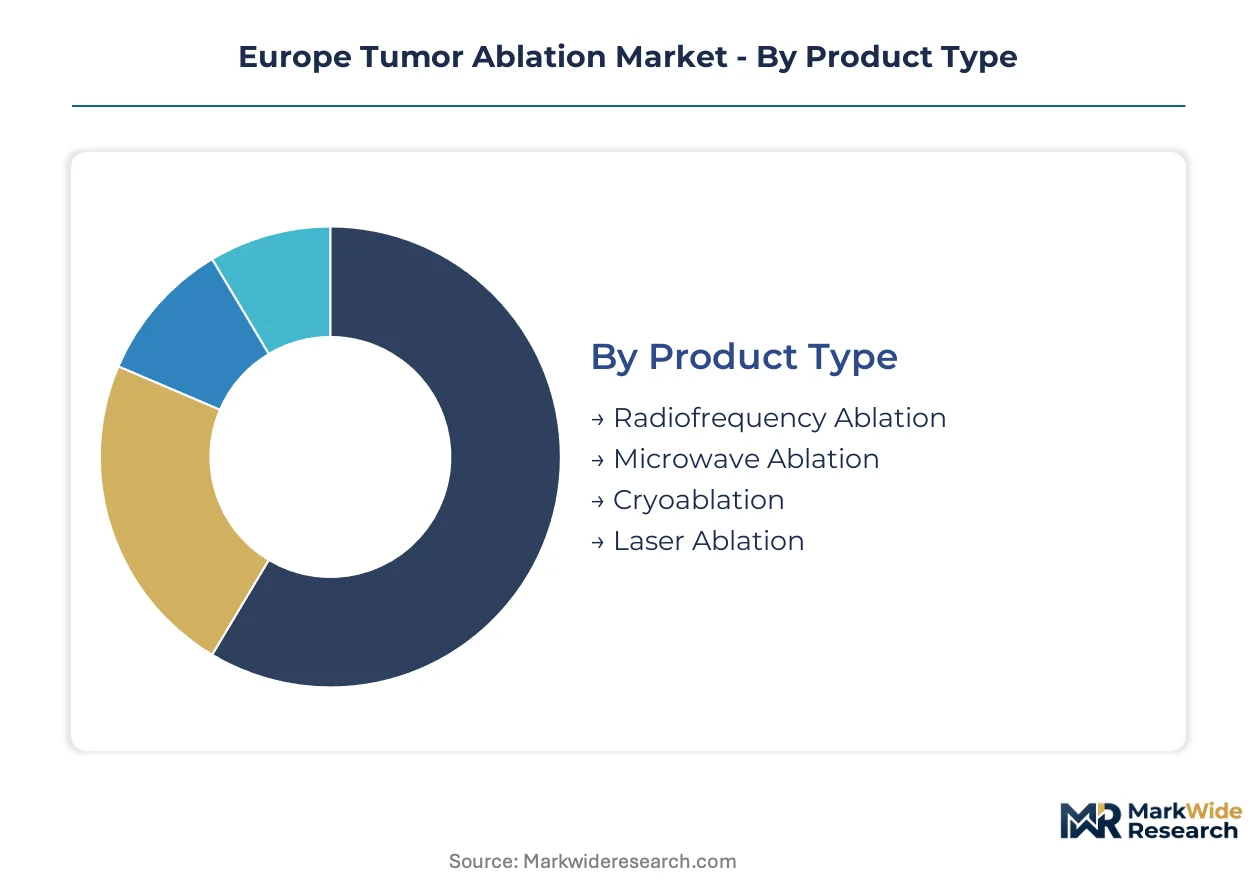
Segmentation in Europe's tumor ablation market reveals how procurement decisions, clinical training pathways, and regulatory compliance burdens cluster around specific technology modalities. Understanding these divisions exposes where service intensity, margin concentration, and competitive positioning diverge across the value chain.
Product Type:
After-sales service intensity varies sharply across ablation modalities, with cryoablation systems demanding refrigerant logistics and specialized preventive maintenance that reshape vendor economics.
- Radiofrequency Ablation:Electromagnetic energy delivery through needle electrodes generates thermal coagulation at 60–100°C, with impedance monitoring ensuring complete necrosis. German interventional radiology centers anchor installed base demand, where mature reimbursement codes and standardized fellowship training sustain replacement cycles despite longer procedure times.
- Microwave Ablation:Electromagnetic radiation at 915 MHz or 2.45 GHz produces larger ablation zones with faster heat induction, reducing operative time for liver and lung lesions. Italian university hospitals in Milan and Rome are converting installed bases most aggressively, drawn by procedural throughput gains in high-volume oncology networks.
- Cryoablation:Argon-helium gas cycles create −40°C iceballs for renal and prostate applications where tissue preservation matters. The EU F-Gas Regulation is compressing refrigerant supply security and forcing service contract restructuring.
- Laser Ablation:Nd:YAG or diode laser fibers deliver precise thermal destruction for small, deep-seated lesions. Research laboratories in the Netherlands pilot MRI-guided configurations.
By volume, radiofrequency ablation leads. By growth pace, microwave ablation is ahead.
End User:
Procurement authority concentrates differently across customer types, with hospital consortia wielding multi-year tender power while specialty centers negotiate on clinical outcome metrics.
- Hospitals:Academic medical centers and large regional hospitals deploy hybrid operating suites combining laparoscopic and percutaneous capabilities. French hospital procurement consortia in Paris and Lyon govern device selection through centralized tenders covering generators, electrodes, and service agreements.
- Oncology Clinics:Dedicated interventional oncology facilities in Germany and Spain focus on outpatient percutaneous procedures, requiring compact generator footprints and rapid electrode turnover. Reimbursement stability under national health insurance frameworks supports capital investment.
- Research Laboratories:University-affiliated centers in Belgium and Switzerland pilot next-generation modalities including irreversible electroporation and histotripsy. Funding depends on competitive grant cycles and industry collaboration.
- Specialty Centers:Urology-focused facilities in the UK and prostate clinics in Italy prioritize cryoablation for organ-sparing tumor control. Premium pricing absorbs higher device and refrigerant costs.
By installed base, hospitals dominate. By expansion rate, oncology clinics are climbing fastest.
Technology:
Margin structures diverge between imaging-integrated and standalone systems, with fusion platforms commanding premium pricing and recurring software licensing.
- Image-Guided:Real-time CT, MRI, or ultrasound navigation with electromagnetic tracking enables sub-centimeter targeting precision. German centers lead adoption of cone-beam CT integration for lung ablation.
- Non-Image Guided:Anatomical landmark-based needle placement persists in resource-constrained settings and emergency interventions. Eastern European regional hospitals retain these systems for cost containment.
- Thermal Techniques:Radiofrequency, microwave, and cryogenic modalities constitute the clinical standard, with temperature monitoring and impedance feedback ensuring safety margins. EMA guidance on thermal damage thresholds shapes validation requirements.
- Mechanized Systems:Robotic needle positioning and automated energy delivery are emerging in high-throughput French and Dutch centers. Capital intensity limits penetration to flagship institutions.
By procedural volume, thermal techniques dominate. By capability investment, image-guided systems are gaining share fastest.
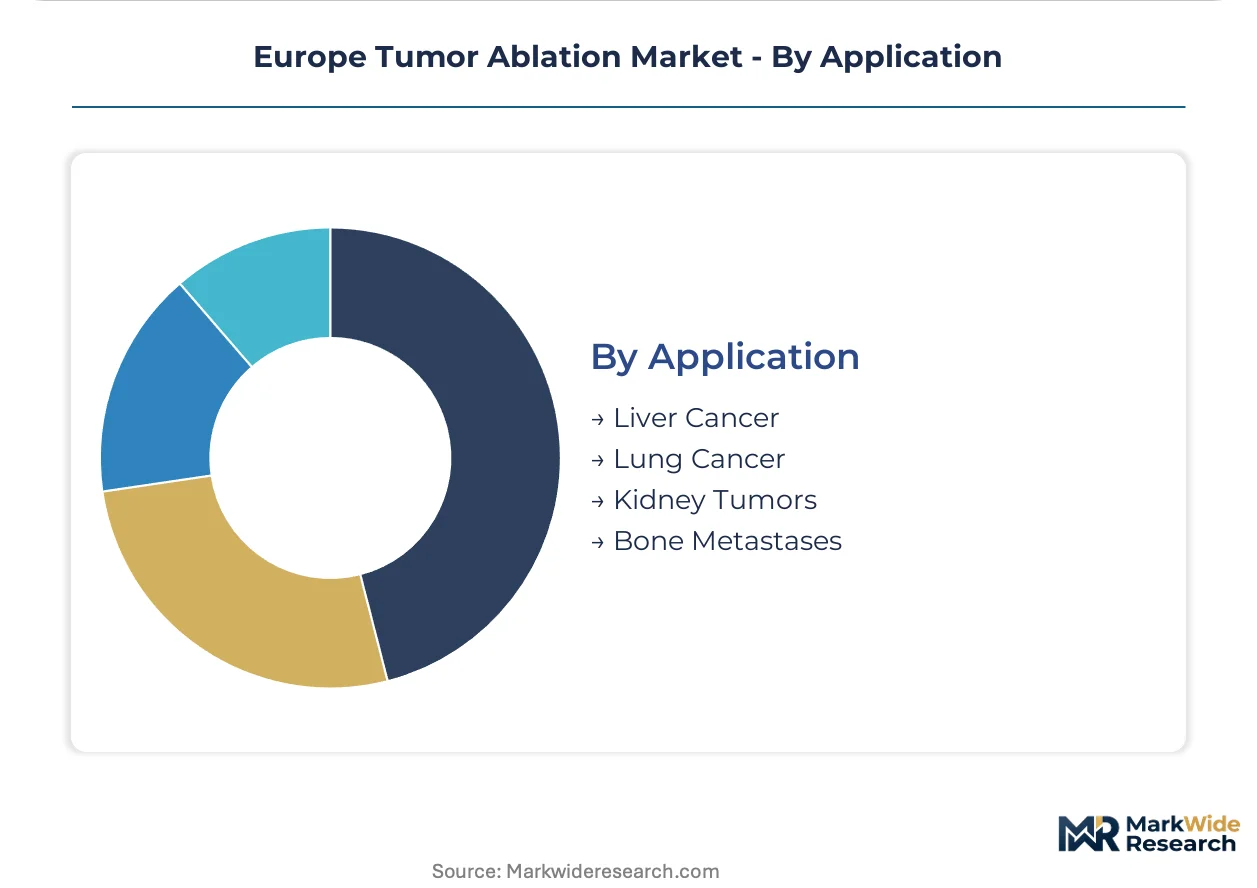
Application:
Clinical evidence requirements and reimbursement pathways vary by tumor site, with hepatic and pulmonary applications enjoying established tariff codes while bone metastasis coverage fragments.
- Liver Cancer:Percutaneous and intraoperative ablation of hepatocellular carcinoma and colorectal metastases represents the most mature indication. Italian and Spanish interventional radiology programs prioritize liver ablation fellowship training.
- Lung Cancer:Microwave ablation of primary and metastatic lesions is expanding fastest as interventional radiologists displace thoracic surgeons for poor-operative-risk patients. German university hospitals report steepest volume growth.
- Kidney Tumors:Cryoablation and radiofrequency ablation compete for small renal mass management, with tissue preservation driving cryoablation preference in German and Austrian urology centers.
- Bone Metastases:Palliative ablation for pain control and local tumor control in osseous lesions remains underpenetrated. Reimbursement heterogeneity across France, Italy, and the UK constrains standardization.
By procedure count, liver cancer leads. By volume expansion, lung cancer is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German interventional radiology centers command pricing premiums that Italian and Spanish facilities cannot replicate, creating a two-tier procurement landscape across the continent.
Germany
Microwave ablation conversion accelerates in university hospitals across Munich and Berlin, driven by procedural throughput targets for liver and lung lesions. The EU MDR and German notified bodies enforce 18-24 month recertification timelines that filter smaller manufacturers from tender participation. The Rhine-Ruhr hospital consortium centralizes procurement for North Rhine-Westphalia's oncology networks.
France
Parisian hospital procurement consortia govern sixty percent of device selection decisions through multi-year supply agreements. ANSM and national health technology assessment bodies have frozen percutaneous ablation tariff updates since 2022, compressing capital equipment budgets. Lyon and Marseille academic centers anchor cryoablation adoption for renal applications despite F-Gas Regulation compliance costs.
Italy
Milan and Rome university hospitals lead microwave ablation installed base conversion from radiofrequency systems. The Italian Medicines Agency aligns with EMA thermal damage threshold guidance for class III device approvals. Lombardy's regional health authority consolidates tendering for interventional oncology equipment across seventeen public hospitals.
Spain
Barcelona and Madrid oncology clinics expand outpatient percutaneous ablation capacity under national health insurance reimbursement stability. Spanish notified bodies extend MDR clinical evaluation timelines for novel irreversible electroporation platforms. Andalusian regional hospitals pilot outcome-based leasing contracts tied to complication rate metrics.
Netherlands
Dutch hospital consortia in Amsterdam and Rotterdam test device leasing models tied to recurrence-free survival outcomes. The Dutch Healthcare Authority calibrates reimbursement for emerging microwave modalities against established radiofrequency benchmarks. Eindhoven's medical technology cluster supports prototype development for MRI-guided laser ablation systems.
Europe Tumor Ablation Market Competitive Landscape
Broad-portfolio conglomerates and specialized interventional oncology firms split the market into distinct capability tiers. Consolidation pressures from EU MDR compliance costs favor established players with dedicated regulatory affairs infrastructure. Three archetypes dominate: diversified medical technology conglomerates with interventional divisions, pure-play ablation device specialists, and integrated laparoscopic instrument ecosystems. Competitive dynamics center on multi-year supply agreement capture and post-market surveillance data generation.
Within the diversified conglomerate tier, Medtronic Plc and Boston Scientific Corporation exemplify scale-driven positioning through sustained procurement relationships with large university hospital networks. Johnson & Johnson MedTech occupies a position anchoring integrated surgical ecosystem strategies. These three entities represent how breadth of interventional portfolios and service infrastructure determine tender success against MDR documentation burdens.
| Leading Market Players |
|---|
| Medtronic Plc |
| Boston Scientific Corporation |
| AngioDynamics |
| Johnson & Johnson MedTech |
| Stryker Corporation |
| EDAP TMS |
| Mermaid Medical |
| HealthTronics |
| Galil Medical Inc. |
| Others |
Pricing and Supply Chain Analysis
EU MDR recertification timelines stretching 18-24 months create a dual pricing squeeze: established manufacturers absorb compliance costs into premium configured-to-order systems while marginal competitors exit, compressing standard-tier supply. This regulatory chokepoint widens spreads between validated premium platforms and economy-tier imports while reshaping vendor consolidation patterns across German and French procurement consortia.
Pricing Analysis
Configured-to-order pricing for integrated imaging-ablation systems commands 40-60 percent premiums over standard radiofrequency generator configurations. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier differentiation, after-sales service bundling, and volume scale commitments from hospital consortia. Cost compression in standard-tier equipment is intensifying because French and Italian centralized tenders prioritize capital efficiency over feature expansion. Oncology clinics in Germany exhibit lowest price sensitivity due to stable national health insurance reimbursement, while Eastern European regional hospitals drive economy-tier volume.
Supply Chain Analysis
Export-control regimes governing high-frequency microwave components and specialized cryogenic valves limit technology flows from US and Japanese suppliers into European assembly operations. Manufacturing concentration centers on Germany, the Netherlands, and Switzerland for precision generator assembly, with China and South Korea supplying ceramic substrates and semiconductor power modules. Supply chain vulnerability rests on single-source dependencies for argon refrigerant logistics under F-Gas Regulation phase-down schedules. Distribution runs through authorized dealer networks serving hospital procurement consortia, with direct manufacturer relationships reserved for flagship university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as MDR compliance filters reshape competitive capacity and microwave ablation replacement cycles accelerate in German interventional radiology centers.
For Market Incumbents: Build regulatory data moats by expanding post-market surveillance infrastructure and clinical evidence generation capabilities. Consolidate service contract penetration across Italian and Spanish hospital networks before MDR recertification windows close for smaller competitors. Deepen backward integration into disposable electrode manufacturing to capture margin compression from centralized tendering.
For New Entrants and Emerging Players: Build out irreversible electroporation capabilities for pancreatic and prostate applications where thermal ablation faces safety constraints. Target bone metastasis palliative ablation in the UK and Netherlands where reimbursement heterogeneity has stalled incumbent investment. Pursue software companion development partnerships with imaging equipment manufacturers to bypass capital-intensive generator manufacturing.
For Investors and Strategic Acquirers: EU MDR Article 120 transition deadlines reshape the acquisition landscape by forcing distressed divestitures from undercapitalized device firms facing recertification failure. Five-to-ten year viability hinges on clinical evidence asset quality rather than installed base scale alone. Acquisition target archetype: mid-cap specialists with complete MDR technical documentation packages and active notified body engagement. Monitor German notified body queue lengths as inflection indicator for regulatory capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Generation | Post-market surveillance data satisfies German notified body requirements for class III recertification. |
| Hospital System Partnership | Multi-year supply agreements with Paris and Milan consortia lock out competitor access. |
| Software Companion Development | Real-time imaging fusion modules differentiate microwave ablation platforms in tender evaluations. |
| Reimbursement Strategy | Health technology assessment submissions in France and Netherlands establish tariff precedents for emerging modalities. |
| CE Marking Pathway | EMA thermal damage threshold alignment accelerates class III device approval timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from EMA guidance documents, EU MDR technical file databases, hospital procurement tender records, and national health technology assessment body publications. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates across the analysis window.
Calibration approaches anchored growth projections to historical replacement cycles for radiofrequency systems and adoption curves for microwave platforms. Segmentation dimensions spanned technology modality, end-user facility type, application site, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and average selling price evolution patterns. Forecast inputs incorporated interventional radiology fellowship program expansion rates and MDR notified body capacity constraints.
Stress conditions across reimbursement freeze durations, F-Gas refrigerant supply disruptions, and MDR recertification failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital capital budget allocation priorities and technology conversion timelines. Material shifts in EU MDR enforcement intensity or national health technology assessment reimbursement rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Germany Radiotherapy Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Global Cancer Treatment Market
Oncology
France Radiation Oncology Market
Oncology
Liposarcoma Treatment Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Radiation Oncology Market
Oncology
Laser Cancer Therapy Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Pancreatic Cancer Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Radiotherapy Market
Oncology
Sterile Oncology Injectable Market