
 Gynecological Cancer Drugs Market | 2026-2036
Gynecological Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Gynecological Cancer Drugs Market Foresight
Oncology nursing specialization is reorganizing treatment delivery across infusion centers and hospital networks. F. Hoffmann-La Roche AG leverages its diagnostic-drug pairing strategy to sustain competitive positioning in HER2-targeted protocols. AstraZeneca dominates PARP inhibitor development through sustained investment in synthetic lethality platforms. Merck & Co. extends its presence via checkpoint inhibitor combinations for recurrent cervical malignancies.
Gynecological cancer drugs comprise small-molecule cytotoxics, monoclonal antibodies, hormone modulators, and immune-modulating biologics formulated for parenteral or oral delivery against malignancies of the female reproductive tract. These agents function by interrupting mitotic division, blocking angiogenic signaling, or activating tumor-specific immune responses in ovarian, cervical, uterine, and vaginal neoplasms. Targeted therapy commands the highest margin pool due to biomarker-driven patient selection and premium pricing for PARP and angiogenesis inhibitors. Immunotherapy represents the fastest-expanding drug type as checkpoint inhibitors gain approval for cervical cancer indications. Intravenous administration anchors volume despite oral hormonal agents maintaining stable share in endometrial protocols.
The FDA accelerates gynecological oncology drug approvals through breakthrough therapy and fast track designations, compressing development timelines while elevating post-market surveillance obligations. EMA's centralized marketing authorization process shapes commercial access across EU member states, with REACH compliance governing active pharmaceutical ingredient manufacturing standards. Stakeholders must monitor evolving biomarker reimbursement policies and biosimilar entry timelines to anticipate portfolio repositioning requirements.
Market Dynamics
FDA breakthrough therapy designations are compressing clinical development timelines for PARP inhibitors and antibody-drug conjugates while elevating post-approval pharmacovigilance burdens across oncology portfolios.
Growth Catalysts
- Biomarker-driven patient stratification:Companion diagnostic pairings with targeted therapies enable precision dosing protocols that expand addressable populations for ovarian and endometrial malignancies.
- IRA Medicare price negotiation exemptions:Orphan drug status for rare gynecological indications shields novel agents from federal pricing pressure during initial commercialization windows.
- Japan's Sakigake designation system:Priority review pathways accelerate market entry for first-in-class immuno-oncology combinations, compressing regulatory lag versus standard PMDA timelines.
Market Restraints
- Platinum-based API supply concentration:Active pharmaceutical ingredient manufacturing for carboplatin and cisplatin clusters in Chinese chemical parks, exposing formulators to export quota volatility.
- EMA centralized authorization friction:Divergent national reimbursement assessments across EU member states delay commercial access despite unified marketing approval.
- Biosimilar bevacizumab substitution:Reference product erosion in ovarian cancer protocols pressures originator pricing power without equivalent clinical data requirements for biosimilar entrants.
Strategic Opportunities
- India's CDSCO fast-track pathways:Accelerated approval frameworks for unmet medical needs enable earlier market entry than standard 30-month review cycles.
- Subcutaneous checkpoint inhibitor administration:Self-injection formulations reduce infusion center dependency and expand community oncology access beyond tertiary hospital networks.
- Digital therapeutics integration:Remote patient monitoring platforms paired with oral PARP regimens enable decentralized toxicity management and dose optimization.
Industry Challenges
- Oncology nursing specialization scarcity:Certified infusion specialists capable of managing immune-related adverse events remain concentrated in academic medical centers, constraining community site expansion.
- Cold chain integrity for biologics:Temperature-controlled distribution of monoclonal antibodies requires validated logistics infrastructure that fragments across rural and ex-urban territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gynecological Cancer Drugs Market |
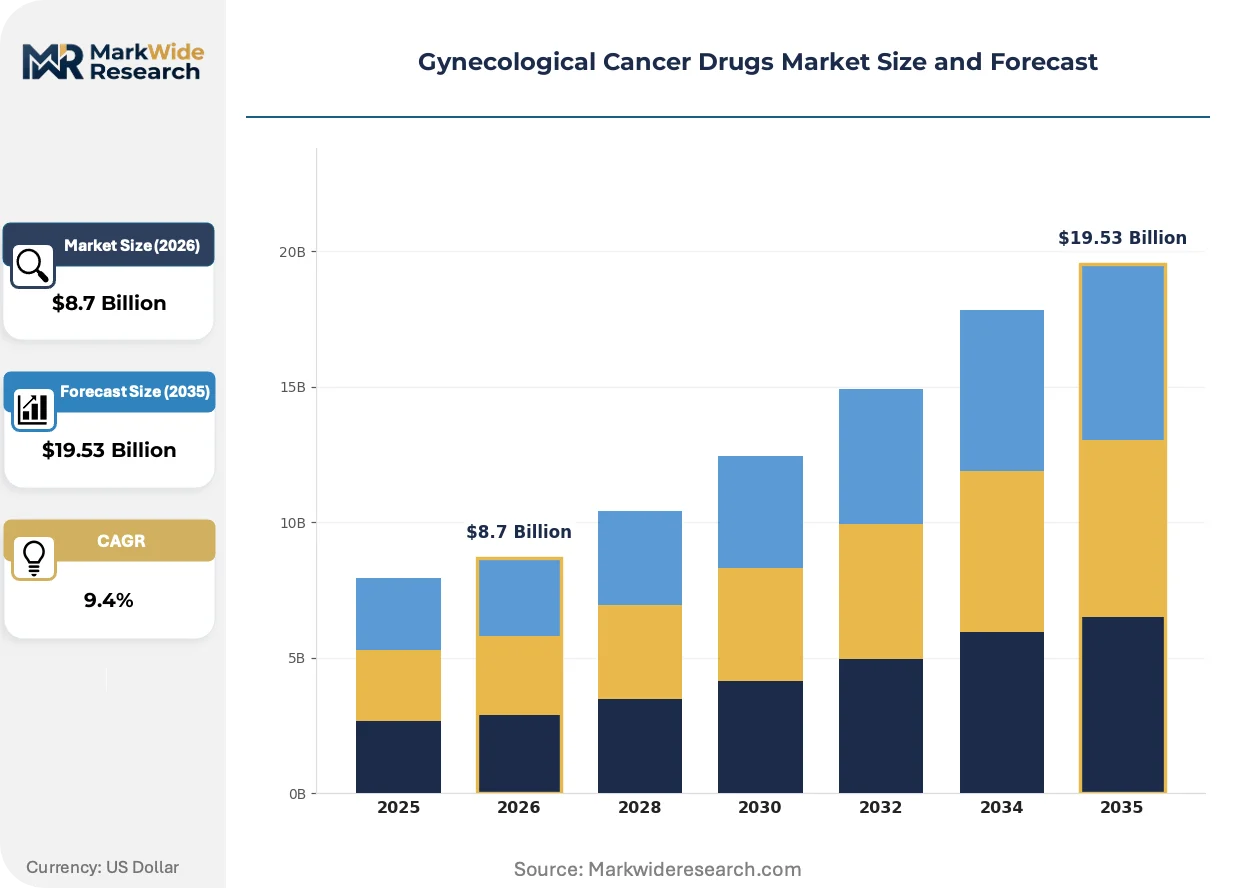
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Chemotherapy, Hormonal Therapy, Targeted Therapy, Immunotherapy Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Homecare, Research Laboratories Therapeutic Area: Ovarian Cancer, Cervical Cancer, Uterine Cancer, Vaginal Cancer |
| Companies Covered | GlaxoSmithKline, Novartis AG, F. Hoffmann-La Roche AG, AbbVie Inc., Johnson & Johnson, AstraZeneca, Pfizer Inc., Merck & Co., Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gynecological Cancer Drugs Market Shifts & Advancements
Next-generation sequencing integration is restructuring clinical trial enrollment and companion diagnostic development across gynecological oncology pipelines.
Liquid biopsy circulating tumor DNA platforms are miniaturizing tissue acquisition requirements for treatment monitoring. Community oncology practices in the United States are adopting these blood-based assays at twice the pace of academic centers. This shift is compressing longitudinal sample collection burdens while enabling real-time resistance mutation detection.
EMA's Clinical Trial Regulation harmonizes submission formats across EU member states, eliminating redundant national ethics reviews for multi-country oncology studies. Pharmaceutical sponsors now file single centralized protocols rather than parallel national applications. This regulatory streamlining most benefits mid-stage biotechs with limited regulatory affairs infrastructure.
Hospital procurement consortia are consolidating purchasing power for high-cost biologics. Integrated delivery networks now negotiate formulary placement directly with manufacturers, displacing traditional wholesale distribution for intravenous oncology agents. This concentration is most visible in the United States, where Catholic health systems and for-profit chains command multi-billion dollar annual pharmaceutical spend.
Gynecological Cancer Drugs Market Segmentation
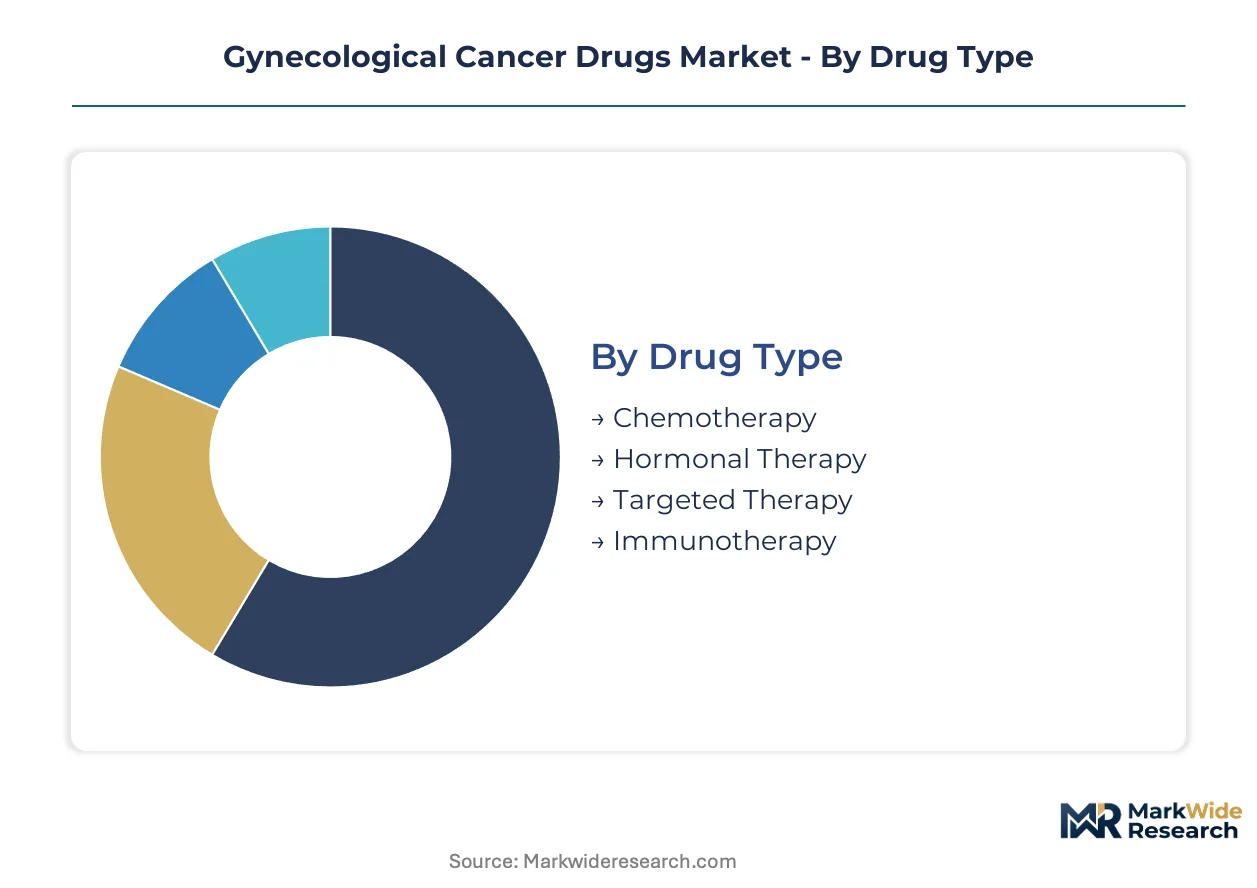
Drug type and administration route segmentation determines reimbursement pathways, manufacturing scale, and site-of-care economics across gynecological oncology. Biomarker eligibility criteria fragment patient populations, creating tiered pricing power for targeted modalities versus commoditized cytotoxics.
Drug Type:
FDA breakthrough therapy and EMA PRIME designations concentrate on distinct molecular mechanisms, accelerating approval velocity for synthetic lethality and immuno-oncology platforms while maintaining standard review timelines for cytotoxic agents.
- Targeted Therapy:PARP inhibitors and angiogenesis blockers exploit homologous recombination deficiency and VEGF signaling dependence. Demand clusters in academic medical centers with next-generation sequencing capacity, where companion diagnostic pairings justify premium reimbursement.
- Immunotherapy:Checkpoint inhibitors activate tumor-specific T-cell responses against PD-L1 expressing cervical malignancies. Merck's pembrolizumab expansion into recurrent disease settings drives fastest-in-category protocol adoption across National Cancer Institute-designated centers.
- Chemotherapy:Platinum-taxane combinations remain first-line standard for advanced ovarian disease. API manufacturing concentration in Chinese chemical parks exposes formulators to export quota volatility.
- Hormonal Therapy:Progestin and selective estrogen receptor modulators address endometrial hyperplasia progression. Stable demand persists in community oncology settings without biomarker testing infrastructure.
Targeted therapy handles the majority of throughput; immunotherapy is the fastest mover on share.
Administration Route:
Site-of-care economics and nursing specialization scarcity reshape route selection, with self-administration formulations capturing margin from infusion center overhead.
- Intravenous:Monoclonal antibodies and antibody-drug conjugates require certified infusion specialist supervision for immune-related adverse event management. Tertiary hospital networks anchor volume despite capacity constraints.
- Oral:PARP inhibitors and hormonal agents enable decentralized toxicity monitoring. United States community oncology practices adopt oral regimens at twice the rate of academic centers.
- Subcutaneous:Self-injection checkpoint formulations reduce facility dependency. European homecare nursing networks expand administration beyond hospital walls.
- Intramuscular:Depot hormonal preparations sustain therapeutic levels with monthly dosing. Limited to endometrial protocols with stable, predictable pharmacokinetic profiles.
Intravenous administration commands the highest absolute volume; subcutaneous delivery is expanding most quickly into community settings.
End User:
Procurement consolidation and formulary control differentiate customer economics, with integrated delivery networks displacing traditional wholesale channels for high-cost biologics.
- Hospitals:Academic medical centers with gynecologic oncology fellowship programs manage complex combination protocols. Catholic health system consortia negotiate direct manufacturer contracts for intravenous biologics.
- Clinics:Community oncology practices adopt liquid biopsy platforms for treatment monitoring. Certified infusion specialist scarcity constrains immune-oncology expansion.
- Homecare:Oral PARP regimens paired with remote patient monitoring enable decentralized care. Cold chain requirements limit biologic administration outside facility settings.
- Research Laboratories:Phase I units within cancer centers enroll biomarker-selected populations. Next-generation sequencing integration restructures trial eligibility screening.
Hospitals handle the majority of throughput; homecare is gaining share fastest as oral targeted therapies expand.
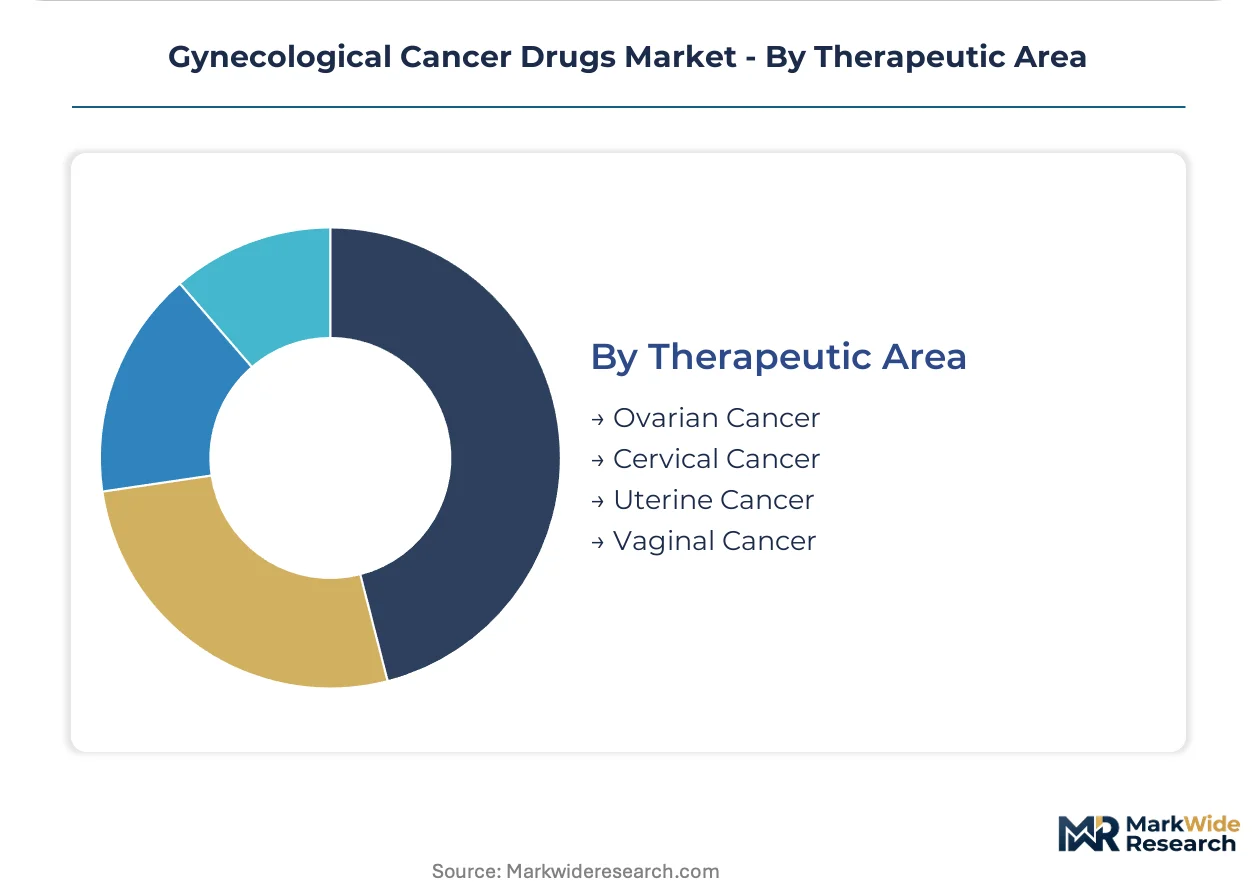
Therapeutic Area:
Incidence patterns and screening infrastructure create divergent addressable populations, with ovarian disease commanding highest per-patient drug spend despite lower case volume.
- Ovarian Cancer:Platinum-resistant recurrence drives PARP inhibitor maintenance adoption. BRCA mutation testing penetration exceeds 80% in United States tertiary centers.
- Cervical Cancer:Checkpoint inhibitor approvals for PD-L1 positive disease expand second-line options. HPV vaccination programs in developed markets compress incident case growth.
- Uterine Cancer:Endometrial carcinoma hormonal protocols maintain stable demand. MSI-high subpopulations qualify for immunotherapy off-label use.
- Vaginal Cancer:Rare incidence limits dedicated drug development. Chemoradiation protocols repurpose cervical cancer agents.
Ovarian cancer handles the majority of throughput; cervical cancer is climbing the fastest on immunotherapy approval momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes intravenous biologics in tertiary centers, while Japan and Germany emphasize oral targeted therapies with decentralized monitoring, and India concentrates cytotoxic chemotherapy in high-volume public hospitals.
United States
Academic medical centers with gynecologic oncology fellowship programs anchor demand for complex combination protocols. The FDA's breakthrough therapy designation compresses approval timelines for PARP inhibitors and antibody-drug conjugates. The National Cancer Institute-designated centers in Boston, Houston, and New York Metro drive biomarker testing penetration exceeding 80% for BRCA mutation screening.
Germany
EMA centralized marketing authorization enables unified commercial access across federal states, though divergent reimbursement assessments at the G-BA create regional access friction. REACH compliance governs active pharmaceutical ingredient manufacturing standards for platinum-based agents. The Rhine-Ruhr and Bavarian hospital networks concentrate infusion center capacity for monoclonal antibody administration.
Japan
PMDA's Sakigake designation system accelerates market entry for first-in-class immuno-oncology combinations, compressing standard review timelines. METI coordinates domestic pharmaceutical manufacturing resilience initiatives. The Tokyo-Osaka corridor anchors precision medicine adoption, with Kanto region hospitals leading liquid biopsy platform integration for treatment monitoring.
India
CDSCO fast-track pathways for unmet medical needs enable earlier market entry than standard 30-month review cycles. The PLI scheme for pharmaceuticals incentivizes domestic API production for carboplatin and paclitaxel. Maharashtra and Gujarat chemical parks concentrate platinum-based API manufacturing, though export quota volatility from Chinese suppliers disrupts formulation supply.
United Kingdom
NICE technology appraisals determine formulary placement for high-cost biologics across NHS trusts, creating tiered access by region. The MHRA operates under retained EU law post-Brexit, maintaining EMA-aligned standards with independent approval pathways. London and Manchester cancer centers drive clinical trial enrollment for next-generation sequencing-selected populations.
Gynecological Cancer Drugs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the gynecological cancer drugs market. The upper tier comprises diversified pharmaceutical conglomerates with diagnostic-drug pairing capabilities and synthetic lethality platforms. Below them, mid-scale biotech specialists concentrate on single-modality breakthroughs. Two dominant competitive moves are reshaping positioning: strategic partnerships between drug developers and companion diagnostic manufacturers, and portfolio diversification into subcutaneous administration formulations that reduce infusion center dependency.
Among the integrated pharmaceutical conglomerates, F. Hoffmann-La Roche AG and AstraZeneca occupy positions exemplifying the diagnostic-therapeutic convergence archetype, while Merck & Co. anchors the checkpoint inhibitor expansion strategy for cervical malignancy indications. These three entities represent distinct competitive vectors: Swiss precision medicine integration, British synthetic lethality leadership, and American immuno-oncology scale.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Novartis AG |
| F. Hoffmann-La Roche AG |
| AbbVie Inc. |
| Johnson & Johnson |
| AstraZeneca |
| Pfizer Inc. |
| Merck & Co. |
| Bristol-Myers Squibb |
| Others |
Supply & Pricing Matrix
Biosimilar bevacizumab substitution in ovarian cancer protocols simultaneously redraws API sourcing geography toward Indian and Korean manufacturers while compressing originator pricing power through reference product erosion. This dual displacement concentrates procurement leverage within hospital consortia and integrated delivery networks that now negotiate formulary placement directly with manufacturers.
Pricing Analysis
Long-term offtake agreements dominate high-cost biologic procurement, with Catholic health systems and for-profit chains locking in multi-year supply commitments for intravenous monoclonal antibodies. Price differentiation hinges on companion diagnostic pairing status and FDA breakthrough therapy designation tier, with biomarker-matched agents commanding premium positioning against commoditized platinum-taxane combinations. Pricing pressure stems from biosimilar entry timelines accelerating without equivalent clinical data requirements for entrants. Community oncology practices exhibit highest price sensitivity due to reimbursement lag and formulary restriction exposure, while academic medical centers maintain lowest sensitivity through NCI-designated center status and research funding offsets.
Supply Chain Analysis
Strategic stockpiling of platinum-based active pharmaceutical ingredients prevails among formulators exposed to Chinese chemical park export quota volatility, contrasting with just-in-time preferences for temperature-sensitive monoclonal antibodies. API manufacturing concentrates in China, India, and Germany, with Maharashtra and Gujarat chemical parks expanding domestic carboplatin and paclitaxel output under PLI scheme incentives. Critical dependencies include platinum salts, taxane bark extracts, and recombinant protein cell lines. Single-source vulnerability from Chinese export restrictions on platinum intermediates threatens formulation continuity. Distribution runs through hospital procurement consortia displacing traditional wholesale channels for intravenous oncology agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consortia and integrated delivery networks, with Catholic health systems and for-profit chains now commanding multi-billion dollar annual pharmaceutical spend that displaces traditional wholesale distribution channels.
For Market Incumbents: Secure companion diagnostic pairing exclusivity through strategic partnerships with liquid biopsy platform developers, defending against biosimilar erosion by embedding biomarker testing protocols into standard-of-care guidelines. Deepen backward integration into platinum-based API manufacturing through acquisitions of Indian chemical park assets, insulating supply continuity from Chinese export quota volatility. Reinforce infusion center capacity through certified oncology nursing specialist training programs that constrain community site expansion by emerging competitors. For New Entrants and Emerging Players: Differentiate on subcutaneous checkpoint inhibitor administration formats that reduce facility dependency and expand community oncology access beyond tertiary hospital networks. Target oral PARP inhibitor regimens paired with remote patient monitoring platforms for homecare penetration, the fastest-expanding end-user segment as decentralized toxicity management gains reimbursement traction. Pursue CDSCO fast-track pathway entry for unmet medical needs in India, enabling earlier market access than standard review cycles and establishing manufacturing foothold for subsequent geographic expansion. For Investors and Strategic Acquirers: FDA breakthrough therapy designation density reshapes the acquisition landscape by compressing commercialization timelines for synthetic lethality and immuno-oncology platforms while elevating post-market surveillance obligations. Long-term viability over the coming decade rests on diagnostic-therapeutic convergence capabilities and synthetic lethality platform breadth. Prioritize acquisition targets with established companion diagnostic partnerships and liquid biopsy integration. Watch biosimilar bevacizumab substitution rates in ovarian cancer protocols as the inflection indicator for originator pricing power erosion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | FDA breakthrough therapy designations accelerate when paired with validated biomarker assays for patient stratification. |
| Subcutaneous Formulation Development | Self-injection checkpoint inhibitors reduce infusion center dependency and expand community oncology access beyond academic centers. |
| API Manufacturing Scale-Up | Indian PLI scheme incentives for domestic carboplatin production reduce exposure to Chinese chemical park export volatility. |
| Liquid Biopsy Platform Integration | Community oncology practices adopt blood-based ctDNA assays at twice the pace of academic centers for treatment monitoring. |
| Reimbursement Strategy Alignment | Orphan drug status shields novel agents from IRA Medicare price negotiation during initial commercialization windows. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration throughout the research process. Primary interviews with formulary directors at integrated delivery networks and oncology nursing specialists at NCI-designated centers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down pharmaceutical spend analysis were triangulated to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including drug type, administration route, therapeutic area, and regional regulatory cluster. CAGRs were derived from patient incidence projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated biomarker testing adoption rates, biosimilar entry timelines, and infusion center capacity expansion plans.
Material uncertainties — regulatory approval delays, reimbursement policy shifts, and API supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about companion diagnostic pairing penetration and checkpoint inhibitor label expansion velocity. Revision becomes warranted when biosimilar substitution rates or platinum export restriction severity cross thresholds that alter competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Cancer API Market
Oncology
Oncology Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Sterile Oncology Injectable Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
AI in Oncology Market
Oncology
Vulvar Cancer Market
Oncology
Global Veterinary Oncology Market
Oncology
Colorectal Cancer Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Global Cancer Profiling Market
Oncology
US Radiation Oncology Market
Oncology
Glioblastoma Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
France Radiation Oncology Market
Oncology
Precision Oncology Market