
 Industrial Hand Tools Market | 2026-2036
Industrial Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hand Tools Market Intelligence
The integration of battery-operated and pneumatic systems into hand tools is reconfiguring performance expectations on assembly lines and in repair shops. This shift prioritizes power-to-weight ratios and cordless operation. Stanley Black & Decker leverages its extensive distribution to serve professional and industrial channels. Robert Bosch GmbH specializes in high-torque electric tools, while Snap-On Incorporated dominates the professional automotive maintenance segment.
Industrial hand tools are non-powered or power-assisted implements for manual operation in manufacturing, maintenance, and construction. These tools are forged from materials like chrome-vanadium steel to withstand high torque and repetitive stress. While wrenches and pliers are a mature, high-volume category, demand for specialized cutting tools is expanding in aerospace and shipbuilding. The construction and automotive assembly line applications command the largest share of tool deployments.
Product standards are influenced by national and international regulations. The U.S. Occupational Safety and Health Administration (OSHA) mandates specific tool safety features, while CE marking is required for market access in Europe. Conformance with ISO 9001 quality standards is often a prerequisite for supplying major industrial end-users. Vendor selection will increasingly hinge on compliance with ergonomic design principles and supply chain transparency.
Market Dynamics
The core dynamic reshaping the industrial hand tools market is the widespread adoption of battery-powered platforms. This technological shift is re-prioritizing design criteria around power-to-weight ratios and cordless mobility, impacting everything from assembly line ergonomics to field repair logistics.
Growth Catalysts
- Manufacturing Expansion:Government initiatives like India's Production Linked Incentive (PLI) scheme are accelerating domestic manufacturing capacity, creating sustained, large-scale demand for a wide range of industrial toolsets across new factory floors.
- Aerospace MRO Demand:The aerospace sector's stringent maintenance, repair, and overhaul (MRO) schedules require specialized, high-torque, and precisely calibrated hand tools, driving growth in a high-margin niche segment.
- Cordless Technology Adoption:The transition to battery-operated tools enhances worksite safety by eliminating cord-related trip hazards and improves operational flexibility, acting as a powerful catalyst for fleet upgrades in construction and automotive repair.
Market Restraints
- Raw Material Volatility:The market's cost structure is highly sensitive to price fluctuations in key inputs like chrome-vanadium steel and specialty alloys, which can compress manufacturer margins without notice.
- Regulatory Fragmentation:Adherence to disparate international standards, such as OSHA requirements in the United States and CE marking prerequisites in Europe, increases design, testing, and compliance costs for manufacturers seeking access to multiple markets.
- Threat of Substitution:Continuous improvements in the performance and cost-effectiveness of powered tools create a substitution risk for traditional non-powered hand tools, particularly in high-volume, repetitive applications.
Strategic Opportunities
- Smart Tool Integration:Embedding sensors and wireless connectivity into hand tools to capture torque data, usage cycles, and location information creates new value streams in quality control and asset management for industrial end-users.
- Marine and Offshore Applications:Developing specialized toolsets with enhanced corrosion resistance and non-sparking properties opens opportunities in the demanding shipbuilding, offshore oil and gas, and marine maintenance segments.
- Emerging Manufacturing Hubs:As manufacturing supply chains diversify, emerging industrial economies in Southeast Asia, such as Vietnam and Indonesia, represent significant greenfield opportunities for tool suppliers.
Industry Challenges
- Technician Skill Gaps:The proliferation of smart, connected tools necessitates new training for technicians, shifting the required skillset from purely mechanical proficiency to include software interaction and data analysis.
- Supply Chain Transparency:Verifying the ethical sourcing of raw materials, from steel alloys to cobalt used in lithium-ion batteries, presents a significant operational and reputational challenge for global tool brands.
- Ergonomic Standard Compliance:Designing tools that meet evolving ergonomic guidelines to reduce repetitive stress injuries and long-term vibration exposure is a complex engineering and compliance challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hand Tools Market |
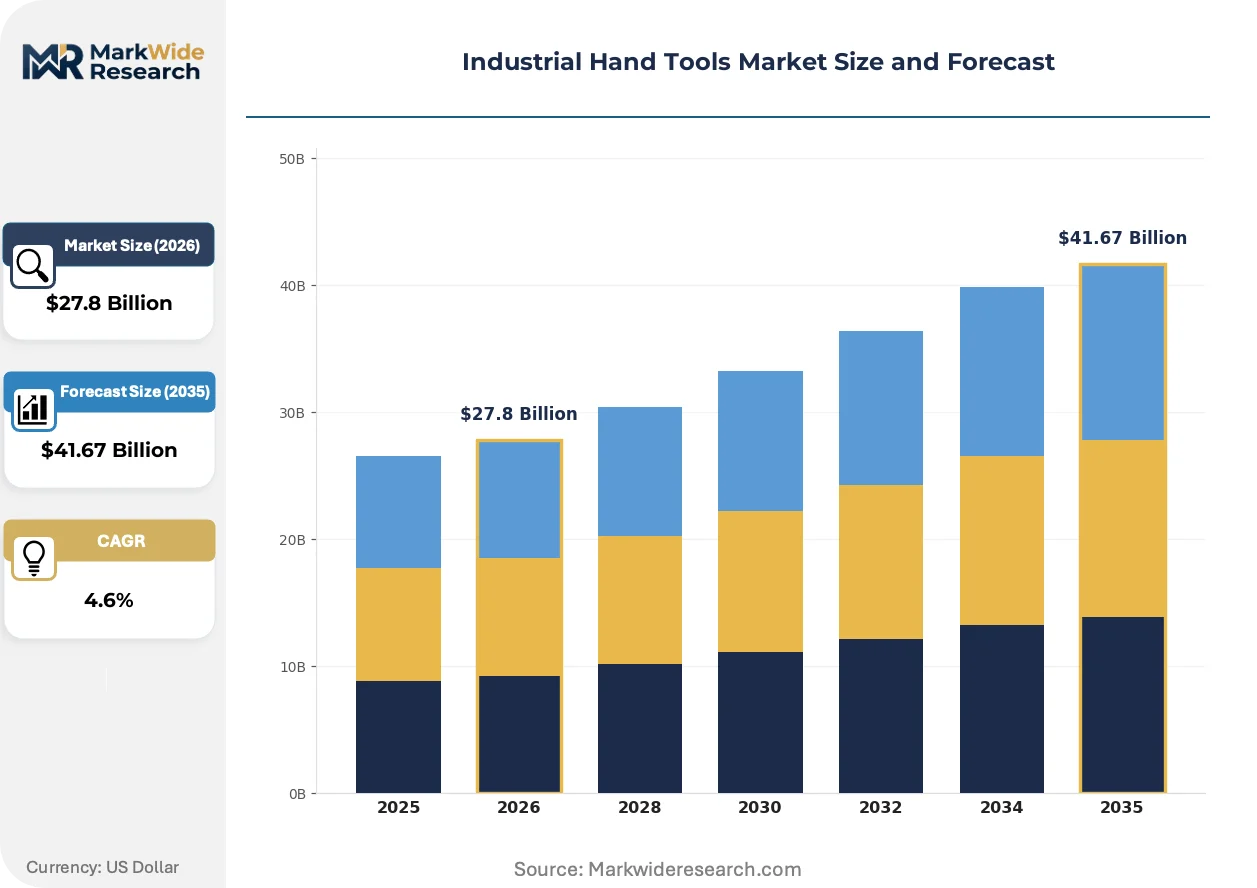
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $41.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screwdrivers, Wrenches, Pliers, Hammers, Measuring Tools, Cutting Tools Technology: Manual, Pneumatic, Hydraulic, Electric, Cordless, Battery Operated Application: Construction, Metal Fabrication, Assembly Lines, Maintenance, Aerospace Equipment, Shipbuilding End User: Manufacturing Plants, Repair Shops, Engineering Firms, Tool Distributors, Oil & Gas Facilities, Mining Operators |
| Companies Covered | Makita Corporation, Snap-On Incorporated, Robert Bosch GmbH, Atlas Copco AB, Apex Tool Group, Stanley Black & Decker, Chervon Holdings, Festool, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hand Tools Market Strategic Shifts & Innovations
Performance benchmarks are being redefined as electromechanical systems integrate with traditional tool forms. This evolution prioritizes not just raw power, but also data generation, operator safety, and total cost of ownership, influencing design and purchasing decisions across industrial sectors.
Brushless motor technology provides a higher power-to-weight ratio, greater efficiency, and longer operational life for cordless tools. Professional users in construction and automotive maintenance are rapidly adopting these advanced tools for their enhanced durability and performance. The superior output of brushless DC motors is collapsing the distinction between cordless convenience and the power of traditional pneumatic or corded electric tools.
Regulations such as the European Union's Machinery Directive are imposing stricter requirements on tool manufacturers regarding user safety, specifically addressing hand-arm vibration and noise levels. This forces engineering teams to integrate advanced dampening materials and ergonomic designs to mitigate operator exposure. The professional-grade tool segment is most affected, where compliance with these standards is a non-negotiable requirement for market access.
A notable behavioral change is the growing interest in tool fleet management services over simple transactional purchases. This model disrupts the traditional sales channel by offering subscription-based access to a managed inventory of tools, including maintenance, tracking, and replacement. This trend is most prominent within large construction firms and industrial facilities in North America, where maximizing tool uptime and minimizing capital expenditure are critical.
Industrial Hand Tools Market Segmentation
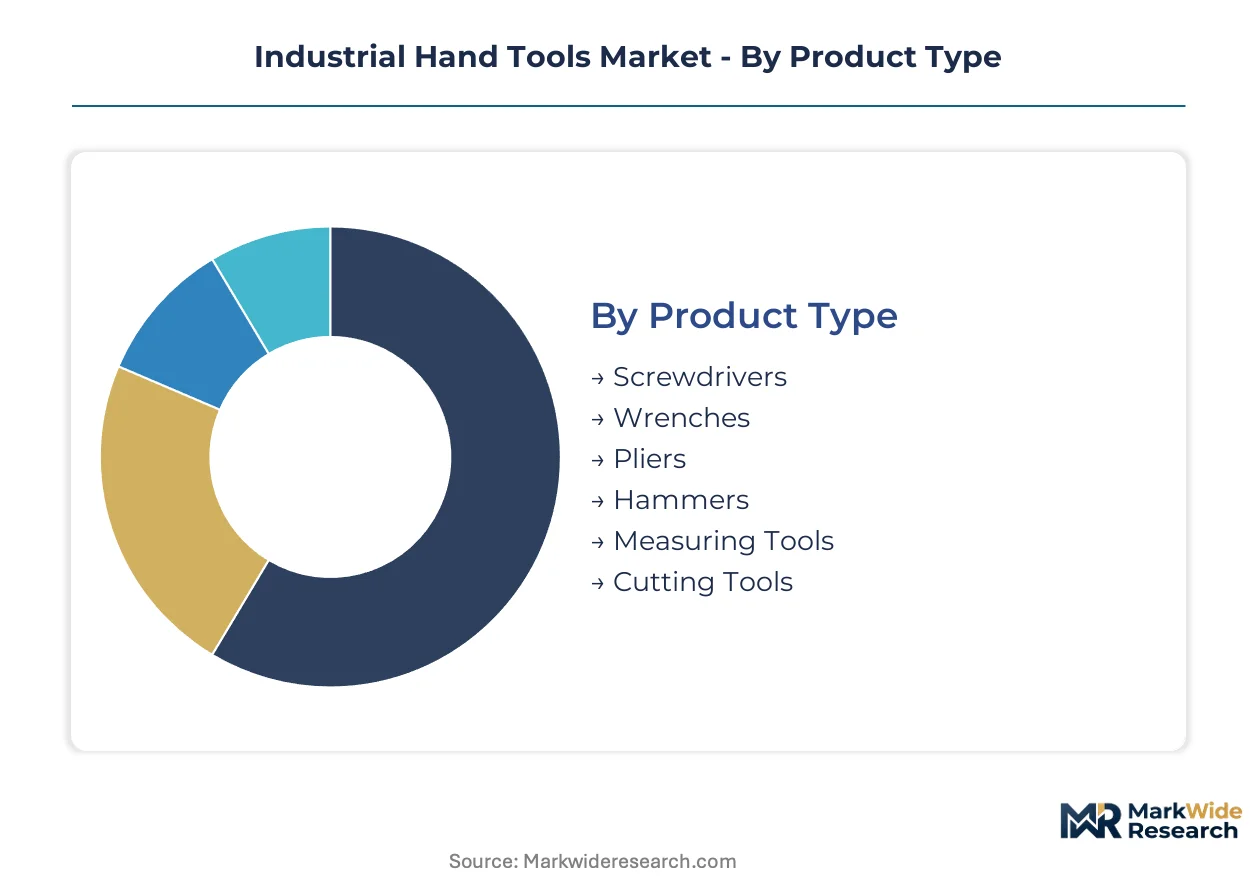
The industrial hand tools market is a diverse ecosystem, categorized to reflect the varied product types, underlying technologies, primary applications, and distinct end-user requirements. Understanding these segments helps in discerning the specific demand drivers, technological shifts, and competitive dynamics influencing market evolution.
Product Type:
The cost tier of industrial hand tools often dictates their material composition and manufacturing precision, influencing their market positioning.
- Wrenches:Wrenches, often forged from chrome-vanadium steel, form a high-volume, mature category essential for general mechanical work across various industrial settings. Demand for these tools remains consistent in maintenance and assembly operations.
- Cutting Tools:Cutting Tools, particularly specialized variants, see demand concentration in aerospace and shipbuilding sectors, driven by precise material processing needs and high-margin niche applications. These tools require superior material hardness and edge retention.
- Screwdrivers:Screwdrivers remain fundamental across all industrial sectors, with specialized tips and ergonomic designs improving user efficiency and reducing fatigue.
- Pliers:Pliers are versatile gripping and cutting tools, seeing widespread use in electrical, plumbing, and general assembly tasks due to their mechanical advantage.
- Hammers:Hammers, essential for striking and shaping, are integral to construction and metal fabrication, with different head materials and weights serving specific impact requirements.
- Measuring Tools:Measuring Tools, including calipers and tape measures, ensure precision and quality control in manufacturing and construction, supporting stringent tolerance requirements.
Wrenches command the established base. The steepest expansion runs through Cutting Tools.
Technology:
The application requirements for industrial hand tools frequently determine the power source and operational mechanism, driving technological advancements.
- Cordless:Cordless tools enhance worksite flexibility and operator safety by eliminating trip hazards, fostering fleet upgrades in construction and automotive repair sectors. Brushless motor technology improves their power-to-weight ratio.
- Battery Operated:Battery Operated tools, leveraging advancements in lithium-ion technology, provide high power-to-weight ratios and extended operational life, gaining significant traction in assembly lines and field service. They offer superior mobility.
- Manual:Manual tools form the foundational segment, essential for tasks requiring fine control, portability, or where power sources are unavailable, maintaining a steady demand in diverse applications.
- Pneumatic:Pneumatic tools offer high torque and durability for repetitive tasks, finding strong demand in heavy manufacturing and automotive workshops where compressed air infrastructure is prevalent.
- Hydraulic:Hydraulic tools deliver immense force for heavy-duty applications like demolition and lifting, primarily used in construction and large-scale industrial maintenance projects.
- Electric:Electric tools provide consistent power for continuous operation, widely adopted in workshops and assembly lines where direct power access is readily available.
Manual tools maintain a foundational presence. Cordless technology is expanding most quickly across new deployments.
Application:
The volume of tools deployed varies significantly across different industrial sectors, reflecting their operational scale and intensity.
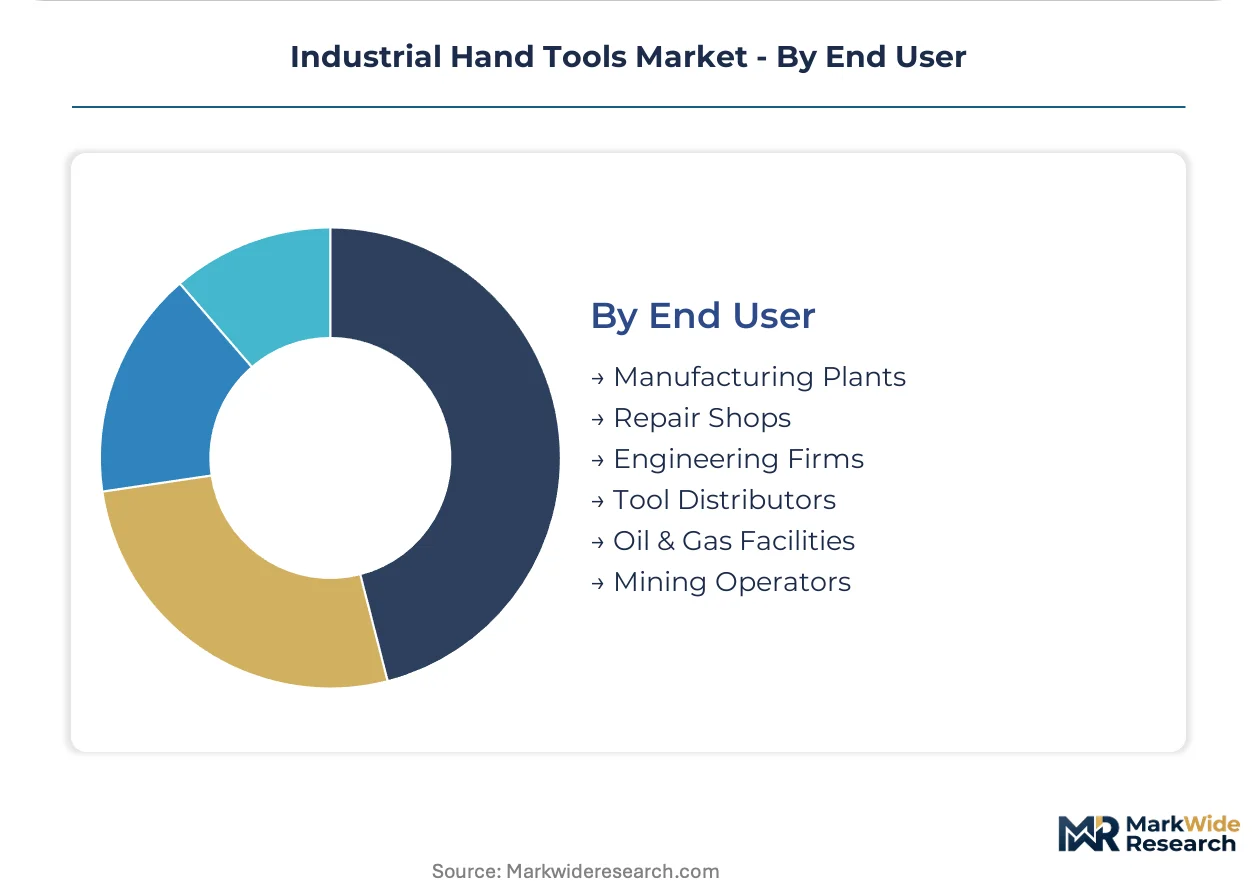
- Construction:Construction applications command the largest share of tool deployments, driven by large-scale infrastructure projects and continuous demand for robust, reliable tools. Fleet upgrades for battery-operated tools are prevalent.
- Automotive Assembly Lines:Automotive Assembly Lines require high-torque, precisely calibrated tools for repetitive fastening and assembly tasks, prioritizing ergonomics and efficiency. Snap-On Incorporated dominates this professional segment.
- Metal Fabrication:Metal Fabrication relies on specialized cutting, grinding, and shaping tools, with demand influenced by manufacturing output and material processing innovation.
- Maintenance:Maintenance, Repair, and Overhaul (MRO) activities across all industries require a broad range of hand tools for routine upkeep and critical repairs, ensuring operational continuity.
- Aerospace Equipment:Aerospace Equipment maintenance demands specialized, high-precision tools for stringent MRO schedules, driving growth in a high-margin niche segment. These tools often require specific certifications.
- Shipbuilding:Shipbuilding requires corrosion-resistant and robust tools for demanding marine environments, including specialized cutting and fastening implements for large structures.
Construction applications represent the largest established base. Aerospace Equipment is climbing the fastest in specialized demand.
End User:
Customer type directly influences procurement patterns and demand for specialized industrial hand tool solutions.
- Manufacturing Plants:Manufacturing Plants represent a primary demand anchor, especially in emerging economies like India, driven by government initiatives such as the PLI scheme, creating large-scale demand for diverse toolsets.
- Repair Shops:Repair Shops, particularly in the automotive sector, drive demand for professional-grade, durable tools, often prioritizing brand reputation and tool longevity. Robert Bosch GmbH specializes in high-torque electric tools.
- Engineering Firms:Engineering Firms influence tool selection through specification and design, often requiring specialized tools for prototyping, testing, and precision assembly tasks.
- Tool Distributors:Tool Distributors serve as critical intermediaries, managing inventory and logistics for a wide range of end-users, reflecting broad market demand across various segments.
- Oil & Gas Facilities:Oil & Gas Facilities require specialized, ruggedized, and often non-sparking tools for hazardous environments, emphasizing safety and durability in extreme conditions.
- Mining Operators:Mining Operators demand heavy-duty, robust tools capable of withstanding harsh operating conditions and continuous use in extraction and processing activities.
Manufacturing Plants constitute the primary demand anchor. Oil & Gas Facilities are gaining share fastest for specialized, ruggedized tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial end-users, from large construction firms to specialized aerospace MRO facilities, concentrate demand for hand tools across diverse global manufacturing hubs. These buyers prioritize tool durability, precision, and increasingly, cordless mobility for operational efficiency. The market dynamics reflect regional economic activity and regulatory frameworks.
United States
Demand for industrial hand tools in the United States stems from robust construction projects and a thriving automotive aftermarket. OSHA mandates specific safety features, influencing tool design and procurement standards. Major industrial clusters in the Midwest, particularly around Detroit, drive demand for specialized assembly and maintenance tools.
Germany
German manufacturing, known for precision engineering and advanced automotive production, requires high-performance industrial hand tools. CE marking is a prerequisite for market access, ensuring compliance with European safety and quality directives. The industrial regions of Bavaria and Baden-Württemberg lead in demand for technically sophisticated tools.
India
India's manufacturing expansion, supported by the Production Linked Incentive (PLI) scheme, generates significant demand for industrial toolsets. BIS standards ensure product quality and safety, aligning with domestic industrial requirements. New factory floors in Maharashtra and Gujarat create a large-scale need for diverse hand tool categories.
China
Chinese industrial growth, particularly in electronics manufacturing and infrastructure development, drives substantial demand for both general and specialized hand tools. GB standards regulate tool performance and safety, impacting local and international suppliers. The Yangtze River Delta region, a major manufacturing hub, sees continuous deployment of hand tools.
Japan
Japanese automotive and aerospace sectors demand high-precision, durable industrial hand tools for their intricate assembly and maintenance processes. JIS standards govern tool quality and material specifications, ensuring reliability in demanding applications. Industrial centers in the Kanto region, including Tokyo, require advanced tools for sophisticated manufacturing.
Industrial Hand Tools Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for industrial hand tools. The market exhibits consolidation at the premium end, driven by established brands with extensive distribution networks. Strategic archetypes include diversified industrial conglomerates and focused niche specialists. Companies primarily engage in portfolio diversification and geographic expansion to secure market share.
On the professional-grade vector, Snap-On Incorporated exemplifies a focus on specialized automotive maintenance tools, catering to demanding professional users. Robert Bosch GmbH, a German-based entity, represents broader industrial and construction segments with its high-torque electric tools. Stanley Black & Decker occupies a position as a diversified industrial conglomerate, leveraging its extensive distribution to serve both professional and industrial channels globally. These entities anchor distinct segments by offering differentiated product portfolios and service models.
| Leading Market Players |
|---|
| Makita Corporation |
| Snap-On Incorporated |
| Robert Bosch GmbH |
| Atlas Copco AB |
| Apex Tool Group |
| Stanley Black & Decker |
| Chervon Holdings |
| Festool |
| Techtronic Industries |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's extensive manufacturing capacity for tool components directly influences global cost structures and competitive pricing. This industrial concentration creates significant leverage for large-volume buyers.
Pricing Analysis
Cost-plus contract patterns, often indexed to chrome-vanadium steel and lithium prices, govern many long-term procurement agreements. Price differentiation stratifies across premium, standard, and economy tiers based on material quality and certification levels like ISO 9001. Pricing softness stems from intense competition in the high-volume manual tool segment. Construction firms demonstrate high price sensitivity, while aerospace MRO operations prioritize precision and durability over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive manufacturing of industrial hand tools. Geographic supply concentration centers on China, India, and Germany for finished goods and key components. Raw material dependencies include chrome-vanadium steel, specialty alloys, and cobalt for lithium-ion batteries. Commodity price volatility represents a structural risk for manufacturers. Distribution runs through a fragmented network of industrial distributors and specialized professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a fragmentation opportunity, driven by the specialized requirements of aerospace equipment maintenance. The shift towards high-precision, application-specific tools creates distinct niche segments for focused players.
For Market Incumbents: Pre-empt disruption from smart tool integration by accelerating R&D in sensor technologies and data analytics platforms. Consolidate market share in mature segments like wrenches through supply chain optimization and cost leadership. The threat of substitution from advanced battery-operated tools requires continuous investment in brushless motor technology to maintain performance parity. Enhance distribution networks to reach emerging manufacturing hubs in Southeast Asia.
For New Entrants and Emerging Players: Pursue white-space opportunities in marine and offshore applications by developing specialized corrosion-resistant and non-sparking toolsets. Target emerging manufacturing hubs in Vietnam and Indonesia, where demand for diverse tool categories is accelerating. A go-to-market angle focused on subscription-based tool fleet management services can penetrate large industrial facilities seeking to minimize capital expenditure. Specialize in ergonomic designs to address technician skill gaps.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers of tool fleet management services and specialized calibration solutions. Long-term viability over the next decade favors companies integrating data analytics into tool performance and predictive maintenance. Acquisition targets include niche manufacturers developing smart tool technologies or those with strong compliance records for ergonomic standards. A signal to watch is the increasing adoption rate of connected tools in construction and automotive repair.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification into Smart Tools | Captures new value streams from data generation and enhances quality control for industrial end-users. |
| Geographic Expansion into Southeast Asia | Penetrates greenfield opportunities in emerging industrial economies like Vietnam and Indonesia. |
| Investment in Ergonomic Design | Ensures compliance with evolving regulatory guidelines and reduces operator injury risks. |
| Development of Corrosion-Resistant Tools | Addresses specialized demand from marine, offshore, and shipbuilding applications. |
| Offering Tool Fleet Management Services | Shifts procurement patterns from transactional purchases to subscription-based models for large firms. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. Discussions involved plant managers, procurement leads, maintenance directors, and R&D engineers. Secondary data sources included government manufacturing reports, industry association publications, and company financial filings. The approach integrated bottom-up data collection with top-down market validation.
The calibration approach refined market projections by aligning historical data with observed growth patterns across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and material composition. Compound Annual Growth Rates were derived through regression analysis and expert consensus. Forecast inputs included manufacturing output projections and raw material price forecasts.
Sensitivities concentrate around raw material price volatility and shifts in regulatory compliance for ergonomic design. Forecasts reflect assumptions regarding technological adoption and global economic stability. Major trade policy changes or unforeseen manufacturing disruptions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Scarifiers Market
Tools
Indexable Tool Inserts Market
Tools
Portable Pressure Washer Market
Tools
Horizontal Milling Machine Market
Tools
Stationary Wood Planer Market
Tools
Floor Saw Market
Tools
Boring-Milling Machines Market
Tools
Caulking Gun Market
Tools
Turning Centers Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Mortiser Market
Tools
Tooling Market
Tools
Wood Floor Grinding Machine Market
Tools
Lathe Machines Market
Tools
Squeegee Market
Tools
Fixed Cutter Bits Market