
 Concrete Saw Market | 2026-2036
Concrete Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Saw Market Analysis
OSHA's respirable crystalline silica rule is expanding enforcement coverage across U.S. construction sites, compelling contractors to replace dry-cutting equipment with water-suppressed or vacuum-integrated concrete saw systems. Husqvarna AB anchors the professional walk-behind segment through its integrated dust-management platforms and rental-channel density. Makita Corporation differentiates in the handheld electric tier with battery-powered masonry solutions that leverage its cordless ecosystem. Hilti AG controls fleet-management services for large contractors, embedding tool-tracking software that sustains recurring revenue attachment rates.
A concrete saw is a power tool or machine engineered to cut through cured concrete, reinforced concrete, asphalt, and masonry using abrasive diamond blades, carbide-tipped discs, or wire embedded with industrial diamonds, with cutting depths ranging from shallow scoring to full-section severance of structural elements. Walk-behind saws dominate highway and airport runway applications where cutting depths exceed 150 millimeters and continuous straight-line accuracy governs joint maintenance quality. Electric power sources are gaining share in indoor demolition and repair settings where emissions compliance and noise ordinances restrict gas-engine operation. Wire saws occupy the premium niche for selective structural dismantling where conventional blade access proves impossible.
OSHA silica standards, EPA emission thresholds for gas-powered equipment, and EU REACH restrictions on abrasive bonding agents collectively reshape product design priorities and market access conditions for concrete saw manufacturers. The U.S. Department of Transportation's Buy America provisions for federally funded infrastructure also constrain sourcing flexibility for blade assemblies and engine components. Stakeholders must monitor regulatory divergence between North American dust-exposure protocols and European chemical-substance restrictions when configuring regional product portfolios and certification investments.
Market Dynamics
OSHA's respirable crystalline silica enforcement is compressing equipment replacement cycles across U.S. construction, forcing contractors to retire dry-cutting fleets ahead of depreciation schedules and redirect capital toward water-suppressed or vacuum-integrated systems.
Growth Catalysts
- Federal bridge rehabilitation mandates:U.S. Department of Transportation funding mechanisms sustain equipment replacement rates among highway maintenance contractors.
- REACH chemical restrictions:ECHA bonding-agent regulations accelerate innovation in blade abrasive formulations across European professional markets.
- Battery platform convergence:Cordless masonry ecosystems reduce operator fatigue in indoor demolition settings where gas-engine bans apply.
Market Restraints
- Diamond abrasive cost volatility:Synthetic diamond supply concentrates in limited production clusters, exposing blade manufacturers to input price swings.
- Gas-engine emission thresholds:EPA Tier 4 Final compliance adds engineering cost and weight penalties to walk-behind saw designs.
- Wire saw technical limitations:Selective dismantling applications require specialized operator training that constrains contractor adoption.
Strategic Opportunities
- Underpenetrated airport runway maintenance:Joint repair specifications in Germany and France specify precision cutting depths that favor advanced walk-behind platforms.
- Buy America blade sourcing:U.S. DOT domestic content rules create captive demand for domestically assembled diamond segments.
- Rental channel digitization:Fleet telemetrics integration enables predictive maintenance scheduling and recurring revenue attachment.
Industry Challenges
- Silica compliance certification timelines:OSHA method validation delays extend product launch schedules for dust-management systems.
- Legacy equipment integration friction:Vacuum-integrated saws require retrofitting incompatible shop-floor extraction infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Saw Market |
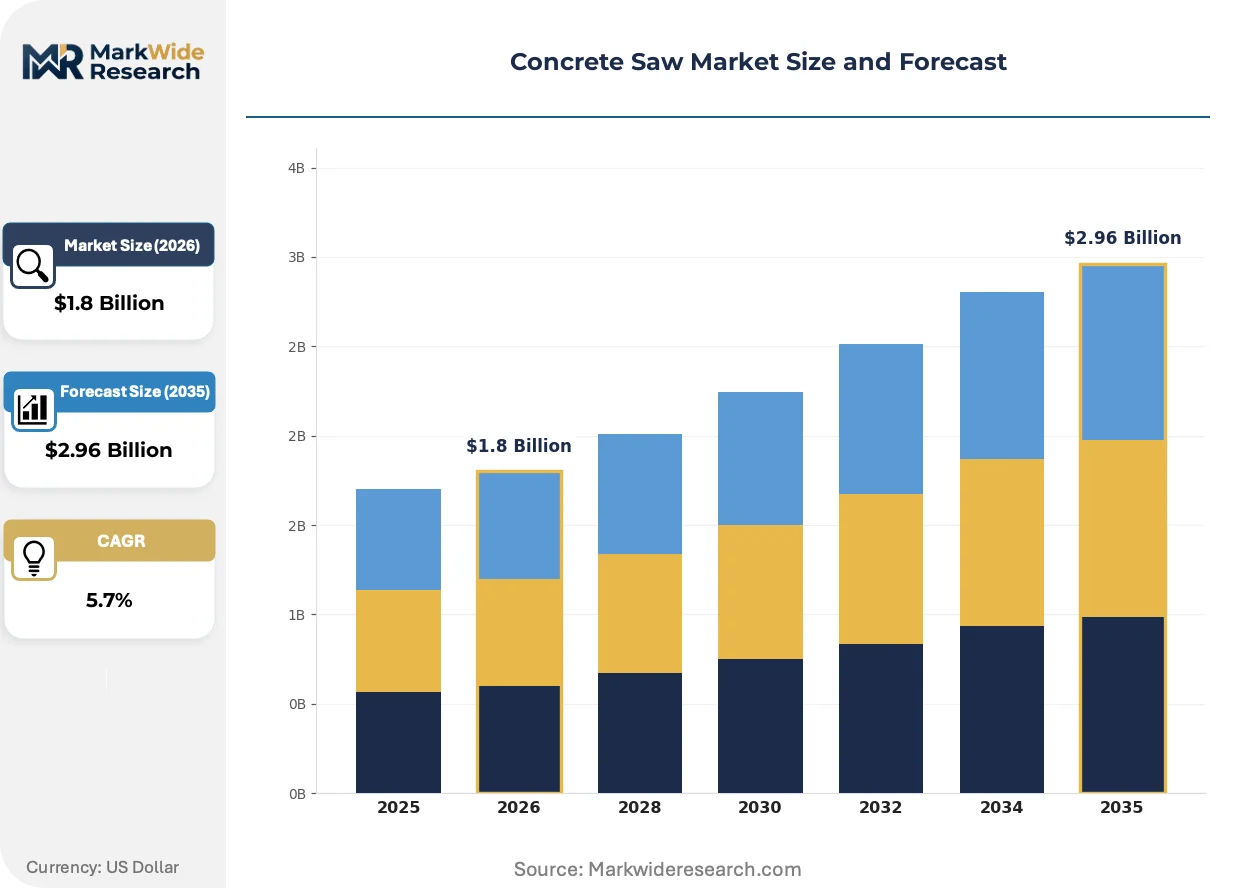
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Saws, Walk-behind Saws, Wall Saws, Wire Saws Power Source: Electric, Gas, Hydraulic, Pneumatic Application: Construction, Demolition, Repair, Flooring End User: Contractors, Construction Companies, DIY Users, Municipalities |
| Companies Covered | Makita Corporation, Wacker Neuson SE, Husqvarna AB, Diamond Products LLC, Tyrolit Schleifmittelwerke Swarovski GmbH, Hilti AG, Robert Bosch GmbH, I.C.S. Cutting Equipment, Inc., Andreas Stihl AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Saw Market Emerging Trajectories
Equipment electrification and connected fleet management are compressing the traditional ownership model, shifting contractor preferences toward performance-guaranteed rental arrangements with embedded compliance monitoring.
Battery-powered concrete cutting platforms are expanding into highway maintenance crews previously wedded to two-stroke gas engines. Municipal contractors in California and New York adopt these systems to satisfy local emission ordinances while maintaining cutting depth specifications. The technology is expanding into specifications that previously excluded cordless equipment.
EPA's tightened silica dust exposure standards are redefining blade guard and water-suppression engineering priorities. Manufacturers must validate capture efficiency rates through third-party testing protocols before OSHA compliance labeling. Walk-behind saw segments face the steepest redesign burden as these machines generate the highest respirable particle volumes.
Equipment-as-a-service contracting is displacing outright purchase in large commercial demolition fleets. Tier-one contractors now specify uptime guarantees and bundled blade replacement rather than capital expenditure. This shift concentrates most visibly in Texas and Florida metropolitan construction markets where fleet scale justifies vendor-managed inventory arrangements.
Concrete Saw Market Segmentation
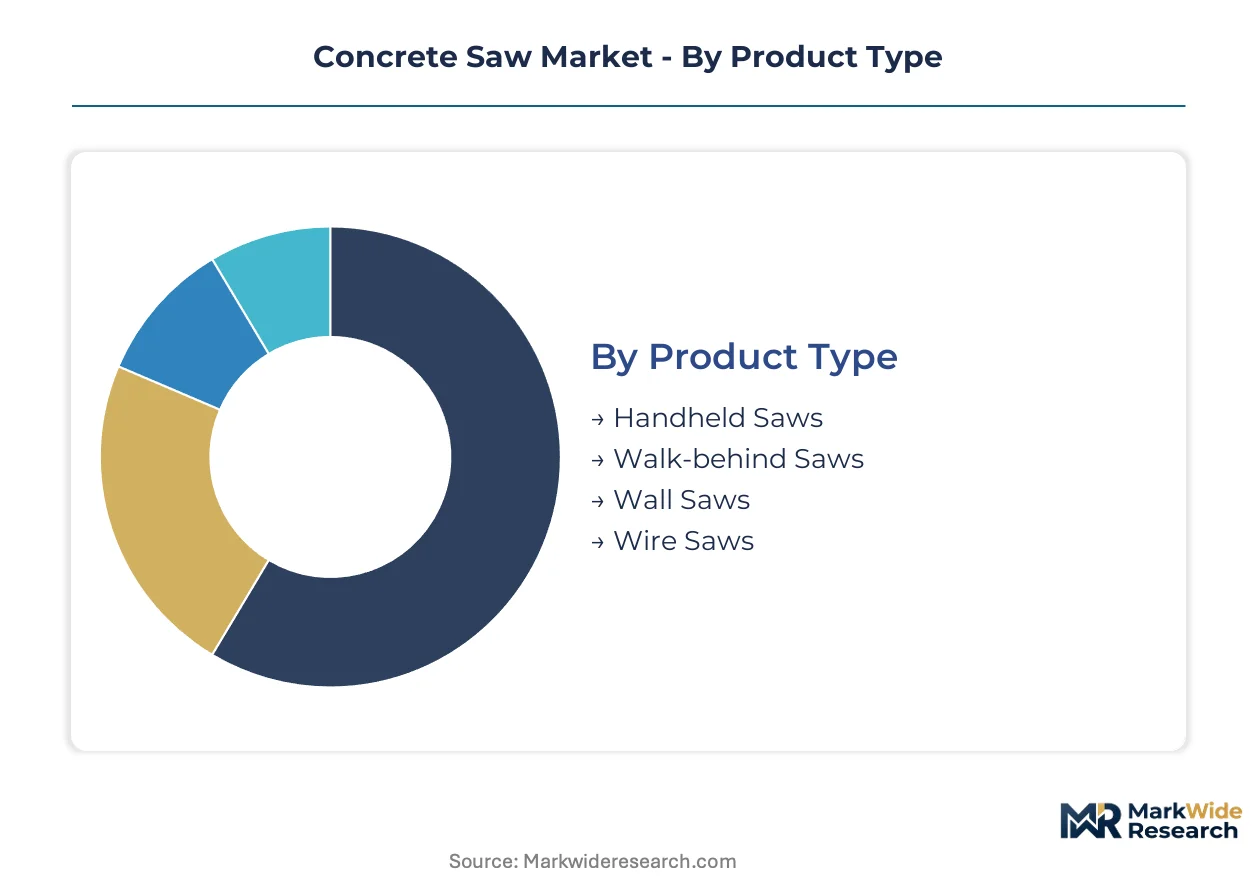
Concrete saw segmentation reflects divergent engineering requirements across cutting depths, power constraints, and jobsite conditions. Equipment specifications must align with OSHA silica exposure protocols, EPA emission thresholds, and the physical demands of reinforced concrete severance.
Product Type:
Supply concentration in diamond blade manufacturing clusters favors platforms with standardized arbor mounts and guard geometries that simplify aftermarket sourcing.
- Handheld Saws:Portable units weighing 15-25 pounds mount diamond blades up to 14 inches for scoring, joint widening, and detail cutting in confined spaces. Demand concentrates among interior demolition crews in California and New York municipalities enforcing gas-engine bans. OSHA wet-cutting mandates accelerate electric model adoption.
- Walk-behind Saws:Self-propelled platforms with 18-48 inch blade diameters achieve cutting depths exceeding 150 millimeters for highway joint maintenance and airport runway rehabilitation. Federal bridge repair programs in the United States sustain replacement cycles among highway maintenance contractors facing silica compliance deadlines.
- Wall Saws:Track-mounted systems enable vertical and horizontal cutting on reinforced concrete walls, bridge abutments, and dam structures where access restricts walk-behind deployment.
- Wire Saws:Diamond-embedded cables navigate irregular geometries and underwater cutting scenarios for selective structural dismantling where blade access proves impossible.
Walk-behind saws absorb the bulk of installed capacity; handheld electric models are expanding most quickly.
Power Source:
Cost tier differentiation separates premium emission-compliant electric systems from economy gas-engine platforms facing regulatory phase-out.
- Electric:Corded and battery-powered motors eliminate exhaust emissions and reduce noise signatures for indoor demolition, hospital renovations, and occupied building modifications. Battery platform convergence from Makita and Milwaukee drives cordless masonry ecosystem adoption.
- Gas:Two-stroke and four-stroke engines deliver portable high-torque output for remote highway maintenance sites lacking grid access. EPA Tier 4 Final compliance adds engineering cost and weight penalties that compress margins.
- Hydraulic:Power units connect to external pumps for underwater cutting and heavy-duty demolition where electrical hazards prohibit corded operation.
- Pneumatic:Compressed air systems serve explosive atmosphere environments and select municipal utility applications with established shop-air infrastructure.
Gas-powered equipment retains the largest installed base; battery-electric configurations are gaining share fastest.
Application:
Volume concentration in new construction contrasts with higher-margin specialized work in controlled demolition and infrastructure rehabilitation.
- Construction:Greenfield concrete cutting for expansion joints, control joints, and structural openings in commercial and residential foundations. Standardized specifications favor rental-channel procurement.
- Demolition:Selective dismantling of reinforced concrete structures, bridge decks, and industrial facilities requiring precision cutting to preserve adjacent elements. Wire saw and wall saw penetration is deepest here.
- Repair:Spall removal, crack remediation, and partial-depth restoration of aging infrastructure. Federal funding mechanisms in the United States sustain equipment utilization rates among specialty repair contractors.
- Flooring:Surface preparation, trench cutting for utility installation, and decorative scoring in commercial and industrial slab work.
Construction applications command the greatest equipment volume; repair work is climbing the fastest.
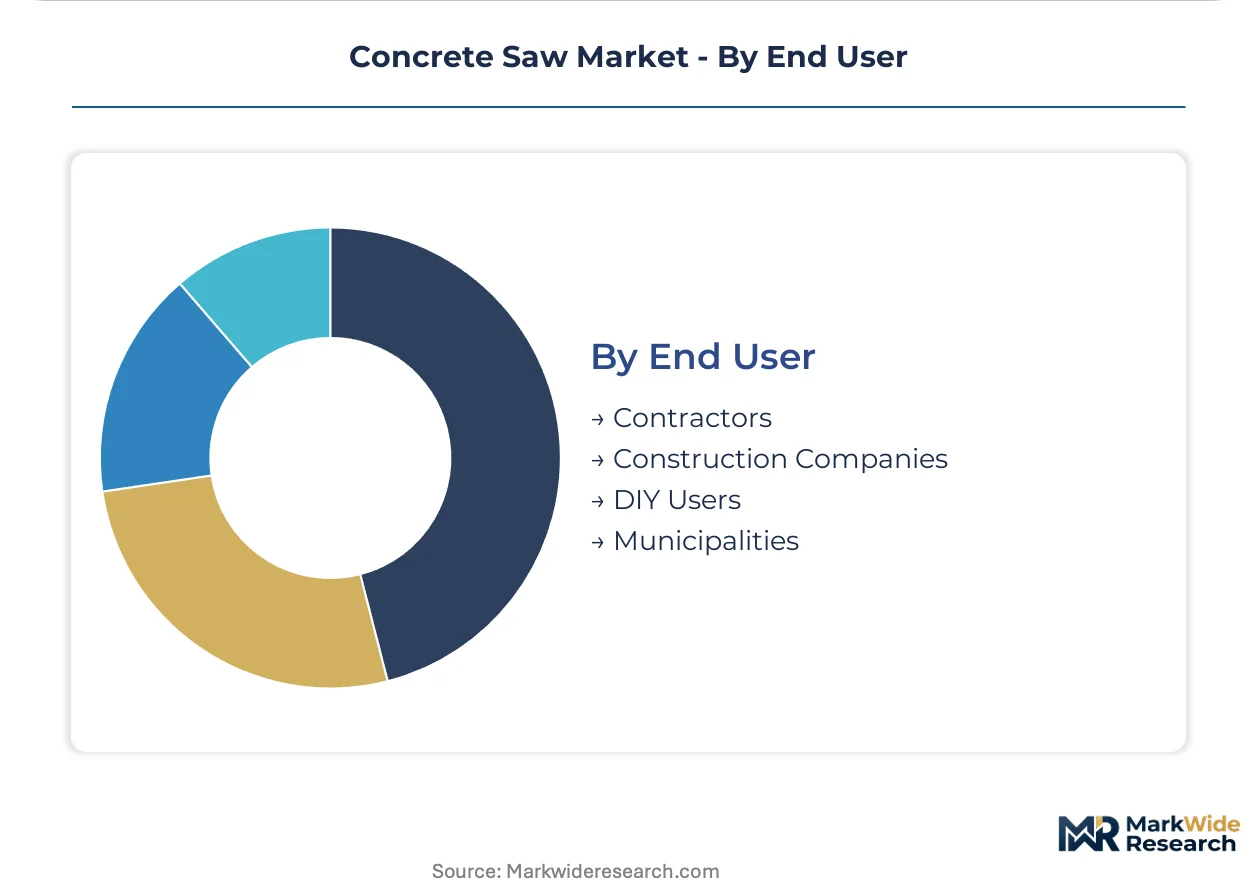
End User:
Customer type determines procurement channel preference, with large fleets favoring rental arrangements and small operators prioritizing capital ownership.
- Contractors:Specialty concrete cutting firms and general demolition contractors operating multi-machine fleets. Equipment-as-a-service contracting with uptime guarantees is displacing outright purchase in Texas and Florida metropolitan markets.
- Construction Companies:General contractors and concrete subcontractors with intermittent cutting requirements favor rental-channel access over capital deployment.
- DIY Users:Residential and light commercial operators purchasing entry-level handheld units through retail distribution.
- Municipalities:City and county highway departments, water authorities, and public works agencies with dedicated maintenance crews. Buy America provisions constrain blade sourcing for federally funded projects.
Contractors absorb the bulk of premium equipment shipments; municipal fleets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American concrete saw demand through its concentration of petrochemical facility maintenance, highway infrastructure corridors, and specialty demolition contractors serving Gulf Coast industrial markets.
United States
Federal bridge rehabilitation programs and commercial building renovation cycles sustain equipment replacement rates across Texas, Florida, and California metropolitan construction markets. OSHA's respirable crystalline silica rule compels contractors to retire dry-cutting fleets and redirect capital toward water-suppressed systems. Houston's petrochemical corridor and Dallas-Fort Worth's highway maintenance networks concentrate walk-behind saw utilization among specialty contractors.
Germany
Airport runway joint repair specifications in Frankfurt and Munich specify precision cutting depths that favor advanced walk-behind platforms. ECHA REACH restrictions on abrasive bonding agents accelerate innovation in blade formulations across European professional markets. Bavaria's construction equipment manufacturing cluster and North Rhine-Westphalia's demolition specialty firms drive specification-grade procurement patterns.
China
Urban renewal initiatives and high-speed rail maintenance programs generate sustained demand for concrete cutting equipment across Yangtze River Delta infrastructure networks. GB standards for construction machinery emissions reshape product design priorities for domestic and export-facing manufacturers. Shanghai's equipment distribution hubs and Guangdong's rental service networks concentrate procurement volume for professional-grade systems.
Japan
Seismic retrofit mandates for aging commercial and public buildings sustain selective dismantling applications in Tokyo and Osaka metropolitan areas. METI energy efficiency guidelines influence electric-powered equipment specifications for indoor demolition settings. Kanto region's precision engineering clusters and Kansai's construction technology integrators drive adoption of wire saw and wall saw platforms.
Australia
Mining infrastructure maintenance and commercial building stock renewal sustain equipment utilization across Queensland and Western Australia resource corridors. State-level workplace health and safety regulations align with ISO silica exposure protocols for professional cutting operations. Sydney's demolition specialty contractors and Melbourne's infrastructure maintenance fleets concentrate premium equipment procurement.
Concrete Saw Market Vendor Landscape
Premium-margin players sit above commodity-margin players across dust-management integration and fleet-service bundling capabilities, compressing returns for undifferentiated blade-and-gas-engine assemblers. The vendor base spans integrated construction equipment conglomerates, specialized diamond tool manufacturers, and regional fabrication shops serving rental channel distributors. Three archetypes dominate: full-service fleet managers with embedded compliance monitoring, diamond abrasive specialists with captive blade technology, and scale-driven equipment assemblers competing on rental channel density. Competitive moves concentrate on strategic partnerships for silica-compliant system validation and geographic expansion into federally funded infrastructure corridors.
Within the integrated equipment tier, Husqvarna AB and Makita Corporation exemplify divergent strategic positions. Husqvarna anchors professional walk-behind deployment through rental-channel infrastructure and dust-management platform integration. Makita occupies a position within cordless masonry ecosystems, leveraging battery platform convergence for indoor demolition specifications. Among specialty abrasive manufacturers, Tyrolit Schleifmittelwerke Swarovski GmbH represents precision-engineered diamond tool archetypes serving selective dismantling applications.
| Leading Market Players |
|---|
| Makita Corporation |
| Wacker Neuson SE |
| Husqvarna AB |
| Diamond Products LLC |
| Tyrolit Schleifmittelwerke Swarovski GmbH |
| Hilti AG |
| Robert Bosch GmbH |
| I.C.S. Cutting Equipment, Inc. |
| Andreas Stihl AG & Co. KG |
| Others |
Supply Flow & Price Mechanics
OSHA silica compliance certification creates a sharp tier divergence between dust-management-integrated platforms and legacy dry-cutting equipment, with that divergence manifesting in both pricing premiums of 40-60% for certified systems and supply chain configurations that concentrate blade guard engineering in Germany and China while domestic assembly clusters serve U.S. DOT Buy America mandates.
Pricing Analysis
Uptime-guaranteed rental contracts anchor value-based pricing for walk-behind saw fleets serving highway maintenance contractors. Three-tier pricing structure across premium, standard, and economy levels separates Hilti-style fleet-managed bundles from rental-channel commodity units and retail handheld models. Pricing pressure stems from EPA Tier 4 Final engineering costs compressing margins on gas-engine platforms. Municipal procurement teams exhibit highest price sensitivity; petrochemical facility maintenance contractors show lowest.
Supply Chain Analysis
Dual-sourcing requirements from U.S. DOT-funded contractors mandate qualified blade segment suppliers in both domestic assembly plants and German precision manufacturing clusters. Synthetic diamond feedstock concentrates in China, Russia, and South Africa; carbide substrates source from Sweden and Austria. Single-source vulnerability runs through synthetic diamond supply given production concentration. Distribution runs through rental channel networks with embedded service technicians for preventive maintenance scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic diamond synthesis capacity constraints prop pricing power for blade manufacturers, as limited reactor installations cap abrasive output expansion regardless of downstream equipment demand.
For Market Incumbents: To counter battery-electric platform entrants from cordless tool ecosystems, Husqvarna and Wacker Neuson should deepen backward integration into diamond segment manufacturing while locking exclusive rental channel partnerships in Texas and Florida metropolitan corridors. Certification investment in OSHA method validation laboratories accelerates compliant product launch timelines against smaller competitors. For New Entrants and Emerging Players: EPA silica enforcement in California and New York opens a window for handheld electric saw specialists to capture interior demolition contractors abandoning gas-engine fleets. Airport runway joint repair specifications in Germany and France represent underpenetrated precision cutting demand. Go-to-market through equipment-as-a-service contracting with embedded blade replacement subscriptions bypasses incumbent rental density. For Investors and Strategic Acquirers: Re-rating potential sits with diamond abrasive specialists given REACH-driven formulation innovation accelerating across European professional markets. Long-term viability favors captive blade technology platforms over equipment assemblers facing commoditization. Watch EPA enforcement expansion into commercial building renovation as inflection signal for wet-cutting equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Compliant System Validation | OSHA third-party testing protocols create regulatory moats for early certifiers. |
| Backward Integration into Diamond Synthesis | Captive abrasive supply insulates margins from synthetic diamond price volatility. |
| Rental Channel Digitization | Fleet telemetrics integration enables predictive maintenance and recurring revenue attachment. |
| Buy America Blade Sourcing | U.S. DOT domestic content rules create captive demand for qualified assembly plants. |
| Battery Platform Convergence | Makita and Milwaukee cordless ecosystems reduce operator fatigue in emission-restricted indoor settings. |
Methodological Framework
Document review covered OSHA enforcement bulletins, EPA emission compliance databases, and ECHA REACH substance restrictions, complemented by interviews with equipment rental channel managers, highway maintenance procurement officers, diamond tool manufacturing engineers, and concrete cutting contractor fleet supervisors. Secondary sources included U.S. DOT funding appropriation records, customs trade data for diamond abrasive imports, and SEC 10-K filings from listed construction equipment manufacturers. Bottom-up equipment shipment estimates triangulated against top-down infrastructure spending allocations.
Historical replacement cycle patterns cross-referenced against panel input from contractor fleet managers informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, power source, application, and end-user procurement channel. CAGRs derived from equipment unit economics and blade consumables attachment rates. Forecast inputs incorporated federal bridge rehabilitation funding trajectories and municipal emission ordinance adoption curves.
The model assumes a particular technology adoption path for battery-electric platforms; alternative pathways for hydrogen fuel cell power would alter the outlook for gas-engine phase-out timing. Forecasts reflect assumptions regarding OSHA enforcement intensity and synthetic diamond supply expansion. Deviation in EPA Tier 5 emission rulemaking would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Rebar Cutter Market
Tools
Cordless Long Neck Grinder Market
Tools
Nail Gun Market
Tools
Adoption of Benelux Power Tools Market
Tools
Industrial Plate Bending Machines Market
Tools
Deburring Tool Market
Tools
Europe Machine Tools Market
Tools
Rotary Tools Market
Tools
Turning Tools Market
Tools
Rivet Busters Market
Tools
Fixed Cutter Bits Market
Tools
Wire Cutters Market
Tools
Hand Saw Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Reamer Market