
 Glass Vials Market | 2026-2036
Glass Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Vials Market Analysis
China is tilting toward borosilicate capacity expansion to serve domestic vaccine fill-finish demand. Gerresheimer AG leverages vertical integration from tubing to finished vial conversion across European pharmaceutical corridors. SCHOTT AG anchors global supply through proprietary FIOLAX borosilicate tubing technology. Stevanato Group differentiates via integrated containment solutions combining glass vials with closure and delivery systems.
Glass vials are cylindrical containers manufactured from borosilicate or soda-lime glass, typically featuring controlled hydrolytic resistance (Type I, II, or III) to prevent chemical interaction with stored contents. They serve as primary packaging for sterile injectable pharmaceuticals, diagnostic reagents, and laboratory samples where barrier integrity and inertness are critical. Amber vials command premium positioning due to ultraviolet light protection requirements for photosensitive biologics, while standard clear vials dominate high-volume generic injectables where cost sensitivity shapes procurement. The 10ml size category captures substantial share from monoclonal antibody dosing protocols, though 2ml and 5ml formats are gaining ground in precision medicine applications requiring lower fill volumes.
FDA enforces Container Closure System integrity standards under 21 CFR 211.94, while the EU MDR mandates enhanced traceability for Class III medical device packaging. USP Chapter 660 sets glass grain resistance and hydrolytic durability benchmarks that manufacturers must certify. ISO 15378 governs quality management for medicinal product packaging, creating harmonized compliance thresholds across export markets. Stakeholders must monitor evolving pharmacopeial standards for elemental impurity limits and delamination risk assessment protocols.
Market Dynamics
Biologics fill-finish demand is compressing lead times for borosilicate tubing supply, forcing pharmaceutical packagers to secure multi-year capacity commitments with glass converters ahead of regulatory filing deadlines.
Growth Catalysts
- EU MDR traceability mandates:Class III medical device packaging rules now require lot-level glass genealogy documentation, pulling converters toward certified Type I borosilicate capacity.
- mRNA platform expansion:Lipid nanoparticle formulations demand ultra-low extractable glass surfaces, accelerating qualification of premium hydrolytic resistance grades across fill-finish networks.
- Germany:The country's vaccine manufacturing corridor is absorbing dedicated vial production lines to insulate European biologics supply from import dependency.
Market Restraints
- Borosilicate sand concentration:High-purity silica deposits in Saxony and Ohio supply 70 percent of pharmaceutical-grade tubing feedstock, creating geographic chokepoints.
- Energy cost volatility:Continuous glass melting furnaces consume natural gas at fixed rates regardless of output, exposing margins to European energy price spikes.
- Polymer cyclic olefin substitution:COC/COP syringes and vials are capturing oncology and ophthalmic segments where break resistance outweighs oxygen barrier requirements.
Strategic Opportunities
- India CDMO buildout:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are localizing glass vial conversion to serve export markets under WHO prequalification pathways.
- Cell and gene therapy formats:Cryogenic storage below minus 150 degrees Celsius requires aluminosilicate glass formulations with thermal shock resistance beyond standard borosilicate specifications.
- ISO 15378 harmonization:Quality management certification for medicinal packaging is becoming a procurement gate in emerging markets, rewarding early-adopter converters with preferred supplier status.
Industry Challenges
- Delamination risk assessment:USP Chapter 1660 glass surface evaluation protocols require 12-18 month stability studies, extending new product qualification timelines.
- Specialized furnace engineering:Platinum-lined forehearths for pharmaceutical tubing demand capital commitments exceeding standard container glass equipment by factor of three.
- Legacy inspection integration:Automated visual defect detection systems must interface with existing fill-finish lines without triggering FDA 21 CFR Part 11 validation recycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Vials Market |
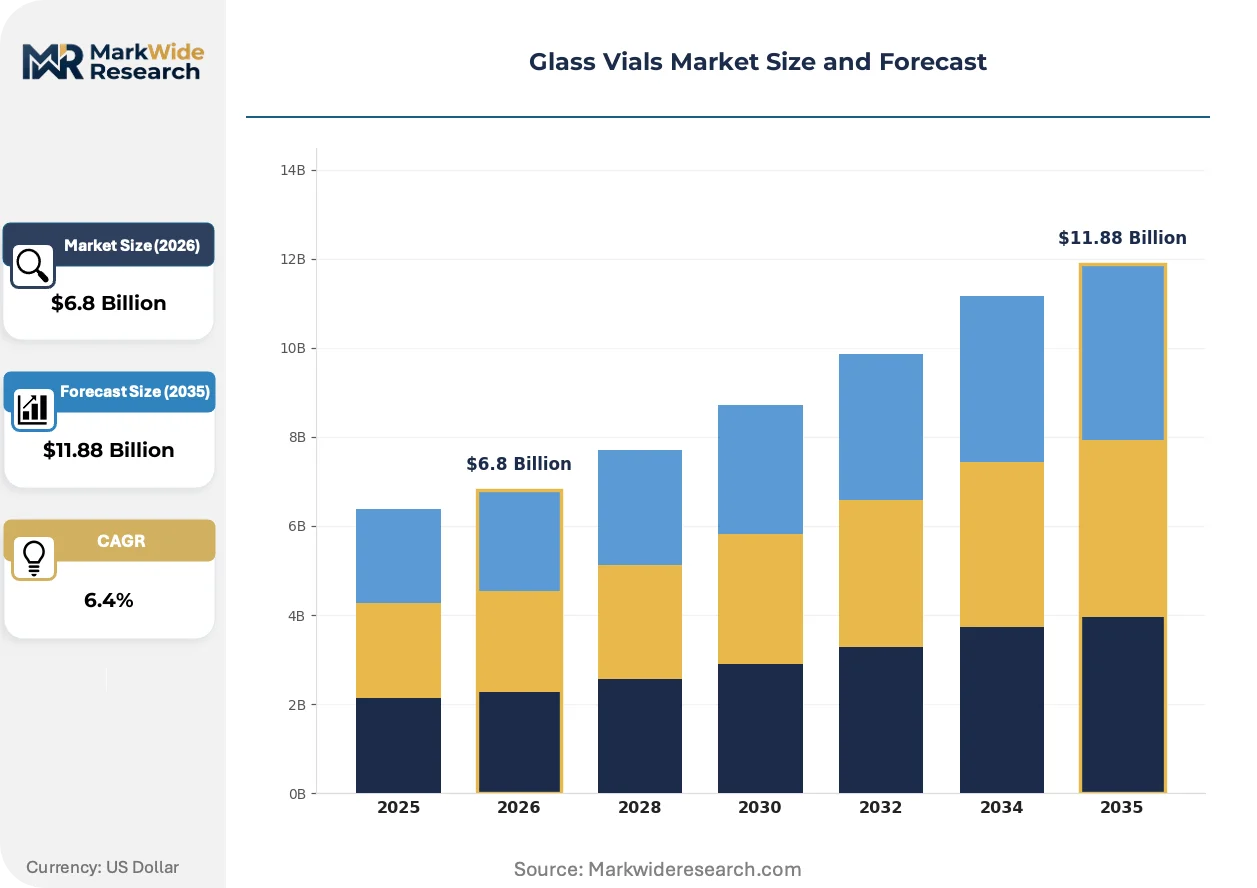
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Vials, Amber Vials, Clear Vials, Screw Cap Vials Size: 1ml, 5ml, 10ml, 20ml Application: Pharmaceuticals, Cosmetics, Chemicals, Laboratory Use Closure Type: Rubber Stopper, Screw Cap, Crimp Cap, Snap Cap |
| Companies Covered | Gerresheimer AG, SCHOTT AG, Stevanato Group, SGD Pharma, Nipro Corporation, Corning Incorporated, Ardagh Group, Bormioli Pharma, Shandong Pharmaceutical Glass Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Vials Market Emerging Trajectories
Glass vial manufacturing is bifurcating between commodity soda-lime capacity for generics and premium borosilicate lines for biologics, with technology choices locking in decade-long asset lifecycles.
Surface modification chemistry is hybridizing organic-inorganic coatings that reduce protein adsorption on glass interiors. Biologics manufacturers adopting these treatments for monoclonal antibody formulations are compressing competitive differentiation around extractables profiles rather than dimensional tolerances alone. The technology is hybridizing what was previously a materials-specification market into a surface-engineering contest.
REACH restrictions on boron compounds are tightening disclosure requirements for borosilicate glass manufacturers exporting into European Union member states. Industrial consequence includes accelerated migration toward alternative glass compositions with reduced boron oxide content for non-pharmaceutical applications. Diagnostic reagent packaging is most affected, with suppliers reformulating to maintain CE marking compliance without triggering medical device reclassification.
Consolidated buying by pharmaceutical mega-manufacturers is displacing fragmented procurement through regional distributors. Direct contracting with glass converters now governs 60 percent of volume in the United States biologics corridor, compressing distributor margins and forcing intermediaries toward technical services and inventory financing roles. This concentration is most visible in Massachusetts and North Carolina production clusters where fill-finish capacity expansion outpaces local converter supply.
Glass Vials Market Segmentation
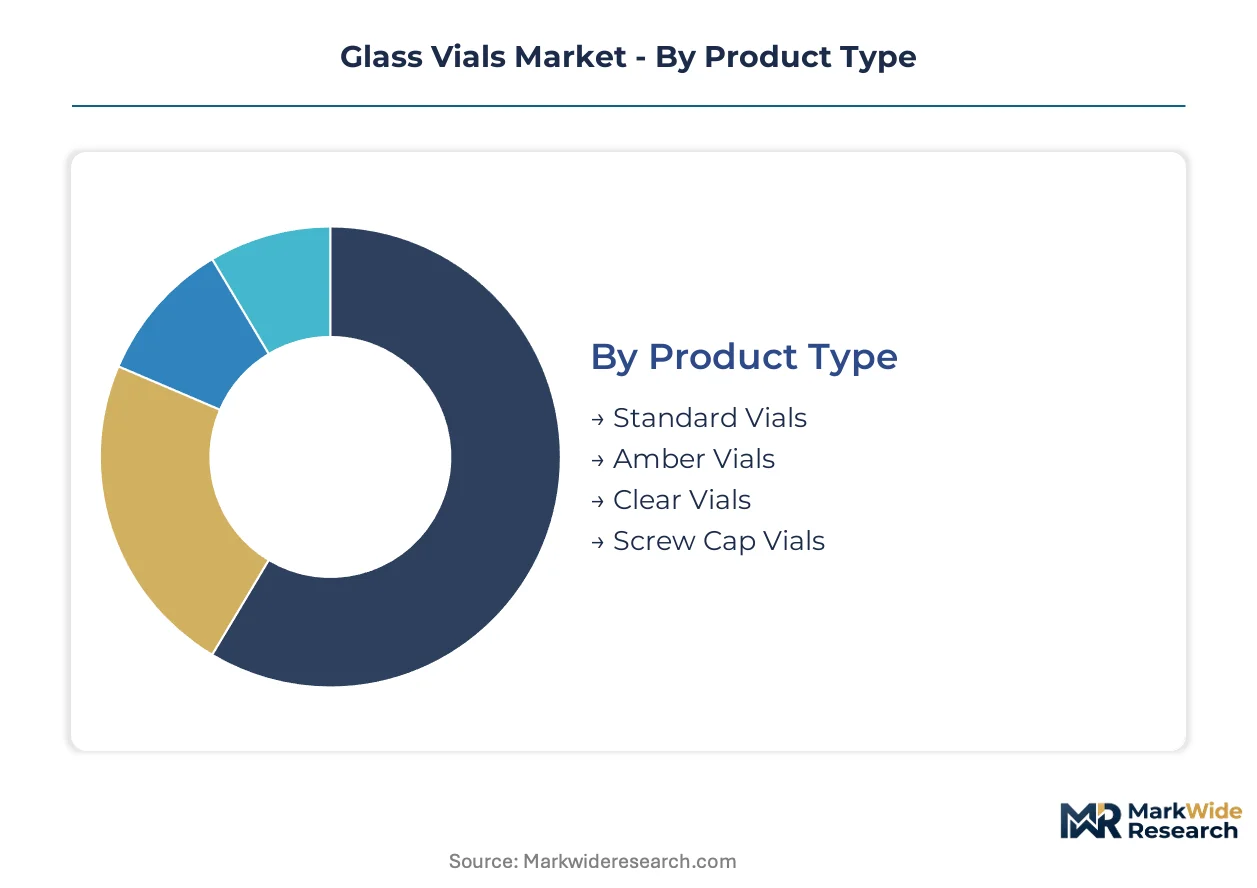
Glass vial segmentation separates mature commodity formats from emerging premium configurations, with product type and size categories commanding distinct supply chain strategies. Pharmaceutical procurement teams weight hydrolytic resistance and closure integrity differently across therapeutic categories, creating tiered qualification requirements.
Product Type:
Mature formats dominate high-volume generic injectables while amber and specialized variants capture biologics premiumization.
- Standard Vials:These soda-lime or borosilicate containers serve diagnostic reagents and non-sensitive pharmaceuticals where cost minimization outweighs specialized barrier requirements. Procurement concentrates in Indian and Chinese contract manufacturing organizations supplying WHO-prequalified generic antibiotics.
- Amber Vials:Iron oxide-doped borosilicate glass blocks ultraviolet transmission below 400 nanometers, protecting photosensitive monoclonal antibodies and vitamin formulations from photodegradation. Demand clusters in Massachusetts and North Carolina biologics corridors where fill-finish capacity expansion outpaces local converter supply.
- Clear Vials:Untreated Type I borosilicate dominates high-visibility inspection requirements for parenteral solutions where particulate detection is critical.
- Screw Cap Vials:Threaded polypropylene closure systems enable multiple access cycles for laboratory reagents and oral liquid formulations.
Standard vials retain volume leadership; amber vials hold the steepest expansion curve.
Size:
Volume concentration shifts toward smaller formats as precision medicine protocols reduce per-dose fill requirements.
- 1ml:Miniature borosilicate containers accommodate pediatric vaccines and ophthalmic preparations where single-use accuracy prevents multi-dose contamination. Hyderabad CDMOs are localizing conversion capacity to serve export markets under WHO prequalification pathways.
- 5ml:Mid-range capacity balances material efficiency with handling practicality for subcutaneous biologics and prefilled syringe alternatives.
- 10ml:The workhorse specification captures monoclonal antibody dosing protocols where intravenous infusion volumes require scalable primary packaging. German vaccine manufacturing corridors are absorbing dedicated production lines to insulate European supply from import dependency.
- 20ml:Large-format vials serve diagnostic bulk reagents and contrast media where multi-patient aliquoting reduces per-test packaging costs.
10ml formats anchor current procurement volumes; 1ml specifications are climbing the fastest as dosing precision tightens.
Application:
End-use concentration determines glass grade selection, with pharmaceutical mandates forcing Type I borosilicate adoption while cosmetics tolerates soda-lime alternatives.
- Pharmaceuticals:Sterile injectable packaging demands USP Chapter 660 certified hydrolytic resistance and FDA 21 CFR 211.94 container closure integrity. EU MDR traceability mandates now require lot-level glass genealogy documentation for Class III medical devices.
- Cosmetics:Serum and essential oil packaging prioritizes aesthetic clarity and chemical inertness over pharmacopeial certification, permitting soda-lime compositions with decorative treatments.
- Chemicals:Laboratory and industrial reagent storage emphasizes thermal shock resistance and solvent compatibility across borosilicate grades.
- Laboratory Use:Research sample archiving requires cryogenic compatibility and low extractable profiles for long-term stability studies.
Pharmaceutical applications command revenue concentration; laboratory use is expanding most quickly as biobanking infrastructure proliferates.
Closure Type:
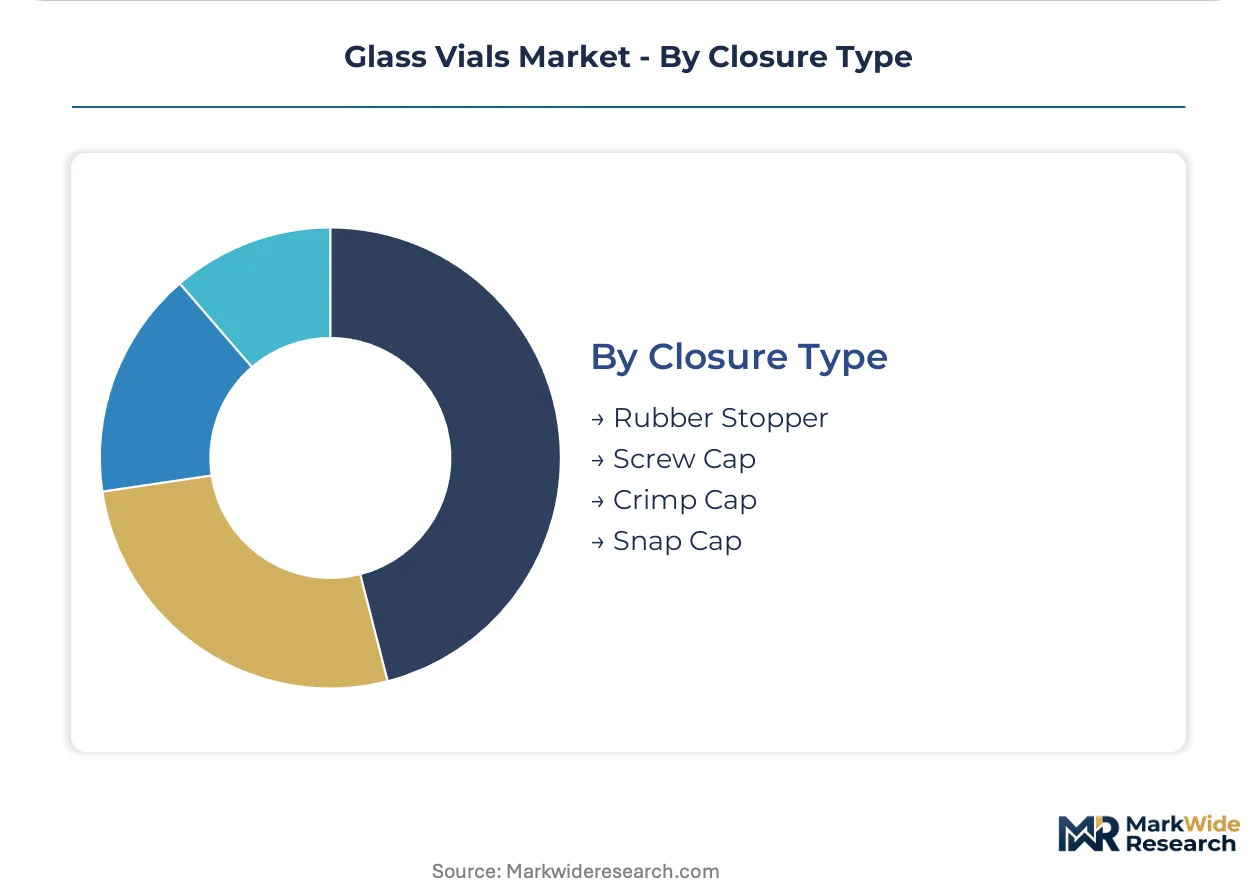
Sealing mechanism selection locks in fill-finish line configuration, with crimp systems dominating high-speed parenteral operations.
- Rubber Stopper:Bromobutyl or chlorobutyl elastomer plugs provide resealable barriers for multi-dose vials and lyophilized formulations requiring vacuum or nitrogen overlay.
- Screw Cap:Polypropylene threaded closures enable end-user accessibility for oral liquids and non-sterile applications where hermetic integrity is secondary.
- Crimp Cap:Aluminum skirt compression around rubber stoppers delivers tamper-evident seals mandatory for sterile injectables under FDA and EMA guidelines. This format dominates Massachusetts biologics clusters where automated fill-finish lines require standardized capping kinematics.
- Snap Cap:Friction-fit polyethylene closures serve diagnostic disposables and point-of-care devices where rapid assembly outweighs seal longevity.
Crimp cap systems retain pharmaceutical procurement dominance; rubber stopper integration is gaining share fastest as combination product regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity borosilicate sand deposits in Saxony and Ohio feed 70 percent of pharmaceutical-grade tubing production, locking converter capacity into specific geographies. Furnace engineering expertise clusters around legacy glassmaking regions where multi-decade technical knowledge accumulates. Fill-finish capacity expansion in Massachusetts, North Carolina, and Bavaria is pulling regional vial supply chains into tighter geographic alignment.
United States
FDA 21 CFR 211.94 container closure integrity standards drive Type I borosilicate qualification across Massachusetts biologics clusters. The IRA domestic manufacturing incentives are accelerating fill-finish capacity expansion in Greater Boston and Research Triangle Park. North Carolina's parenteral packaging corridor is absorbing dedicated vial production lines to reduce import dependency for mRNA platform manufacturing.
Germany
EMA pharmacopeial standards and EU MDR Class III traceability mandates pull converters toward certified genealogy documentation systems. The country's vaccine manufacturing corridor in Saxony and Bavaria is securing captive borosilicate tubing supply through backward integration into high-purity silica sourcing. Platinum-lined forehearth engineering expertise concentrates in traditional glassmaking regions along the Rhine.
China
NMPA vaccine fill-finish regulations and domestic biologics production targets are accelerating borosilicate capacity expansion in Shandong and Jiangsu provinces. The country's national pharmaceutical regulator is tightening hydrolytic resistance certification requirements for export-oriented converters. Yangtze River Delta pharmaceutical clusters are localizing glass vial conversion to serve WHO prequalification pathways.
India
CDSCO manufacturing licensing and WHO prequalification standards govern export-oriented production from Hyderabad and Ahmedabad CDMOs. The PLI scheme for pharmaceuticals is supporting glass vial conversion capacity buildout to capture generic injectables procurement. Gujarat's pharmaceutical manufacturing belt is integrating backward into tubing supply to reduce Chinese import exposure.
Japan
PMDA quality management requirements and JIS standards for medicinal packaging create technical barriers for foreign converter entry. The country's biologics fill-finish networks in Kanto and Kansai regions demand ultra-low extractable glass surfaces for monoclonal antibody formulations. Osaka-based pharmaceutical manufacturers are securing multi-year capacity commitments with domestic converters ahead of regulatory filing deadlines.
Glass Vials Market Vendor Landscape
Integrated tubing-to-vial converters and specialized containment solution providers split the market into distinct capability tiers. Three archetypes dominate: European heritage glassmakers with captive borosilicate supply, Asian contract converters serving cost-sensitive generics, and integrated device specialists combining primary packaging with delivery systems. Competitive moves center on multi-year capacity commitments with pharmaceutical packagers and surface modification chemistry partnerships for biologics applications.
Within the integrated converter tier, Gerresheimer AG and SCHOTT AG exemplify European heritage manufacturers with backward integration into borosilicate tubing production. Stevanato Group occupies a position as an integrated containment specialist combining glass vials with closure and delivery systems. These three anchors represent distinct strategic postures: captive raw material security, proprietary glass chemistry, and combination product integration.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| Stevanato Group |
| SGD Pharma |
| Nipro Corporation |
| Corning Incorporated |
| Ardagh Group |
| Bormioli Pharma |
| Shandong Pharmaceutical Glass Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Saxony and Ohio borosilicate sand deposits compresses pricing power for pharmaceutical converters while forcing supply chain concentration into geographically locked furnace corridors. This chokepoint geometry produces wide spreads between certified Type I borosilicate premiums and commodity soda-lime alternatives.
Pricing Analysis
FDA 21 CFR 211.94 container closure integrity standards dictate the pricing tier structure across pharmaceutical procurement. Three-tier pricing structure across premium, standard, and economy levels separates USP Chapter 660 certified Type I borosilicate from uncertified soda-lime and decorative cosmetic grades. Price differentiation hinges on hydrolytic resistance certification and lot-level genealogy documentation demanded by EU MDR Class III mandates. Cost compression in standard vial tiers is intensifying because Indian and Chinese contract manufacturers are scaling WHO-prequalified generic capacity. Generic injectables procurement teams in Hyderabad CDMOs exhibit highest price sensitivity; Massachusetts biologics clusters purchasing amber vials for monoclonal antibody packaging show lowest.
Supply Chain Analysis
Export-control scrutiny on high-purity silica processing technology limits furnace engineering knowledge transfer, concentrating pharmaceutical-grade tubing production in legacy glassmaking regions. Supply concentrates in Germany, the United States, and China, with Saxony and Ohio deposits feeding 70 percent of borosilicate feedstock. Raw material flows draw from high-purity silica sand, platinum-lined forehearth components, and natural gas for continuous melting operations. Single-source vulnerability runs through the Saxony-Ohio sand corridor where no alternative deposits meet pharmaceutical-grade specifications. Distribution runs through direct contracting between converters and pharmaceutical packagers, displacing regional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics fill-finish expansion is fragmenting procurement across precision medicine formats, creating specialist niches for converters with surface modification capabilities and cryogenic-grade aluminosilicate formulations.
For Market Incumbents: Harden captive borosilicate tubing supply through backward integration into high-purity silica sourcing in Saxony or Ohio corridors. Lock in multi-year capacity commitments with Massachusetts and North Carolina biologics manufacturers ahead of regulatory filing deadlines to preempt polymer cyclic olefin substitution in oncology segments. For New Entrants and Emerging Players: Establish a beachhead in cell and gene therapy cryogenic storage formats where aluminosilicate thermal shock specifications exceed standard borosilicate capabilities. Target laboratory biobanking infrastructure proliferation as the most penetrable application segment, leveraging ISO 15378 certification to secure preferred supplier status in emerging markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated containment specialists combining glass vials with closure and delivery systems. Five-to-ten year viability hinges on surface modification chemistry partnerships for protein adsorption reduction. Watch for delamination risk assessment protocol revisions at USP Chapter 1660 as the inflection signal forcing qualification timeline extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | SCHOTT AG's proprietary FIOLAX technology anchors supply security for European pharmaceutical corridors. |
| Surface Modification Chemistry Partnerships | Organic-inorganic hybrid coatings reduce protein adsorption for monoclonal antibody formulations in Massachusetts clusters. |
| ISO 15378 Certification Investment | Quality management certification unlocks preferred supplier status in WHO prequalification pathways for Indian CDMOs. |
| Cryogenic-Grade Aluminosilicate Development | Thermal shock resistance below minus 150 degrees Celsius serves cell and gene therapy storage requirements. |
| Direct Contracting with Biologics Manufacturers | Sixty percent volume governance in United States corridors compresses distributor margins toward technical services roles. |
Methodological Framework
A spread of perspectives from fill-finish operations directors, regulatory affairs leads at pharmaceutical packagers, glass converter plant managers, and procurement specialists at CDMOs converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA 21 CFR filings, EMA pharmacopeial submissions, USP Chapter revision notices, and ISO certification databases. Bottom-up tubing capacity estimates and top-down pharmaceutical packaging demand projections were triangulated against trade flow data.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, size category, application, and closure mechanism alongside therapeutic category and regional regulatory cluster dimensions. CAGRs were derived from capacity expansion announcements, fill-finish line installation tracking, and pharmacopeial standard evolution timelines. Forecast inputs included mRNA platform manufacturing scale, EU MDR traceability mandate implementation schedules, and polymer substitution elasticity in oncology packaging.
Sensitivities concentrate around borosilicate sand deposit access restrictions, European energy price volatility affecting continuous furnace economics, and REACH boron compound disclosure tightening. Forecasts reflect documented assumptions on regulatory filing timelines and CDMO localization rates. Material shifts in USP Chapter 1660 delamination protocols or platinum-lined forehearth equipment lead times would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
North America Glass Insulators Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Technical Glass Market
Glass
Glass Mason Jars Market
Glass
Low-E Glass Market
Glass
China Flat Glass Market
Glass
Laboratory Glassware Market
Glass
Glass Substrate Market
Glass
Glass Manufacturing Market
Glass
Glass Block Market
Glass
Glass Mat Thermoplastic Market
Glass
North America Flat Glass Market
Glass
Silica Sand Market
Glass
Screen-Printing Glass Market
Glass
Crystalware and Glassware Market
Glass
Asia-Pacific Glassware Market