
 Tamper Evident Bag Sealers Market | 2026-2036
Tamper Evident Bag Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Tamper Evident Bag Sealers Market Analytics
Direct distribution to pharmaceutical contract packagers is fragmenting as regional equipment dealers and digital procurement platforms capture mid-size buyers. PAC Machinery leverages its North American service network to sustain aftermarket revenue from heat-sealer installations. Tamper Technologies specializes in adhesive-sealer systems for forensic and evidence-handling applications, occupying a defensible niche with limited direct competition. Innoseal Systems controls European pharmaceutical accounts through CE-marked equipment and localized technical support.
Tamper evident bag sealers are electromechanical devices that apply irreversible closure mechanisms to flexible packaging, typically operating at temperatures between 120°C and 200°C for heat-sealed variants or employing pressure-sensitive adhesive tapes for cold-sealed formats. Their primary purpose is to provide visible proof of unauthorized access, protecting product integrity across supply chains. Heat sealers dominate pharmaceutical and food applications where hermetic barrier properties are mandatory, while adhesive sealers are gaining share in electronics and cosmetics for their compatibility with temperature-sensitive contents. Clip sealers remain a mature, cost-driven category with thinner margin pools concentrated in bulk industrial supply.
FDA 21 CFR Part 11 and EU MDR traceability requirements are compelling pharmaceutical packagers to upgrade to validated sealing equipment with audit-ready documentation. The EPA and OSHA frameworks in the United States additionally shape equipment specifications through emissions and workplace safety standards for thermal sealing operations. ISO 9001 and ISO 15378 certifications are becoming baseline qualifications for vendor selection in regulated industries. Stakeholders must weigh capital deployment between validated pharmaceutical-grade systems and versatile multi-material platforms as end-user compliance requirements diverge.
Market Dynamics
Pharmaceutical serialization mandates and cold-chain integrity requirements are compressing equipment replacement cycles, forcing packagers to abandon legacy heat-sealers for validated systems with audit-trail documentation. This regulatory pressure layer intersects with supply-chain regionalization, creating divergent procurement patterns across developed and emerging manufacturing clusters.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements compel pharmaceutical contract packagers to install validated sealing equipment with tamper-evident documentation trails. Equipment vendors report accelerated upgrade cycles among US-based drug distributors.
- Cold-chain biologics expansion:Temperature-sensitive gene therapies and mRNA vaccines require hermetic barrier sealing at cryogenic-compatible specifications, driving demand for precision heat-sealers with validated temperature control.
- EU MDR serialization:Medical device traceability mandates in Germany and neighboring export markets tighten packaging integrity standards, prompting equipment procurement from CE-marked suppliers with localized technical support.
Market Restraints
- Stainless steel and copper input volatility:Heat-sealer chassis and heating element fabrication depends on commodity metals subject to supply disruption and price swings, compressing OEM margin structures.
- Validated equipment supply concentration:Pharmaceutical-grade systems with ISO 15378 certification concentrate among a limited vendor base in Western Europe and North America, creating procurement bottlenecks for mid-size Asian packagers.
- Adhesive-sealer temperature limitations:Pressure-sensitive tape systems fail to achieve hermetic barrier properties required for moisture-sensitive pharmaceuticals, restricting their addressable market within regulated drug packaging.
Strategic Opportunities
- Indian pharmaceutical contract manufacturing:CDSCO export compliance requirements and PLI scheme incentives are expanding packaging capacity in Hyderabad and Ahmedabad clusters, creating equipment demand from both multinational and domestic sealers.
- Blockchain-integrated audit trails:Convergence of IoT-enabled sealing equipment with distributed ledger verification is digitizing chain-of-custody documentation for forensic evidence handling and high-value logistics.
- Digital procurement platforms:Mid-size pharmaceutical and cosmetics packagers in Southeast Asia are bypassing traditional distributor networks for direct equipment sourcing, lowering customer acquisition costs for agile OEMs.
Industry Challenges
- Validation engineering talent scarcity:Pharmaceutical equipment qualification requires specialists fluent in FDA and EMA documentation protocols; this expertise concentrates among aging workforces in Germany and Switzerland, constraining vendor scale-up.
- Legacy system integration friction:Brownfield pharmaceutical facilities operate mixed-vintage packaging lines where new sealing equipment must interface with decade-old PLCs and MES architectures, extending commissioning timelines.
- CE marking timeline compression:EU MDR's tightened conformity assessment procedures delay equipment market entry by six to eighteen months, disadvantaging smaller OEMs against entrenched competitors with notified body relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamper Evident Bag Sealers Market |
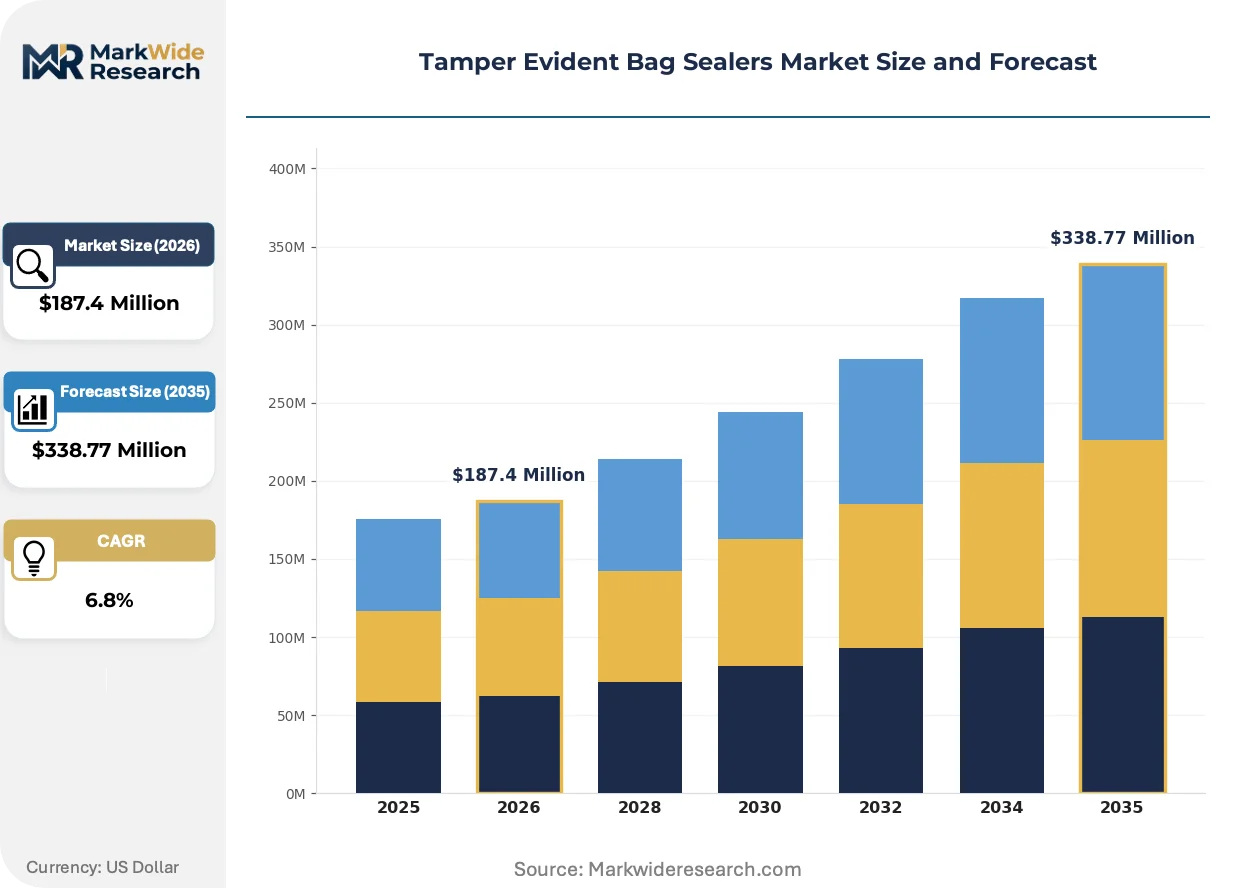
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sealers, Cold Sealers, Adhesive Sealers, Clip Sealers End User: Food Industry, Pharmaceutical Industry, Cosmetics Industry, Electronics Sector Material: Polyethylene, Polypropylene, Nylon, Polyester Seal Type: Flat Seals, Gusseted Seals, Zipper Seals, Pressure Seals |
| Companies Covered | Innoseal Systems, Tamper Technologies, PAC Machinery, Quick Pak, Adsure Packaging, Butler Staple, Packaging Aids, Joke Folienschweitechnik, Multiko Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamper Evident Bag Sealers Market Evolving Landscape
Equipment intelligence and materials science are converging to redefine tamper-evident sealing from passive mechanical function to active supply-chain verification node. Three developments dominate vendor R&D roadmaps and buyer specification sheets.
Smart heat-sealing systems equipped with embedded temperature sensors and edge computing capability are digitizing quality assurance workflows. Pharmaceutical contract packagers in Germany and Switzerland are deploying these units to eliminate manual seal-inspection labor. Real-time thermal profiling generates machine-readable compliance records that integrate directly with batch release systems.
EU MDR traceability requirements are mandating unique device identification on medical device packaging, forcing sealers to accommodate inline printing and vision verification modules. Equipment vendors are reconfiguring standard platforms to accept serialization hardware without compromising sealing cycle times. German medical device exporters face the tightest compliance deadlines, driving concentrated procurement of integrated sealing-printing systems.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts. Mid-size pharmaceutical packagers in India and Southeast Asia are purchasing base hardware through digital marketplaces while sourcing technical support from regional third-party providers. This purchasing pattern compresses OEM service revenue per installation but accelerates equipment placement velocity in price-sensitive markets.
Tamper Evident Bag Sealers Market Segmentation
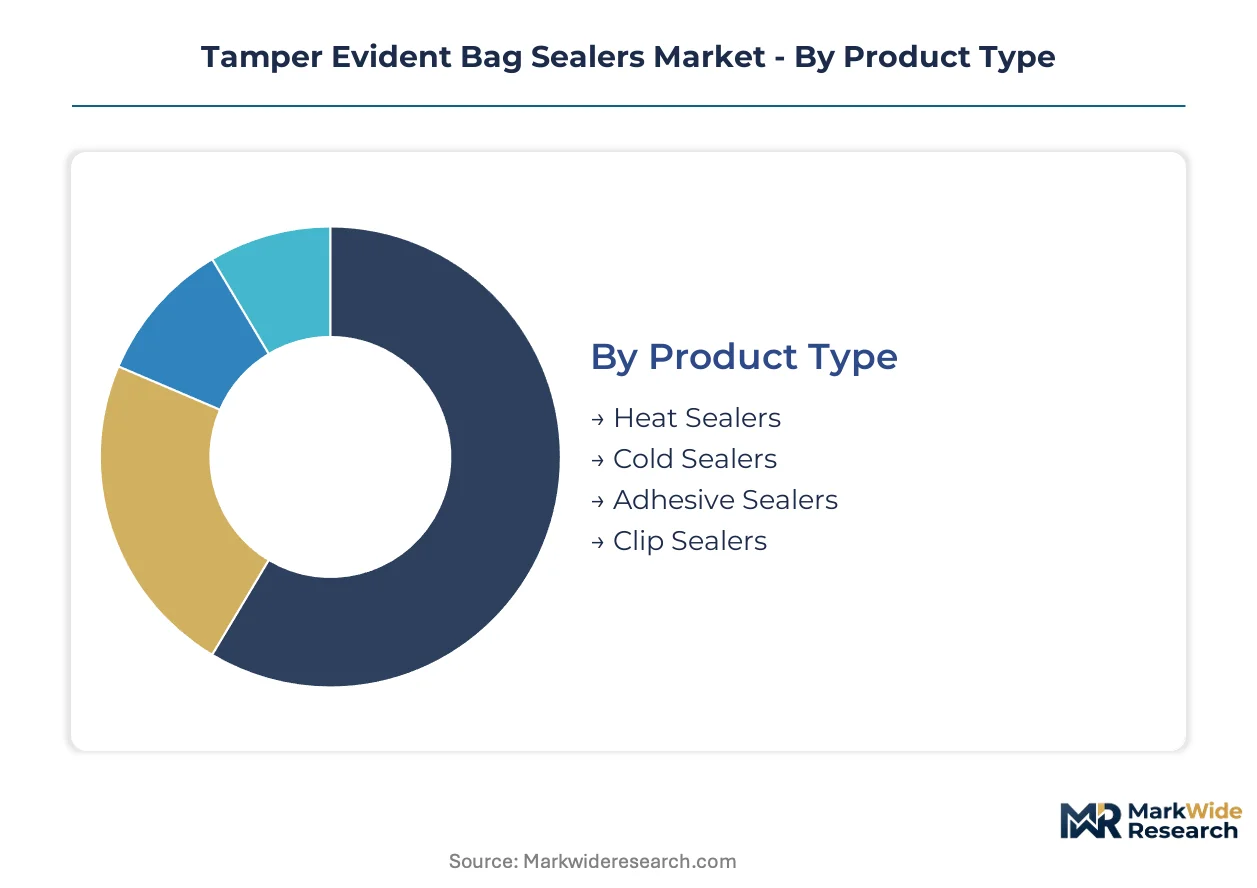
Segmentation in tamper evident bag sealers reveals how equipment specifications diverge across regulatory environments and material science requirements. Each dimension—product mechanism, end-use compliance burden, substrate compatibility, and seal geometry—creates distinct procurement criteria and vendor specialization zones.
Product Type:
Use-case spectrum spans from hermetic barrier requirements in pharmaceutical cold chains to cost-sensitive industrial bulk handling.
- Heat Sealers:Electromechanical systems operating between 120°C and 200°C generate irreversible fusion bonds in polyethylene and polypropylene substrates. Pharmaceutical contract packagers in Germany specify these for cryogenic-compatible gene therapy shipments under EU MDR traceability mandates.
- Cold Sealers:Pressure-activated adhesive systems eliminate thermal stress on temperature-sensitive contents. Cosmetics manufacturers in Southeast Asia favor these for volatile fragrance compounds where heat exposure degrades product integrity.
- Adhesive Sealers:Tape-based closure mechanisms suit forensic evidence handling and electronics packaging where reseal detection matters more than hermetic barriers.
- Clip Sealers:Mechanical crimping devices dominate industrial supply chains where cost-per-seal metrics override barrier performance requirements.
The dominant share belongs to Heat Sealers, while Cold Sealers are closing the gap fastest.
End User:
Compliance intensity tiers separate regulated pharmaceutical serialization from discretionary cosmetic branding investments.
- Food Industry:Modified atmosphere packaging and extended shelf-life applications drive heat-sealer procurement with HACCP-aligned documentation. FDA food safety modernization rules compel upgrade cycles among US-based protein processors.
- Pharmaceutical Industry:Cold-chain biologics and mRNA vaccine distribution mandate validated sealing with audit-trail documentation. German exporters face the tightest EU MDR serialization deadlines, concentrating demand for CE-marked equipment with integrated vision systems.
- Cosmetics Industry:Premium brand protection and anti-counterfeiting measures sustain adhesive-sealer demand across European luxury packaging lines.
- Electronics Sector:Static-dissipative sealing requirements and moisture sensitivity specifications favor precision-controlled heat sealers for semiconductor component packaging.
Pharmaceutical Industry commands the largest equipment spend, though Electronics Sector procurement is expanding most quickly.
Material:
Substrate selection dictates temperature windows, seal strength parameters, and compatibility with automated handling systems.
- Polyethylene:Low-density and linear-low variants dominate food and pharmaceutical primary packaging for their heat-seal responsiveness and moisture barrier properties. Indian contract manufacturers in Hyderabad specify medical-grade PE for CDSCO-compliant export shipments.
- Polypropylene:Higher melting points and clarity suit medical device trays and sterile barrier systems requiring autoclave compatibility. German medical device exporters favor cast PP for EU MDR UDI labeling integration.
- Nylon:Oxygen barrier performance sustains niche demand in vacuum-packaged protein and pharmaceutical applications.
- Polyester:Dimensional stability and printability drive selection for cosmetic and electronics packaging requiring premium surface aesthetics.
Polyethylene retains the dominant position, with Polypropylene gaining share fastest on medical device packaging growth.
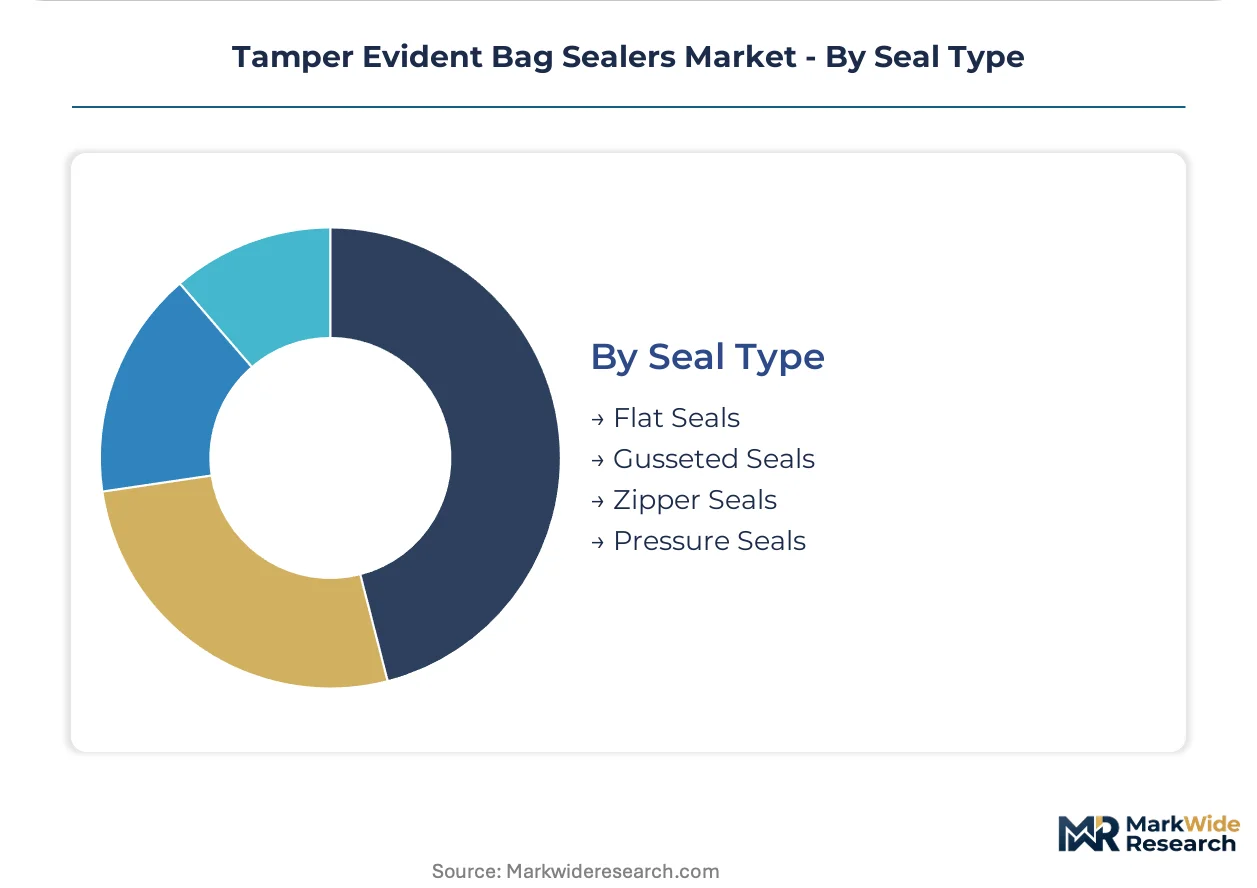
Seal Type:
Geometry specifications determine throughput speeds, filling efficiencies, and tamper-evidence visibility.
- Flat Seals:Simple transverse sealing bars maximize line speed for high-volume food and industrial applications where pouch geometry remains uniform.
- Gusseted Seals:Side-fold constructions expand volumetric capacity for bulk pharmaceutical powders and irregular electronics components. Swiss packaging engineers specify these for automated bagging lines serving multi-national drug distributors.
- Zipper Seals:Reclosable interlocking profiles add consumer convenience and multi-dose compliance in cosmetic and over-the-counter pharmaceutical segments.
- Pressure Seals:Adhesive-based closure systems serve evidence-handling and courier applications where mechanical integrity must survive environmental stress without thermal processing.
Flat Seals hold the dominant share, while Gusseted Seals are climbing fastest on pharmaceutical powder packaging expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export compliance mandates and pharmaceutical serialization requirements are redistributing equipment procurement across manufacturing clusters with varying regulatory maturity. Cold-chain logistics expansion and medical device traceability deadlines are concentrating demand in jurisdictions with advanced pharmaceutical infrastructure.
United States
FDA 21 CFR Part 11 electronic records requirements are accelerating replacement cycles among contract packagers serving domestic drug distribution. The EPA and OSHA frameworks additionally shape thermal sealing equipment specifications through emissions and workplace safety standards. Greater Boston and the Research Triangle host concentrated pharmaceutical manufacturing bases where validated sealing systems with audit-trail documentation dominate procurement specifications.
Germany
EU MDR serialization deadlines and medical device export compliance are driving CE-marked equipment procurement with integrated vision verification modules. The country's notified body relationships and technical validation expertise create procurement advantages for established European vendors. Baden-Württemberg and Bavaria concentrate medical device packaging operations where UDI labeling integration requirements tighten equipment specifications.
India
CDSCO export compliance requirements and PLI scheme incentives are expanding pharmaceutical contract manufacturing capacity in Hyderabad and Ahmedabad clusters. Domestic equipment vendors compete with multinational suppliers on price-sensitive procurement from mid-size packagers. The Telangana and Gujarat pharmaceutical corridors are upgrading from legacy heat-sealers to validated systems as export certification standards tighten.
Switzerland
Swissmedic pharmaceutical manufacturing standards and precision engineering heritage sustain demand for high-validity sealing equipment with temperature profiling capabilities. The country's validation engineering talent concentration supports complex equipment qualification protocols. Basel and Zurich pharmaceutical manufacturing zones specify precision heat-sealers for biologics and gene therapy cold-chain applications.
China
NMPA pharmaceutical packaging standards and domestic biologics manufacturing expansion are driving equipment procurement in Yangtze River Delta pharmaceutical clusters. Local vendors compete on cost while multinational suppliers capture premium validated system segments. Shanghai and Suzhou pharmaceutical manufacturing bases are upgrading sealing infrastructure to meet export market compliance requirements.
Tamper Evident Bag Sealers Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers differentiated by validation documentation depth and geographic service density. European and North American vendors concentrate pharmaceutical-grade systems with ISO 15378 certification and CE marking, while Asian fabricators compete on cost-efficient platforms for industrial and food applications. Strategic archetypes include validation-focused pharmaceutical specialists, multi-material platform generalists, and regional cost-optimized fabricators. Competitive dynamics center on geographic expansion through distributor partnerships and portfolio diversification into adjacent sealing technologies.
Within the pharmaceutical-specialist tier, Innoseal Systems and Tamper Technologies exemplify equipment vendors with regulatory-centric positioning. PAC Machinery anchors the North American service-network archetype with aftermarket revenue streams from installed heat-sealer bases. These named entities represent distinct strategic postures rather than exhaustive market coverage, with each occupying differentiated positions across compliance intensity segments and geographic service requirements.
| Leading Market Players |
|---|
| Innoseal Systems |
| Tamper Technologies |
| PAC Machinery |
| Quick Pak |
| Adsure Packaging |
| Butler Staple |
| Packaging Aids |
| Joke Folienschweitechnik |
| Multiko Packaging |
| Others |
Value Network & Pricing Analysis
Commodity metal volatility in stainless steel and copper heating elements compresses OEM margin structures while simultaneously widening the spread between validated pharmaceutical-grade systems and standard industrial platforms. This input-cost instability forces buyers into longer-term contract commitments for ISO 15378-certified equipment, reshaping procurement patterns across both pricing tiers and supply chain configurations.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with FDA-validated and CE-marked systems commanding substantial premiums over uncertified industrial alternatives. Pricing stratifies across three performance tiers: pharmaceutical-grade validated systems with audit-trail documentation, mid-tier food-industry platforms with HACCP alignment, and economy-grade industrial sealers for bulk supply chains. Cost compression in the mid-tier is intensifying because regional Asian fabricators are undercutting established European vendors on base hardware. Mid-size pharmaceutical contract packagers in India exhibit the highest price sensitivity, while German medical device exporters prioritize compliance documentation over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for heating element and control module sourcing. Equipment fabrication concentrates in Germany, Switzerland, and China, with precision engineering components drawing from Swiss and German supplier bases while commodity chassis and standard electronics feed from Chinese manufacturing clusters. Raw material dependencies center on stainless steel for corrosion-resistant sealing surfaces, copper for heating elements, and specialized thermoplastics for temperature-resistant housings. Single-source vulnerability persists for ISO 15378-certified validation documentation services, which concentrate among aging specialist workforces in Germany and Switzerland. Distribution runs through a hybrid model combining direct OEM relationships with large pharmaceutical packagers, regional equipment dealers serving mid-tier buyers, and emerging digital procurement platforms capturing price-sensitive Southeast Asian demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity anchored in regulatory entrenchment. FDA 21 CFR Part 11 and EU MDR documentation requirements create switching costs that protect incumbent positions while constraining new entrant scale.
For Market Incumbents: Harden regulatory documentation capabilities as the primary defensive perimeter against emerging Asian cost competitors. Invest in validation engineering talent retention programs in Germany and Switzerland, where specialist expertise concentrates among aging workforces. Deepen backward integration into heating element manufacturing to offset stainless steel and copper input volatility, securing margin control against commodity price swings. For New Entrants and Emerging Players: Pursue digital procurement platform partnerships as the fastest vector into mid-tier pharmaceutical and cosmetics packagers in Southeast Asia. Target India's Hyderabad and Ahmedabad contract manufacturing clusters, where CDSCO export compliance requirements are tightening equipment standards and creating replacement demand. Position around after-sales service unbundling, offering base hardware through online marketplaces while sourcing regional technical support from third-party providers. For Investors and Strategic Acquirers: EU MDR serialization deadlines reshape the acquisition landscape by compressing equipment vendor timelines and advantaging established players with notified body relationships. Frame long-term viability around the 5-10 year regulatory compliance cycle, where pharmaceutical serialization mandates sustain recurring upgrade demand. Target acquisition candidates with concentrated CE-marked equipment portfolios and existing technical validation partnerships in Germany. Monitor CDSCO enforcement intensity in India as the signal to watch for emerging market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Investment | FDA 21 CFR Part 11 compliance creates audit-ready equipment differentiation against uncertified competitors. |
| Regional Service Network Expansion | Localized technical support in India and Southeast Asia captures mid-tier pharmaceutical procurement shifting to digital channels. |
| Heating Element Backward Integration | In-house production of copper and stainless steel components insulates margins from commodity metal volatility. |
| Blockchain Audit Trail Integration | IoT-enabled sealing equipment with distributed ledger verification digitizes chain-of-custody for forensic applications. |
| CE Marking Fast-Track Partnership | Notified body relationships compress EU MDR equipment approval timelines against smaller OEM competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical contract packaging executives, equipment procurement managers at medical device manufacturers, validation engineering specialists, and aftermarket service heads at regional dealer networks. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU MDR conformity assessment procedures, CDSCO export compliance circulars, ISO 15378 certification registries, and customs trade data for equipment import flows. Bottom-up segmentation modeling triangulated against top-down market sizing from identified vendor revenue disclosures.
Calibration against historical replacement cycles and regulatory deadline impacts anchored the projection framework across the analysis window. Segmentation dimensions included sealing mechanism type, end-use compliance intensity, substrate material compatibility, and seal geometry specifications alongside regional regulatory cluster differentiation. CAGRs were derived from equipment procurement velocity tied to pharmaceutical serialization mandate timelines and cold-chain biologics expansion trajectories. Forecast inputs incorporated validation engineering talent availability constraints and commodity metal price trend assumptions.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical capital expenditure cycles, biologics manufacturing investment flows, or stainless steel supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and equipment replacement elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Padding Bags Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Packaging Peanuts Market