
 Case Closures and Sealers Market | 2026-2036
Case Closures and Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Case Closures and Sealers Market Outlook
The EU Packaging and Packaging Waste Regulation is decoupling virgin plastic dependency from closure manufacturing, compelling converters toward mono-material and bio-based designs. Berry Global Inc. leverages its European thermoforming footprint to supply pharmaceutical-grade child-resistant closures compliant with EN ISO 8317. Amcor PLC anchors global flexible-lid capacity while navigating divergent FDA and EMA migration limits. Silgan Holdings Inc. dominates metal closure supply to European beverage bottlers through its Spanish and German manufacturing sites.
Case closures and sealers are mechanical or adhesive devices engineered to 0.1–0.3 mm dimensional tolerances, formed through injection molding, compression molding, or extrusion lamination, designed to preserve product integrity against oxygen ingress, moisture transmission, and microbial contamination. Caps and seals lead volume due to universal food and beverage applicability, though adhesive tapes represent the fastest-expanding segment driven by e-commerce protective packaging requirements. Plastic retains dominant material share for cost scalability, while composite constructions capture premium margin pools in pharmaceutical cold-chain applications where multi-layer barrier performance commands price premiums over standard polyethylene or polypropylene alternatives.
FDA 21 CFR Part 211, EMA Annex 1 sterile manufacturing guidelines, and EU REACH substance restrictions collectively elevate closure validation burdens, forcing suppliers to maintain extractables and leachables documentation across jurisdictions. Germany's national packaging registry LUCID and France's AGEC anti-waste law extend producer responsibility to closure components, reshaping material selection criteria. Stakeholders must monitor evolving extended producer responsibility fee structures and migration testing protocols to anticipate compliance cost trajectories.
Market Dynamics
EU MDR traceability mandates and child-resistant closure requirements are compressing supplier qualification timelines while elevating extractables documentation burdens across pharmaceutical packaging procurement.
Growth Catalysts
- EU MDR serialization mandates:Pharmaceutical manufacturers must integrate tamper-evident closures with 2D data matrix codes by 2027, expanding demand for validated sealing systems.
- Child-resistant packaging regulations:EN ISO 8317 compliance requirements in Germany and France are driving replacement cycles for standard caps in OTC drug segments.
- Mono-material design pivot:EU Packaging and Packaging Waste Regulation incentives are accelerating polypropylene closure adoption over multi-layer alternatives in beverage applications.
Market Restraints
- Aluminum sheet volatility:Metal closure margins compress when London Metal Exchange aluminum prices spike, forcing Spanish and German manufacturers to absorb cost or lose bottler contracts.
- Migration testing fragmentation:Divergent FDA 21 CFR Part 211 and EMA Annex 1 extractables protocols force dual validation tracks, extending time-to-market for global closure suppliers.
- Biopolymer performance gaps:Bio-based polyhydroxyalkanoates exhibit inferior oxygen barrier properties versus conventional polyethylene, limiting cold-chain pharmaceutical adoption.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO-aligned facilities in Hyderabad and Ahmedabad are investing in EU-compliant closure lines to serve European generic drug distributors.
- E-commerce protective packaging:Adhesive tape demand from automated fulfillment centers is outpacing traditional corrugated box sealing in German logistics corridors.
- Smart closure integration:NFC-enabled temperature logging caps are converging with blockchain traceability platforms in high-value biologics distribution.
Industry Challenges
- Extractables chemist scarcity:Specialized analytical talent capable of running USP 1664 migration studies commands premium salaries, constraining mid-tier closure validation capacity.
- Legacy injection mold retrofit costs:Converting steel tooling for thinner-wall mono-material designs requires capital outlays that strain family-owned converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Closures and Sealers Market |
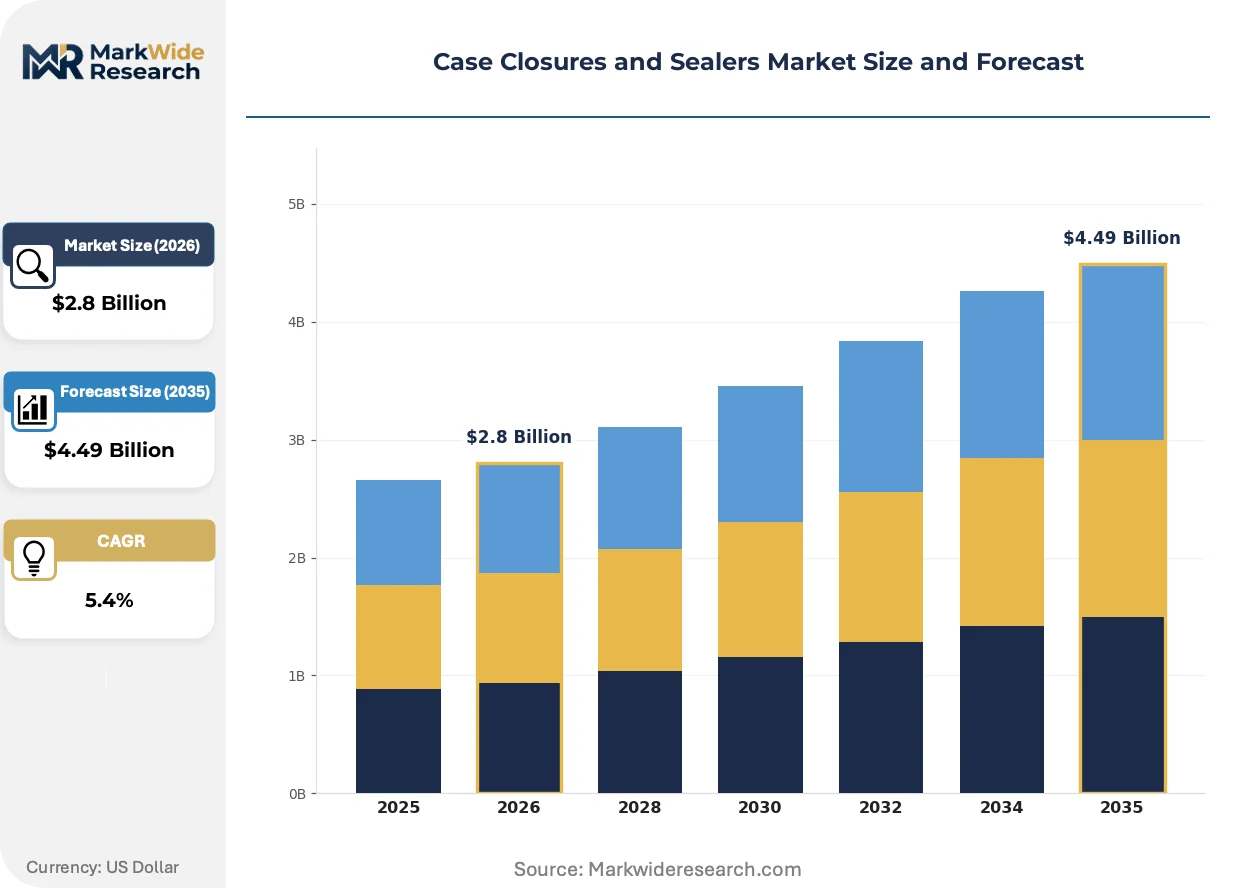
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Corks, Seals, Adhesive Tapes Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Application: Packaging, Protection, Transportation, Storage |
| Companies Covered | Berry Global Inc., Amcor PLC, AptarGroup Inc., Silgan Holdings Inc., Closure Systems International, Sonoco Products Company, 3M Company, Huhtamaki Group, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Closures and Sealers Market Strategic Shifts
Closure manufacturing is pivoting toward validated mono-material architectures as regulatory migration limits tighten and pharmaceutical traceability requirements deepen technical specifications across supply chains.
Digital printing integration is consolidating direct-to-closure serialization as the dominant anti-counterfeiting technology. Contract packaging organizations in Switzerland and Germany are adopting UV-cured inkjet systems that embed unique identifiers without secondary labeling operations. This capability is compressing equipment amortization timelines for converters serving high-value biologics markets.
REACH substance restrictions are forcing reformulation of plasticizer packages in polyvinyl chloride seals. ECHA's 2023 update to candidate list obligations has triggered supplier audits across French and Italian cosmetic closure networks. Pharmaceutical-grade thermoplastic elastomer alternatives are capturing specification share in parenteral vial applications where leachable profiles must meet tightened analytical thresholds.
Consolidated procurement by pan-European beverage bottlers is compressing supplier rosters and extending contract durations. Multinational soft drink manufacturers in Germany and Spain now mandate three-year framework agreements with volume guarantees, displacing spot-market purchasing. This concentration is elevating technical service capabilities as a competitive differentiator among closure converters competing for retained supply positions.
Case Closures and Sealers Market Segmentation
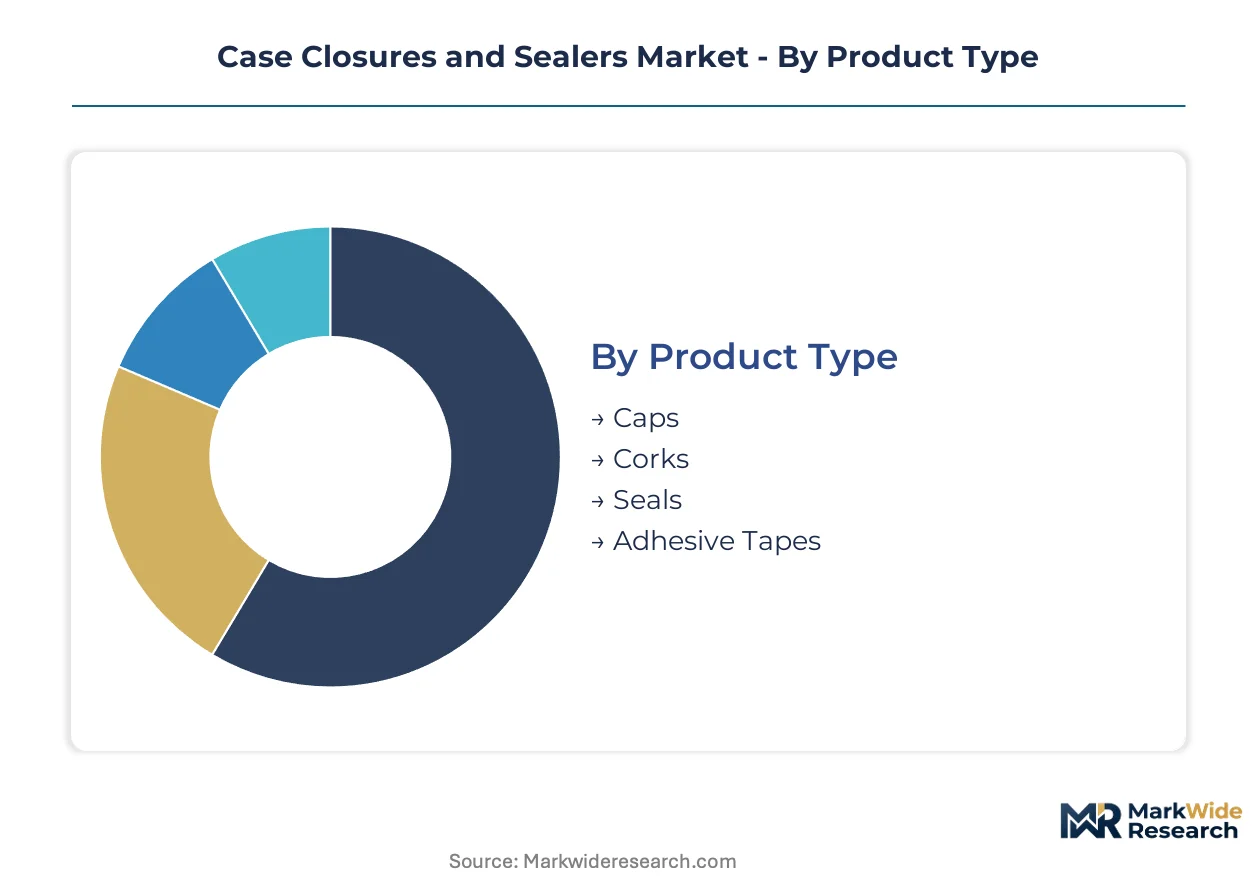
Segmentation in case closures and sealers reveals divergent technical requirements across pharmaceutical validation, beverage cost engineering, and e-commerce protective applications. Material selection and closure architecture determine regulatory compliance pathways and manufacturing investment intensity for converters serving these distinct demand pools.
Product Type:
Standalone closure systems dominate high-volume beverage and pharmaceutical packaging, while embedded sealing elements integrate into multi-component protective solutions for logistics and cold-chain distribution.
- Caps:Threaded thermoplastic or metal closures engineered to 0.1–0.3 mm dimensional tolerances through injection or compression molding. Demand concentrates in German beverage bottling corridors where mono-material polypropylene designs are displacing multi-layer constructions under EU Packaging and Packaging Waste Regulation incentives.
- Adhesive Tapes:Pressure-sensitive films and water-activated reinforced tapes formed through extrusion lamination and hot-melt coating. German automated fulfillment centers in Leipzig and Duisburg are driving specification shifts toward high-tack acrylic formulations that secure corrugated integrity through multi-modal e-commerce distribution.
- Corks:Natural and agglomerated bark closures with cellular structure providing elastic recovery for wine and spirits sealing.
- Seals:Induction-heatable foil laminates and tamper-evident bands applied as secondary integrity barriers across pharmaceutical and food containers.
Caps lead volumes today; adhesive tapes are gaining share fastest.
Material:
Cost tier structures separate commodity-scale thermoplastics from premium multi-layer barrier constructions commanding validation documentation premiums in regulated end-uses.
- Plastic:Polyethylene, polypropylene, and thermoplastic elastomer formulations processed through injection molding for cost-scalable closure production. French and Italian cosmetic brands are accelerating polypropylene adoption to align with AGEC anti-waste law mono-material recyclability mandates.
- Composite:Multi-layer coextrusions combining oxygen barrier polymers with structural substrates for cold-chain pharmaceutical applications. Swiss biologics distributors specify these constructions where EMA Annex 1 migration limits demand documented leachable profiles exceeding standard polyethylene performance.
- Metal:Aluminum and tinplate sheet formed through deep drawing and thread rolling for beverage and industrial closures.
- Glass:Ground and polished borosilicate or soda-lime closures for high-purity chemical and pharmaceutical containment.
Plastic dominates tonnage across applications; composite constructions capture the steepest margin expansion in validated pharmaceutical segments.
End User:
Customer type segmentation separates specification-intensive regulated industries from price-sensitive consumer goods procurement with shorter qualification cycles.
- Pharmaceuticals:Sterile and non-sterile drug packaging requiring child-resistant mechanisms, tamper-evident features, and extractables documentation. German generic manufacturers in Bavaria and North Rhine-Westphalia are retrofitting lines for EU MDR-compliant closures with integrated 2D data matrix serialization.
- Food & Beverage:Carbonated soft drink, bottled water, and alcoholic beverage sealing with oxygen ingress and carbonation retention specifications. Spanish citrus juice bottlers in Valencia are consolidating supplier rosters around three-year framework agreements with volume guarantees.
- Cosmetics:Fragrance, skincare, and personal care closures emphasizing aesthetic differentiation and dispenser functionality.
- Household Products:Cleaning chemical and automotive fluid containers requiring chemical compatibility and child-resistant compliance for caustic formulations.
Food and beverage generates the highest closure volumes; pharmaceuticals is expanding most quickly on regulatory retrofit demand.
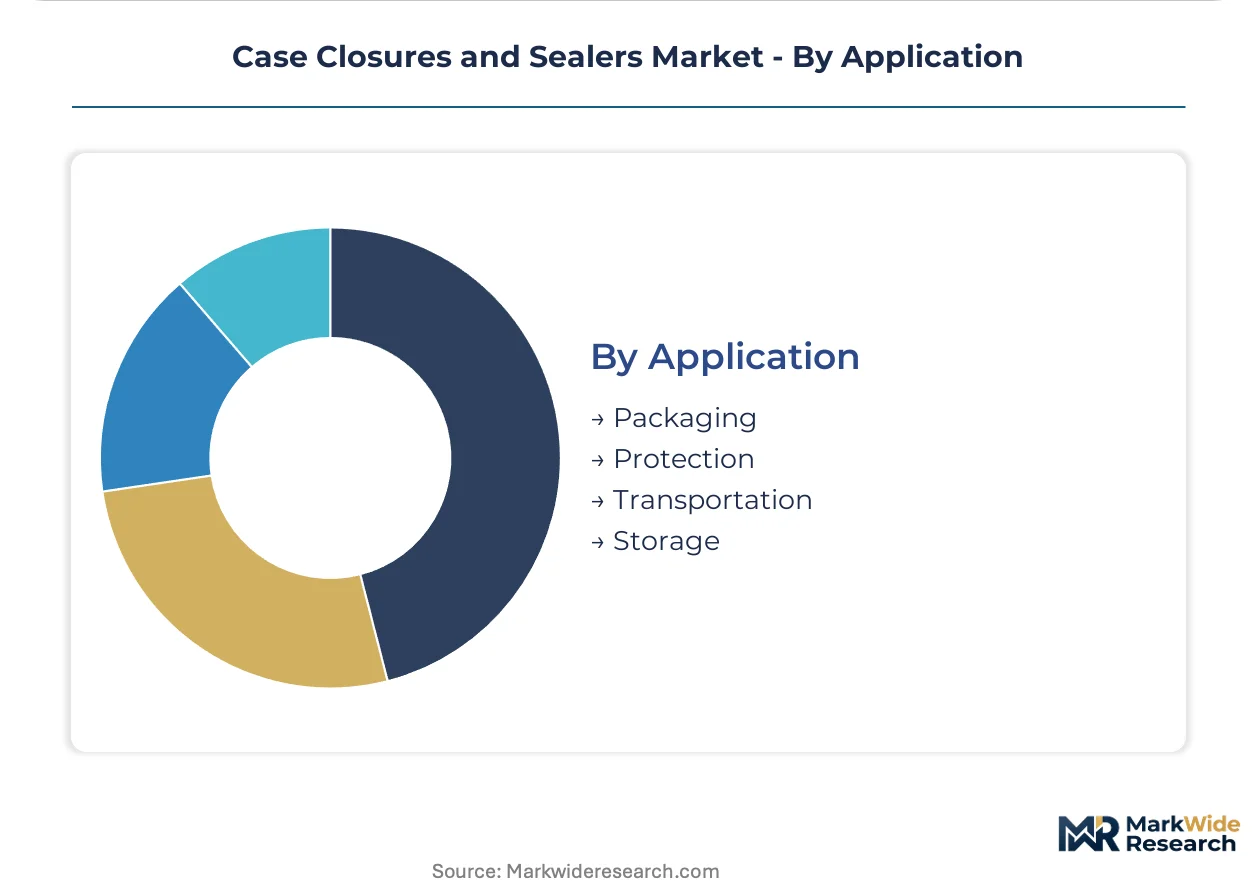
Application:
Volume concentration varies across primary packaging integration, secondary protective functions, and logistics infrastructure sealing requirements.
- Packaging:Primary container closure for product containment, preservation, and dispensing. German pharmaceutical contract packaging organizations in Baden-Württemberg are adopting UV-cured inkjet serialization systems that embed anti-counterfeiting identifiers directly onto closure surfaces.
- Protection:Moisture, oxygen, and microbial barrier sealing for shelf-life extension. French cosmetic distribution networks specify these systems where REACH substance restrictions have triggered reformulation of legacy plasticizer packages in polyvinyl chloride seals.
- Transportation:Load unitization and transit damage prevention through stretch film, strapping, and adhesive tape systems.
- Storage:Long-term warehouse containment and environmental protection for bulk and finished goods inventory.
Packaging commands the largest share of closure demand; protection applications are climbing the fastest on cold-chain pharmaceutical expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tooling engineers and polymer chemists concentrate in German industrial clusters, anchoring European closure innovation capacity. Swiss precision manufacturing expertise and Indian pharmaceutical formulation talent are reshaping supply chain geography.
Germany
Pharmaceutical contract packaging organizations in Baden-Württemberg drive demand for EU MDR-compliant closures with integrated serialization. LUCID packaging registry obligations extend producer responsibility to closure components, elevating documentation burdens. Bavarian generic manufacturers retrofit lines for child-resistant mechanisms serving export markets.
Switzerland
Biologics distributors specify composite multi-layer constructions where EMA Annex 1 migration limits demand validated leachable profiles. Swissmedic oversight of sterile manufacturing elevates extractables documentation requirements. Basel-area contract packaging organizations adopt UV-cured inkjet serialization systems embedding anti-counterfeiting identifiers directly onto closure surfaces.
India
CDSCO-aligned facilities in Hyderabad and Ahmedabad invest in EU-compliant closure lines serving European generic drug distributors. Pharmaceutical export growth from Indian formulation hubs accelerates specification alignment with EMA traceability mandates. Domestic biopolymer research programs address oxygen barrier performance gaps limiting cold-chain adoption.
Spain
Citrus juice bottlers in Valencia consolidate supplier rosters around three-year framework agreements with volume guarantees. Metal closure manufacturers absorb aluminum sheet volatility from London Metal Exchange price spikes to retain bottler contracts. Catalan cosmetic brands accelerate polypropylene adoption aligning with EU Packaging and Packaging Waste Regulation recyclability incentives.
France
AGEC anti-waste law mandates extend producer responsibility to closure components, triggering supplier audits across cosmetic closure networks. ECHA REACH substance restrictions force reformulation of plasticizer packages in polyvinyl chloride seals. Paris-region fragrance houses specify thermoplastic elastomer alternatives meeting tightened analytical thresholds for parenteral applications.
Case Closures and Sealers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent investment profiles. Integrated resin-to-closure manufacturers command cost advantages in beverage volume segments while specialized pharmaceutical converters capture margin premiums through validation documentation services. The market structures around three archetypes: multinational diversified packaging conglomerates, regional closure specialists, and materials-science-focused innovators. Consolidation activity concentrates in European beverage supply chains while technology licensing agreements proliferate in pharmaceutical-grade barrier systems.
Among diversified packaging conglomerates, Berry Global Inc. and Amcor PLC exemplify scale-driven positions spanning multiple material platforms and end-use segments. Silgan Holdings Inc. occupies a specialized position within metal closure supply. These three entities represent distinct strategic postures: resin integration breadth, global flexible-lid capacity, and regional manufacturing density respectively.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor PLC |
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Closure Systems International |
| Sonoco Products Company |
| 3M Company |
| Huhtamaki Group |
| Alcoa Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates gate qualified supply for pharmaceutical-grade closures while reserving premium-tier pricing access to converters with validated mono-material documentation and extractables testing capabilities. German beverage bottlers now bundle three-year framework agreements with technical service retainers, compressing spot-market participation and elevating contract-based pricing power for integrated resin-to-closure manufacturers.
Pricing Analysis
Bundled validation services versus unbundled component supply splits pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels separates EMA Annex 1-compliant pharmaceutical closures with full extractables documentation from commodity beverage caps and generic industrial seals. Price differentiation rests on certification grade and volume scale, with German generic manufacturers absorbing 15-20% premiums for EU MDR serialization-ready systems. Cost compression in standard-tier polypropylene closures is intensifying because Spanish and Italian converters are retrofitting legacy injection molds for thinner-wall mono-material designs. Food and beverage procurement teams exhibit highest price sensitivity, while Swiss biologics distributors prioritize barrier performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from pan-European beverage bottlers mandate multi-supplier qualification across German, Spanish, and French manufacturing sites, preventing single-source concentration despite consolidation trends. Raw material dependencies center on polypropylene resin from Belgian and Dutch petrochemical complexes, aluminum sheet from German and Austrian rolling mills, and specialty thermoplastic elastomers from Swiss polymer compounders. Supply chain risk from London Metal Exchange aluminum price volatility forces Spanish metal closure manufacturers to absorb margin compression or sacrifice bottler contracts. Distribution runs through converter-direct relationships with beverage bottlers and pharmaceutical contract packaging organizations, supplemented by specialized distribution networks serving cosmetic and household product segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical validation services and mono-material design premiums, justified by the cost-down trajectory of polypropylene resin integration and the premium-tier shift toward EMA Annex 1-compliant barrier systems.
For Market Incumbents: Lock in retained supply positions with German beverage bottlers through dedicated technical service teams and three-year volume guarantees that preempt spot-market competitors. Retrofit Spanish and German injection molding capacity for thinner-wall mono-material designs to capture EU Packaging and Packaging Waste Regulation compliance premiums before mid-tier converters complete capital programs.
For New Entrants and Emerging Players: NFC-enabled temperature logging caps offer a technology-first wedge into Swiss biologics distribution networks where blockchain traceability integration commands specification share. Target Indian pharmaceutical export corridors in Hyderabad and Ahmedabad where CDSCO-aligned facilities are investing in EU-compliant closure lines without incumbent supplier relationships. Lead with validation documentation services rather than component pricing to bypass capital-intensive molding investments.
For Investors and Strategic Acquirers: Roll-up economics work for specialized pharmaceutical closure converters because extractables chemist scarcity and dual validation track requirements create durable moats against commodity competitors. Five-to-ten year viability hinges on consolidation of European beverage supply chains around technical service capabilities rather than resin cost alone. Watch for aluminum price volatility spikes as inflection indicators that accelerate converter exits and create acquisition entry points.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Design Pivot | Captures EU Packaging and Packaging Waste Regulation compliance premiums in German beverage bottling corridors. |
| Backward Integration into Polypropylene Resin | Secures cost scalability against commodity price volatility for high-volume closure production. |
| Extractables Documentation Services | Differentiates pharmaceutical converters under divergent FDA and EMA migration testing protocols. |
| Smart Closure Integration | Converges NFC-enabled temperature logging with blockchain traceability for Swiss biologics distributors. |
| Indian Pharmaceutical Export Alignment | Positions EU-compliant closure lines to serve European generic drug distributors from Hyderabad and Ahmedabad. |
Study Parameters
Multiple input streams — primary interviews with pharmaceutical packaging procurement managers, beverage bottler supply chain directors, and polymer chemists at specialized compounders; secondary validation through EMA Annex 1 guidance documents, EU MDR implementation timelines, and LUCID packaging registry filings; plus customs data on aluminum sheet and polypropylene resin trade flows — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Cross-referencing historical closure shipment patterns against panel input from German contract packaging organizations and Spanish citrus juice bottlers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material platform, end-user industry, and application function, with CAGRs derived from regression analysis of regulatory retrofit cycles and mono-material adoption curves. Industry-specific forecast inputs incorporated EU MDR serialization mandate compliance timelines and child-resistant packaging replacement cycles in German and French OTC drug segments.
The model holds under stable regulatory implementation schedules and aluminum price corridors; deviation in REACH substance restriction timelines or London Metal Exchange volatility spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Sterile Lids Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Japan Plastic Caps and Closures Market