
 Taiwan Data Center Server Market | 2026-2036
Taiwan Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Server Market Insights
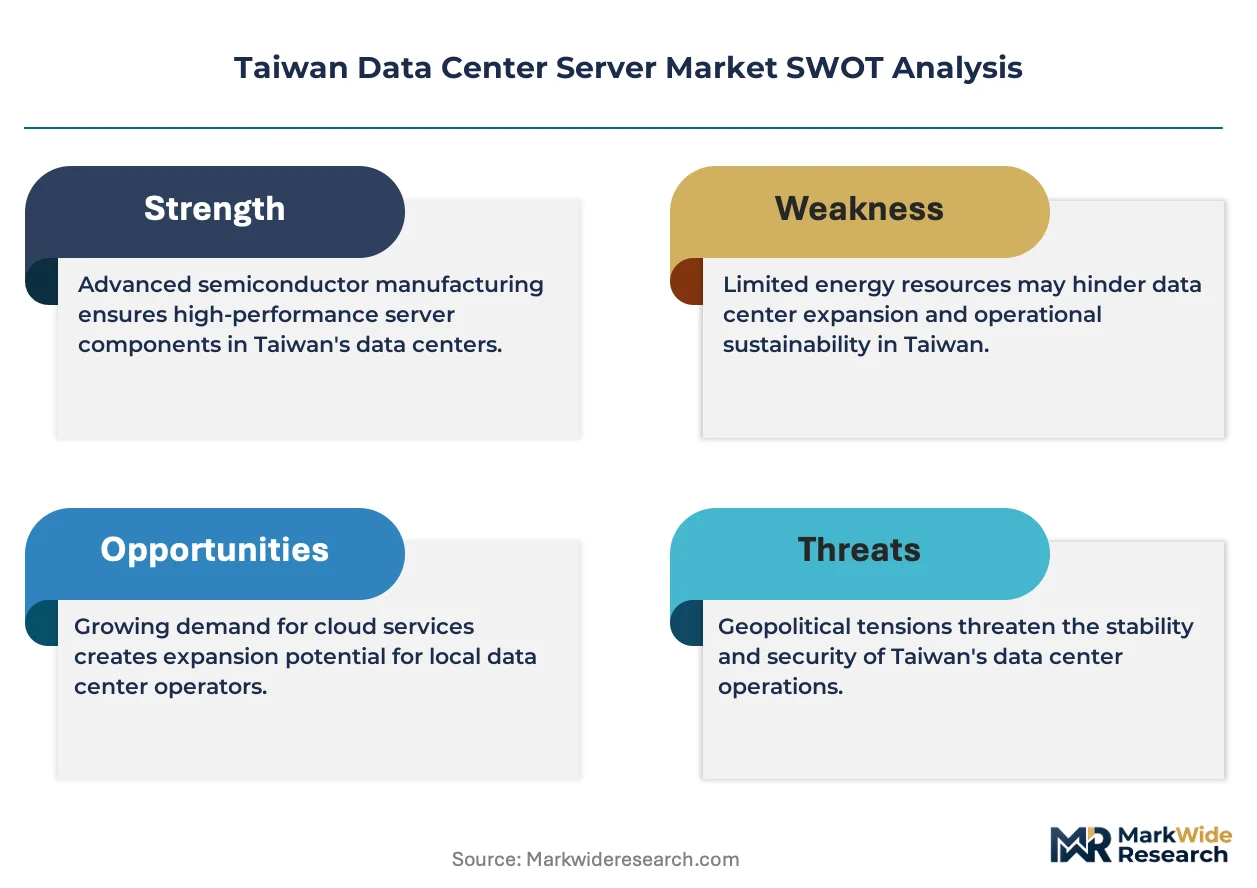
Taiwan's renewable energy procurement framework under the Ministry of Economic Affairs is rebalancing data center development priorities toward lower-carbon power sourcing. Quanta Cloud Technology leverages its ODM heritage to dominate custom server builds for hyperscale clients. Wiwynn sustains manufacturing scale through captive facilities in Taoyuan. Super Micro Computer differentiates via liquid-cooled architectures for high-density AI workloads.
Taiwan data center servers are enterprise-grade compute platforms engineered around x86 and ARM processor architectures, typically deployed in 42U to 52U rack configurations with redundant power supplies and hot-swappable components, designed to process, store, and distribute digital workloads for cloud, enterprise, and telecommunications operators. Rack servers occupy the core volume position due to their flexibility across colocation and hyperscale environments. Hyper-converged systems are capturing accelerated interest as technology firms consolidate storage, compute, and virtualization into unified footprints. Blade servers retain niche traction among financial services operators prioritizing density and cable reduction.
National Communications Commission standards govern telecommunications facility certifications, while Bureau of Energy efficiency mandates shape power usage effectiveness thresholds for new builds. The Ministry of Economic Affairs administers renewable energy procurement rules that directly influence site selection and long-term operating cost structures. Stakeholders must weigh the trade-off between Taoyuan's established fiber and power infrastructure against emerging southern cluster locations where land and green energy access are expanding.
Market Dynamics
Renewable energy procurement rules administered by Taiwan's Ministry of Economic Affairs are restructuring data center site selection and power contracting strategies across the island, forcing operators to secure green energy certificates before facility commissioning.
Growth Catalysts
- Cloud capacity expansion:Hyperscale providers are scaling compute footprints in Taipei and Taoyuan to serve regional AI inference demand. This is pulling rack server volumes upward across colocation facilities.
- Hyper-converged consolidation:Technology firms are replacing discrete storage arrays with unified compute-storage nodes. Bureau of Energy efficiency thresholds favor these denser configurations.
- Financial services densification:Banking operators prioritize blade architectures to reduce cabling complexity in trading floor deployments. National Communications Commission telecommunications certifications support low-latency co-location.
Market Restraints
- Land scarcity in northern clusters:Taoyuan's industrial zones face competing semiconductor fab demand. Data center developers encounter zoning delays and elevated lease rates.
- Power grid interconnection queues:Taiwan Power Corporation substation upgrades lag facility construction timelines. New builds face 18-24 month energization delays in saturated northern corridors.
- Liquid cooling retrofit complexity:Legacy air-cooled facilities require structural reinforcement for coolant distribution. High-density AI racks demand plumbing infrastructure absent in 2015-2019 vintage builds.
Strategic Opportunities
- Southern Taiwan greenfield development:Tainan and Kaohsiung offer land banks and offshore wind proximity. Ministry of Economic Affairs renewable energy rules favor these locations for long-term power purchase agreements.
- ARM architecture migration:Cloud operators are qualifying ARM-based servers for power-sensitive workloads. This diversifies supplier options beyond x86 dominance.
- Edge computing node deployment:Telecommunications operators are installing micro data centers at 5G base stations. National Communications Commission facility certifications govern these distributed installations.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design requires specialized fluid dynamics expertise. Local universities produce insufficient graduates in this intersection of mechanical and electrical engineering.
- Legacy virtualization stack integration:Financial services operators maintain VMware estates that resist container-native workload migration. Hyper-converged procurement stalls on software licensing renegotiation.
- Supply chain reconfiguration friction:Component sourcing from multiple ASEAN assembly locations complicates just-in-time inventory. Logistics coordination across the Taiwan Strait adds customs documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Server Market |
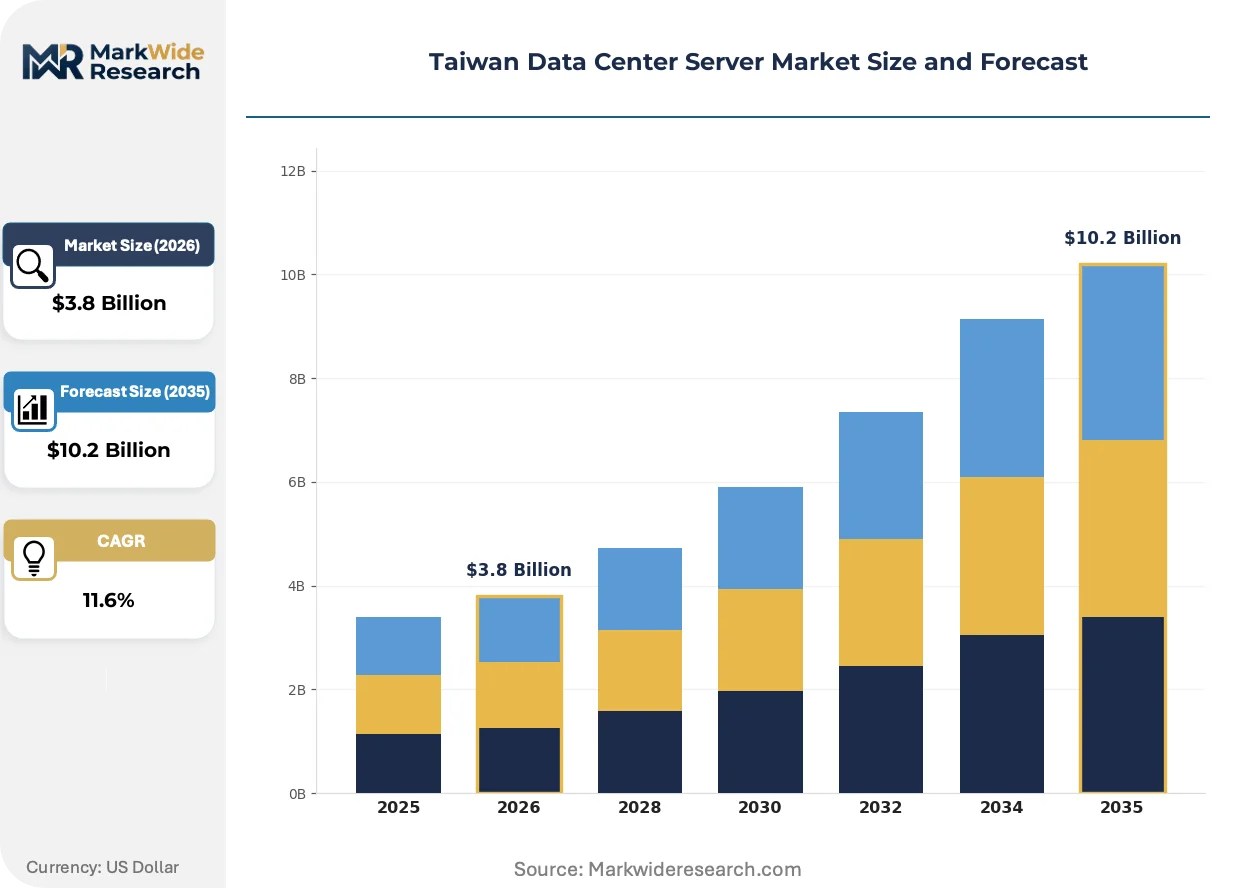
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Hyper-Converged Systems Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Telecommunications, Financial Services, Healthcare, Technology Firms Solution: Storage Solutions, Virtualization Software, Security Solutions, Networking Infrastructure |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Cisco Systems, Fujitsu, Kingston Technology Company, Nvidia Corporation, Super Micro Computer, Quanta Cloud Technology, Wiwynn, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Server Market Trends and Innovations
Intelligent infrastructure management systems are penetrating Taiwan data center operations, compressing manual oversight requirements while elevating thermal and power optimization precision.
Immersion cooling technology is automating heat removal from GPU-intensive AI training clusters. Cloud operators in Taoyuan are piloting dielectric fluid baths for 100kW+ rack densities. This architecture is automating the elimination of mechanical refrigeration, slashing power usage effectiveness ratios below industry averages.
Ministry of Economic Affairs renewable energy procurement mandates are compelling power purchase agreement restructuring. New facility approvals now require documented green energy sourcing percentages. Developers are responding by securing offshore wind allocations before construction financing closes.
Financial services procurement patterns are favoring outcome-based infrastructure contracts over capital acquisition. Technology firms are unbundling hardware ownership from operational management, paying per compute-hour instead. This shift is most visible among Taipei-based securities trading houses consolidating vendor relationships.
Taiwan Data Center Server Market Segmentation
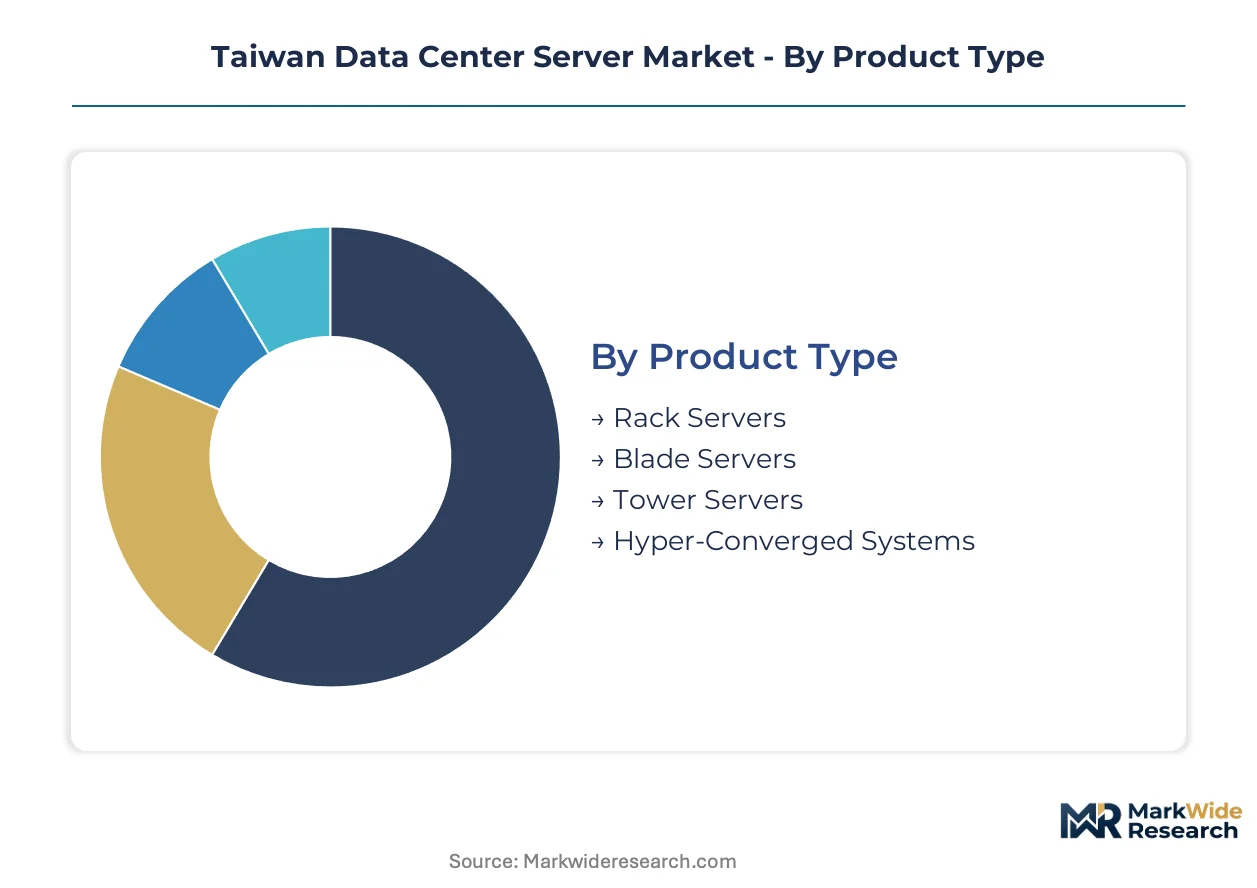
Taiwan's data center server market segments reflect divergent procurement priorities across hyperscale cloud operators, financial institutions, and telecommunications carriers. Each dimension captures distinct technical requirements, compliance obligations, and power density constraints that shape vendor selection and facility design decisions.
Product Type:
Supply concentration among Taiwan's ODM manufacturers favors rack and blade configurations, with custom builds dominating hyperscale procurement while standardized platforms serve enterprise colocation demand.
- Rack Servers:These 42U to 52U form factors accommodate x86 and ARM processor architectures with redundant hot-swappable power supplies. Cloud service providers in Taipei and Taoyuan are scaling rack deployments to serve regional AI inference workloads, pulling volumes upward across colocation facilities despite land scarcity constraints in northern industrial zones.
- Hyper-Converged Systems:Unified compute-storage nodes consolidate virtualization, storage, and networking into single footprints. Technology firms are replacing discrete storage arrays with these denser configurations, as Bureau of Energy efficiency thresholds favor integrated power and thermal management over legacy discrete architectures.
- Blade Servers:High-density modular designs reduce cabling complexity for trading floor deployments. Financial services operators in Taipei prioritize these configurations for latency-sensitive co-location adjacent to securities exchanges.
- Tower Servers:Standalone vertical enclosures serve remote office and small datacenter requirements. Healthcare providers deploy these for departmental imaging and patient record systems where rack infrastructure proves economically unjustified.
Today's leader: Rack Servers. Tomorrow's challenger: Hyper-Converged Systems.
Deployment Model:
Cost tier differentiation separates capital-intensive owned infrastructure from operational expenditure models, with hybrid architectures capturing mid-market firms navigating workload portability requirements.
- On-Premises:Enterprise-owned facilities with direct control over hardware, power, and cooling. Financial services operators maintain these for regulatory data sovereignty under National Communications Commission telecommunications certifications.
- Cloud-Based:Hyperscale provider-managed compute with utility pricing. Technology firms are unbundling hardware ownership from operational management, paying per compute-hour instead of capital acquisition.
- Hybrid:Workload portability across private and public infrastructure. Healthcare organizations deploy these configurations to balance patient data compliance with burst capacity for genomic analysis.
- Managed Services:Third-party operational oversight of customer-owned equipment. Telecommunications operators offer these to enterprises lacking in-house thermal engineering expertise for liquid-cooled AI clusters.
Hybrid deployments are gaining share fastest among regulated industries, while cloud-based models dominate technology firm expansion.
End User:
Application-specific requirements drive divergent procurement patterns, with latency sensitivity and data sovereignty creating distinct vendor qualification criteria across verticals.
- Telecommunications:5G core network functions and edge computing nodes. These operators are installing micro data centers at base station locations, with National Communications Commission facility certifications governing distributed installations.
- Financial Services:Low-latency trading infrastructure and risk analytics. Banking operators prioritize blade architectures and co-location proximity to exchanges, consolidating vendor relationships around outcome-based infrastructure contracts.
- Healthcare:Electronic medical records and medical imaging storage. These deployments emphasize data residency compliance and disaster recovery redundancy over compute density.
- Technology Firms:AI training clusters and cloud-native application hosting. These buyers drive adoption of immersion cooling and ARM architecture migration for power-sensitive workloads.
Technology firms currently anchor procurement volume. Financial services represent the steepest expansion trajectory for high-density configurations.
Solution:
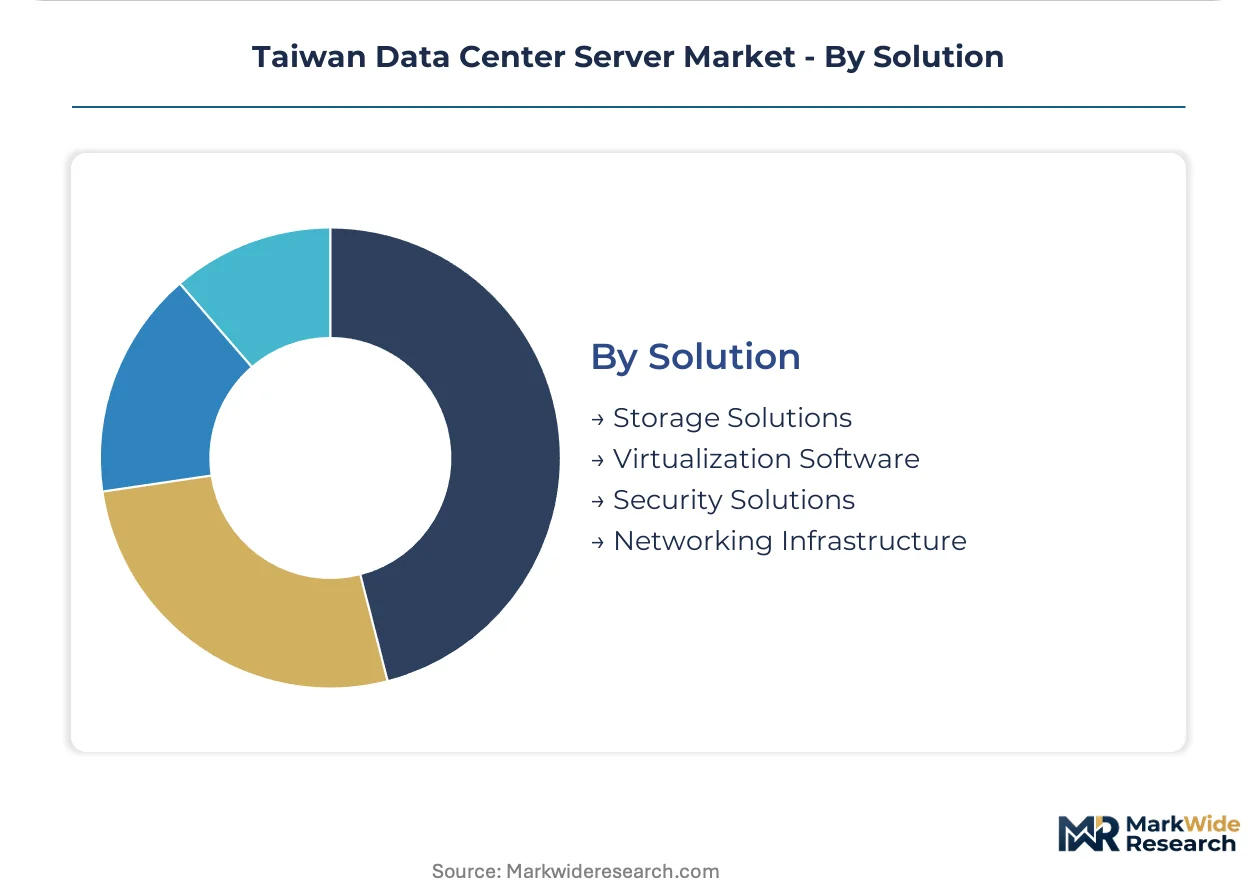
Margin concentration in software-defined layers is displacing commodity hardware value capture, with virtualization and security solutions commanding premium pricing over storage and networking components.
- Storage Solutions:All-flash arrays and software-defined storage for high-throughput workloads. Cloud operators in Taoyuan are scaling these for AI training data lakes.
- Virtualization Software:Hypervisors and container orchestration platforms. Legacy VMware estates at financial services operators resist container-native migration, stalling hyper-converged procurement on licensing renegotiation.
- Security Solutions:Hardware security modules and encryption acceleration. These address data protection requirements under telecommunications and financial regulations.
- Networking Infrastructure:High-speed interconnects and software-defined networking. These enable east-west traffic patterns in distributed AI clusters.
Virtualization software commands the highest margin expansion. Storage solutions face the greatest price pressure from commodity flash and software-defined alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's data center server industry traces its lineage to the island's semiconductor manufacturing ascendancy in the 1980s, when electronics contract manufacturing created the component ecosystem and engineering talent pool that now feeds server assembly and ODM operations.
Northern Taiwan
Taipei and Taoyuan anchor the island's data center concentration, with hyperscale cloud providers scaling compute footprints to serve regional AI inference demand. National Communications Commission telecommunications certifications govern facility operations in this corridor. Taoyuan's industrial zones face competing semiconductor fab demand, creating zoning delays and elevated lease rates for data center developers.
Central Taiwan
Taichung and Changhua are emerging as secondary clusters where land availability exceeds northern constraints. Ministry of Economic Affairs renewable energy procurement rules favor these locations for long-term power purchase agreements. Central Science Park infrastructure supports component logistics for server assembly operations serving domestic and export markets.
Southern Taiwan
Tainan and Kaohsiung offer greenfield development opportunities with land banks and offshore wind proximity. Bureau of Energy efficiency mandates shape power usage effectiveness thresholds for new builds in this region. Developers are securing offshore wind allocations before construction financing closes to meet commissioning requirements.
Eastern Taiwan
Hualien and Taitung remain peripheral to data center development due to limited fiber infrastructure and seismic considerations. Taiwan Power Corporation grid interconnection queues are shorter here, though submarine cable landing points concentrate on the western seaboard. Eastern counties may eventually host disaster recovery facilities leveraging geographic separation from primary clusters.
Taiwan Data Center Server Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the custom build versus standardized platform divide, with ODM heritage conferring manufacturing scale advantages that pure-play brands cannot replicate. The vendor base stratifies into three tiers: hyperscale-direct ODMs, enterprise-focused systems integrators, and component specialists supplying memory and acceleration silicon. Consolidation pressure runs through the middle tier as cloud operators bypass traditional channel relationships. Capacity expansion and captive manufacturing control represent the dominant competitive moves, with players securing wafer allocations and assembly floor space ahead of demand spikes.
Among Taiwan-based ODMs, Quanta Cloud Technology and Wiwynn exemplify the hyperscale-direct archetype, leveraging captive facilities in Taoyuan to sustain manufacturing scale for custom server builds. Super Micro Computer, though US-headquartered, occupies a differentiated position through liquid-cooled architecture specialization for high-density AI workloads. Dell Technologies and Hewlett Packard Enterprise sit within the enterprise systems tier, competing on global service footprints and software integration capabilities rather than manufacturing proximity.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Fujitsu |
| Kingston Technology Company |
| Nvidia Corporation |
| Super Micro Computer |
| Quanta Cloud Technology |
| Wiwynn |
| Others |
Pricing and Supply Chain Analysis
Ministry of Economic Affairs renewable energy procurement rules gate qualified supply access and premium-tier pricing for Taiwan data center servers, forcing operators to secure green energy certificates before facility commissioning and bifurcating vendor tiers between compliant and non-compliant suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Taiwan's data center server market, with liquid-cooled AI configurations commanding premium positioning against air-cooled commodity rack units. Price differentiation hinges on Bureau of Energy efficiency certification tiers and customization depth for hyperscale direct procurement. Cost compression in standard-tier rack servers is intensifying because ODM manufacturers compete on manufacturing scale for cloud provider volume contracts. Financial services operators exhibit the least price sensitivity, prioritizing latency performance and telecommunications certification compliance over per-unit acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Taoyuan and Taichung manufacturing corridors are tightening assembly floor capacity for custom server builds. Supply concentrates in Taiwan, China, and Vietnam for motherboard assembly and chassis fabrication, with memory modules and GPU accelerators drawing from South Korean and US semiconductor fabricators. Single-source vulnerability for advanced AI training chips from NVIDIA creates procurement bottlenecks for high-density configurations. Distribution runs through direct hyperscale relationships and enterprise systems integrators, bypassing traditional channel intermediaries for volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's data center server market represents a late-cycle quality story where renewable energy compliance and liquid-cooled density specifications now separate viable suppliers from commodity players, with hyperscale operators consolidating procurement around qualified ODM partners.
For Market Incumbents: Lock in captive manufacturing capacity in Taoyuan and central Taiwan science parks before semiconductor fab competition escalates land and power access constraints. Deepen backward integration into liquid cooling component supply to defend margin position against emerging thermal engineering specialists. Secure long-term power purchase agreements with offshore wind developers to maintain Ministry of Economic Affairs compliance eligibility for hyperscale tenders.
For New Entrants and Emerging Players: Begin with edge computing micro data center deployments for telecommunications operators, where National Communications Commission certification requirements create defensible qualification barriers against established rack server incumbents. Target southern Taiwan greenfield developments in Tainan and Kaohsiung where land scarcity pressures are lowest and renewable energy access is expanding fastest. Lead with ARM architecture migration services as a differentiated go-to-market angle for power-sensitive cloud workloads.
For Investors and Strategic Acquirers: Roll-up economics work for liquid-cooled thermal engineering specialists because hyperscale AI deployment timelines are compressing qualification windows and fragmenting vendor relationships across multiple cooling technology providers. Mid-cap ODMs with captive Taoyuan manufacturing and established Bureau of Energy efficiency certifications represent the most viable acquisition archetype over the medium-term horizon. Watch for hyperscale direct procurement contract announcements as the signal indicating which thermal engineering capabilities are achieving preferred vendor status.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Power Purchase Agreement | Secures Ministry of Economic Affairs compliance eligibility for facility commissioning and hyperscale vendor qualification. |
| Liquid Cooling Infrastructure Investment | Addresses Bureau of Energy efficiency thresholds for AI training clusters above 100kW rack densities. |
| ARM Architecture Platform Development | Diversifies processor supply beyond x86 dominance for power-sensitive cloud workloads. |
| Edge Computing Node Deployment | Captures 5G base station micro data center demand under National Communications Commission facility certifications. |
| Southern Taiwan Manufacturing Expansion | Accesses land banks and offshore wind proximity in Tainan and Kaohsiung for greenfield development. |
Research Methodology
Bottom-up hyperscale and enterprise procurement modeling reconciled against top-down ODM manufacturing capacity tracking forms the analytical core of this study. Primary interviews with data center facility operators, cloud procurement executives, thermal engineering directors, and telecommunications infrastructure planners combined with secondary validation from Taiwan Power Corporation interconnection queue data, Bureau of Energy efficiency filings, and National Communications Commission certification records. SEC filings from server ODMs and hyperscaler capex disclosures provided additional triangulation points for volume and value estimation.
Input-output matrices map server unit shipments against power density specifications, cooling architecture types, and end-use verticals across the projection horizon. Segmentation dimensions include product form factor, deployment model, end-user industry, and solution layer, with regional clusters modeled at northern, central, and southern Taiwan granularity. CAGRs derive from regression analysis of historical hyperscale capacity expansion patterns against renewable energy procurement timeline constraints, incorporating Bureau of Energy efficiency mandate phase-in schedules as structural inflection inputs.
Several conditions sit outside the modeled scope, including potential relaxation of Ministry of Economic Affairs renewable energy rules, Taiwan Power Corporation grid infrastructure acceleration beyond disclosed interconnection queues, and geopolitical disruption to semiconductor component supply chains. Forecasts reflect assumptions regarding continued hyperscale investment appetite and ARM architecture qualification timelines. Material deviation in hyperscale direct procurement contract announcements or Bureau of Energy efficiency threshold adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Rack Market