
 Sweden Data Center Rack Market | 2026-2036
Sweden Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Rack Market Insights
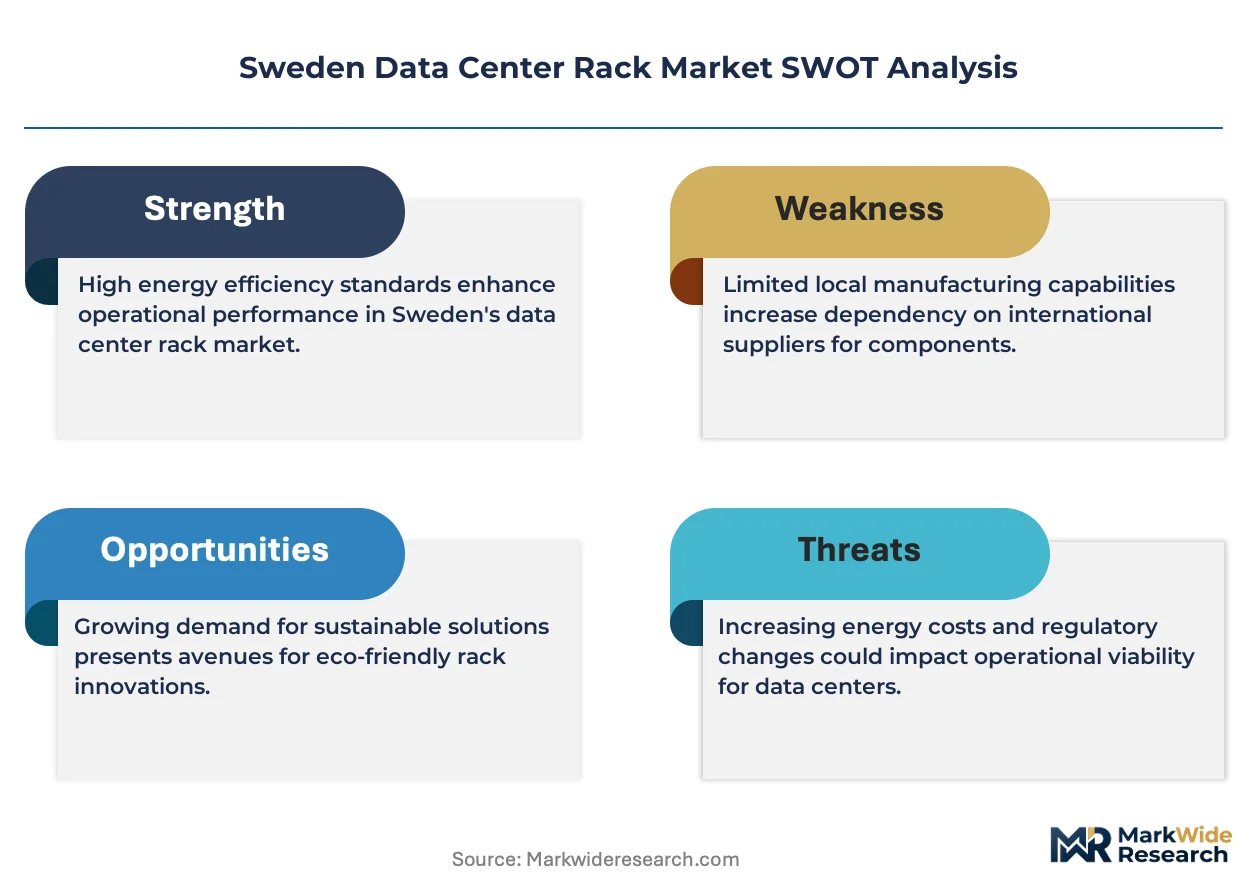
Premium rack specifications for liquid-cooled AI workloads is decoupling from commodity air-cooled units on price, thermal density, and certification requirements. Schneider Electric SE leverages its integrated cooling-rack portfolio to capture high-density deployments. Rittal GmbH & Co. KG anchors its position through precision manufacturing of modular enclosures for Nordic climate conditions. Vertiv Group Corp. differentiates via thermal management systems engineered for direct-to-chip liquid cooling integration.
Data center racks are structural enclosures that house servers, networking equipment, and power distribution units, typically constructed from cold-rolled steel with load ratings exceeding 1,500 kg and designed to optimize airflow or liquid cooling distribution. Their primary purpose is to organize IT infrastructure into standardized form factors that enable efficient cooling, cable management, and physical security in commercial computing environments. Enclosed rack configurations lead the product mix where acoustic containment and physical security drive procurement decisions among financial services enterprises. Liquid-cooling racks represent the fastest-expanding cooling technology segment as thermal design power thresholds for AI accelerators exceed traditional air-cooling limits. Custom size racks concentrate margin pools where hyperscale operators specify non-standard heights and depths for specialized accelerator hardware.
The Swedish Energy Agency enforces efficiency standards that compel data center operators to document power usage effectiveness, directly shaping rack-level cooling architecture decisions. BSI standards and EU Green Deal carbon accounting requirements intersect with national building codes to mandate thermal performance disclosures for enclosure systems. CE marking and RoHS compliance form baseline market access conditions for rack manufacturers supplying Swedish infrastructure projects. Stakeholders must monitor how the EU AI Act's infrastructure transparency requirements cascade into rack-level telemetry and monitoring specifications before procurement cycles finalize.
Market Dynamics
Liquid-cooling infrastructure is electrifying rack procurement decisions as AI training clusters in Stockholm and Uppsala exceed 100kW per rack thermal thresholds, forcing operators to abandon legacy air-cooled architectures mid-deployment cycle.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Operators must document embodied emissions in enclosure systems, accelerating replacement of legacy steel racks with lower-carbon modular designs certified under updated CE marking protocols.
- Hyperscale campus expansion in Stockholm:Cloud providers are consolidating Nordic data gravity around metropolitan fiber nodes, concentrating demand for high-load-rated enclosures with integrated cable management.
- Direct-to-chip liquid cooling:Thermal design power thresholds for AI accelerators now exceed 700W per chip, making precision-manufactured cold plates and manifold-integrated racks essential infrastructure rather than optional upgrades.
Market Restraints
- Specialized steel alloy supply concentration:Cold-rolled steel with specific tensile properties for 1,500kg+ load ratings sources primarily from Nordic mills with limited surge capacity, creating input bottlenecks during hyperscale construction windows.
- Liquid-cooling certification complexity:BSI standards for direct-to-chip systems lack harmonization with EU-wide pressure equipment directives, forcing manufacturers to maintain parallel testing protocols for Swedish market access.
- Skilled installation labor scarcity:Precision alignment of coolant distribution units with rack manifolds requires certified technicians, and training pipeline capacity lags deployment schedules in Uppsala and Gävleborg clusters.
Strategic Opportunities
- Modular enclosure retrofit services:Existing air-cooled facilities in Malmö and Gothenburg seek phased liquid-cooling conversions without full rack replacement, creating aftermarket hardware integration and engineering services demand.
- EU AI Act infrastructure transparency requirements:Telemetry mandates for high-risk AI systems cascade into rack-level monitoring specifications, opening specification windows for smart enclosures with embedded power and thermal sensors.
- Edge computing node proliferation:5G network densification and autonomous vehicle data processing are driving compact, weather-hardened rack demand in northern Sweden's Arctic Circle testing corridors.
Industry Challenges
- Legacy facility structural constraints:Raised floor depths and ceiling heights in pre-2020 Stockholm data centers cannot accommodate liquid-cooling manifolds without expensive building modification permits under national construction codes.
- Cross-vendor coolant compatibility:Proprietary dielectric fluid formulations from cooling system suppliers create integration friction with third-party rack manifolds, complicating multi-vendor procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Rack Market |
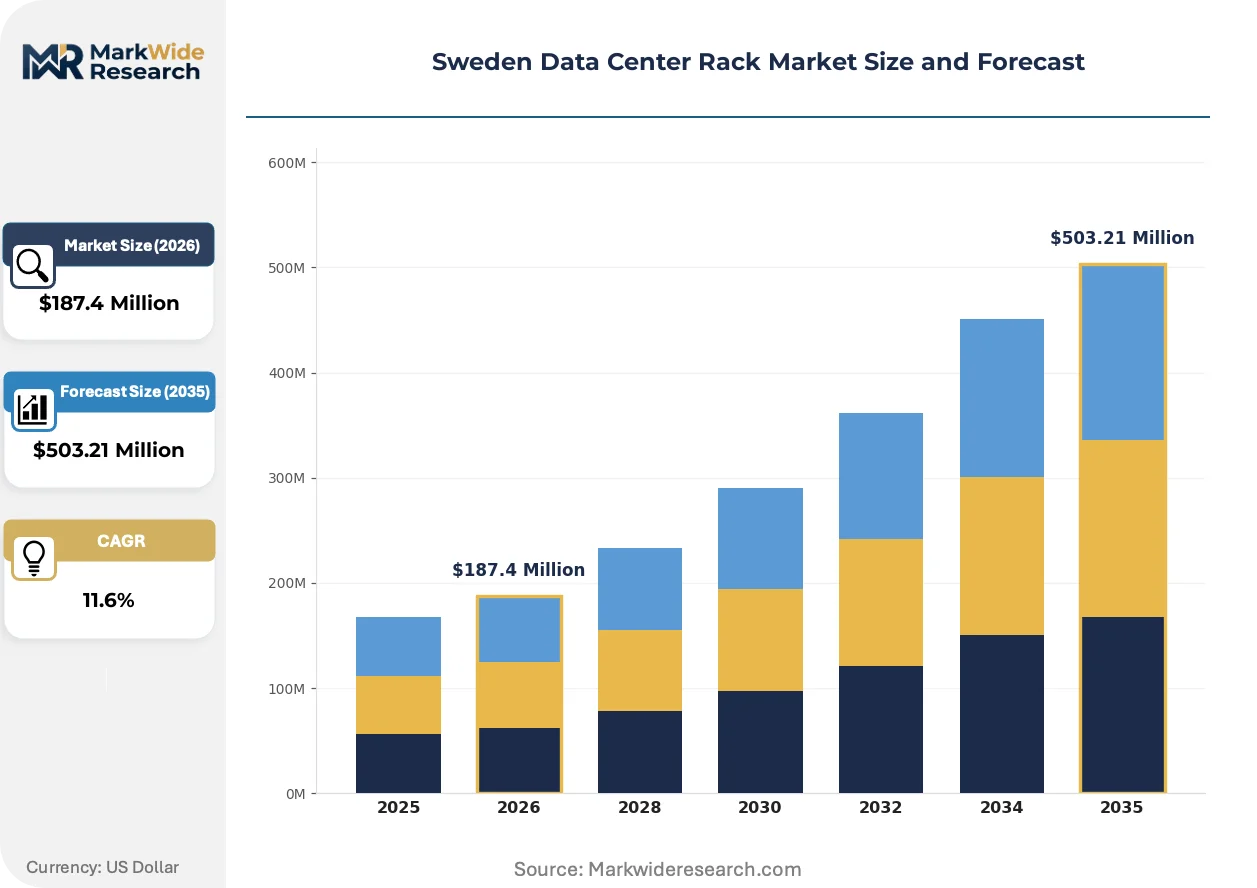
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Modular Rack End User: Telecom, IT Services, Cloud Providers, Enterprises Cooling Technology: Air-Cooling, Liquid-Cooling, Immersion Cooling, Free Cooling Size: 42U, 45U, 48U, Custom Size |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Rittal GmbH & Co. KG, Eaton Corporation plc, nVent Electric plc, Black Box Corporation, Hewlett Packard Enterprise, ENOC SYSTEM AB, ABB Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Rack Market Trends and Innovations
Three simultaneous vectors are restructuring the Swedish data center rack landscape: thermal architecture transformation, regulatory disclosure intensification, and procurement model consolidation around integrated cooling-enclosure packages.
Direct-to-chip liquid cooling is electrifying rack design specifications by embedding coolant distribution manifolds and quick-disconnect couplings directly into enclosure frames. Financial services enterprises in Stockholm's Kista district are specifying these integrated systems for trading floor adjacency deployments where acoustic containment and thermal density must coexist. The technology is compressing procurement cycles as operators abandon separate cooling and rack vendor relationships in favor of single-source thermal-envelope responsibility.
The Swedish Energy Agency's efficiency documentation requirements intersect with EU CSRD sustainability reporting mandates to force granular power usage effectiveness disclosure at the rack level. This regulatory convergence compels manufacturers to embed calibrated power distribution monitoring and thermal telemetry as standard rather than premium features. Hyperscale operators building in Uppsala are now mandating digital twin compatibility in rack specifications to satisfy upcoming infrastructure transparency audits.
Consolidated procurement of cooling-rack bundles is displacing discrete component purchasing among cloud providers with Stockholm metropolitan deployments. Tier-1 operators are negotiating thermal performance guarantees that span both enclosure and coolant distribution system, transferring integration risk to vendors. This pattern is most visible in hyperscale campus developments where single-source accountability for thermal design power compliance reduces project management overhead during compressed construction timelines.
Sweden Data Center Rack Market Segmentation
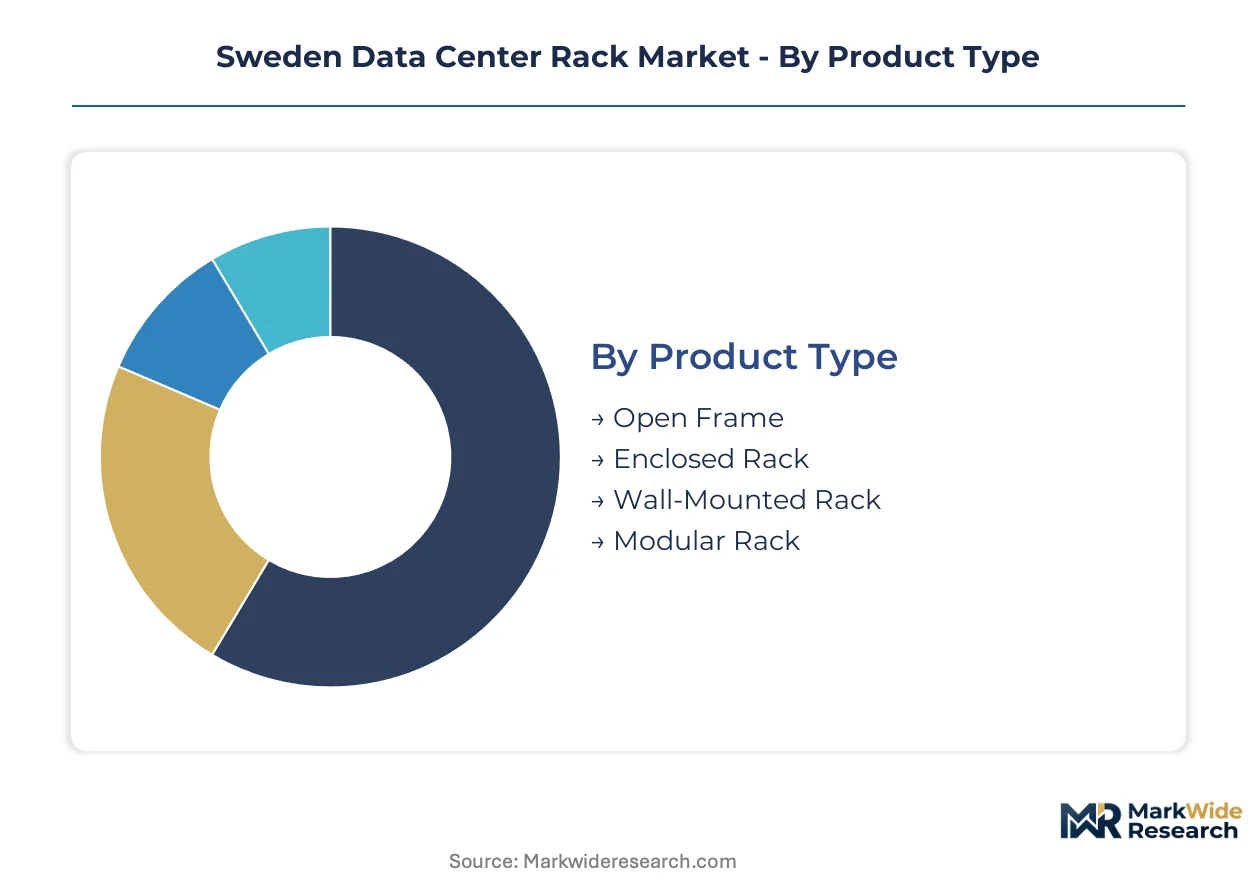
Rack segmentation in Sweden reflects divergent thermal architectures and deployment scales. Procurement patterns split between hyperscale liquid-cooling specifications and enterprise air-cooled standards. Understanding these fault lines clarifies where margin pools concentrate versus where volume commoditizes.
Product Type:
Structural configuration dictates cooling compatibility, security tier, and installation flexibility across Swedish facilities.
- Enclosed Rack:Steel-framed cabinets with lockable doors and side panels contain acoustic emissions and support physical security protocols. Financial services enterprises in Stockholm's Kista district specify these for trading floor adjacency deployments where noise suppression and access control converge.
- Modular Rack:Factory-integrated enclosures with pre-installed cable management and cooling distribution manifolds enable rapid deployment timelines. Cloud providers building hyperscale campuses in Uppsala favor these for compressed construction windows where field integration risk must transfer to vendors.
- Open Frame:Four-post structures without panels maximize airflow for legacy air-cooled servers in cost-sensitive retrofit scenarios.
- Wall-Mounted Rack:Compact hinged enclosures serve edge computing nodes and 5G aggregation points in space-constrained urban locations.
Enclosed Rack leads on scale; Modular Rack leads on momentum.
End User:
Customer procurement sophistication spans from standardized volume purchasing to bespoke thermal performance contracting.
- Cloud Providers:Hyperscale operators negotiate integrated cooling-rack bundles with thermal design power guarantees. These buyers in Stockholm metropolitan clusters consolidate Nordic data gravity around fiber-rich nodes, driving demand for non-standard rack dimensions and embedded telemetry.
- Enterprises:Corporate IT departments prioritize acoustic containment and physical security over thermal density. Financial services and manufacturing firms in Gothenburg and Malmö specify enclosed configurations with CE-marked compliance documentation for audit trails.
- IT Services:Colocation operators balance multi-tenant flexibility with operational standardization across shared facilities.
- Telecom:Network operators deploy weather-hardened compact racks for 5G densification and Arctic Circle testing corridors.
Cloud Providers command specification authority; Enterprises anchor replacement demand.
Cooling Technology:
Thermal architecture selection now determines rack procurement cycles rather than following them.
- Liquid-Cooling:Direct-to-chip and immersion systems integrate coolant distribution manifolds into enclosure frames. AI training clusters in Stockholm and Uppsala exceeding 100kW per rack thermal thresholds make precision-manufactured cold plates essential infrastructure.
- Air-Cooling:Conventional perforated-door configurations with raised floor plenums dominate legacy facility inventories. Pre-2020 Stockholm data centers with constrained ceiling heights continue deploying these where building modification permits prove prohibitive.
- Immersion Cooling:Dielectric fluid bath enclosures serve specialized high-density compute nodes in research and cryptocurrency applications.
- Free Cooling:Air-side economizer integration exploits Nordic climate conditions for seasonal efficiency gains in hyperscale facilities.
Air-Cooling retains installed base dominance; Liquid-Cooling climbs the fastest.
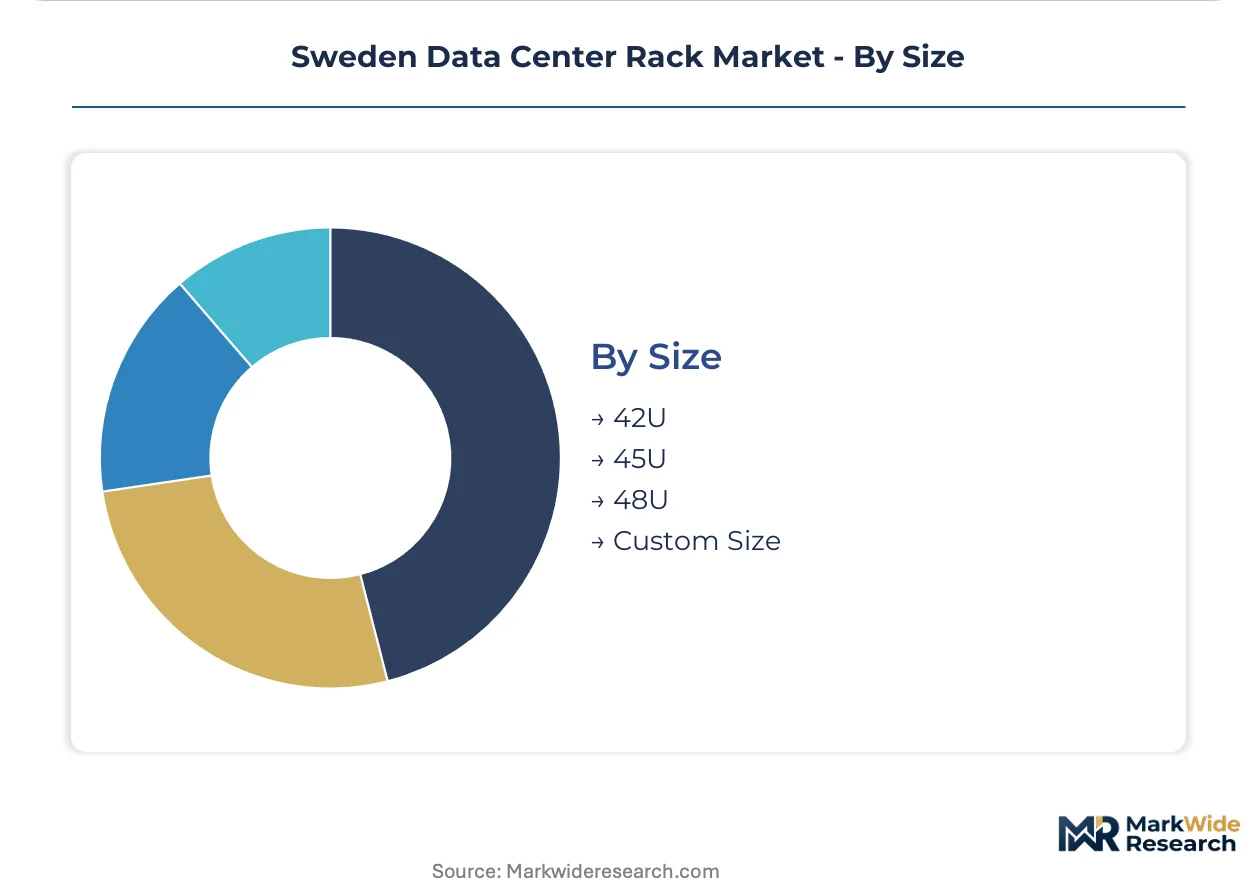
Size:
Rack height standardization fragments as accelerator hardware dimensions diverge from legacy server form factors.
- Custom Size:Non-standard heights and depths accommodate specialized AI accelerator hardware and liquid-cooling manifolds. Hyperscale operators in Uppsala specify these configurations to optimize floor space utilization against thermal design power requirements.
- 42U:The historical standard for enterprise air-cooled servers maintains procurement volume in retrofit and replacement cycles.
- 45U:Intermediate heights bridge legacy infrastructure and denser modern deployments.
- 48U:Extended configurations maximize vertical space in new-build facilities with adequate ceiling clearance.
42U leads on shipment volume; Custom Size concentrates margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's specialized engineering workforce anchors Nordic data center infrastructure development, with Stockholm's metropolitan cluster drawing hyperscale operators seeking liquid-cooling expertise and Uppsala's technical universities feeding precision manufacturing talent into enclosure supply chains.
Stockholm Metropolitan Area
Hyperscale cloud campuses concentrate in Kista and surrounding fiber-rich nodes, driving demand for custom-dimensioned racks with integrated coolant distribution. The Swedish Energy Agency enforces granular power usage effectiveness documentation that shapes procurement specifications. AI training clusters exceeding 100kW per rack thermal density are forcing liquid-cooling infrastructure deployment across new-build facilities.
Uppsala
Research-intensive compute installations leverage proximity to technical universities for thermal engineering collaboration. EU CSRD sustainability reporting mandates intersect with national efficiency standards to compel embedded telemetry in rack specifications. Cloud providers building hyperscale campuses here negotiate compressed construction timelines that favor modular enclosure systems with pre-integrated cooling manifolds.
Gothenburg
Legacy enterprise data centers in Sweden's second-largest city pursue phased air-to-liquid cooling retrofits without full infrastructure replacement. CE marking and RoHS compliance requirements anchor procurement decisions among manufacturing firms with audit-intensive operations. Financial services and industrial enterprises specify enclosed rack configurations prioritizing acoustic containment over thermal density.
Malmö
Cross-border connectivity to Copenhagen drives edge computing node deployment for low-latency applications. BSI standards for enclosure systems shape vendor selection among colocation operators serving Danish-Swedish enterprise demand. 5G network densification creates procurement windows for compact, weather-hardened racks in space-constrained urban locations.
Gävleborg
Northern Sweden's emerging data center corridor exploits cool climate conditions for free cooling integration. Skilled technician scarcity for precision coolant distribution unit alignment creates installation bottlenecks during hyperscale construction windows. Arctic Circle testing corridors for autonomous vehicle data processing drive demand for specialized environmental hardening in rack specifications.
Sweden Data Center Rack Market Competitive Landscape
Top-tier vendors anchor integrated cooling-rack bundles, while mid-tier fabricators compete on modular enclosure customization and regional logistics responsiveness. The vendor base stratifies between thermal performance guarantors and commodity structural steel suppliers. Three archetypes dominate: integrated infrastructure providers, precision enclosure specialists, and regional system integrators. Competitive moves concentrate on thermal-envelope single-source accountability and backward integration into coolant distribution component manufacturing.
Among integrated infrastructure providers, Schneider Electric SE, Vertiv Group Corp., and Rittal GmbH & Co. KG occupy positions exemplifying the shift toward thermal performance contracting. Schneider Electric SE represents the integrated portfolio archetype spanning power distribution through cooling integration. Vertiv Group Corp. sits within the thermal management specialization tier where coolant distribution engineering determines competitive positioning. Rittal GmbH & Co. KG anchors German precision manufacturing credibility for modular enclosures engineered to Nordic climate conditions. These three companies illustrate how procurement consolidation around single-source thermal accountability is restructuring vendor relationships in Stockholm and Uppsala hyperscale developments.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Rittal GmbH & Co. KG |
| Eaton Corporation plc |
| nVent Electric plc |
| Black Box Corporation |
| Hewlett Packard Enterprise |
| ENOC SYSTEM AB |
| ABB Ltd. |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal carbon accounting mandates gate both qualified supply and premium-tier pricing access, forcing rack manufacturers to certify lower-carbon steel grades and modular designs before hyperscale operators in Stockholm and Uppsala will entertain procurement discussions. This sustainability filter stratifies the vendor base between certified premium suppliers and commodity fabricators locked out of high-density AI cluster contracts.
Pricing Analysis
Bundled cooling-rack integration commands premium positioning against unbundled component sourcing, with three-tier pricing structure across premium, standard, and economy levels separating liquid-cooling certified systems from air-cooled enclosures and basic open-frame units. Price differentiation rests on CE marking tier and thermal performance guarantee coverage, with cost compression in standard air-cooled tiers intensifying because Nordic steel mills lack surge capacity during hyperscale construction windows. Cloud providers show lowest price sensitivity as they negotiate thermal-envelope single-source accountability, while enterprise retrofit buyers in Gothenburg and Malmö drive hardest bargain on replacement cycles.
Supply Chain Analysis
Single-source vulnerability sits with Nordic cold-rolled steel mills supplying specialized alloys for 1,500kg+ load-rated enclosures, drawing from Sweden, Finland, and Germany for precision-manufactured structural components. Raw material dependencies center on high-tensile steel grades, dielectric coolant formulations, and precision-machined manifold assemblies, with tariff exposure on German-engineered cooling components complicating multi-vendor procurement strategies. Distribution runs through direct vendor relationships with hyperscale operators and regional system integrators serving enterprise retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sweden data center rack market operates as a regulatory compounder, where the EU AI Act infrastructure transparency requirements cascade into rack-level telemetry specifications and sustain replacement demand across compliance cycles.
For Market Incumbents: Deepen backward integration into coolant distribution component manufacturing to capture margin pools shifting from discrete rack sales toward thermal performance contracting. Incumbent vendors must defend against modular retrofit specialists by embedding calibrated power and thermal sensors as standard features before EU CSRD audits commence, leveraging certification investment as a switching-cost moat. For New Entrants and Emerging Players: Edge computing node environmental hardening offers a technology-first wedge into underserved Arctic Circle testing corridors and 5G densification sites where weather-hardened compact rack demand outruns incumbent supply responsiveness. New entrants should target Gävleborg and northern Sweden geographies with rapid-deployment modular systems, using direct-to-chip liquid cooling compatibility as the primary go-to-market angle to bypass entrenched air-cooled relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with certified installation labor pipelines and modular enclosure customization capabilities, as these assets compound in scarcity value against hyperscale construction timelines. Acquisition targets should demonstrate digital twin compatibility and EU Green Deal certification pathways, with the signal to watch being BSI standard harmonization progress that would unlock margin expansion for early-compliant vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooling Bundle Integration | Single-source thermal accountability reduces project management overhead for Uppsala hyperscale campuses. |
| Embedded Telemetry Standardization | EU AI Act compliance mandates position smart enclosures for specification windows ahead of procurement cycles. |
| Modular Retrofit Service Expansion | Phased air-to-liquid conversions in Malmö and Gothenburg create aftermarket hardware integration demand. |
| Certified Installation Labor Pipeline | Training capacity expansion addresses technician scarcity bottlenecking Gävleborg cluster deployment schedules. |
| Digital Twin Compatibility Investment | Swedish Energy Agency documentation requirements compel granular power usage effectiveness disclosure infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center engineering directors, hyperscale procurement officers, thermal management specialists, and Nordic steel mill supply planners with secondary validation against SEC filings from infrastructure providers, Swedish Energy Agency efficiency documentation, BSI standard registers, and EU regulatory databases. Bottom-up shipment tracking and top-down facility investment analysis triangulated market sizing across the projection horizon.
Segment-weighting approach distributed value and volume across product type, cooling technology, end user, and regional deployment clusters, with CAGRs derived from facility construction pipeline analysis and thermal density requirement trajectories. The modeling framework incorporated hyperscale capex disclosure patterns, liquid-cooling penetration assumptions, and regulatory compliance timeline phasing throughout the forecast period.
The model holds under sustained AI training cluster expansion and EU regulatory enforcement continuity; deviation in Nordic steel mill capacity or BSI-EU directive harmonization delays would shift volume timing and margin distribution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
New York Data Center Market