
 China Data Center Storage Market | 2026-2036
China Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Storage Market Insights
China's eastern seaboard data center corridor is fragmenting into competing hyperscale hubs. Huawei Technologies Co., Ltd. dominates domestic flash storage controller development through in-house semiconductor design. Inspur Electronic Information Industry Co., Ltd. anchors server-storage integration for government and telecom tenders. Tencent Cloud Computing (Beijing) Co., Ltd. competes through proprietary distributed object storage architectures optimized for video and gaming workloads.
Data center storage encompasses electromechanical and solid-state systems engineered for enterprise-grade durability, measured by mean time between failures exceeding one million hours and input/output operations per second densities reaching millions per device. Solid state drives lead product type value pools due to latency requirements for real-time analytics, while hybrid storage architectures bridge magnetic archival capacity with flash performance tiers. Flash storage technology captures the fastest expansion trajectory as Chinese foundries advance NAND fabrication capabilities. Colocation deployment models concentrate margin pools in tier-one cities where land and power constraints limit greenfield construction.
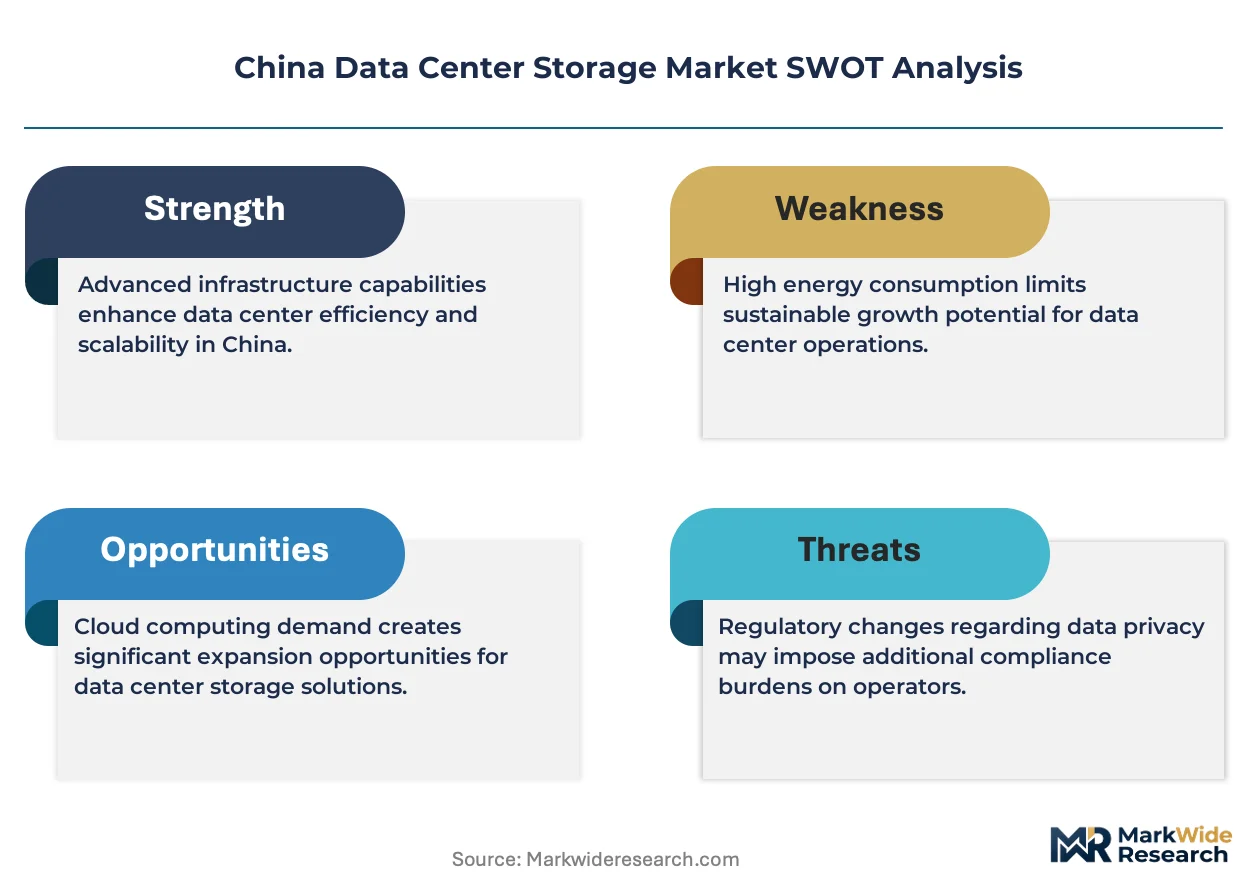
MIIT data center efficiency mandates and GB standards for energy consumption ratio enforcement are reshaping procurement specifications toward liquid-cooled, high-density storage configurations. NMPA cybersecurity review protocols for critical information infrastructure restrict foreign equipment ratios in designated facilities. SAMR antitrust scrutiny of cloud provider vertical integration is influencing partnership structures between hardware vendors and platform operators. Stakeholders must monitor domestic NAND supply ramp schedules and provincial carbon intensity quotas to calibrate capacity planning timelines.
Market Dynamics
MIIT efficiency mandates and NMPA cybersecurity review protocols are compressing procurement cycles while forcing domestic certification requirements onto storage infrastructure decisions across China's eastern seaboard data center corridor.
Growth Catalysts
- AI Training Workloads:Cloud service providers in Beijing and Shanghai are expanding storage procurement to support artificial intelligence model training. Flash storage arrays with sub-millisecond latency are displacing magnetic systems for real-time analytics pipelines.
- NMPA Cybersecurity Mandates:Critical information infrastructure designation requirements are accelerating demand for domestically certified storage systems. Foreign equipment ratios face strict caps in designated facilities.
- Yangtze River Delta Concentration:Hyperscale hub development across Shanghai, Jiangsu, and Zhejiang provinces is concentrating procurement volume. Land and power constraints in tier-one cities are favoring high-density storage configurations.
Market Restraints
- NAND Supply Concentration:Domestic foundry ramp schedules for advanced NAND fabrication remain uncertain. Memory controller supply bottlenecks are constraining flash storage system output.
- Power Infrastructure Limits:Provincial carbon intensity quotas under dual carbon goals are capping data center expansion in key eastern provinces. Beijing and Shanghai municipal governments are restricting new construction permits.
- Liquid Cooling Capex Burden:GB standards for energy consumption ratio enforcement are requiring costly infrastructure retrofits. Air-cooled legacy facilities face stranded asset risk without thermal redesign investment.
Strategic Opportunities
- Western China Expansion:Underpenetrated markets in Sichuan, Guizhou, and Inner Mongolia offer lower power costs and cooler climates. National computing hub initiatives are redirecting storage demand inland.
- Edge Computing Architectures:Distributed object storage optimized for video and gaming workloads is creating new deployment patterns. Content delivery networks are driving tier-two and tier-three city installations.
- SAMR Antitrust Enforcement:Scrutiny of cloud provider vertical integration is opening partnership structures between hardware vendors and platform operators. Independent storage system vendors are gaining tender access.
Industry Challenges
- Flash Controller Talent Scarcity:In-house semiconductor design capabilities are concentrated at a handful of domestic firms. Firmware engineering for enterprise-grade durability specifications requires specialized expertise.
- Legacy System Integration:Hybrid storage architectures bridging magnetic archival capacity with flash performance tiers are creating complex migration pathways. Mean time between failures certification for mixed environments extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Storage Market |
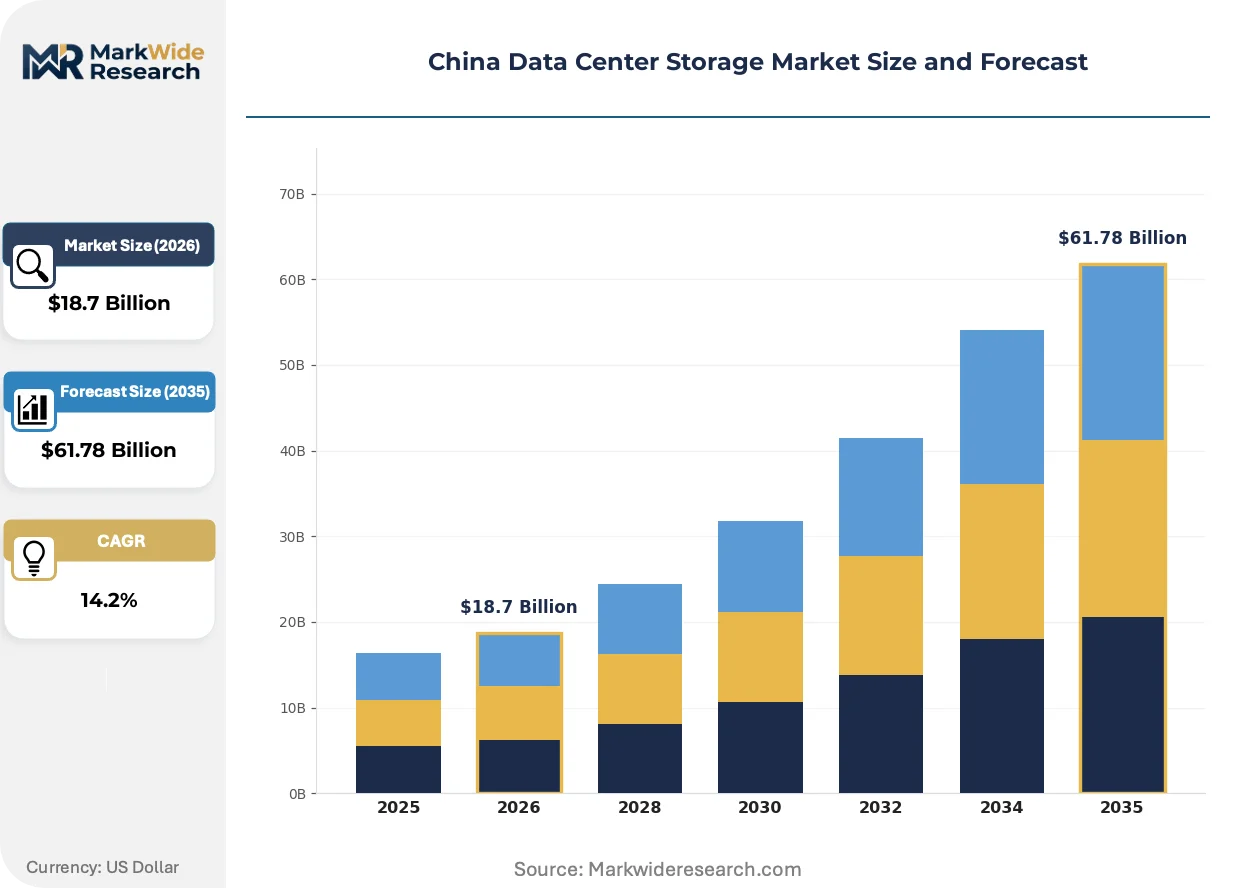
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Cloud Storage Technology: Flash Storage, Magnetic Storage, Optical Storage, Hybrid Storage End User: Telecommunications, BFSI, IT Companies, E-commerce Deployment Model: On-premises, Cloud-based, Hybrid, Colocation |
| Companies Covered | Huawei Technologies Co., Ltd., Alibaba Cloud Computing Co., Ltd., Inspur Electronic Information Industry Co., Ltd., Dell Technologies Inc., Hewlett Packard Enterprise Company, Tencent Cloud Computing (Beijing) Co., Ltd., Baidu AI Cloud Computing Ltd., China Telecom Corporation Limited, Lenovo Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Storage Market Trends and Innovations
Storage technology evolution in China is compressing around three vectors: domestic semiconductor capability advancement, regulatory compliance automation, and procurement model restructuring for AI-optimized infrastructure.
PCIe 5.0 NVMe solid-state drives are doubling interface bandwidth for enterprise storage arrays. Hyperscale cloud operators in Beijing and Shanghai are deploying these devices for training workload datasets. The technology is digitizing storage tiering decisions by enabling real-time data placement across performance and capacity layers without application-level intervention.
MIIT data center efficiency mandates are enforcing GB standard compliance through provincial inspection regimes. Facilities must document power usage effectiveness ratios and thermal design specifications. Colocation operators in the Yangtze River Delta are responding by specifying liquid-cooled, high-density storage configurations in new construction tenders.
Hyperscale buyers are consolidating storage procurement through direct foundry relationships rather than channel distribution. Server-storage integration specialists are capturing government and telecom tenders with bundled offerings. This concentration is most visible in Jiangsu and Zhejiang provinces where provincial SOE cloud contracts are consolidating vendor pools.
China Data Center Storage Market Segmentation
Storage procurement patterns across China's data center corridor diverge sharply by performance tier, workload latency requirements, and regulatory compliance obligations. Segment boundaries are hardening as MIIT efficiency mandates and NMPA cybersecurity protocols force technology-specific purchasing decisions.
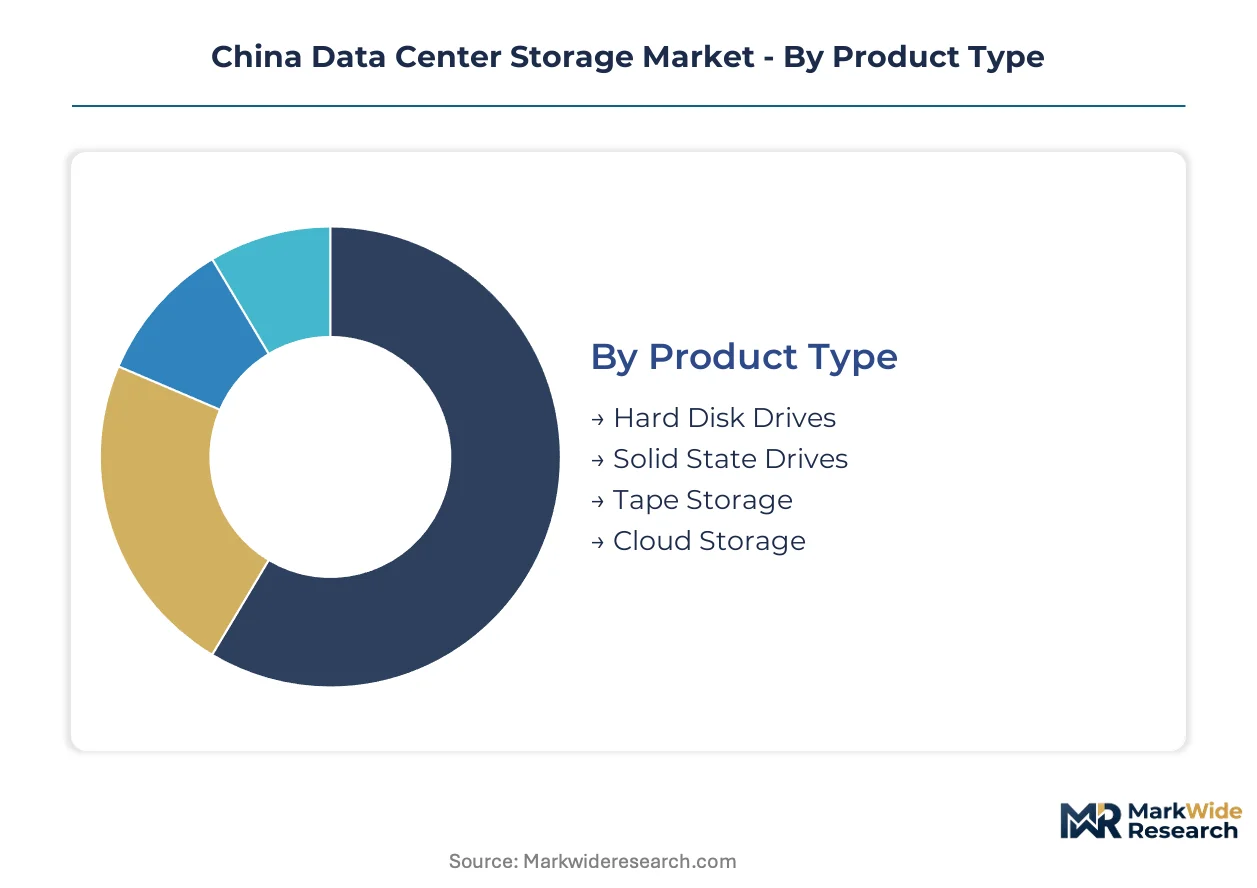
Product Type:
Cost tier determines procurement volume distribution, with flash commanding premium positioning against magnetic alternatives in AI-optimized facilities.
- Solid State Drives:NAND-based architectures deliver sub-millisecond latency for real-time analytics pipelines. Cloud service providers in Beijing and Shanghai are displacing magnetic systems for AI training workloads. PCIe 5.0 NVMe interfaces are doubling bandwidth for hyperscale deployments.
- Hard Disk Drives:Electromechanical systems retain cost-per-terabyte advantages for archival and cold storage tiers. Magnetic capacity layers bridge flash performance with long-term retention economics in hybrid configurations.
- Tape Storage:Linear tape-open systems serve compliance-mandated long-term retention for financial and government sectors under archival durability specifications.
- Cloud Storage:Distributed object architectures abstract physical infrastructure through API-driven consumption models for variable workload patterns.
Solid State Drives commands the established base. The steepest expansion runs through Cloud Storage.
Technology:
Application workload characteristics dictate technology selection, with latency-sensitive AI pipelines forcing flash adoption against throughput-optimized archival systems.
- Flash Storage:Non-volatile memory cell arrays eliminate mechanical latency for transaction processing and model training datasets. Domestic NAND fabrication ramp schedules are constraining controller supply for enterprise-grade durability specifications exceeding one million hours MTBF.
- Hybrid Storage:Automated tiering engines migrate data across flash and magnetic layers based on access patterns. Yangtze River Delta colocation operators specify these configurations to balance GB standard energy consumption ratios with performance guarantees.
- Magnetic Storage:Rotating platter systems retain dominance in bulk capacity deployments where power constraints under dual carbon goals limit flash proliferation.
- Optical Storage:Write-once media serve tamper-evident archival requirements for legal and regulatory documentation under NMPA critical infrastructure protocols.
Magnetic Storage commands the established base. The steepest expansion runs through Flash Storage.
End User:
Customer type concentration mirrors procurement scale, with hyperscale cloud operators and state-affiliated carriers driving volume against fragmented enterprise demand.
- IT Companies:Hyperscale cloud operators in Beijing and Shanghai consolidate storage procurement through direct foundry relationships rather than channel distribution. AI training workload expansion is compressing refresh cycles for flash-dominant configurations.
- Telecommunications:State-owned carriers anchor government and enterprise cloud tenders with bundled server-storage integration requirements. Provincial SOE contracts in Jiangsu and Zhejiang are consolidating vendor pools around domestic certification compliance.
- BFSI:Banking and insurance sectors face NMPA cybersecurity review mandates restricting foreign equipment ratios in designated critical infrastructure facilities.
- E-commerce:Transaction volume spikes during promotional cycles demand elastic storage provisioning through cloud-based deployment models.
Telecommunications commands the established base. The steepest expansion runs through IT Companies.
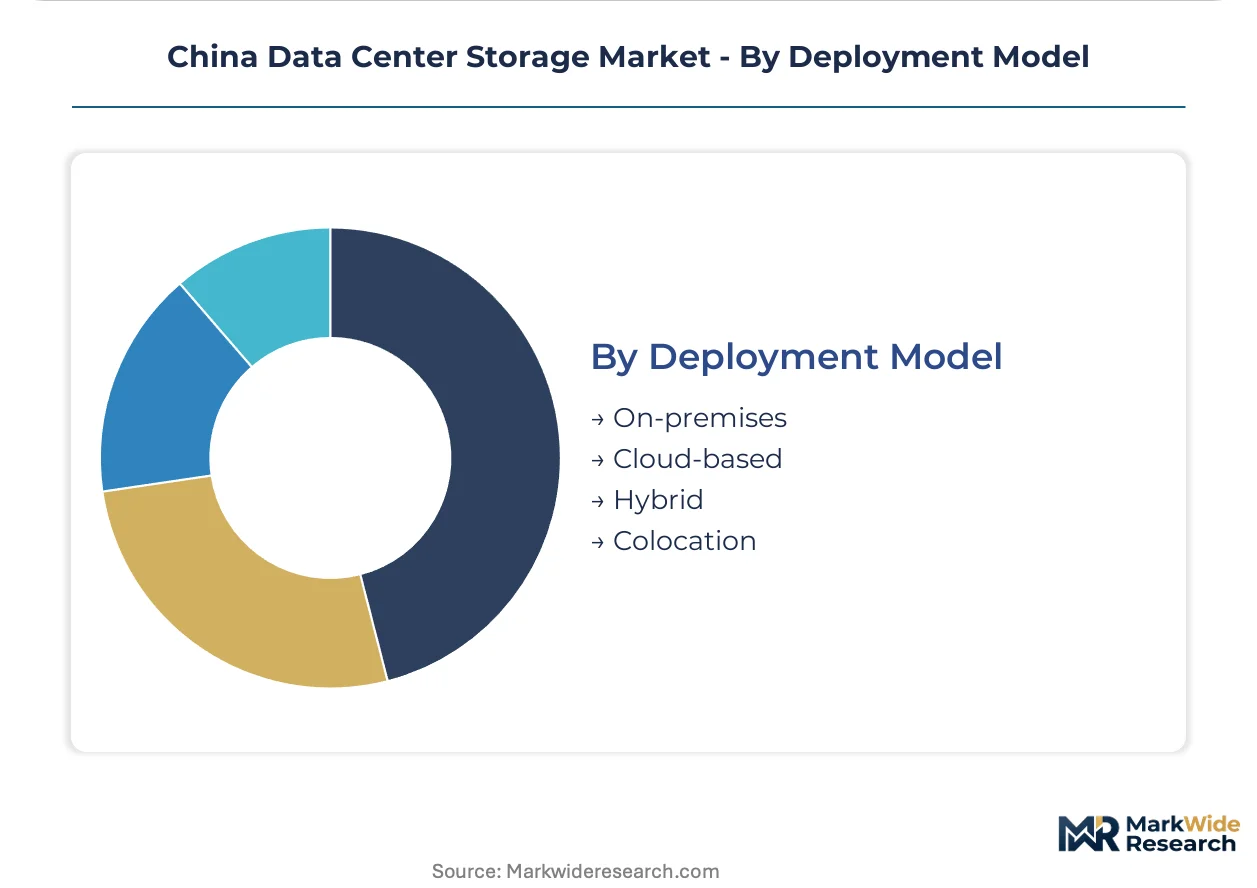
Deployment Model:
Geography constrains deployment feasibility, with land and power scarcity in tier-one cities forcing density-optimized configurations against underpenetrated western expansion zones.
- Colocation:Third-party facilities in Shanghai, Jiangsu, and Zhejiang concentrate margin pools where municipal construction permit restrictions limit greenfield development. Liquid-cooled, high-density storage specifications are dominating new tender requirements under GB standard enforcement.
- Cloud-based:Consumption-priced object storage eliminates capital intensity for variable workloads. Distributed architectures optimized for video and gaming workloads are driving edge installations in tier-two and tier-three cities.
- On-premises:Captive facilities retain preference for classified government workloads and latency-sensitive financial transaction processing.
- Hybrid:Orchestrated data placement across owned and leased infrastructure balances compliance sovereignty with elasticity requirements.
On-premises commands the established base. The steepest expansion runs through Colocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor underwrites China's data center storage concentration by enabling sub-four-hour transit for technical personnel between hyperscale clusters. This infrastructure asset anchors the eastern seaboard's dominance in flash storage procurement and AI training workload deployment.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces concentrate hyperscale procurement volume under MIIT efficiency mandates. GB standards for energy consumption ratio enforcement are reshaping tender specifications toward liquid-cooled configurations. Land scarcity in Shanghai municipality is forcing high-density storage deployments into suburban Jiangsu industrial parks.
Beijing-Tianjin-Hebei
Cloud service providers in Beijing are expanding flash storage procurement for AI model training datasets. NMPA cybersecurity review protocols restrict foreign equipment ratios in designated critical infrastructure facilities. Municipal construction permit restrictions are pushing capacity expansion toward Hebei satellite zones.
Guangdong-Hong Kong-Macao Greater Bay Area
Shenzhen and Guangzhou anchor demand for distributed object storage architectures optimized for video and gaming workloads. SAMR antitrust scrutiny of cloud provider vertical integration is influencing partnership structures between hardware vendors and platform operators. Provincial SOE cloud contracts are consolidating vendor pools around domestic certification compliance.
Sichuan-Chongqing
Chengdu and Chongqing offer lower power costs and cooler climates under national computing hub initiatives. Dual carbon goals are redirecting storage demand inland from saturated eastern markets. Western expansion zones present underpenetrated markets for colocation operators seeking alternatives to tier-one city constraints.
China Data Center Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the controller and memory fabrication layers. The vendor structure bifurcates between hyperscale cloud operators consolidating procurement through direct foundry relationships and independent hardware vendors capturing government tenders. Three archetypes dominate: semiconductor-integrated platform operators, server-storage bundlers serving state-affiliated carriers, and foreign multinationals navigating NMPA cybersecurity restrictions. Competitive positioning hardens around domestic certification compliance and liquid-cooled thermal design capabilities.
Among domestic platform operators, Huawei Technologies Co., Ltd. and Tencent Cloud Computing (Beijing) Co., Ltd. occupy positions reflecting divergent infrastructure strategies. Inspur Electronic Information Industry Co., Ltd. anchors the server-storage integration archetype for government and telecom procurement cycles. These three entities exemplify how vendor selection increasingly correlates with certification status under MIIT and NMPA protocols rather than pure performance specifications.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Alibaba Cloud Computing Co., Ltd. |
| Inspur Electronic Information Industry Co., Ltd. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise Company |
| Tencent Cloud Computing (Beijing) Co., Ltd. |
| Baidu AI Cloud Computing Ltd. |
| China Telecom Corporation Limited |
| Lenovo Group Limited |
| Others |
Pricing and Supply Chain Analysis
NAND controller supply bottlenecks determine both pricing tier spreads and supply chain shape in China's data center storage market. Memory controller scarcity compresses margins for flash storage systems while concentrating procurement power among hyperscale cloud operators with direct foundry relationships.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud operators from mid-tier colocation providers and enterprise buyers. Pricing stratifies across premium flash configurations for AI training workloads, standard hybrid architectures for general compute, and economy magnetic tiers for archival retention. Cost compression in economy tiers intensifies as domestic NAND foundries expand wafer output. Hyperscale buyers exhibit lowest price sensitivity due to captive supply agreements, while provincial SOE cloud contracts face strict budget caps under government procurement rules.
Supply Chain Analysis
Export-control regimes restricting advanced lithography equipment constrain domestic NAND fabrication ramp schedules. Controller silicon draws from Taiwan, South Korea, and USA design houses, while NAND wafer supply centers on Chinese and Korean foundries. Single-source vulnerability sits with advanced memory controller IP concentrated at foreign semiconductor firms. Distribution runs through direct hyperscale procurement channels and tiered distributor networks serving government and enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale cloud operators consolidating procurement through direct foundry relationships, fragmenting vendor access for independent hardware suppliers.
For Market Incumbents: Entrench domestic certification advantages under NMPA cybersecurity protocols by accelerating in-house controller development. Deepen backward integration into NAND fabrication partnerships to offset foreign IP dependency. Defend government tender access through bundled server-storage integration offerings aligned with MIIT efficiency mandates.
For New Entrants and Emerging Players: Western China underpenetration offers lower power costs and cooler climates under national computing hub initiatives. Target Sichuan and Guizhou provinces for colocation facility partnerships. Pursue edge computing architectures for video and gaming workloads in tier-two cities as the most penetrable deployment pattern.
For Investors and Strategic Acquirers: NMPA cybersecurity milestone enforcement reshapes the acquisition landscape by privileging domestically certified storage system vendors. Long-term viability centers on controller semiconductor capabilities and liquid-cooled thermal design expertise. Watch domestic NAND supply ramp schedules as the critical inflection signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic NAND Fabrication Scale-Up | Reduces controller supply dependency under MIIT localization mandates. |
| Liquid-Cooled Storage Configuration Development | Meets GB standard energy consumption ratio enforcement in Yangtze River Delta. |
| NMPA Cybersecurity Certification Investment | Unlocks critical infrastructure facility procurement restricted by foreign equipment caps. |
| Western China Colocation Partnership | Captures national computing hub redirect demand from saturated eastern markets. |
| Edge Object Storage Architecture Launch | Addresses video and gaming workload growth in tier-two and tier-three cities. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation. Interviews covered data center infrastructure executives, storage procurement officers at hyperscale cloud operators, MIIT policy researchers, NAND foundry planning managers, and colocation facility operators. Secondary sources included MIIT efficiency mandate documentation, NMPA cybersecurity review protocols, SAMR antitrust filings, hyperscaler capital expenditure disclosures, and provincial carbon intensity quota announcements. Bottom-up segment sizing triangulated against top-down market aggregate checks.
Forecast inputs considered deployment model shifts, product type mix evolution, and end-user concentration patterns across the projection horizon. Segmentation dimensions modeled include storage technology tier, deployment geography cluster, and customer type scale. CAGRs derived from segment-level volume trajectories weighted by pricing tier dynamics. NAND supply ramp schedules and provincial permit approval velocities served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by cloud operators would shift outcomes. Material shifts in NMPA cybersecurity equipment ratio enforcement or MIIT efficiency mandate stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Middle East Data Center Power Market