
 Hong Kong Data Center Power Market | 2026-2036
Hong Kong Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Power Market Insights
Project finance structures with power purchase agreement backing are reshaping competitive entry in Hong Kong data center power. Schneider Electric leverages its integrated microgrid portfolio to anchor large-scale deployments across the territory. CLP Power sustains grid interconnection dominance through dedicated substation investments serving Tseung Kwan O and Tsuen Wan clusters. Delta Electronics differentiates through high-efficiency power conversion systems purpose-built for tropical humidity conditions.
Hong Kong data center power encompasses the generation, conditioning, distribution, and backup systems that ensure continuous electrical supply to server facilities operating at densities exceeding 15 kW per rack. Uninterruptible power supply configurations and diesel rotary uninterruptible power supply (DRUPS) architectures provide ride-through capability during grid transitions, while switchgear rated to IEC 61439 standards segments primary and secondary distribution paths. Power source segmentation shows diesel-genset hybrid systems occupying the largest installed base, though renewable-backed configurations are gaining share as offtake agreements with offshore wind projects mature. Cooling technology segmentation reveals liquid cooling as the fastest-growing category, driven by GPU-intensive workloads in financial services and artificial inference applications where air cooling reaches thermal limits.
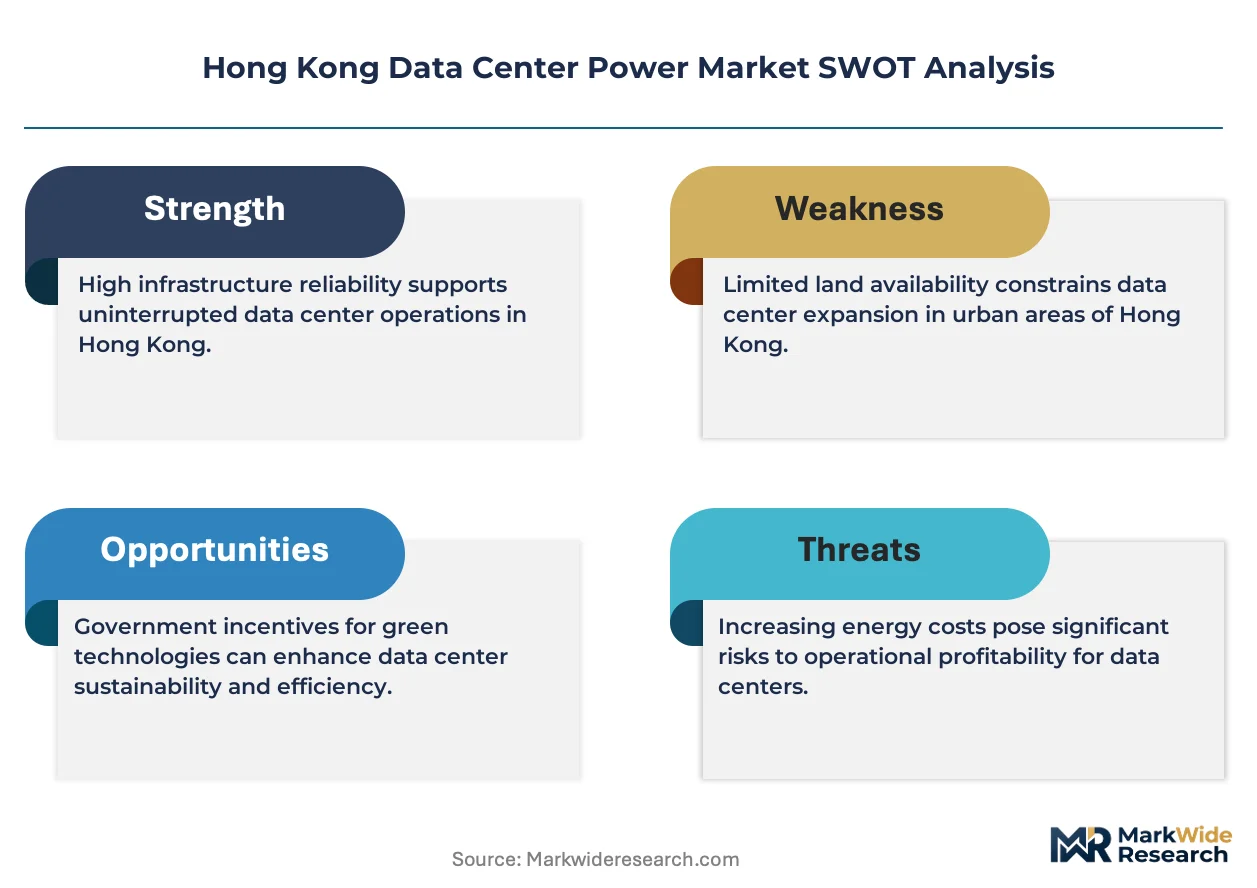
Hong Kong's Electrical and Mechanical Services Department enforces the Code of Practice for Energy Efficiency of Electrical Installations, which mandates power usage effectiveness reporting for facilities above defined consumption thresholds. The Environment Bureau's carbon neutrality policy and CLP Power's renewable energy certificate program together shape procurement standards, pressuring operators to document Scope 2 emissions reductions. Stakeholders must monitor grid reinforcement timelines and interconnection queue positions, as transmission capacity constraints at urban substations will determine which campus expansions proceed on schedule.
Market Dynamics
CLP Power's renewable energy certificate program and the Environment Bureau's carbon neutrality mandates are compressing deployment timelines for data center operators, forcing simultaneous grid interconnection queuing and on-site generation planning.
Growth Catalysts
- Financial services digitization:Banks and asset managers are expanding colocation footprints to support real-time trading platforms and digital banking infrastructure, pulling demand for resilient power architectures.
- Code of Practice for Energy Efficiency:Hong Kong's Electrical and Mechanical Services Department mandates power usage effectiveness reporting, creating compliance-driven retrofit cycles and equipment refresh demand.
- Submarine cable proximity:Hyperscale operators cluster in Tseung Kwan O Industrial Estate to minimize latency to trans-Pacific fiber routes, concentrating power infrastructure investment in this corridor.
Market Restraints
- Urban substation congestion:Transmission capacity constraints at primary grid nodes in Kowloon and Hong Kong Island limit interconnection approvals, extending project lead times.
- Diesel fuel volatility:Backup generator operators face input cost uncertainty as marine gas oil prices fluctuate, compressing operating margin predictability for DRUPS-reliant facilities.
- Land scarcity premiums:Industrial estate availability in Tsuen Wan and Tseung Kwan O commands elevated lease rates, inflating total cost of ownership for power infrastructure deployments.
Strategic Opportunities
- Offshore wind offtake:Renewable-backed power purchase agreements with emerging South China Sea wind projects offer Scope 2 emissions reduction pathways for carbon disclosure compliance.
- Liquid cooling convergence:GPU-intensive AI inference workloads are driving adoption of direct-to-chip thermal management, opening power density configurations beyond air-cooled limits.
- Microgrid islanding capability:Integrated battery storage and on-site generation systems enable participation in grid services markets during peak demand events.
Industry Challenges
- Specialized commissioning expertise:IEC 61439 switchgear certification and tropical-rated UPS integration require scarce electrical engineering talent, extending facility startup schedules.
- Legacy DRUPS replacement cycles:Existing diesel rotary uninterruptible power supply infrastructure demands phased modernization without disrupting continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Power Market |
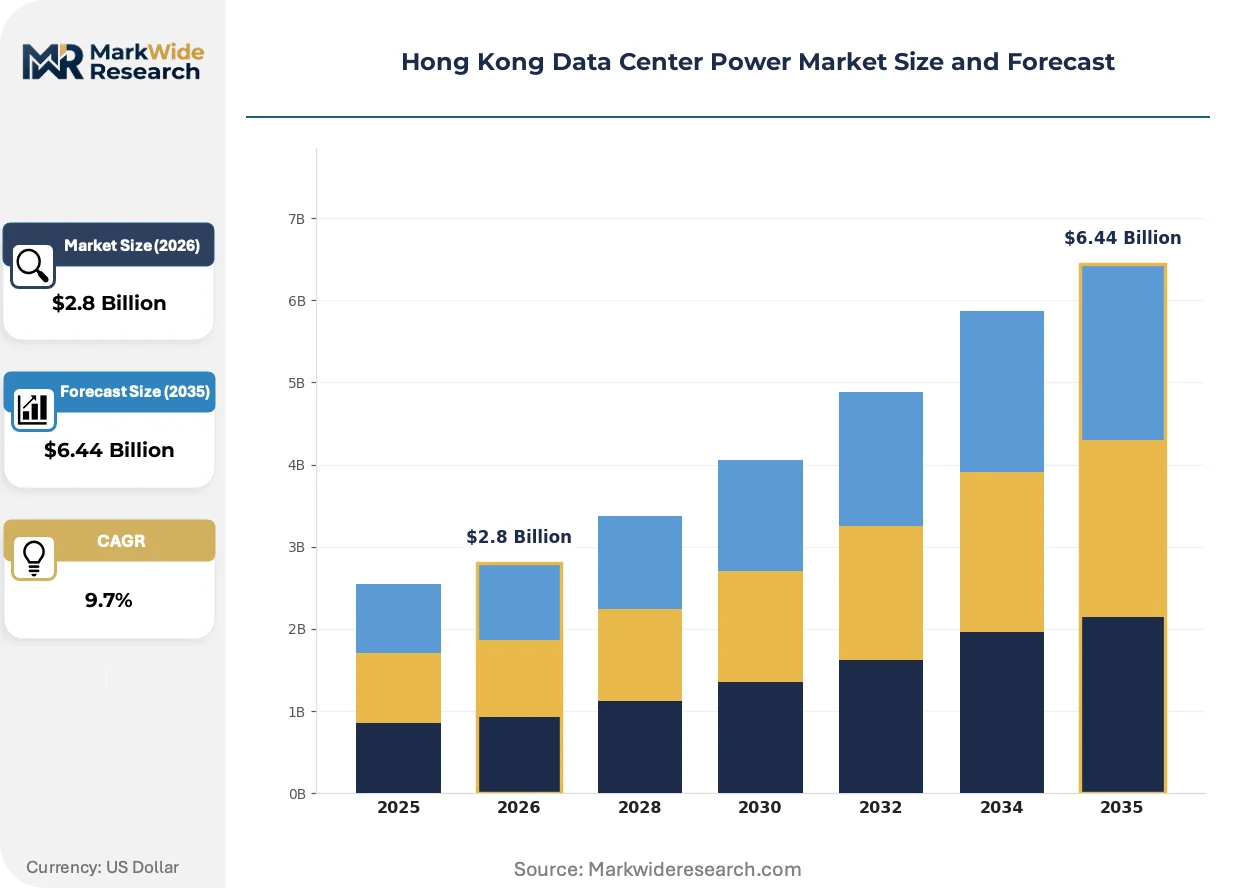
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable, Diesel, Natural Gas, Grid Service Type: Colocation, Managed Services, Dedicated Hosting, Hybrid Cloud Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Immersion Cooling End User: Telecom, Financial Services, E-commerce, Healthcare |
| Companies Covered | CLP Power, Hong Kong Electric Company, Schneider Electric, Fuji Electric, Piller Power Systems, Legrand, Delta Electronics, Eaton, Vertiv Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Power Market Trends and Innovations
Power architecture decisions in Hong Kong data centers are converging around three vectors: thermal management intensification, procurement compliance tightening, and operational model restructuring.
Direct liquid cooling is hybridizing rack-level power distribution by enabling 50-plus kilowatt densities previously unreachable with air-cooled designs. Financial services and AI inference operators are deploying cold plate and immersion systems at scale. This density compression is hybridizing traditional raised-floor layouts with overhead busbar and in-row power architectures.
The Environment Bureau's carbon neutrality policy and CLP Power's renewable energy certificate program are mandating documented Scope 2 emissions reductions. Facility operators must now secure verifiable clean energy procurement or purchase offsets. Hyperscale campuses in Tseung Kwan O are responding fastest, embedding renewable-backed power purchase agreements into project finance structures.
Buyer contracting patterns are consolidating around long-term capacity reservations with embedded energy price hedges. Colocation providers are unbundling power pass-through from space leases, exposing operators to wholesale electricity market volatility. This restructuring is most visible among financial services tenants demanding price certainty for multi-year deployments.
Hong Kong Data Center Power Market Segmentation
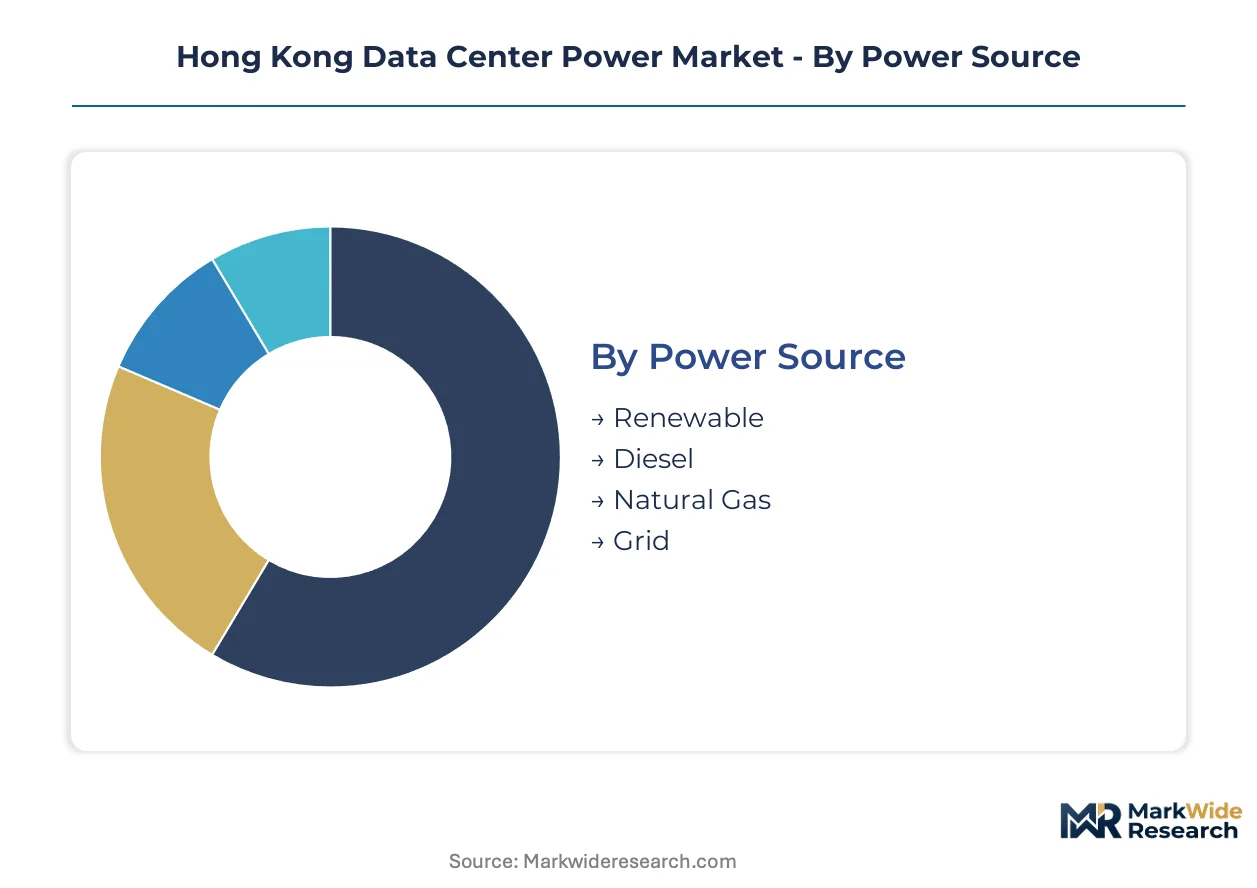
Hong Kong data center power procurement splits across four dimensions: how electricity is sourced, how facilities are operated, how heat is rejected, and which industries consume capacity. Each axis carries distinct regulatory, technical, and cost implications for facility design.
Power Source:
Cost tier differentiation separates baseline grid supply from premium low-carbon alternatives, with capital intensity rising as operators add on-site generation or renewable certificates.
- Diesel:Rotary UPS and genset configurations dominate existing installations, providing ride-through capability during CLP Power grid transitions. Financial services operators in Tseung Kwan O retain DRUPS infrastructure for sub-10-second failover compliance, though fuel price volatility compresses operating margins.
- Renewable:Offshore wind-backed power purchase agreements and CLP Power renewable energy certificates enable Scope 2 emissions documentation for carbon disclosure mandates. Hyperscale campuses embed these contracts into project finance structures to satisfy Environment Bureau neutrality timelines.
- Natural Gas:Trigeneration systems supply baseload power plus absorption cooling for facilities seeking thermal efficiency integration.
- Grid:Direct interconnection through dedicated substations remains the default for smaller colocation operators lacking capital for on-site generation.
Diesel commands the established base. The steepest expansion runs through renewable-backed configurations.
Service Type:
Customer control over infrastructure determines power architecture responsibility, with higher service tiers demanding more resilient backup systems.
- Colocation:Multi-tenant facilities standardize power redundancy to attract financial services and cloud customers. Operators unbundle power pass-through from space leases, exposing tenants to wholesale electricity volatility while offering long-term capacity reservations with price hedges.
- Dedicated Hosting:Single-tenant deployments allow customized UPS configurations matching specific workload criticality. Banks in Tsuen Wan clusters specify IEC 61439-rated switchgear and tropical-rated UPS integration for trading floor uptime guarantees.
- Managed Services:Providers retain full power infrastructure responsibility, absorbing operational risk for healthcare and e-commerce clients.
- Hybrid Cloud:Workload portability between on-premise and public cloud creates variable power density requirements across facility zones.
Colocation holds the volume concentration. The fastest share gains are occurring in hybrid cloud as enterprises rebalance capex and opex.
Cooling Technology:
Thermal management intensity tracks rack power density, with liquid and immersion systems unlocking densities beyond air-cooled limits.
- Liquid Cooling:Direct-to-chip cold plates handle GPU-intensive AI inference workloads exceeding 50 kW per rack. Financial services operators deploy these systems for real-time risk analytics where air cooling hits thermal constraints.
- Air Cooling:Raised-floor CRAH configurations persist for legacy enterprise workloads below 15 kW per rack, though efficiency retrofits are accelerating under Electrical and Mechanical Services Department reporting mandates.
- Immersion Cooling:Dielectric fluid baths enable the highest densities for cryptocurrency and HPC applications, with tropical humidity compatibility driving adoption in Hong Kong's climate.
- Evaporative Cooling:Adiabatic systems supplement mechanical cooling during shoulder seasons, reducing CLP Power grid draw and operating costs.
Air cooling retains the installed majority. Liquid cooling is climbing the fastest as AI workloads proliferate.
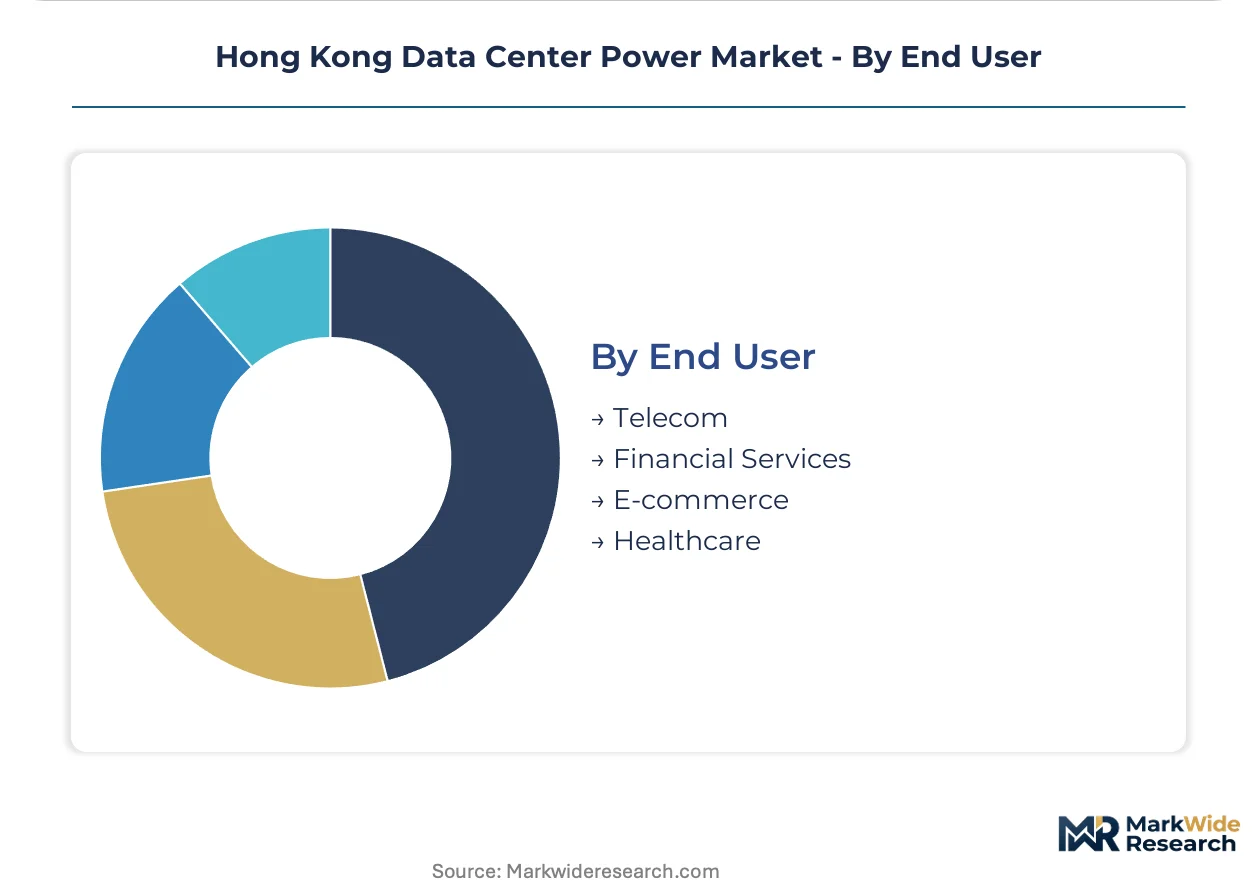
End User:
Industry-specific uptime requirements and regulatory exposure shape power architecture specifications and procurement contracting patterns.
- Financial Services:Banks and asset managers mandate Tier III or Tier IV redundancy with sub-15-minute backup runtime for trading platforms. HKMA operational resilience guidelines and real-time settlement demands pull investment toward DRUPS and microgrid islanding capability.
- Telecom:Mobile network operators and internet exchanges prioritize submarine cable proximity in Tseung Kwan O, concentrating power infrastructure investment near landing points for latency-sensitive traffic exchange.
- E-commerce:Peak demand volatility during promotional events drives interest in battery storage participation in CLP Power grid services markets.
- Healthcare:Patient data hosting under Hong Kong's PDPO requirements demands encrypted power monitoring and documented business continuity testing.
Financial services anchors premium power investment. E-commerce is expanding most quickly as cross-border retail digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hong Kong data center power infrastructure relies on imported electricity and fuel, with CLP Power sourcing generation from the Daya Bay nuclear plant and liquefied natural gas terminals. The territory's export-import energy balance shapes procurement strategies, pressuring operators to secure renewable certificates and on-site generation capacity.
Tseung Kwan O Industrial Estate
Hyperscale campuses cluster near submarine cable landing points serving trans-Pacific fiber routes. CLP Power has invested in dedicated 132kV substations to support density loads exceeding 100 MW per campus. Financial services firms anchor demand here, mandating Tier IV redundancy for trading infrastructure.
Tsuen Wan Cluster
Dedicated hosting facilities serve banking clients requiring customized switchgear configurations. Hong Kong Electric Company maintains grid interconnection dominance through urban substation upgrades. The district faces transmission capacity constraints, extending interconnection approval timelines.
Kowloon Bay
Legacy colocation operators manage diesel rotary UPS infrastructure originally deployed for enterprise workloads. Electrical and Mechanical Services Department energy efficiency codes drive retrofit cycles for facilities below modern power usage effectiveness thresholds. Battery storage pilots are testing grid services participation.
Sha Tin
Telecom exchanges and internet backbone operators concentrate near terrestrial cable corridors. Delta Electronics and Vertiv Group supply tropical-rated power conversion equipment to manage humidity-induced equipment degradation. Managed services providers absorb operational risk for healthcare clients under PDPO requirements.
Hong Kong Island
Land scarcity limits greenfield expansion, forcing vertical retrofit of existing commercial buildings. Schneider Electric anchors microgrid deployments integrating battery storage with on-site generation. Premium lease rates inflate total cost of ownership for power infrastructure.
Hong Kong Data Center Power Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying power conversion, thermal management, and switchgear subsystems. The vendor base organizes around three archetypes: integrated infrastructure platforms, electrical component fabricators, and power quality specialists. Competitive positioning hinges on project finance structuring capability and tropical climate certification. Players are pursuing strategic partnerships with offshore wind developers and expanding commissioning expertise pools.
Within the integrated platform tier, Schneider Electric and Vertiv Group exemplify full-stack providers spanning microgrid design through operational software. CLP Power occupies a unique position as the territory's dominant grid interconnection gatekeeper, controlling dedicated substation investments that determine which campus expansions proceed on schedule. Delta Electronics represents the component specialist archetype, with power conversion systems purpose-built for high-humidity operating environments.
| Leading Market Players |
|---|
| CLP Power |
| Hong Kong Electric Company |
| Schneider Electric |
| Fuji Electric |
| Piller Power Systems |
| Legrand |
| Delta Electronics |
| Eaton |
| Vertiv Group |
| Others |
Pricing and Supply Chain Analysis
Diesel fuel price volatility determines both margin compression for DRUPS-reliant operators and the geographic clustering of backup generation capacity around Tseung Kwan O and Tsuen Wan industrial zones. CLP Power grid interconnection queue positions and renewable energy certificate premiums simultaneously shape procurement tier spreads and facility location decisions across Hong Kong's constrained land base.
Pricing Analysis
Financial services buyers anchor long-term capacity reservations with embedded energy price hedges. Three-tier pricing structure across premium renewable-backed, standard grid-interconnected, and economy diesel-hybrid configurations reflects certification tier and uptime guarantee differentiation. Pricing pressure stems from CLP Power transmission capacity constraints extending interconnection timelines and inflating substation upgrade pass-through costs. Colocation tenants exhibit highest price sensitivity due to unbundled power pass-through exposure, while dedicated hosting banks absorb premium pricing for customized switchgear configurations.
Supply Chain Analysis
Contract manufacturing concentration rests with Delta Electronics and Vertiv Group for tropical-rated power conversion equipment, with Schneider Electric anchoring integrated microgrid platform assembly. Geographic supply concentration centers on Taiwan for advanced UPS components, mainland China for switchgear fabrication, and Japan for precision power quality instrumentation. Raw material dependencies include copper busbar stock, silicon carbide semiconductors, and marine-grade diesel fuel. Single-source vulnerability concentrates in IEC 61439-certified switchgear suppliers qualified for Hong Kong's humidity conditions. Distribution runs through CLP Power's dedicated substation infrastructure and direct OEM channel partnerships with facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon neutrality mandates from Hong Kong's Environment Bureau are compressing deployment timelines and forcing simultaneous grid interconnection queuing and renewable procurement planning, creating a high-growth disruption window for power infrastructure specialists.
For Market Incumbents: Insulate margin position through backward integration into battery storage systems and captive renewable energy certificate procurement. CLP Power's substation investment dominance threatens non-integrated operators with interconnection delays. Vertical control over commissioning expertise pools extends facility startup schedules and locks out competitors. For New Entrants and Emerging Players: Establish a beachhead in liquid cooling power distribution architectures for GPU-intensive AI inference workloads. Tseung Kwan O hyperscale campuses represent the most penetrable segment, with financial services operators demanding 50-plus kilowatt density configurations beyond legacy air-cooled limits. Go-to-market positioning should emphasize tropical humidity certification and direct-to-chip thermal management integration. For Investors and Strategic Acquirers: The Environment Bureau's carbon neutrality policy reshapes the acquisition landscape toward renewable-backed project finance capability. Long-term viability favors operators with embedded offshore wind power purchase agreements and documented Scope 2 reduction pathways. Target acquisition archetype: integrated platform providers with CLP Power interconnection queue positions. Signal to monitor: grid reinforcement timeline announcements for urban substation capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Certificate Procurement | CLP Power certificate programs enable Scope 2 compliance for carbon disclosure mandates. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems unlock 50 kW densities for AI inference workloads in financial services. |
| Microgrid Islanding Capability Investment | Battery storage integration enables CLP Power grid services participation during peak demand. |
| IEC 61439 Switchgear Certification | Tropical-rated certification qualifies suppliers for Hong Kong's humidity-degraded electrical environments. |
| Offshore Wind Power Purchase Agreement | South China Sea wind offtake contracts embed renewable backing into project finance structures. |
Research Methodology
The analysis maps diesel-genset hybrid systems, renewable-backed configurations, liquid cooling architectures, and grid-interconnected facilities, each validated through primary interviews with data center facility directors, CLP Power interconnection planners, electrical engineering contractors, and financial services colocation procurement leads. Secondary sources include Electrical and Mechanical Services Department energy efficiency filings, Environment Bureau carbon neutrality policy documents, CLP Power renewable energy certificate registry data, and submarine cable landing point infrastructure records. Bottom-up facility capacity estimates triangulate against top-down territory electricity consumption projections.
Assumption sets held CLP Power grid reinforcement timelines and offshore wind project development schedules fixed at announced trajectories, while diesel fuel price volatility and land lease rate inflation were varied across sensitivity bands. Segmentation dimensions modeled span power source, service type, cooling technology, and end user industry across the projection horizon. CAGRs derive from facility pipeline tracking and interconnection queue position analysis, with inputs including hyperscale campus announcement cadence and financial services digitization spend patterns.
Stress conditions across marine gas oil price spikes, CLP Power transmission delay extensions, and renewable certificate premium inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on grid decarbonization policy continuity and submarine cable capacity expansion. Quarterly review of CLP Power substation investment announcements and Environment Bureau enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
DC Powered Servers Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Managed Data Center Services Market