
 Asia-Pacific Hosting Infrastructure Services Market | 2026-2036
Asia-Pacific Hosting Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hosting Infrastructure Services Market Insights
Enterprise buyers are redrawing the demand map for Asia-Pacific Hosting Infrastructure Services, as large enterprises and government agencies displace SMEs as the fastest-growing buyer archetype. Alibaba Cloud leverages its domestic data center density to anchor mainland China workloads. Microsoft Azure sustains hybrid cloud dominance through extensive partner channel control across Southeast Asia. Huawei Cloud competes aggressively on sovereign cloud mandates in Indonesia and Thailand.
Asia-Pacific Hosting Infrastructure Services encompass compute, storage, and networking resources delivered through third-party data centers with service level agreements guaranteeing uptime percentages typically ranging from 99.9% to 99.999%, designed to host applications, databases, and digital platforms without capital-intensive facility ownership. Cloud Hosting captures the fastest expansion as enterprises migrate legacy virtualization stacks to elastic consumption models. Hybrid Cloud deployments concentrate margin pools where managed service bundles overlay orchestration complexity. Containerization technology leads R&D allocation as Kubernetes-native platforms displace traditional hypervisor architectures.
China's MIIT enforces GB standards for cloud service classification and cross-border data transfer restrictions, while India's MeitY mandates data localization for government cloud procurement, and Australia's TGA-aligned frameworks impose cybersecurity baselines on critical infrastructure hosting. These regulations shape demand toward compliant in-country facilities and certified operators. Stakeholders must monitor evolving sovereignty requirements and certification reciprocity across jurisdictions to align capacity planning with enforceable compliance thresholds.
Market Dynamics
Container orchestration platforms are compressing legacy virtualization margins across the Asia-Pacific Hosting Infrastructure Services landscape, forcing providers to rearchitect service delivery around Kubernetes-native stacks or cede workload portability to hyperscale competitors.
Growth Catalysts
- India's MeitY Localization Mandates:Government cloud procurement rules requiring in-country data residency are funneling sovereign workloads toward domestic facilities in Mumbai and Hyderabad.
- Financial Services Real-Time Trading:Capital markets firms across Singapore and Hong Kong are expanding colocation footprints to minimize latency for algorithmic execution platforms.
- Containerization Migration:Kubernetes-native infrastructure is supplanting traditional hypervisor estates as enterprises seek granular resource elasticity and faster deployment cycles.
Market Restraints
- Power Input Cost Volatility:Electricity tariffs in Australian and Japanese data center clusters are squeezing facility operating margins and complicating long-term pricing commitments.
- Cross-Border Data Transfer Friction:China's MIIT GB standards impose circuitous compliance pathways for multinational enterprises operating hybrid workloads across mainland and offshore nodes.
- Technical Debt in Legacy Stacks:Decade-old virtualization estates in Southeast Asian manufacturing hubs resist seamless container migration without substantial re-platforming investment.
Strategic Opportunities
- Indonesia's Sovereign Cloud Gap:Regulatory pressure for data localization outpaces certified domestic supply, creating first-mover advantage for compliant facility operators in Jakarta.
- Edge-AI Convergence:GPU-accelerated edge nodes combined with 5G network slicing are opening low-latency inference hosting for autonomous systems and industrial IoT.
- Green Certificate Arbitrage:Renewable energy attribute trading schemes in South Korea and Japan allow carbon-neutral positioning without captive renewable generation.
Industry Challenges
- Kubernetes Operations Talent Scarcity:Platform engineering and Site Reliability Engineering skill pools remain concentrated in Bangalore and Singapore, constraining regional expansion velocity.
- Multi-Cloud Orchestration Complexity:Enterprise buyers demand unified management across Alibaba Cloud, Azure, and Huawei Cloud estates, stretching managed service provider integration capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hosting Infrastructure Services Market |
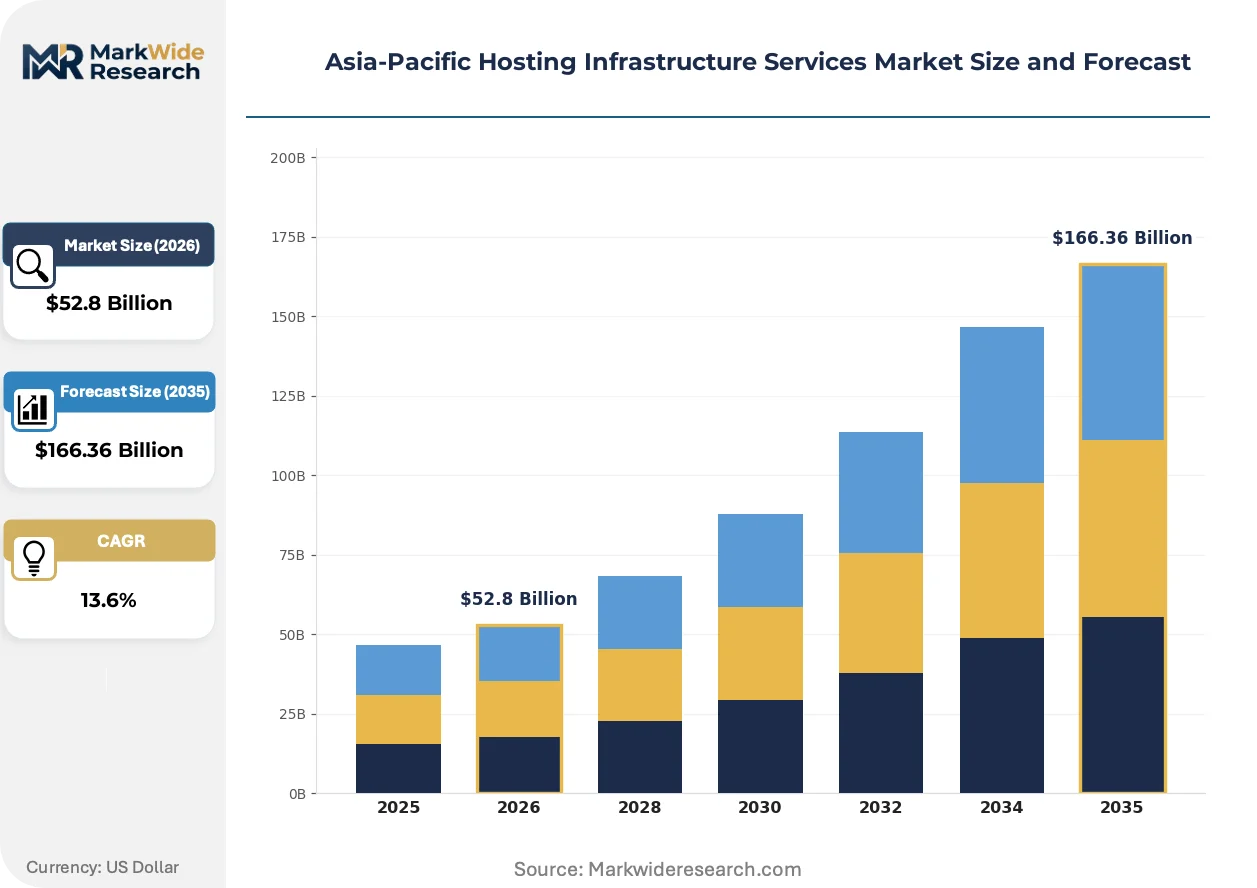
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $166.36 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Hosting, Shared Hosting, VPS Hosting, Cloud Hosting Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions Technology: Containerization, Virtualization, Serverless Computing, Edge Computing |
| Companies Covered | Amazon Web Services, Microsoft Azure, Alibaba Cloud, Google Cloud, Tencent Cloud, Huawei Cloud, IBM Cloud, Oracle Cloud, NTT Communications, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hosting Infrastructure Services Market Trends and Innovations
Asia-Pacific Hosting Infrastructure Services are being reconstituted around three concurrent vectors: infrastructure software abstraction, regulatory jurisdiction arbitrage, and buyer procurement model compression. These forces are collapsing traditional service boundaries and recalibrating competitive differentiation.
Kubernetes-native container platforms are supplanting VMware and Hyper-V estates as the default compute abstraction layer. Large enterprises in Australia's financial sector are migrating production workloads to orchestrated microservices architectures within eighteen-month windows. This shift is compressing managed service margins while elevating platform engineering and DevOps automation to core value propositions.
China's MIIT cloud service classification standards and cross-border data transfer restrictions are fragmenting architectural patterns for multinational enterprises. Organizations must now maintain distinct operational regimes for mainland China workloads versus Hong Kong or Singapore nodes. Financial services and healthcare verticals are responding by bifurcating cloud strategies and accepting redundant infrastructure investment.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based accountability for uptime, security posture, and cost optimization. Traditional reseller channels across Thailand and Vietnam are losing ground to direct hyperscale engagements and specialized managed service aggregators. This concentration is most visible in India's digital transformation initiatives, where government agencies are bypassing systems integrators for certified cloud-direct contracts.
Asia-Pacific Hosting Infrastructure Services Market Segmentation
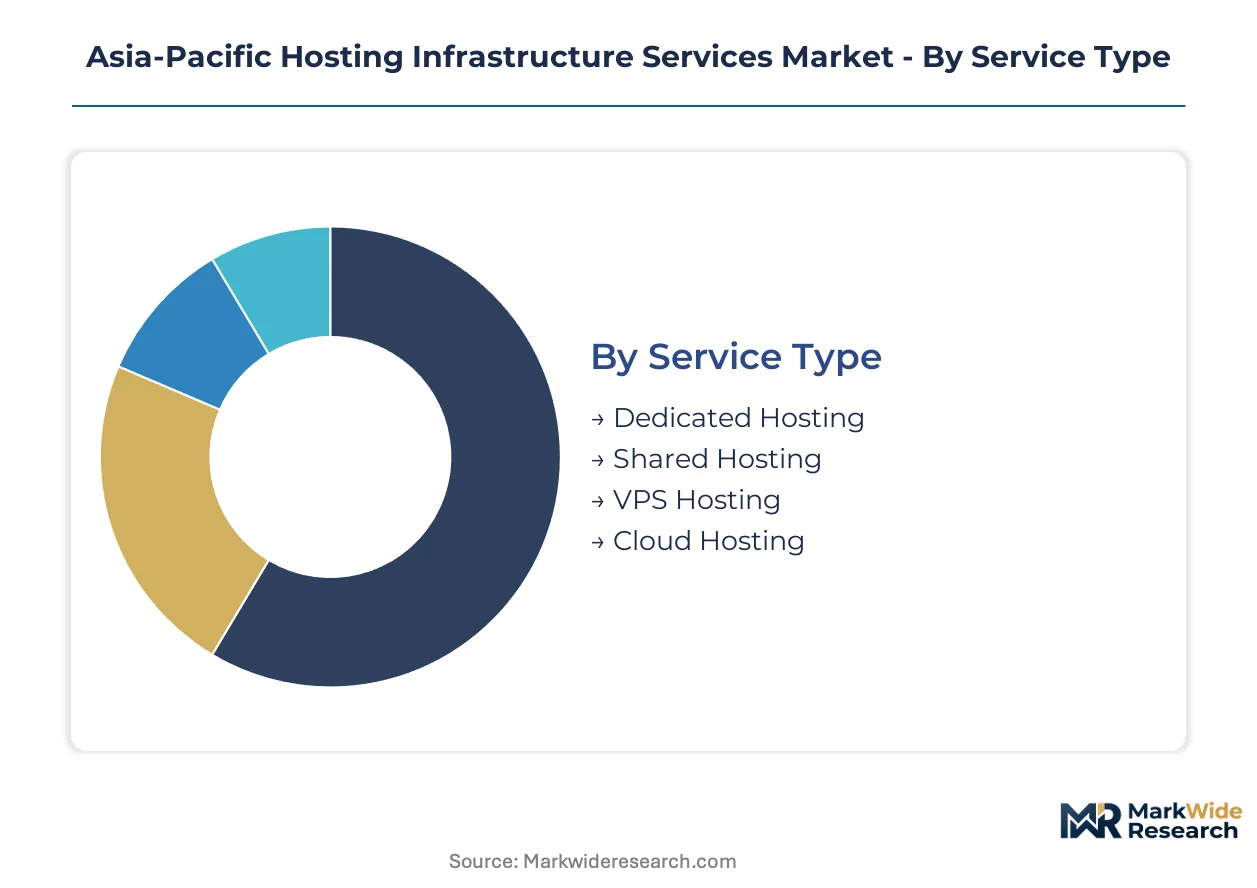
Hosting infrastructure services fragment across four operational dimensions that determine procurement priorities and vendor selection criteria. Service type and deployment model decisions cascade through technology architecture choices and end-user compliance requirements. Each segmentation axis carries distinct margin profiles and substitution vulnerabilities that reshape competitive positioning.
Service Type:
Cloud Hosting exerts the strongest substitution pressure on legacy delivery models as elastic consumption models displace fixed-capacity contracts across the region.
- Cloud Hosting:Elastic compute and storage resources delivered through hyperscale data centers with metered billing and API-driven provisioning. Financial services firms in Singapore and Hong Kong are migrating trading platforms to cloud-native architectures to capture sub-millisecond latency advantages. Kubernetes-native orchestration is accelerating workload portability between providers.
- Dedicated Hosting:Single-tenant physical servers with guaranteed resource isolation and custom hardware configurations. India's government cloud procurement under MeitY mandates is funneling sovereign workloads toward dedicated facilities in Mumbai and Hyderabad. Compliance certification requirements favor established operators with in-country presence.
- VPS Hosting:Virtualized partitions of physical servers offering root access at intermediate price points. Southeast Asian e-commerce platforms use VPS tiers for staging environments and moderate-traffic production workloads.
- Shared Hosting:Multi-tenant server environments with standardized control panels and limited customization. Small business websites and personal projects in Indonesia and Vietnam remain the primary demand base.
Shared Hosting anchors the volume base while Cloud Hosting gains share at the steepest rate.
Deployment:
Margin concentration follows deployment complexity, with hybrid configurations capturing premium pricing through orchestration layer value-adds.
- Hybrid Cloud:Interconnected public and private infrastructure with unified management planes and workload portability policies. Australia's financial sector is deploying hybrid stacks to satisfy APRA prudential standards while leveraging public cloud burst capacity. Microsoft's partner channel dominance across Southeast Asia sustains deployment momentum.
- Private Cloud:Single-organization infrastructure with dedicated hardware and customized security postures. China's MIIT GB standards for cloud service classification are driving domestic enterprises toward certified private cloud operators. Data localization mandates in multiple jurisdictions reinforce demand.
- Public Cloud:Shared multi-tenant resources with global availability zones and standardized service catalogs. Alibaba Cloud's domestic data center density captures mainland China workloads through proximity advantages.
- On-Premises:Customer-owned facilities with full operational control and capital-intensive infrastructure ownership. Legacy manufacturing hubs in Thailand and Malaysia retain on-premises estates due to re-platforming cost barriers.
Public Cloud commands the largest revenue pool while Hybrid Cloud expands most quickly through enterprise transformation mandates.
End User:
Procurement authority is shifting toward centralized IT functions with outcome-based contracting replacing transactional service purchases.
- Large Enterprises:Multi-divisional organizations with dedicated infrastructure teams and complex compliance portfolios. India's digital transformation initiatives are bypassing systems integrators for direct cloud contracts with certified providers. Container orchestration expertise requirements favor managed service partnerships.
- Government:Central and state agencies with sovereign data requirements and certified procurement frameworks. Australia's TGA-aligned cybersecurity baselines impose hosting standards on critical infrastructure operators. Certification reciprocity limitations complicate multi-country deployments.
- SMEs:Mid-sized organizations with limited internal technical resources and price-sensitive procurement criteria. Indonesia's sovereign cloud gap creates compliance challenges for domestic SMEs serving regulated industries.
- Educational Institutions:Universities and research facilities with variable compute demands and grant-funded procurement cycles. GPU-accelerated research workloads are migrating toward specialized academic cloud partnerships.
SMEs generate the highest transaction volume while Government segments post the steepest expansion trajectory through digitization mandates.
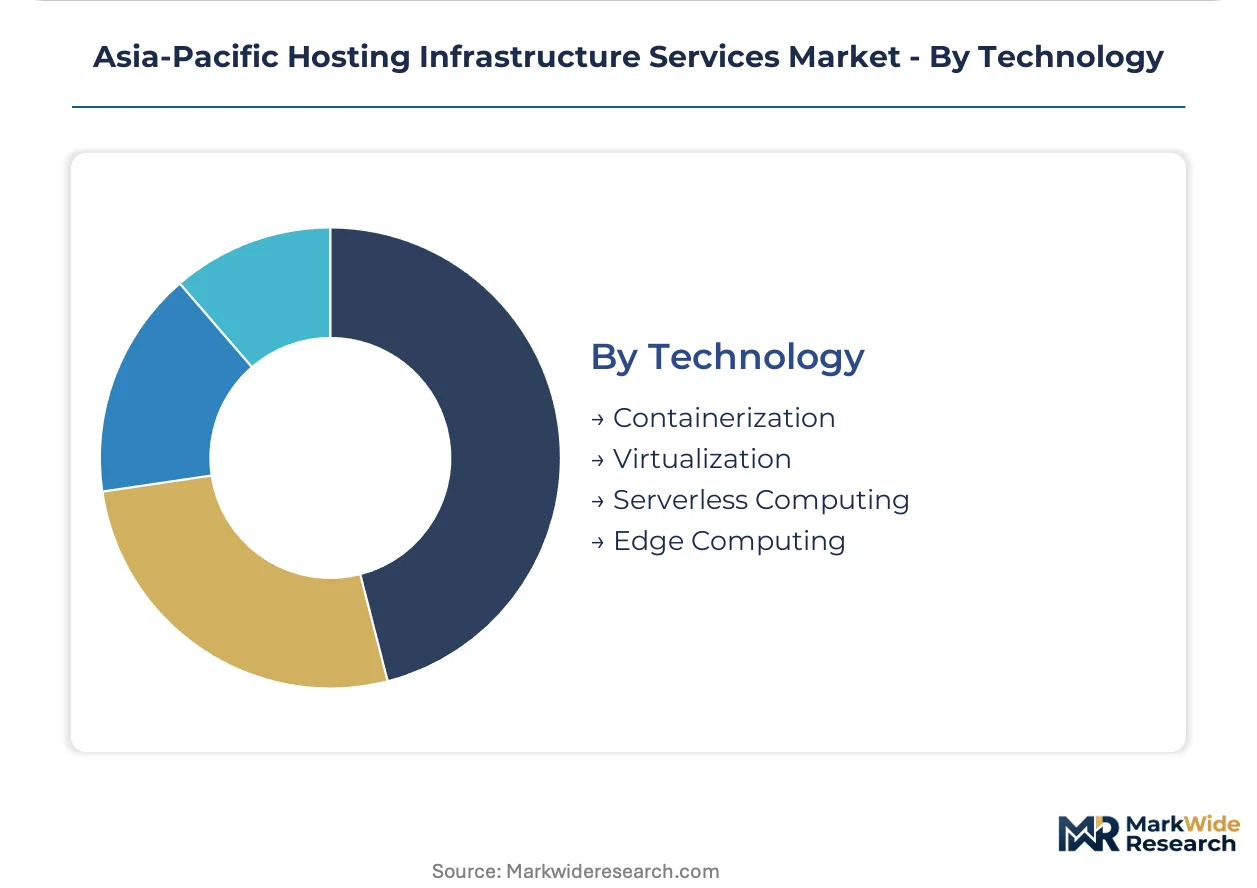
Technology:
R&D allocation concentrates on abstraction layers that compress hardware differentiation and elevate software-defined value capture.
- Containerization:Kubernetes-native platforms with microservices orchestration and declarative infrastructure management. Australia's financial sector is completing eighteen-month production migration windows from legacy hypervisor estates. Platform engineering talent scarcity in Bangalore and Singapore constrains regional deployment velocity.
- Edge Computing:Distributed compute nodes positioned proximal to data sources with 5G network slicing integration. South Korea and Japan's renewable energy attribute trading schemes enable carbon-neutral edge positioning without captive generation. Autonomous systems and industrial IoT inference workloads drive GPU-accelerated node deployment.
- Serverless Computing:Event-driven execution environments with automatic scaling and per-invocation billing. Event processing pipelines in Singapore's fintech ecosystem are adopting serverless architectures for variable load patterns.
- Virtualization:Traditional hypervisor-based compute abstraction with mature tooling and established operational procedures. Southeast Asian manufacturing hubs retain decade-old virtualization estates resisting seamless container migration without substantial investment.
Virtualization retains the installed base majority while Containerization climbs the fastest through Kubernetes-native platform standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific submarine cable network spanning the SEA-ME-WE 3 and APCN-2 corridors underwrites the region's centrality in global data transit, with Singapore's Tuas cable landing station anchoring interconnection density between East Asia and Europe.
China
MIIT cloud computing standards and cross-border data transfer restrictions are fragmenting architectural patterns for multinational enterprises. GB standards for cloud service classification enforce strict operational regimes distinguishing mainland workloads from Hong Kong nodes. Shanghai and Beijing data center clusters concentrate certified private cloud capacity for domestic financial services firms.
India
MeitY localization mandates for government cloud procurement are funneling sovereign workloads toward domestic facilities. RBI guidelines on data residency for payment systems reinforce compliance requirements for financial services hosting. Mumbai, Bangalore, and Hyderabad form the primary concentration of certified data center capacity serving digital transformation initiatives.
Australia
APRA prudential standards and TGA-aligned cybersecurity baselines impose hosting requirements on critical infrastructure operators. The country's National Broadband Network underwrites edge computing deployment for latency-sensitive applications. Sydney and Melbourne data center markets concentrate hybrid cloud adoption among financial services and healthcare verticals.
Indonesia
Sovereign cloud regulatory pressure for data localization outpaces certified domestic supply, creating capacity constraints for compliant operators. The government's data protection law implementation timeline accelerates enterprise migration planning. Jakarta emerging as the primary concentration for new facility investment targeting banking and e-commerce workloads.
Japan
METI industrial policy and renewable energy attribute trading schemes enable carbon-neutral hosting positioning without captive generation. The country's seismic resilience standards elevate facility construction costs and operator certification requirements. Tokyo and Osaka metro areas concentrate GPU-accelerated infrastructure serving AI inference and financial trading platforms.
Asia-Pacific Hosting Infrastructure Services Market Competitive Landscape
Concentration sits with hyperscale cloud providers and domestic champions operating across tiered service portfolios. The vendor base separates into three strategic layers: global hyperscalers with regional presence, China-based operators with domestic density advantages, and specialized managed service aggregators. Competitive dynamics center on data center capacity expansion in compliance-heavy jurisdictions and managed service bundling to capture orchestration complexity premiums.
Among global hyperscalers, Amazon Web Services, Microsoft Azure, and Alibaba Cloud exemplify the three dominant archetypes. Amazon Web Services anchors the premium-tier infrastructure-as-a-service segment through extensive service catalog breadth. Microsoft Azure occupies a position emphasizing hybrid cloud dominance and partner channel control across Southeast Asian markets. Alibaba Cloud represents the domestic champion model leveraging in-country data center density to capture mainland China workloads subject to MIIT regulatory requirements.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Alibaba Cloud |
| Google Cloud |
| Tencent Cloud |
| Huawei Cloud |
| IBM Cloud |
| Oracle Cloud |
| NTT Communications |
| Others |
Pricing and Supply Chain Analysis
Kubernetes-native container platforms displacing legacy hypervisor estates are redrawing supply geography toward Bangalore and Singapore talent clusters while compressing managed service margins across tiered consumption models. This substitution simultaneously elevates platform engineering premiums and erodes virtualization-based pricing power in Southeast Asian manufacturing hubs.
Pricing Analysis
Volume-discount tiering structures stratify across committed-use contracts, on-demand burst capacity, and spot-instance provisioning. Price differentiation centers on certification grade—MIIT GB compliance in China commands substantial premiums—and geographic delivery cost differentials between Mumbai and Sydney facilities. Cost compression in shared hosting tiers is intensifying because hyperscale providers are absorbing small-business workloads through self-service portals. SMEs exhibit highest price sensitivity, while financial services firms in Singapore and Hong Kong prioritize latency guarantees over unit economics.
Supply Chain Analysis
Inventory and lead-time observations reveal GPU accelerator shortages constraining edge-AI node deployment timelines across Tokyo and Seoul facilities. Geographic supply concentration centers on China for server hardware assembly, Taiwan for advanced semiconductor components, and Malaysia for data center construction materials. Raw material dependencies span lithium-ion battery systems for backup power, specialized cooling fluids, and fiber-optic cable sheathing. Single-source vulnerability in MIIT-certified equipment creates compliance bottlenecks for mainland China workloads. Distribution runs through direct hyperscale engagements and certified managed service aggregators bypassing traditional reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
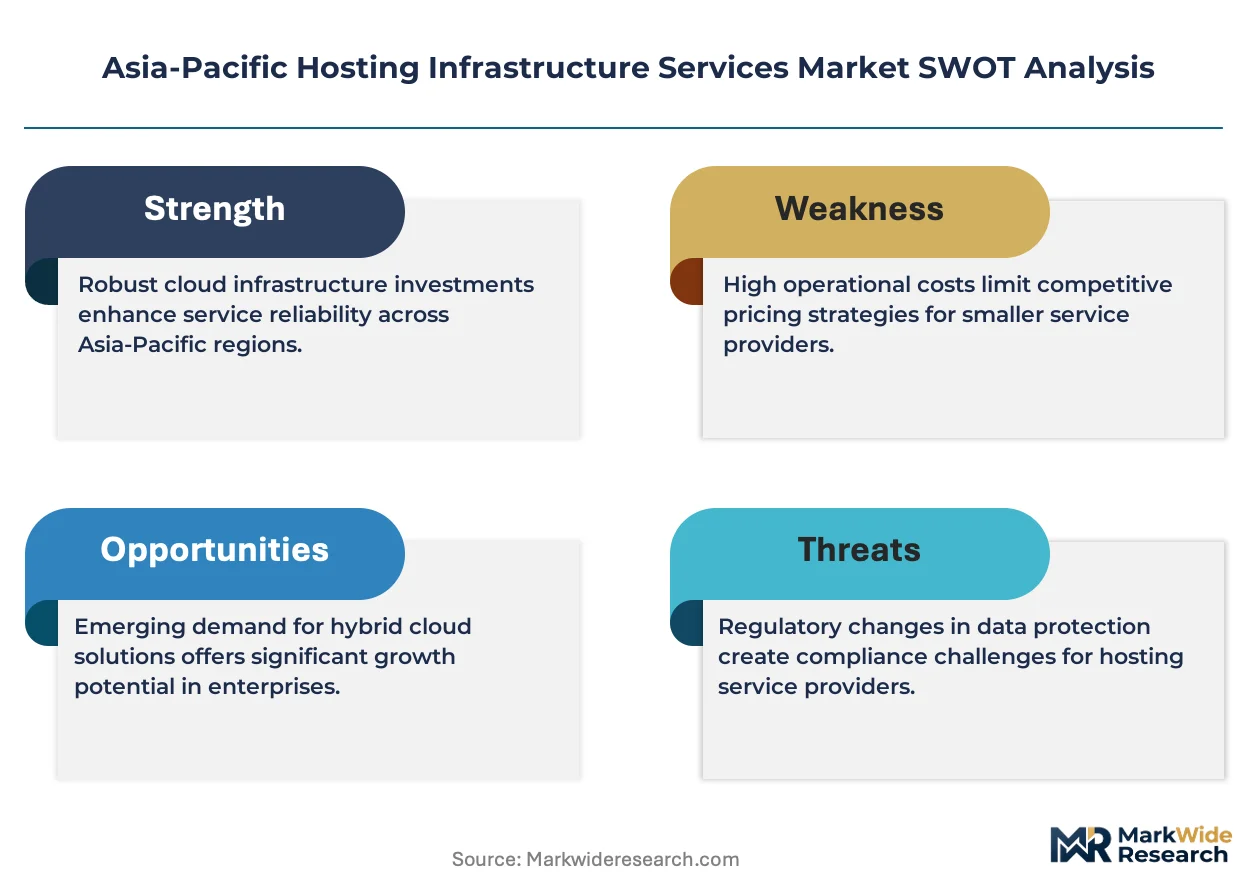
Asia-Pacific hosting infrastructure sits at an early-cycle expansion story justified by sovereign cloud mandates outpacing certified domestic supply in Indonesia and accelerating government digitization programs across India and Australia.
For Market Incumbents: Consolidate data center capacity in Jakarta and Bangkok to capture sovereign cloud premiums before regulatory deadlines tighten. Deepen backward integration into renewable energy sourcing through South Korean and Japanese green certificate trading schemes. Channel control investments in Vietnam and Thailand resist hyperscale direct-engagement erosion.
For New Entrants and Emerging Players: MIIT certification fast-tracks unlock mainland China market access for specialized GPU-accelerated edge operators. Indonesia's banking and e-commerce verticals present the most penetrable segment given certified supply constraints. Go-to-market positioning through Jakarta-based system integrators with existing regulatory relationships accelerates contract capture.
For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors platform-engineering talent aggregators over pure hardware operators. Long-term viability rests on orchestration-layer software differentiation rather than facility ownership alone. Kubernetes-native managed service providers with Bangalore or Singapore engineering density represent priority acquisition targets. The signal to watch is certification reciprocity agreements between ASEAN regulators enabling multi-country workload portability.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | GB standards compliance unlocks mainland China financial services and government procurement pipelines. |
| GPU-Accelerated Edge Expansion | Tokyo and Osaka metro deployments capture AI inference workloads from autonomous systems and industrial IoT. |
| Green Certificate Arbitrage | Renewable energy attribute trading in South Korea enables carbon-neutral positioning without captive generation. |
| Kubernetes Talent Acquisition | Platform engineering teams in Bangalore accelerate regional container orchestration service delivery. |
| Sovereign Cloud Partnership | Jakarta facility alliances with domestic banks address data localization mandates ahead of regulatory deadlines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility managers, cloud procurement officers at financial services firms, platform engineering leads, and regulatory compliance specialists. Secondary validation drew from MIIT GB standard filings, MeitY certification registries, hyperscaler capex disclosures, and submarine cable landing station capacity reports. Bottom-up facility capacity modeling and top-down enterprise IT spending analysis were triangulated to reconcile supply and demand estimates.
Across the analysis window, the forecasting framework modeled deployment model transitions, organization size tiers, vertical compliance requirements, and regional regulatory clustering. CAGRs were derived from elasticity-adjusted adoption curves weighted by certification timeline constraints. Containerization penetration rates and sovereign cloud procurement volumes served as primary demand-side inputs, while power cost trajectories and data center construction pipelines anchored supply-side boundaries.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of data localization mandates and stable hyperscale pricing discipline; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Data Center Fabric Market