

Switchgear for Data Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Switchgear for Data Centers Market Insights
Modular switchgear configurations with integrated busway and monitoring is recalibrating procurement patterns across data center operators. Schneider Electric leverages its prefabricated power module portfolio to anchor large hyperscale contracts in North America. Eaton competes through aggressive R&D intensity in solid-state protection technologies. Siemens differentiates via deep domain expertise in gas-insulated systems for high-density urban deployments.
Switchgear for data centers comprises electrical protection and distribution apparatus—circuit breakers, contactors, busbars, and relay systems—engineered to manage fault currents from 10 kA to 100 kA while ensuring sub-cycle interruption for critical IT loads. Its primary purpose centers on maintaining power continuity and personnel safety within facilities where downtime costs escalate into millions per minute. Gas-insulated switchgear retains structural dominance in space-constrained metropolitan builds where footprint efficiency commands premium positioning. Air-insulated variants occupy the volume tier across greenfield hyperscale campuses where land abundance reduces enclosure density requirements. Digital control technology is capturing the fastest expansion trajectory as operators mandate remote telemetry and predictive maintenance integration.
The US National Electrical Code and NFPA 70E standards shape product certification requirements and arc-flash mitigation specifications for domestic installations. IEC 61439 and the EU F-Gas Regulation govern European market access while restricting SF6-intensive designs. China's GB standards and dual carbon goals impose efficiency benchmarks on imported and locally manufactured equipment alike. Stakeholders must monitor how evolving grid interconnection codes and carbon border adjustments reshape sourcing geography and technology roadmaps.
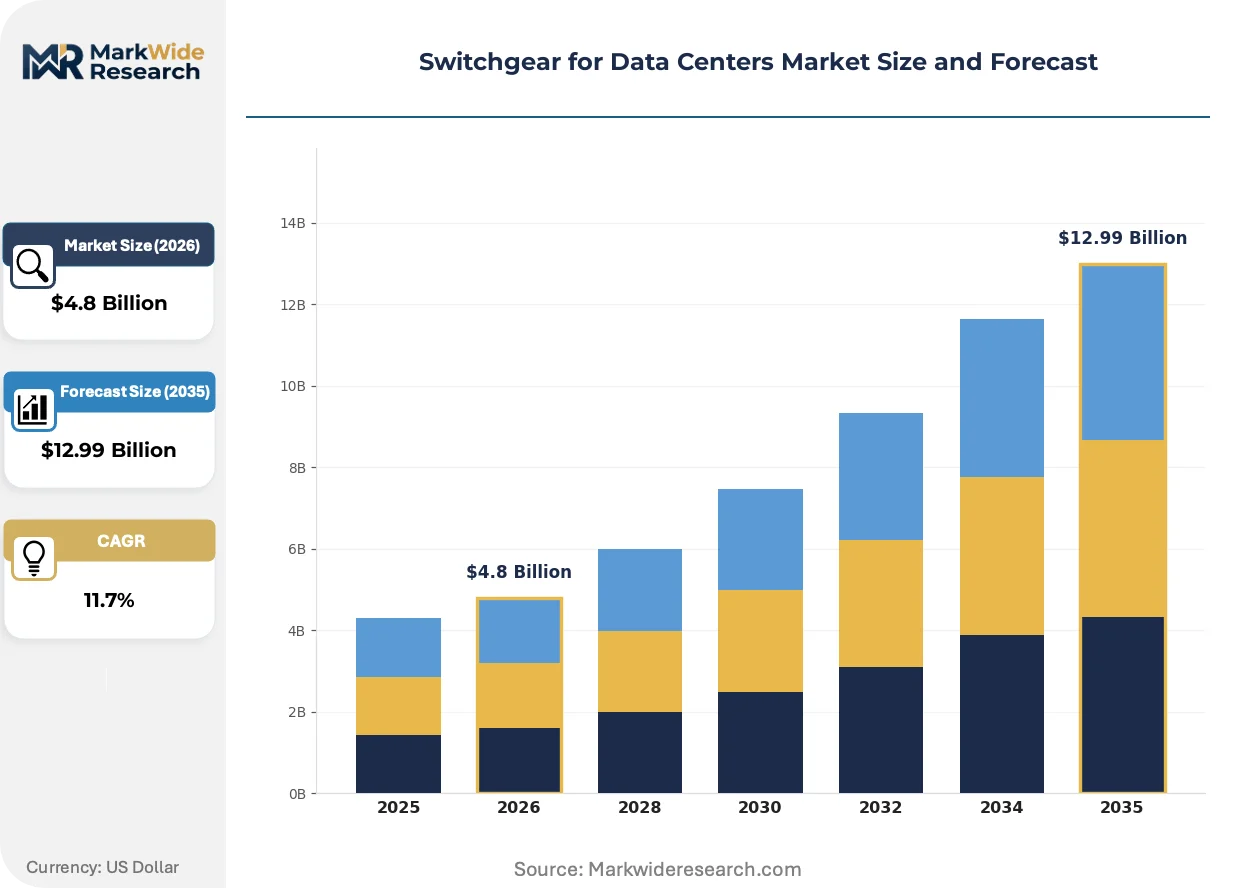
Market Dynamics
Hyperscale AI infrastructure buildouts are compressing procurement cycles for high-capacity electrical distribution systems, forcing switchgear vendors to accelerate modular platform development and pre-certification workflows.
Growth Catalysts
- EU F-Gas Regulation:The accelerated phase-out of SF6-dependent equipment across European facilities is generating replacement demand for gas-insulated alternatives with lower global warming potential.
- AI workload multiplication:Training clusters and inference farms require fault-current ratings above 63 kA, pulling premium-rated switchgear into standard hyperscale specifications.
- Busway integration:Pre-terminated power distribution modules are reducing on-site electrical commissioning from weeks to days for multi-gigawatt campus deployments.
Market Restraints
- Copper and silver price volatility:Busbar and contact materials constitute 35-45% of raw material costs, exposing margins to commodity exchange fluctuations.
- Specialized foundry concentration:High-purity aluminum casting for gas-tight enclosures relies on a limited supplier base concentrated in German and Austrian industrial regions.
- SF6 disposal liability:End-of-life handling requirements under EU F-Gas Regulation impose extended cost obligations on operators of legacy installations.
Strategic Opportunities
- Edge computing micro-facilities:Sub-10 MW distributed nodes in secondary US metros lack purpose-built electrical infrastructure, creating openings for compact air-insulated units.
- Digital twin integration:Switchgear telemetry is converging with building management systems to enable predictive arc-flash mitigation and automated load balancing.
- India's PLI scheme:Domestic manufacturing incentives for electrical equipment are attracting component localization investments to serve South Asian data center construction.
Industry Challenges
- Arc-flash engineering expertise:Shortage of certified protection engineers is extending commissioning timelines for complex bus-tie configurations in multi-building campuses.
- Legacy 480V integration:New 415V IEC-standard switchgear requires custom transformation interfaces when retrofitting into existing North American distribution architectures.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switchgear for Data Centers Market Trends and Innovations
Electrical infrastructure for data centers is undergoing a fundamental reconfiguration as density requirements clash with sustainability mandates and operational velocity demands.
Solid-state circuit protection is converging with conventional electromechanical breaker platforms to enable sub-millisecond fault isolation without mechanical wear degradation. Hyperscale operators in the United States are piloting silicon-carbide-based protection modules for high-frequency switching environments. This convergence is compressing the traditional replacement cycle for electromechanical assets while establishing new performance benchmarks for arc-energy containment.
The EU F-Gas Regulation is mandating comprehensive SF6 phase-out schedules that extend through 2030 for new installations and 2050 for existing assets. Equipment manufacturers must redesign gas-insulated switchgear around fluoronitrile or vacuum interruption technologies to maintain European market access. German and French utilities are accelerating pilot deployments of SF6-free medium-voltage gear to secure early-mover regulatory compliance positioning.
Power-as-a-service contracting is displacing traditional capital procurement for electrical infrastructure in colocation and enterprise facilities. Leasing structures bundle switchgear, installation, and lifecycle maintenance into per-kW-monthly arrangements that transfer obsolescence risk to vendors. This model is gaining traction most visibly in the United Kingdom and Netherlands where energy-as-a-service frameworks have matured in adjacent building systems markets.
Switchgear for Data Centers Market Segmentation
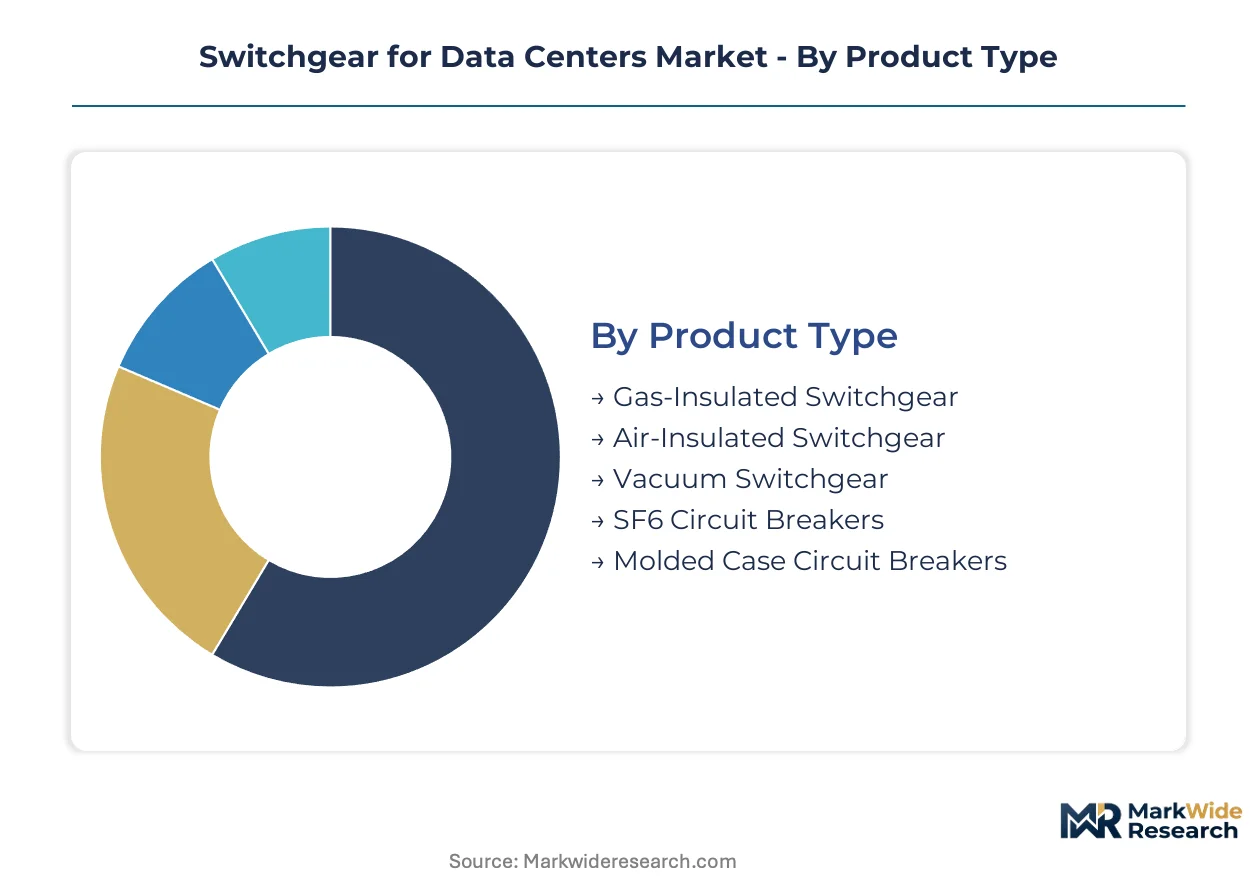
Electrical infrastructure procurement in data centers diverges sharply across facility scale and operational models. Capital allocation patterns, technology refresh cycles, and regulatory exposure vary meaningfully between hyperscale campuses and distributed edge nodes.
Product Type:
Capital intensity peaks with gas-insulated systems requiring precision-machined enclosures and sealed gas handling infrastructure.
- Gas-Insulated Switchgear:Sealed sulfur hexafluoride or fluoronitrile-filled chambers enable 40-60% footprint reduction versus air-insulated equivalents. Demand concentrates in Frankfurt, London, and Singapore where real estate premiums exceed $500 per square meter and EU F-Gas Regulation compliance mandates low-GWP alternatives.
- Air-Insulated Switchgear:Open-air busbar and breaker assemblies suit land-abundant hyperscale campuses in rural Virginia, Oregon, and Iowa. Operators accept larger electrical rooms to avoid gas containment complexity and end-of-life disposal liabilities.
- Vacuum Switchgear:Ceramic-enclosed vacuum interrupters eliminate gas handling entirely while matching GIS fault-current ratings.
- SF6 Circuit Breakers:Legacy installations dominate European retrofit markets facing mandated phase-out timelines.
- Molded Case Circuit Breakers:Thermoset-housed units populate branch circuit protection in colocation and enterprise facilities.
Most installed capacity flows through Air-Insulated Switchgear. Expansion is steepest in Gas-Insulated Switchgear as metropolitan land scarcity intensifies.
Technology:
Control sophistication determines operational labor intensity and predictive maintenance capability across facility tiers.
- Digital Control:Microprocessor-based protection relays with IEC 61850 communication enable sub-cycle fault coordination and automated arc-flash energy reduction. Hyperscale operators in the United States mandate native SCADA integration for multi-gigawatt campus synchronization.
- Remote Monitoring:Cloud-connected thermal and partial discharge sensors shift maintenance from calendar-based to condition-based intervals. Edge computing sites lacking on-site electrical expertise depend on vendor-managed monitoring subscriptions.
- Automated Switching:Motorized breaker operators enable load transfer sequences without manual intervention during utility outages.
- Load Break Technology:Make-before-break contactors handle routine feeder reconfiguration in live electrical environments.
- Solid-State Relays:Silicon-controlled rectifier and IGBT-based switching eliminates mechanical wear for high-frequency cycling applications.
Digital Control commands the highest premium pricing. Remote Monitoring is gaining share fastest among distributed facility portfolios.
Application:
Facility scale dictates fault-current magnitude, redundancy topology, and commissioning velocity requirements.
- Hyperscale Data Centers:Single-campus power demands exceeding 500 MW require 63-100 kA interrupting ratings and synchronized bus-tie configurations. Cloud providers in the United States specify modular switchgear skids factory-tested to compress field commissioning schedules.
- Edge Computing Sites:Sub-10 MW distributed nodes in secondary metros lack purpose-built electrical infrastructure. Compact pad-mounted switchgear with integrated transformers addresses space-constrained retail and industrial deployments.
- Colocation Facilities:Multi-tenant power distribution demands tenant-isolated metering and flexible breaker provisioning.
- Cloud Service Providers:Captive infrastructure teams drive standardization across global facility portfolios.
- Telecommunication Hubs:DC power distribution traditions create hybrid AC-DC switching requirements.
Hyperscale Data Centers absorb the largest absolute capital volumes. Edge Computing Sites are expanding most quickly as latency-sensitive workloads proliferate.
End User:
Procurement sophistication and lifecycle cost visibility vary sharply across customer technical depth.
- Cloud Operators:Amazon Web Services, Microsoft Azure, and Google Cloud Platforms specify custom switchgear platforms with 25-year design lives and embedded digital twin compatibility. Their engineering teams validate arc-flash studies and protection coordination internally.
- Data Center Service Providers:Equinix, Digital Realty, and CyrusOne balance standardization against tenant-specific customization requests. Power-as-a-service contracting transfers obsolescence risk to vendors while preserving operational flexibility.
- IT Infrastructure Providers:Dell, HPE, and Lenovo integrate switchgear specifications into modular data center product lines.
- Network Management Companies:Telecommunication carriers prioritize proven designs over leading-edge specifications.
- Content Delivery Networks:Cache-heavy architectures emphasize reliability over density in electrical infrastructure decisions.
Cloud Operators drive technology roadmaps through direct engineering engagement. Data Center Service Providers are diversifying procurement fastest across vendor portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical distribution infrastructure for mission-critical computing originated in the United States during the 1960s mainframe era, with American manufacturers pioneering the first high-rupture-capacity breaker systems for early data processing centers.
United States
Hyperscale cloud operators in Northern Virginia, Oregon, and Iowa are commissioning multi-gigawatt electrical campuses with 63-100 kA interrupting ratings. The National Electrical Code and NFPA 70E standards govern arc-flash mitigation specifications and product certification requirements. Ashburn's Data Center Alley hosts the densest concentration of switchgear procurement activity worldwide as Amazon Web Services, Microsoft Azure, and Google Cloud Platforms expand adjacent facilities.
Germany
Frankfurt's financial district and Berlin's tech corridor are driving demand for gas-insulated switchgear with fluoronitrile alternatives to SF6. The EU F-Gas Regulation mandates comprehensive phase-out schedules through 2030 for new installations and 2050 for existing assets. Munich-based engineering consultancies are validating vacuum interruption technologies for high-density urban deployments where real estate premiums exceed $500 per square meter.
China
Beijing-Tianjin-Hebei and Yangtze River Delta clusters are absorbing domestic switchgear production for AI training infrastructure. GB standards and dual carbon goals impose efficiency benchmarks on imported and locally manufactured equipment alike. Shanghai's Lingang Special Area is attracting prefabricated electrical module factories to serve hyperscale construction timelines compressed to 12-18 months.
India
Mumbai and Bengaluru data center operators are sourcing compact air-insulated switchgear for sub-10 MW edge computing nodes in secondary metros. The PLI scheme for electrical equipment manufacturing is attracting component localization investments from multinational vendors. Maharashtra's MMRDA is fast-tracking power distribution approvals for Navi Mumbai's emerging cloud campus zone.
Singapore
Tanjong Kling and Loyang industrial estates are deploying gas-insulated systems where land scarcity commands maximum footprint efficiency. The Energy Market Authority's grid interconnection codes are reshaping technology roadmaps for imported switchgear. Jurong Island's integrated power infrastructure is serving as a testbed for digital twin integration in electrical distribution systems.
Switchgear for Data Centers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service bundling dimensions in electrical infrastructure procurement. The vendor base clusters around three strategic archetypes: integrated industrial conglomerates with full power distribution portfolios, specialized electrical equipment pure-plays with deep protection engineering expertise, and infrastructure technology vendors extending from cooling and power conditioning into switchgear adjacencies. Consolidation pressure is intensifying as hyperscale operators reduce approved vendor lists to three or four per region, while modular platform licensing and power-as-a-service contracting emerge as dominant competitive moves.
Within the integrated conglomerate tier, Schneider Electric and Siemens exemplify full-stack power distribution capabilities spanning low-voltage through medium-voltage applications. Eaton occupies a position bridging industrial equipment breadth with data center-specific protection specialization. These three anchors represent contrasting geographic emphases—Schneider Electric's French origins, Siemens' German engineering heritage, and Eaton's American industrial roots—while collectively defining the competitive frontier around digital control integration and prefabricated electrical module deployment.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton |
| ABB |
| Siemens |
| Vertiv |
| Legrand |
| Mitsubishi Electric |
| Cummins |
| Socomec |
| Others |
Pricing and Supply Chain Analysis
Captive aluminum foundry operations in Germany and Austria anchor both the supply position and pricing power for gas-insulated switchgear manufacturers serving European data centers. This backward integration into high-purity casting insulates incumbents from commodity volatility while enabling premium positioning for fluoronitrile-filled systems under EU F-Gas Regulation compliance mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by fault-current rating and digital control sophistication. Premium tiers command positioning through IEC 61850 certification and embedded SCADA compatibility, while hyperscale cloud operators in the United States show least price sensitivity due to total-cost-of-ownership procurement frameworks. Cost compression in standard air-insulated segments is intensifying because copper busbar volatility exposes margins to London Metal Exchange fluctuations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, bypassing electrical distributors for factory-tested modular skids. Manufacturing gravity centers on Germany, China, and the United States, with ceramic vacuum interrupters sourcing from Japanese suppliers and silver-plated contacts drawing from Mexican fabricators. Single-source vulnerability concentrates in Austrian high-pressure die-casting for GIS enclosures, creating tariff exposure risk under evolving EU carbon border adjustment mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
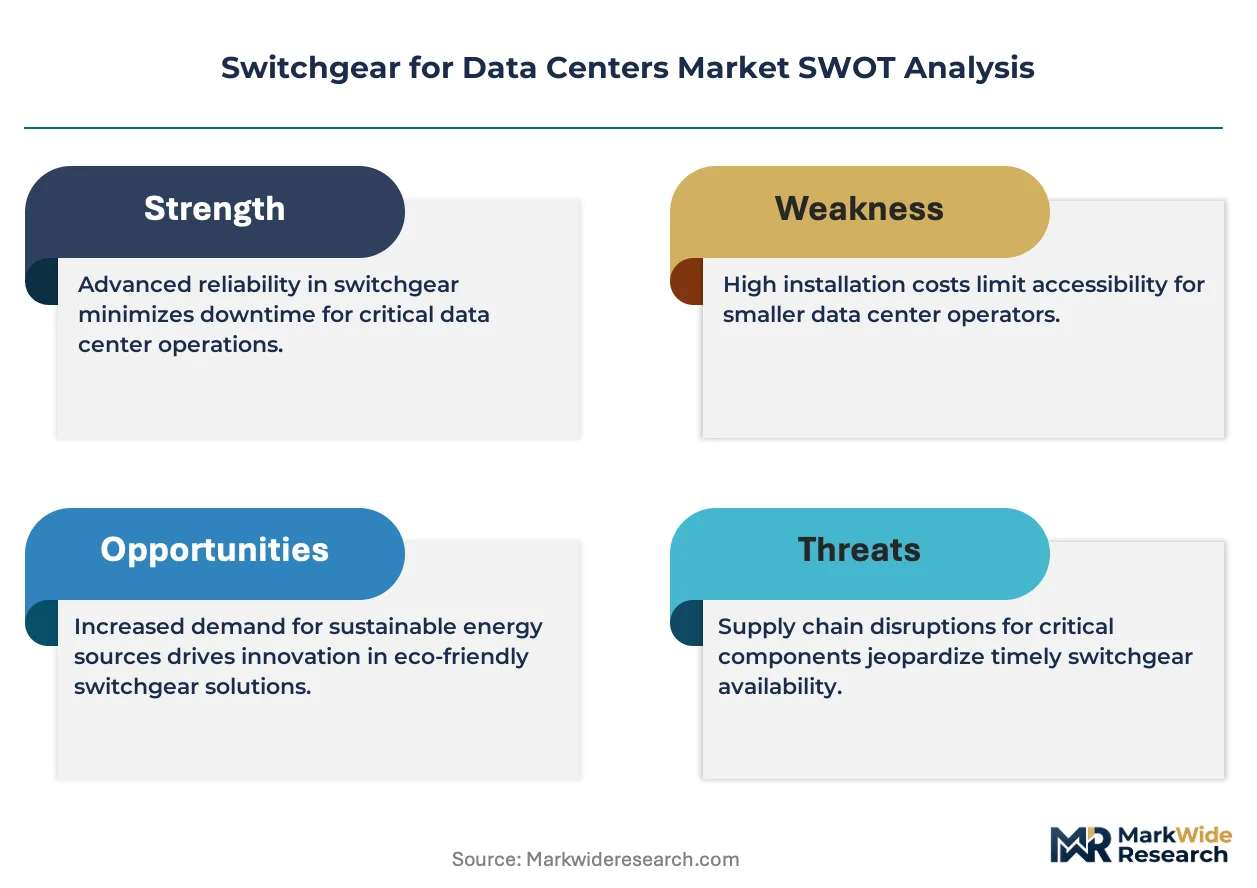
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Frankfurt and Berlin diverge sharply from unregulated buildouts in rural Virginia and Iowa, creating margin expansion opportunities for vendors with dual-standard product platforms.
For Market Incumbents: Acquire solid-state protection engineering teams to counter silicon-carbide module entrants from adjacent power electronics sectors. Incumbent vendors must secure captive foundry capacity in Germany before Austrian aluminum casting consolidation accelerates, while accelerating pre-certification workflows to match hyperscale procurement velocity demands. For New Entrants and Emerging Players: Enter via India's PLI scheme for electrical equipment manufacturing, targeting sub-10 MW edge computing nodes in secondary metros like Hyderabad and Chennai where purpose-built infrastructure remains scarce. New entrants should lead with compact air-insulated units featuring integrated remote monitoring subscriptions, bypassing capital-intensive GIS development. For Investors and Strategic Acquirers: Roll-up economics work for regional switchgear service specialists because fragmented aftermarket maintenance contracts across European legacy SF6 installations create predictable recurring revenue streams. Investors should monitor EU F-Gas Regulation enforcement intensity as the inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Technology Transition | Fluoronitrile and vacuum interruption platforms secure EU F-Gas Regulation compliance positioning. |
| Prefabricated Module Deployment | Factory-tested electrical skids compress hyperscale commissioning schedules from weeks to days. |
| Digital Twin Integration | SCADA-native switchgear converges with building management systems for predictive arc-flash mitigation. |
| Power-as-a-Service Contracting | Per-kW-monthly arrangements transfer obsolescence risk to vendors in UK and Netherlands colocation markets. |
| Component Localization Investment | India PLI scheme incentives attract busbar and contact manufacturing for South Asian data center construction. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with data center engineering directors, electrical contractor procurement leads, and switchgear OEM product managers alongside secondary validation. Primary fieldwork draws from hyperscaler capex disclosures, FERC interconnection filings, and EU F-Gas Regulation implementation guidance, with bottom-up facility deployment counts triangulated against top-down electrical infrastructure spend estimates.
Rate-of-change decomposition separates volume expansion from value mix shifts across the analysis window, modeling segmentation dimensions including insulation technology type, control sophistication tier, facility scale category, and regional regulatory cluster. CAGRs were derived from installation run-rate extrapolation adjusted for technology substitution effects, with AI workload density assumptions and grid interconnection queue data informing capacity expansion forecasts.
Inputs from hyperscaler engineering teams and European regulatory filings were available through the study window; gaps in real-time commodity cost pass-through data introduce uncertainty bands around margin projections. Forecasts reflect assumptions about EU F-Gas Regulation phase-out adherence and copper price trajectory stability, with periodic stress-testing of base assumptions recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.